
 Disinfectant & Antimicrobial Chemicals Market | 2026-2036
Disinfectant & Antimicrobial Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfectant & Antimicrobial Chemicals Market Analytics
Capital-intensity divergence between integrated manufacturers and formulation-only specialists is redrawing competitive boundaries in antimicrobial chemicals. Ecolab Inc sustains upstream control over peroxyacetic acid supply chains that smaller competitors cannot replicate. Reckitt Benckiser Group plc dominates branded consumer disinfectant shelves through retail channel leverage and sustained advertising investment. 3M Company differentiates via proprietary quaternary ammonium compound delivery systems that command premium placement in institutional procurement.
Disinfectant and antimicrobial chemicals encompass biocidal formulations designed to destroy or inhibit microorganisms on surfaces, equipment, and skin, typically containing active concentrations of quaternary ammonium compounds, hydrogen peroxide, or sodium hypochlorite at specified ppm levels effective against bacterial, viral, and fungal pathogens. These chemicals serve critical functions in infection prevention, food safety assurance, and industrial hygiene maintenance across commercial and institutional environments. Quaternary ammonium compounds occupy the largest volume position due to their broad spectrum efficacy and material compatibility, while hydrogen peroxide formulations represent the fastest-expanding category as healthcare facilities replace chlorine-based alternatives to reduce corrosion and respiratory irritation. Wipes and sprays capture disproportionate margin pools in the formulation dimension because ready-to-use formats eliminate dilution errors and support compliance documentation in regulated settings.
The EPA regulates disinfectant efficacy claims through its Office of Pesticide Programs, requiring standardized kill-time data against specified pathogen panels before products enter US commerce. FDA oversight of healthcare antiseptics and OSHA bloodborne pathogen standards create layered compliance obligations that filter out undercapitalized entrants. State-level green chemistry initiatives, particularly California's Safer Consumer Products regulations, are accelerating reformulation investments toward lower-toxicity active ingredients. Stakeholders must monitor evolving pathogen resistance patterns and regulatory tolerance thresholds for legacy actives to anticipate portfolio restructuring requirements.
Market Dynamics
Healthcare facilities are consolidating surface disinfection protocols around peroxide-based actives, forcing chlorine-bleed formulation specialists into accelerated R&D cycles or exit decisions. EPA's emerging pathogen guidance and California's Safer Consumer Products regulations are tightening active ingredient tolerances faster than legacy supply chains can reformulate.
Growth Catalysts
- Hospital-acquired infection prevention mandates:CMS reimbursement penalties for preventable infections are expanding surface disinfection budgets in acute care settings across the United States.
- REACH authorization pressures in Europe:Legacy quaternary ammonium compound restrictions are accelerating demand for biodegradable alternatives in German and French institutional procurement.
- Electrostatic sprayer deployment:Aviation and hospitality sectors are standardizing touchless application systems that reduce labor hours while improving coverage consistency.
Market Restraints
- Ethylene oxide sterilization residue limits:FDA's tightened medical device sterilization standards are forcing chemical sterilants into costly validation protocols.
- Isopropyl alcohol supply concentration:Gulf Coast petrochemical corridor disruptions expose formulation specialists to input volatility without backward integration.
- Material compatibility failures:Accelerated hydrogen peroxide concentrations above 7% degrade polycarbonate medical device housings, limiting application scope.
Strategic Opportunities
- India's healthcare infrastructure expansion:Ayushman Bharat hospital network growth is creating first-time institutional demand for EPA-registered disinfectants in tier-2 and tier-3 cities.
- UV-C and chemistry convergence:Combined photocatalytic oxidation systems are opening premium positioning in pharmaceutical cleanroom applications.
- California green chemistry mandates:Safer Consumer Products regulations are creating first-mover advantage for bio-based active ingredient developers.
Industry Challenges
- GLP laboratory capacity constraints:EPA efficacy study backlogs are extending product registration timelines beyond 24 months.
- Legacy ERP integration with batch record systems:Electronic signature compliance for 21 CFR Part 11 is forcing mid-tier manufacturers into unplanned capital expenditure cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfectant & Antimicrobial Chemicals Market |
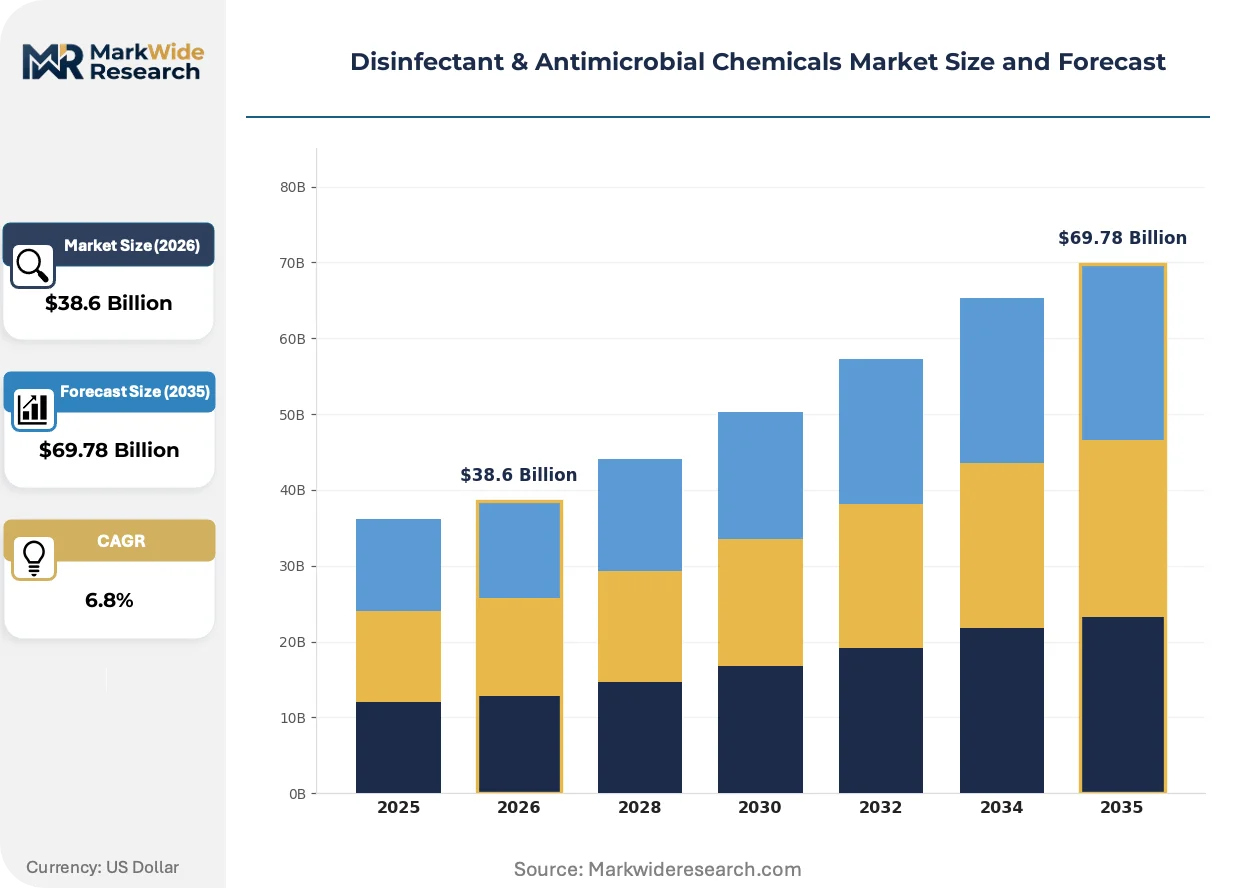
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Compounds, Hydrogen Peroxide, Sodium Hypochlorite, Alcohols Application: Household Cleaning, Industrial Hygiene, Healthcare Facilities, Food Processing Formulation: Aqueous Solutions, Powders, Wipes, Sprays End User: Residential, Commercial, Healthcare, Industrial |
| Companies Covered | Reckitt Benckiser Group plc, 3M Company, STERIS plc, Ecolab Inc, The Clorox Company, Procter & Gamble, SC Johnson Professional, GOJO Industries, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfectant & Antimicrobial Chemicals Market Evolving Landscape
Active ingredient delivery mechanisms are fragmenting across electrochemical generation, stabilized peroxide matrices, and bio-based alternatives. Formulation houses must now maintain parallel development tracks for divergent regulatory tolerances.
Stabilized hydrogen peroxide systems are replacing legacy chlorine-based protocols in endoscopy reprocessing suites. German hospital procurement consortia are mandating corrosion-free alternatives to extend flexible instrument service life. This transition is miniaturizing on-site generation systems that eliminate bulk chemical storage and simplify compliance documentation.
California's Safer Consumer Products regulations are forcing reformulation investments toward lower-toxicity quaternary ammonium alternatives. Manufacturers serving West Coast institutional buyers must now submit alternative analysis workplans before maintaining legacy product registrations. Healthcare and food service segments are absorbing premium pricing for compliant formulations to avoid supply discontinuity.
Consolidated procurement through GPOs and national distributors is compressing supplier rosters. Smaller regional formulation specialists are losing shelf placement to integrated manufacturers with captive active ingredient supply. United States acute care networks are standardizing around single-source contracts that bundle chemicals, application equipment, and compliance training.
Disinfectant & Antimicrobial Chemicals Market Segmentation
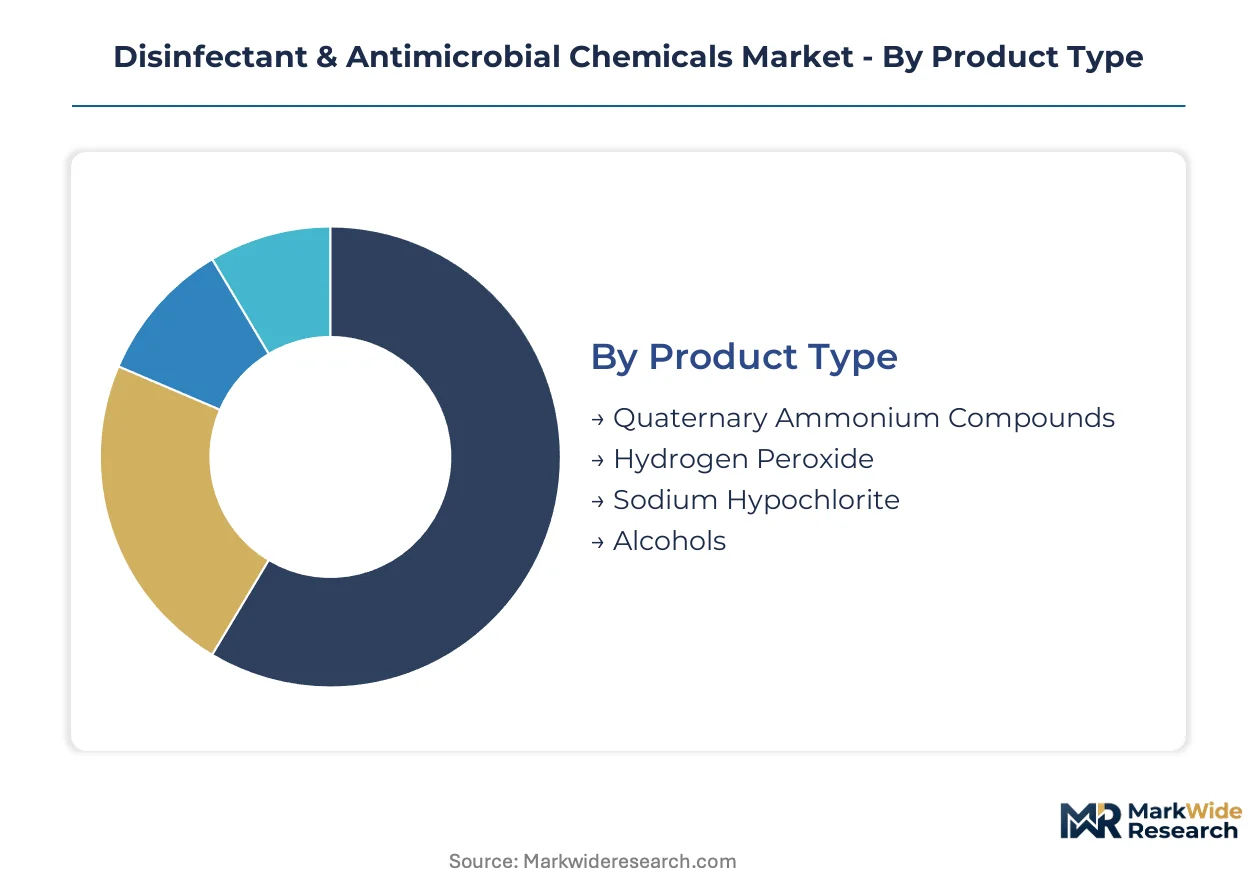
Segmentation in antimicrobial chemicals reveals how substitution pressures and regulatory tolerances fragment demand across active ingredient classes. Procurement patterns diverge sharply between cost-sensitive bulk buyers and compliance-driven institutional accounts.
Product Type:
Substitution pressure from green chemistry mandates and corrosion concerns is reshaping the active ingredient hierarchy faster than legacy supply chains can adapt.
- Quaternary Ammonium Compounds:These cationic surfactants deliver broad-spectrum efficacy against bacteria and enveloped viruses at concentrations typically ranging 400-800 ppm. Hospital networks in the United States favor quats for surface compatibility with polycarbonate medical devices, though California's Safer Consumer Products regulations are forcing reformulation toward lower-toxicity alternatives.
- Hydrogen Peroxide:Stabilized peroxide matrices at 3-7% concentrations provide sporicidal activity without the respiratory irritation associated with chlorine-based chemistry. German hospital procurement consortia are mandating these corrosion-free alternatives to extend flexible endoscope service life, driving fastest adoption in endoscopy reprocessing suites.
- Sodium Hypochlorite:Bleach-based formulations retain cost advantage in municipal water treatment and food processing sanitation despite material degradation risks.
- Alcohols:Isopropyl and ethyl alcohol solutions dominate hand hygiene and rapid surface disinfection where evaporation speed matters.
Quaternary ammonium compounds anchor the volume base while hydrogen peroxide gains share at the steepest rate.
Application:
Cost tier stratification separates premium institutional protocols from commodity household purchases.
- Healthcare Facilities:Acute care networks demand EPA-registered hospital disinfectants with documented kill times against antibiotic-resistant pathogens. CMS reimbursement penalties for preventable infections are expanding surface disinfection budgets in United States acute care settings.
- Industrial Hygiene:Manufacturing plants require heavy-duty formulations for biofilm control in cooling towers and process equipment.
- Household Cleaning:Consumer preferences for convenience formats drive wipes and spray packaging innovation.
- Food Processing:USDA and FDA dual oversight mandates residue-free chemistry for equipment and environmental surfaces in meat and dairy operations.
Healthcare facilities command premium pricing while food processing delivers the most volume-sensitive demand.
Formulation:
Application method determines compliance documentation burden and labor efficiency.
- Wipes:Pre-saturated nonwoven substrates eliminate dilution errors and support chain-of-custody records required in pharmaceutical cleanrooms.
- Sprays:Ready-to-use trigger and aerosol formats capture disproportionate margin pools through retail channel placement.
- Aqueous Solutions:Concentrated liquids for dilution-on-site remain dominant in cost-driven municipal and industrial accounts.
- Powders:Solid formulations reduce shipping costs and storage footprint for remote healthcare facilities in India's tier-2 and tier-3 cities.
Wipes anchor the margin structure while sprays expand most quickly through electrostatic application system adoption.
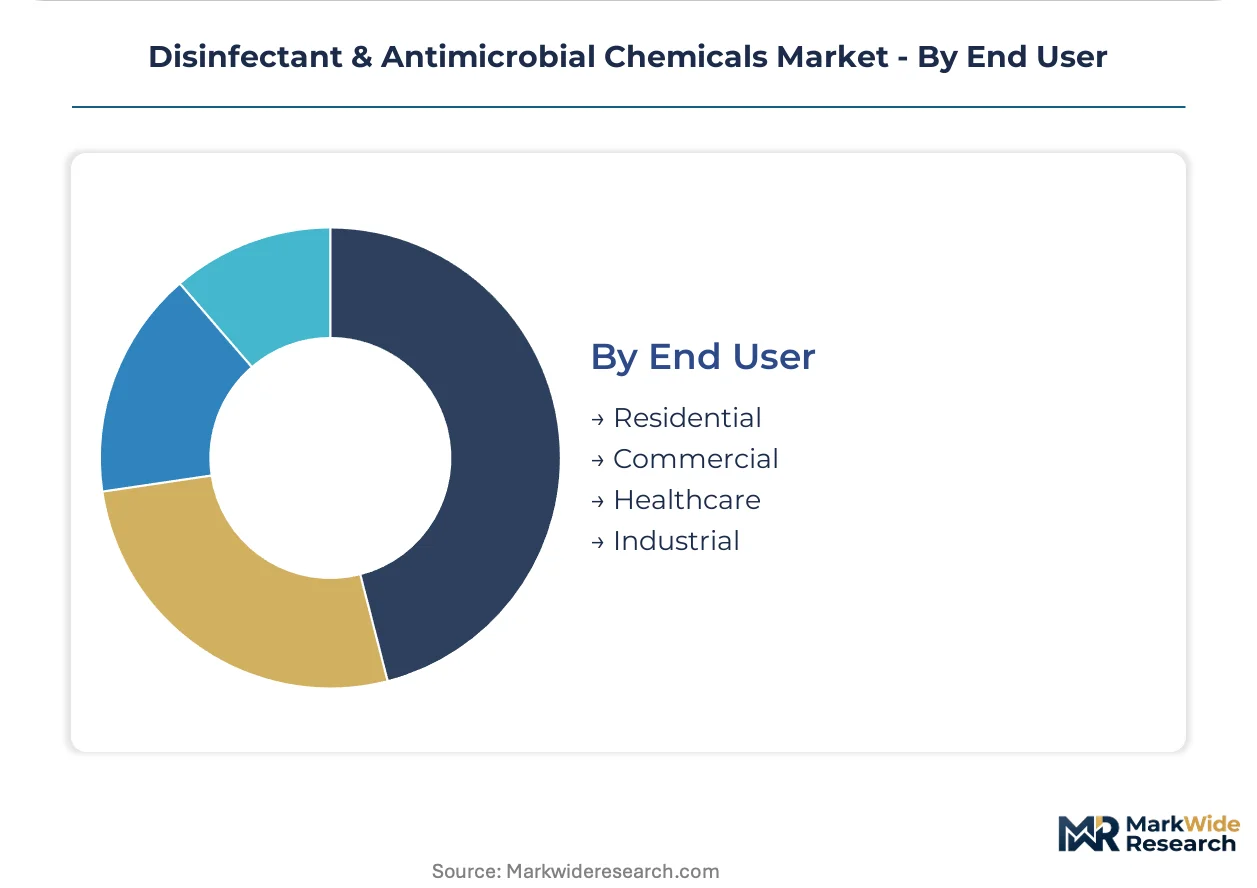
End User:
Customer type dictates procurement sophistication and regulatory exposure.
- Healthcare:Hospital systems consolidate through GPO contracts bundling chemicals, equipment, and training.
- Industrial:Manufacturing sites prioritize bulk chemical economics over formulation complexity.
- Commercial:Facility management services balance efficacy claims against liability exposure.
- Residential:Brand recognition and retail shelf placement drive consumer selection.
Healthcare anchors the compliance premium while commercial users represent the most price-elastic segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between institutional procurement in wealthy healthcare systems and cost-optimized bulk purchasing in emerging markets. The United States concentrates premium formulation demand through hospital GPO contracts, while India and Germany represent contrasting growth vectors driven by infrastructure expansion and regulatory substitution pressures respectively.
United States
Acute care networks drive premium disinfectant volumes through consolidated GPO procurement bundling chemicals with compliance training. CMS reimbursement penalties for hospital-acquired infections sustain elevated surface disinfection budgets across the country's 6,000-plus hospitals. EPA's Office of Pesticide Programs maintains stringent efficacy claim validation that filters out undercapitalized entrants, with registration timelines now stretching beyond 24 months.
Germany
Hospital procurement consortia mandate corrosion-free hydrogen peroxide alternatives to extend flexible endoscope service life, accelerating peroxide-based chemistry adoption. REACH authorization pressures on legacy quaternary ammonium compounds are forcing rapid portfolio restructuring toward biodegradable actives. The Rhine-Ruhr industrial corridor hosts concentrated formulation R&D activity serving Central European institutional buyers.
India
Ayushman Bharat hospital network expansion creates first-time institutional demand for EPA-registered disinfectants in tier-2 and tier-3 cities previously served by commodity bleach. CDSCO alignment with international registration standards is streamlining import pathways for multinational suppliers. Maharashtra and Gujarat pharmaceutical manufacturing clusters absorb disproportionate volumes of sporicidal formulations for cleanroom applications.
China
Domestic healthcare infrastructure investment drives demand for high-efficacy surface disinfectants in newly constructed tertiary hospitals. NMPA tightening of medical device sterilization standards parallels FDA trajectory, elevating validation requirements for chemical sterilants. Yangtze River Delta chemical manufacturing bases supply both domestic institutional buyers and export markets with concentrated active ingredients.
United Kingdom
NHS procurement consolidation favors suppliers offering bundled chemical and application equipment contracts with outcome-based compliance metrics. Post-Brexit regulatory divergence from EU REACH is creating uncertainty for quaternary ammonium compound suppliers serving both markets. London and Southeast England acute networks anchor premium pricing for ready-to-use wipe formats eliminating dilution errors.
Disinfectant & Antimicrobial Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in antimicrobial chemicals. Backward integration into active ingredient production separates Ecolab Inc's peroxyacetic acid supply control from formulation-only competitors lacking captive raw material security. The competitive terrain organizes around three archetypes: integrated chemical manufacturers with upstream synthesis capabilities, branded consumer goods houses with retail channel leverage, and institutional specialists with proprietary delivery system patents. Consolidation through GPO contract capture and on-site generation system deployment represents the dominant competitive moves reshaping supplier rosters.
Among Anglo-Dutch and American diversified conglomerates, Reckitt Benckiser Group plc and 3M Company exemplify contrasting positioning strategies. Reckitt Benckiser occupies the branded consumer disinfectant tier through sustained advertising investment and retail shelf dominance. 3M represents the institutional technology archetype, commanding premium placement through proprietary delivery systems rather than commodity chemistry. Ecolab Inc anchors the integrated manufacturer tier with captive supply chain control that smaller formulation specialists cannot replicate.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| 3M Company |
| STERIS plc |
| Ecolab Inc |
| The Clorox Company |
| Procter & Gamble |
| SC Johnson Professional |
| GOJO Industries |
| Kimberly-Clark Corporation |
| Others |
Value Network & Pricing Analysis
Hydrogen peroxide substitution for chlorine-based actives simultaneously redistributes supply geography toward Gulf Coast petrochemical corridors and compresses pricing premiums for corrosion-sensitive institutional buyers. This input shift tightens backward-integrated producers' margin capture while formulation-only specialists absorb volatility from concentrated isopropyl alcohol feedstock markets.
Pricing Analysis
After-sales revenue from bundled compliance training and on-site generation system maintenance drives lifetime value for institutional disinfectant suppliers. Three-tier pricing structure across EPA-registered hospital grade, commercial standard, and industrial economy levels separates acute care networks from cost-sensitive municipal buyers. Pricing pressure stems from GPO consolidation forcing volume discounts in exchange for sole-source contract status. Healthcare facilities exhibit lowest price sensitivity due to CMS penalty exposure, while food processing plants represent the most price-elastic procurement segment.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Rotterdam-Antwerp corridors constrain just-in-time active ingredient delivery for European and Asian formulation houses. Peroxyacetic acid production concentrates in the United States, Germany, and China; quaternary ammonium compound synthesis anchors in India and the United States. Raw material flows draw from ethylene oxide, fatty alcohols, and hydrogen peroxide precursors. Single-source vulnerability pervades Gulf Coast petrochemical corridor disruptions. Distribution runs through national GPOs, regional specialty distributors, and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where EPA registration timelines exceeding 24 months create regulatory entrenchment that shields incumbents from rapid competitive entry. Switching costs escalate through bundled equipment-chemical-training contracts that embed suppliers within hospital operational protocols.
For Market Incumbents: Shield market position by deepening captive supply of peroxyacetic acid precursors and accelerating on-site electrochemical generation system deployment. Consolidate GPO contract capture before REACH authorization pressures force portfolio restructuring. Prioritize California Safer Consumer Products pre-registration to preempt competitor first-mover advantage in green chemistry segments. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 city hospital networks where Ayushman Bharat infrastructure expansion creates first-time institutional demand absent entrenched supplier relationships. Target pharmaceutical cleanroom applications with photocatalytic oxidation system integration. Pursue CDSCO alignment partnerships to streamline import pathway navigation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap formulation specialists lacking backward integration but holding EPA-registered product portfolios and established GPO relationships. Long-term viability hinges on regulatory entrenchment durability and green chemistry transition execution. Monitor GLP laboratory capacity expansion as inflection indicator for registration timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Ecolab's peroxyacetic acid supply control demonstrates margin capture unavailable to formulation-only competitors. |
| On-Site Electrochemical Generation System Deployment | Stabilized hydrogen peroxide production at hospital sites eliminates bulk storage compliance burdens and locks in recurring chemical supply. |
| California Safer Consumer Products Pre-Registration | Alternative analysis workplan submission secures first-mover positioning before legacy quaternary ammonium restrictions tighten. |
| India Distribution Infrastructure Buildout | Ayushman Bharat hospital network penetration in tier-2 and tier-3 cities captures infrastructure expansion-driven demand. |
| UV-C Photocatalytic Oxidation Convergence | Combined chemistry-hardware systems command premium placement in pharmaceutical cleanroom applications. |
Research Methodology
Cross-validation between primary interviews with EPA registration consultants, hospital GPO contract managers, and formulation R&D directors and secondary validation through EPA Office of Pesticide Programs registration databases, CDSCO import pathway filings, and REACH authorization status records anchors the qualitative findings. Bottom-up triangulation from active ingredient production capacity and top-down validation from end-use procurement budgets frame the market sizing. Customs data from United States, Germany, and India trade flows corroborate supply geography assumptions.
Sensitivity analysis across hydrogen peroxide feedstock cost scenarios and EPA registration timeline variations shapes the projection framework. Segmentation dimensions span active ingredient class, formulation format, application sector, and regional regulatory cluster. CAGR derivation rests on hospital infection prevention budget trajectories, green chemistry mandate adoption curves, and electrostatic sprayer deployment rates. Industry-specific forecast inputs incorporate CMS reimbursement penalty evolution and REACH authorization sunset schedules.
Decision-makers should treat outputs as directional under sustained hospital-acquired infection prevention budget elevation and stable EPA efficacy claim validation standards; material deviation through regulatory acceleration or macroeconomic contraction would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Hypochlorous Acid Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
Disinfectant Chemicals Market
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
Color Preservatives Market