
 Color Preservatives Market | 2026-2036
Color Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Color Preservatives Market Analytics
Multi-source procurement among global food manufacturers is repositioning supply relationships across the color preservatives value chain. Sensient Technologies Corporation leverages its technical formulation depth to sustain premium positioning in natural color systems. Döhler Group anchors European supply through integrated extraction capabilities and beverage-sector specialization. GNT Group competes on botanical sourcing transparency, while Oterra dominates carotenoid and anthocyanin portfolios for clean-label applications.
Color preservatives comprise stabilizing compounds—ascorbates, citrates, tocopherols, and rosemary extracts—that inhibit oxidative degradation and maintain chromatic integrity in finished goods. These additives function through free-radical scavenging and metal chelation, preserving visual appeal across shelf life. Natural color preservatives lead formulation trends as food and beverage manufacturers reformulate around consumer preference for recognizable ingredient decks. Powder formulations capture margin pools through extended stability and lower logistics costs versus liquid alternatives. Synthetic segments retain volume in emerging-market pharmaceutical and textile applications where cost sensitivity dominates specification.
REACH and the EU Green Deal constrain synthetic additive registration while accelerating natural-substance dossier requirements across Europe. FDA color additive regulations and FSSAI labeling mandates in India create divergent compliance pathways that fragment product portfolios. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation investments and avoid market-access delays.
Market Dynamics
Clean-label mandates from REACH and FSSAI are forcing simultaneous reformulation across multiple preservative categories, compressing development timelines while fragmenting supplier qualification requirements.
Growth Catalysts
- Eu Green Deal chemical substitution:REACH Annex XIV expansion accelerates natural antioxidant dossier submissions across food and cosmetic applications.
- Beverage sector reformulation:Carbonated and functional drink manufacturers replace synthetic stabilizers with rosemary extract and tocopherol blends to meet retailer clean-label specifications.
- India enforcement tightening:FSSAI's 2023 labeling rules and BIS standard updates drive domestic procurement shifts toward certified natural preservative suppliers.
Market Restraints
- Botanical raw material volatility:Rosemary and marigold harvest yields fluctuate with Mediterranean and Indian monsoon patterns, creating input cost instability for natural extract producers.
- Extraction capacity concentration:Supercritical CO2 processing infrastructure clusters in Germany and Italy, creating geographic supply bottlenecks for high-purity carotenoid production.
- Synthetic cost anchoring:Petroleum-derived BHT and BHA retain price advantages in Southeast Asian and African processed food sectors, limiting natural penetration.
Strategic Opportunities
- Precision fermentation scale-up:Microbial production of astaxanthin and lycopene bypasses agricultural extraction constraints, enabling supply security for pharmaceutical and nutraceutical applications.
- Sub-Saharan Africa underpenetration:Nigeria and Kenya processed food sectors lack domestic natural preservative formulation expertise, creating technical service entry points.
- EU CSRD supply chain disclosure:Corporate sustainability reporting mandates force CPG brands to document ingredient provenance, advantaging suppliers with certified transparent sourcing.
Industry Challenges
- Natural-synthetic equivalency testing:Demonstrating shelf-life parity between clean-label and legacy formulations extends R&D cycles by 12-18 months for reformulating manufacturers.
- Cross-jurisdiction dossier fragmentation:Divergent EFSA, FDA, and FSSAI safety data requirements force redundant toxicology studies, inflating registration costs for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Color Preservatives Market |
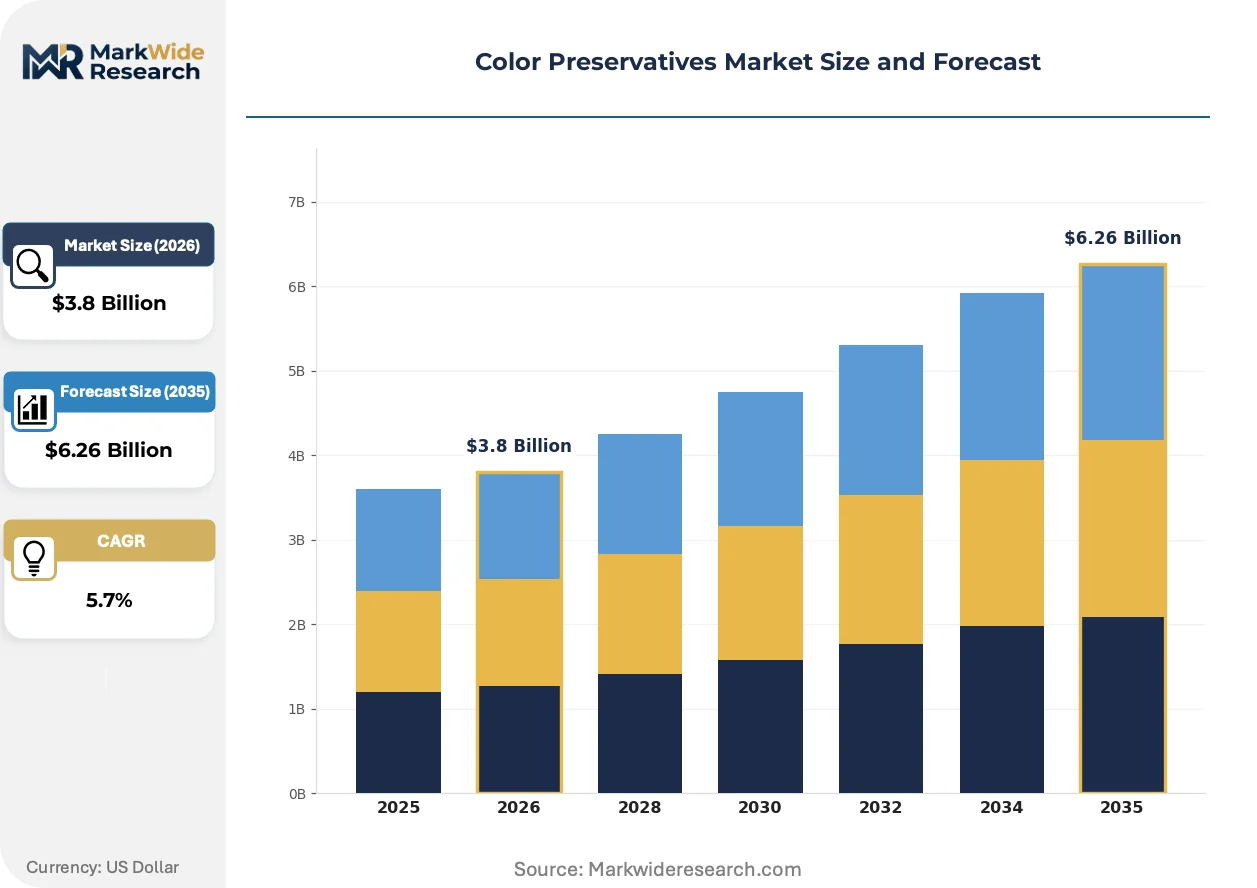
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Natural, Organic, Inorganic Application: Food & Beverage, Cosmetics, Textile, Pharmaceuticals End User: Food Manufacturers, Cosmetic Companies, Textile Producers, Pharmacies Formulation: Liquid, Powder, Granule, Emulsion |
| Companies Covered | Sensient Technologies Corporation, Archer Daniels Midland Company, Döhler Group, Givaudan, Oterra, GNT Group, BASF SE, DSM-Firmenich, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Color Preservatives Market Evolving Landscape
Formulation science is converging with bioprocessing advances to unlock scalable natural alternatives, while regulatory disclosure mandates transform supply chain transparency from marketing advantage to compliance necessity.
Encapsulation technology is modularizing antioxidant delivery systems. Liposomal and nano-emulsion formats protect ascorbates and tocopherols from premature oxidation during high-temperature processing. Bakery and frying oil manufacturers adopt these formats fastest where thermal stress degrades conventional additives. Modular delivery architectures enable preservative suppliers to customize release profiles for specific pH and temperature windows without reformulating active compounds.
REACH authorization sunset dates for synthetic phenolic antioxidants are compressing substitution timelines. ECHA's 2025-2027 review schedule for BHT and TBHQ forces food manufacturers to validate natural alternatives under accelerated stability protocols. European margarine and edible oil processors face the tightest compliance windows, driving joint development contracts with rosemary extract suppliers to secure qualified supply before authorization withdrawals.
Retailer clean-label scorecards are restructuring procurement qualification criteria. Walmart and Carrefour sustainability indices now weight ingredient recognizability above cost in supplier selection algorithms. North American private-label food manufacturers respond fastest, reformulating around consumer-identifiable preservatives like mixed tocopherols and green tea extract. This behavioral shift concentrates volume among suppliers with third-party organic and non-GMO certifications, compressing margins for uncertified competitors.
Color Preservatives Market Segmentation
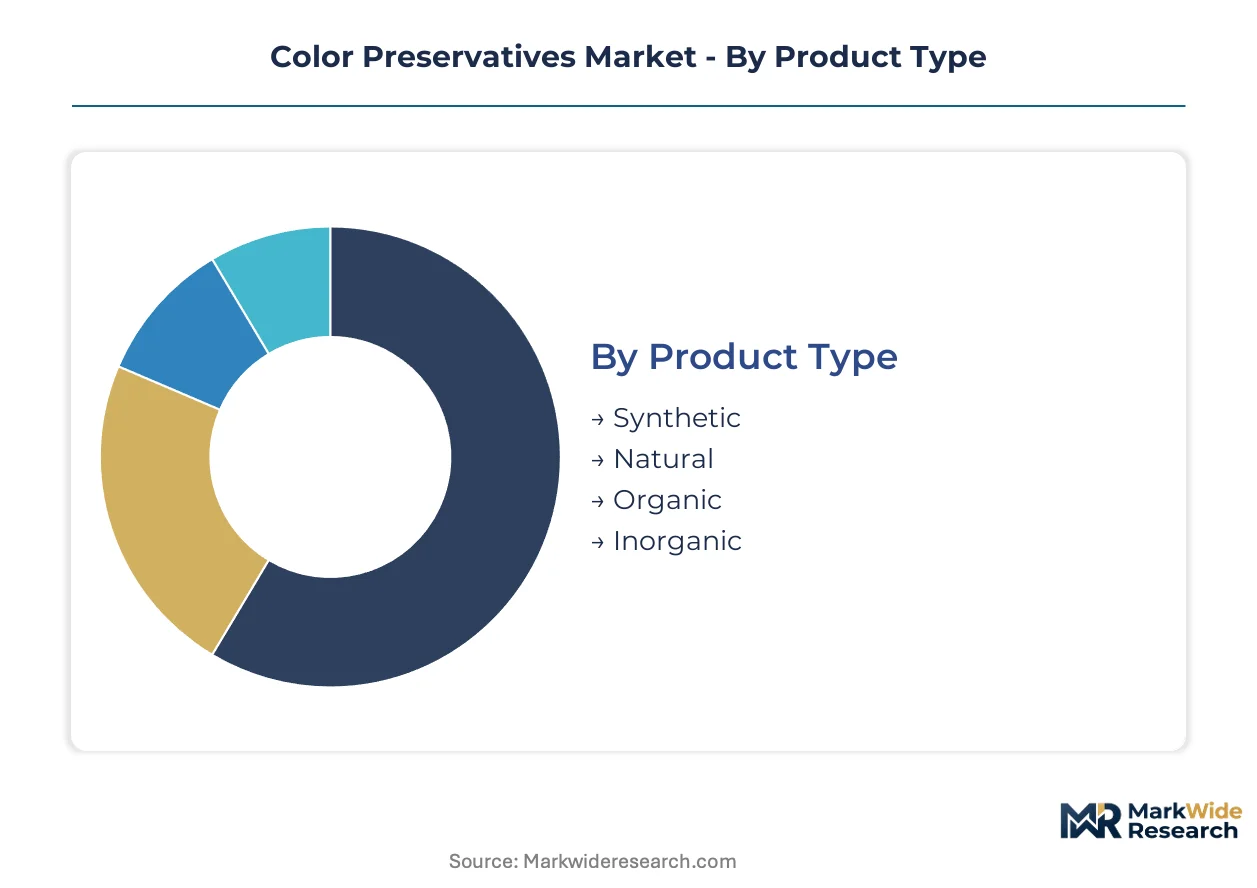
Segmentation in color preservatives determines regulatory pathway complexity and supply chain configuration. Formulation choices directly impact REACH dossier requirements, FSSAI certification timelines, and customer qualification protocols across end-use verticals.
Product Type:
Natural and organic segments carry heavier certification burdens than synthetic equivalents, with EFSA novel food approvals and USDA organic compliance adding 18-24 months to market entry. Synthetic formulations face REACH Annex XIV authorization pressures but require simpler toxicology packages.
- Natural:Botanical extracts—rosemary, green tea, and mixed tocopherols—dominate clean-label reformulation. Beverage manufacturers in Germany and France drive procurement as retailer scorecards penalize synthetic alternatives. Supply security depends on Mediterranean and Indian monsoon harvests.
- Synthetic:Petroleum-derived BHT, BHA, and TBHQ retain cost advantages in Southeast Asian processed foods. REACH sunset dates for phenolic antioxidants compress substitution timelines to 2025-2027, forcing accelerated natural validation protocols.
- Organic:Certified organic tocopherols and rosemary extracts command premium positioning through USDA and EU organic logos. Cosmetic applications in California and Lombardy absorb highest volumes where certification transparency drives consumer preference.
- Inorganic:Mineral-based stabilizers including citrates and ascorbates serve pharmaceutical parenteral applications. USP and EP monograph compliance governs procurement from injectable drug manufacturers in New Jersey and Basel.
Leading the category by volume: Synthetic. Expanding most quickly: Natural.
Application:
Application segments diverge sharply in margin structure and technical service intensity. Food and beverage demands formulation partnership; pharmaceutical requires GMP documentation depth.
- Food & Beverage:Margarine, edible oils, and carbonated drinks absorb bulk volumes. Encapsulation formats protect actives through high-temperature processing. European edible oil processors face tightest REACH compliance windows.
- Cosmetics:Skincare and color cosmetics prioritize photostability and skin compatibility. Korean and French formulators specify liposomal delivery for vitamin E derivatives. Clean beauty mandates accelerate rosemary extract substitution.
- Textile:Dye fixation and oxidative protection for natural fibers. Synthetic BHT dominates cost-sensitive Bangladesh and Vietnamese garment sectors where natural alternatives remain uneconomical.
- Pharmaceuticals:Parenteral and oral dosage forms demand USP-grade antioxidants. Astaxanthin from precision fermentation gains traction in ophthalmic applications. Regulatory dossier costs exclude smaller API manufacturers.
Highest margin capture: Pharmaceuticals. Fastest volume growth: Food & Beverage.
End User:
End user concentration shapes supplier relationship models. Multinational food manufacturers demand global specification harmonization; textile producers prioritize spot purchasing flexibility.
- Food Manufacturers:Global CPG brands drive standardization across production facilities. Walmart and Carrefour sustainability indices now weight ingredient recognizability above cost in procurement algorithms.
- Cosmetic Companies:Indie brands and multinational houses split procurement patterns. Korean beauty conglomerates specify fermented astaxanthin for premium positioning.
- Textile Producers:Bangladesh and Vietnam garment clusters absorb commodity-grade synthetic stabilizers. Natural penetration limited by finished goods price ceilings.
- Pharmacies:Compounding and OTC supplement channels drive small-batch tocopherol demand. USP verification programs govern supplier qualification.
Most consolidated buying power: Food Manufacturers. Steepest expansion trajectory: Cosmetic Companies.
Formulation:
Formulation choice determines logistics economics and processing compatibility. Powder formats extend shelf life but sacrifice dissolution speed; emulsions enable direct incorporation but raise transport costs.
- Liquid:Ready-to-dose convenience for high-volume beverage and oil processing. Thermal degradation during shipping limits geographic reach from production sites.
- Powder:Extended stability and lower logistics costs versus liquid alternatives. Bakery and dry mix manufacturers specify microencapsulated formats for flour incorporation.
- Granule:Intermediate flow properties for tableting and direct compression. Pharmaceutical oral solid dosage forms dominate uptake.
- Emulsion:Liposomal and nano-emulsion architectures protect actives through thermal stress. Frying oil and extruded snack applications adopt fastest.
Dominant by volume: Powder. Gaining share fastest: Emulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean rosemary harvests and Indian marigold cultivation anchor raw-material supply for natural color preservatives, while regulatory divergence across major economies fragments compliance pathways.
Germany
Beverage manufacturers in Bavaria and Baden-Württemberg drive demand for rosemary extract formulations. ECHA's REACH Annex XIV review schedule for synthetic phenolic antioxidants accelerates substitution timelines through 2027. Supercritical CO2 extraction infrastructure clusters around Frankfurt-Rhine-Main, concentrating high-purity carotenoid production capacity.
India
Domestic food processors in Maharashtra and Gujarat reformulate around clean-label specifications. FSSAI's 2023 labeling rules and updated BIS standards enforce stricter additive disclosure requirements. Marigold cultivation in Karnataka and Tamil Nadu supplies lutein feedstock for regional extractors serving both food and pharmaceutical channels.
United States
Private-label manufacturers in Chicago and New Jersey respond to Walmart sustainability scorecards prioritizing ingredient recognizability. FDA color additive regulations maintain distinct approval pathways for natural versus synthetic categories. California cosmetic formulators in Los Angeles County specify organic-certified tocopherols for clean beauty positioning.
China
Precision fermentation startups in Shanghai and Jiangsu province scale microbial astaxanthin production for nutraceutical applications. SAMR food additive standards govern import registration for foreign natural preservative suppliers. Yangtze River Delta chemical processors invest in encapsulation technology for thermal-stable antioxidant delivery.
Brazil
Processed food manufacturers in São Paulo and Minas Gerais retain synthetic BHT formulations for cost-sensitive margarine applications. ANVISA additive regulations lag European substitution timelines, preserving legacy preservative volumes. Southern agricultural regions supply botanical raw materials for emerging domestic extraction capacity.
Color Preservatives Market Competitive Landscape
Capacity expansion dominates the current landscape as extraction infrastructure scales to meet compressed REACH substitution deadlines. The vendor base separates into three functional tiers: integrated multinational suppliers with fermentation and botanical capabilities, regional specialists focused on single-source extraction, and commodity distributors serving cost-sensitive emerging markets. Strategic archetypes include vertically integrated natural extractors controlling upstream cultivation, technology licensors of encapsulation delivery systems, and formulation partners offering application-specific stability testing. M&A activity concentrates on fermentation biotechnology acquisitions, while geographic expansion targets Indian and Southeast Asian procurement offices.
Within the integrated multinational tier, Sensient Technologies Corporation and Döhler Group exemplify divergent specialization models. Sensient anchors North American and European supply through technical formulation depth in natural color systems. Döhler leverages German extraction infrastructure and beverage-sector focus to secure continental procurement relationships. GNT Group occupies a distinct position built on botanical sourcing transparency credentials for clean-label applications.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| Döhler Group |
| Givaudan |
| Oterra |
| GNT Group |
| BASF SE |
| DSM-Firmenich |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Marigold flower price indices in Karnataka and Tamil Nadu cascade through lutein extraction economics into three-tier pricing structures across premium certified, standard food-grade, and economy synthetic tiers. European edible oil processors absorb the steepest premia for REACH-compliant rosemary extracts, while Southeast Asian margarine manufacturers anchor contract negotiations to petroleum-derived BHT spot markets.
Pricing Analysis
Warranty and shelf-life guarantee bundling separates premium natural extract suppliers from unbundled commodity distributors. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and organic traceability. Pricing pressure stems from FSSAI enforcement compressing synthetic-to-natural substitution timelines in India. Food manufacturers in Maharashtra exhibit highest price sensitivity; pharmaceutical formulators in Basel accept premium positioning for USP-grade tocopherols.
Supply Chain Analysis
Dual-sourcing mandates from Walmart and Carrefour sustainability scorecards force CPG brands to qualify redundant rosemary extract suppliers across Mediterranean and Indian origins. Supercritical CO2 processing infrastructure concentrates in Germany and Italy, while marigold cultivation feeds from Karnataka and Tamil Nadu. Single-source vulnerability persists for high-purity carotenoid streams. Distribution runs through Rotterdam and Singapore regional hubs into European and Asia-Pacific formulation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where fermentation biotechnology and captive botanical cultivation determine supply security. Players pursue upstream control over precision astaxanthin production and backward integration into certified organic rosemary estates.
For Market Incumbents: Extend technical service capabilities into accelerated stability testing to compress customer reformulation cycles. Build captive marigold cultivation in Tamil Nadu to offset monsoon-driven raw material volatility. Sensient Technologies and Döhler Group already anchor this defensive posture. For New Entrants and Emerging Players: Begin with technical partnership models in Nigeria and Kenya where domestic natural preservative formulation expertise remains scarce. Target beverage sector reformulation in sub-Saharan Africa. Fermentation-derived astaxanthin offers the cleanest white-space entry vector. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation specialists in Shanghai and Jiangsu province where SAMR registration barriers exclude foreign competition. Five-to-ten year viability hinges on microbial production scale-up displacing agricultural extraction. Watch ECHA authorization sunset announcements as inflection signals for natural substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial astaxanthin production bypasses Mediterranean harvest volatility for pharmaceutical supply security. |
| Backward Integration into Cultivation | Captive rosemary estates in Portugal and Spain secure REACH-compliant feedstock for European processors. |
| Encapsulation Technology Licensing | Liposomal delivery patents protect tocopherols through high-temperature frying oil applications. |
| Joint Development Contracts | European margarine processors pre-qualify natural alternatives before BHT authorization withdrawals. |
| Sub-Saharan Technical Service Expansion | Lagos and Nairobi procurement offices capture unmet demand from processed food manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this color preservatives assessment. Primary interviews with extraction plant managers, F&B procurement leads at global CPG brands, cosmetic formulators in Lombardy, and pharmaceutical GMP auditors combined with ECHA dossier databases, FSSAI notification records, and EU import statistics. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Data-stream reconciliation across marigold harvest reports, supercritical CO2 capacity utilization, and REACH authorization timelines informed the analytical framework. Segmentation dimensions spanned natural versus synthetic grade tiers, food versus pharmaceutical end-use industries, powder versus emulsion formulation formats, and regional regulatory clusters. CAGRs derived from substitution elasticity modeling and clean-label penetration curves. Precision fermentation yield improvements and FSSAI enforcement intensity served as industry-specific forecast inputs across the projection horizon.
Botanical harvest failure, ECHA authorization schedule acceleration, and FSSAI labeling rule postponement are the dominant revision risks. Deviation in monsoon-driven marigold yields would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Hypochlorous Acid Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
Sterilants Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Vaporized Hydrogen Peroxide Sterilization Systems Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Disinfectant Chemicals Market