
 Preservatives Market | 2026-2036
Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Preservatives Market Intelligence
ISO 22000 certification is redrawing competitive boundaries for preservative suppliers serving multinational food manufacturers. BASF SE leverages its integrated acetic acid and propionic acid platforms to sustain cost positions across European and Asian supply corridors. Kerry Group anchors its portfolio in clean-label fermentation-derived solutions, competing directly against synthetic incumbents in beverage preservation applications.
Preservatives are chemical or biological additives that inhibit microbial spoilage, enzymatic degradation, or oxidative rancidity in formulated products, typically functioning at concentrations between 0.01% and 0.3% by weight depending on the active moiety and target pathogen spectrum. Their primary commercial purpose is extending shelf stability while maintaining sensory and nutritional integrity across distribution chains. Natural Preservatives command widening formulation slots in premium food and personal care lines as consumer label scrutiny intensifies, though Synthetic Preservatives still dominate volume in cost-sensitive beverage and bakery segments where pH control and mold inhibition remain non-negotiable. The Pharmaceutical application dimension represents a concentrated margin pool where USP-NF and EP compliance requirements filter out commodity suppliers.
The US FDA governs preservative safety through 21 CFR 172 and 182 listings, while the EPA regulates antimicrobial pesticides used in food-contact applications under FIFRA, creating dual compliance tracks for suppliers with broad product portfolios. The EU EFSA evaluates new preservative submissions under novel food and food additive pathways, with REACH adding substance registration burdens that favor larger registrants with dedicated toxicology dossiers. Stakeholders must monitor evolving clean-label definitions and regional maximum-permitted-level adjustments to align R&D pipelines with shifting formulation standards.
Market Dynamics
Clean-label formulation mandates from multinational food manufacturers are compressing synthetic preservative volumes while fermentation-derived alternatives scale capacity. This demand pivot is restructuring supplier qualification criteria and capital allocation across the value chain.
Growth Catalysts
- REACH substance registration:The EU's tightening toxicology dossier requirements favor incumbent registrants with dedicated regulatory affairs teams, consolidating viable supply bases for European food processors.
- Beverage shelf-life extension:Aseptic packaging convergence with natural acidulants is opening formulation slots in premium ready-to-drink categories previously dominated by benzoates.
- India food processing expansion:Domestic cold chain infrastructure gaps and export compliance requirements are accelerating preservative adoption in processed fruit, dairy, and spice value chains.
Market Restraints
- Acetic acid feedstock volatility:Petrochemical derivative pricing swings compress margin predictability for synthetic acid producers serving cost-sensitive bakery segments.
- Clean-label substitution ceiling:Natural alternatives face efficacy thresholds below 0.1% concentration in high-water-activity applications, limiting displacement potential in certain beverage matrices.
- FSSAI additive approval timelines:India's novel food additive pathway averages 18-24 months for full clearance, delaying market entry for fermentation-derived actives.
Strategic Opportunities
- Pharmaceutical USP-NF compliance:Injectable and ophthalmic formulation standards filter out commodity suppliers, creating concentrated margin pools for dedicated cGMP preservative manufacturers.
- Personal care microbiome positioning:Skin flora-compatible preservation systems are opening premium slots in Korean and Japanese cosmetic formulations.
- Biopreservation convergence:Bacteriocin-cultured dairy byproduct streams paired with modified atmosphere packaging are enabling label-friendly meat preservation in European retail channels.
Industry Challenges
- ISO 22000 auditor scarcity:Certification body capacity constraints are extending supplier qualification timelines for multinational food manufacturers.
- Cross-contamination control capex:Dedicated fermentation and synthetic production lines require segregated facility investments to meet allergen and kosher/halal certification standards.
- Legacy formulation revalidation:Decades-old product specifications in institutional foodservice channels resist clean-label reformulation due to sensory benchmarking requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preservatives Market |
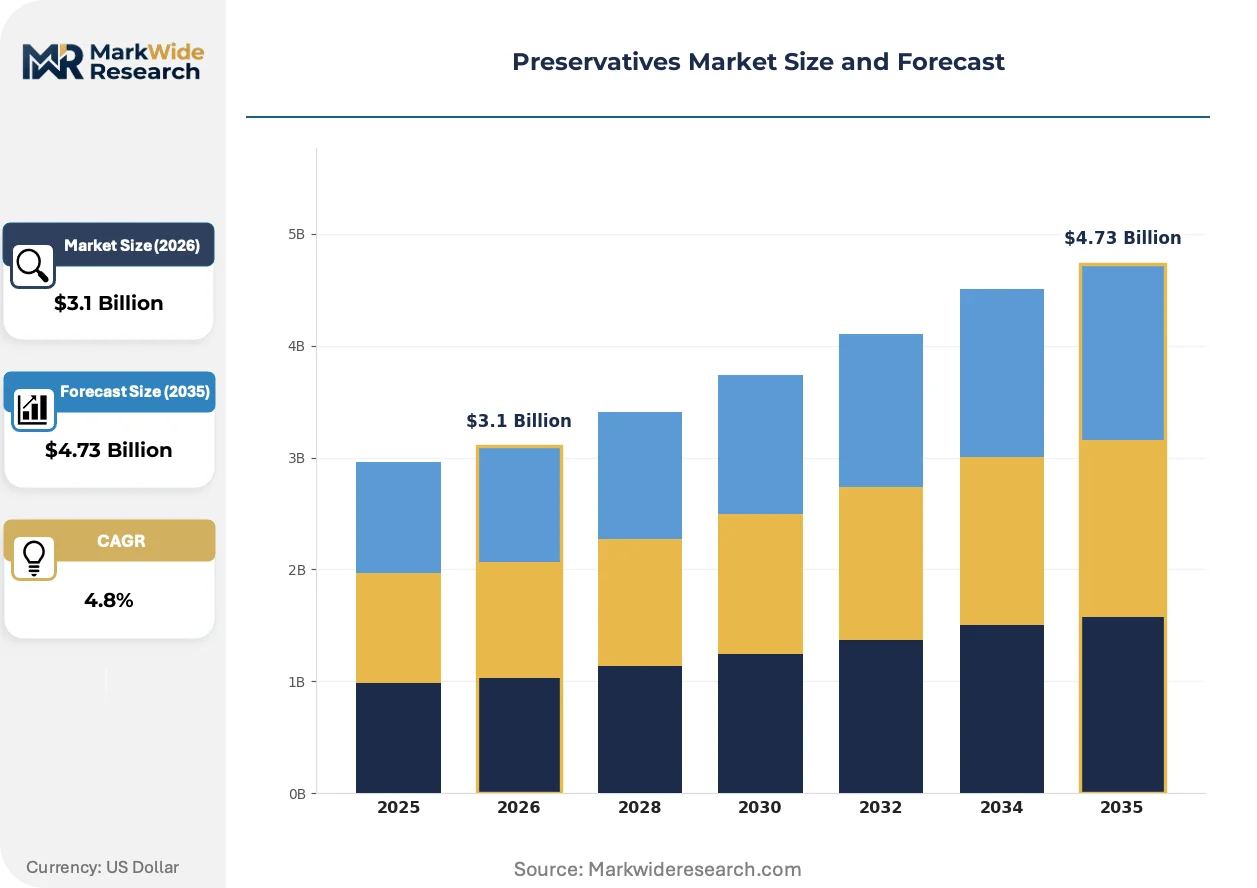
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.73 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Preservatives, Natural Preservatives, Organic Acids, Antioxidants Application: Food Preservation, Beverage Preservation, Personal Care, Pharmaceuticals Form: Liquid, Powder, Granules, Tablets End User: Food Industry, Cosmetic Industry, Healthcare, Retail |
| Companies Covered | BASF SE, Cargill, Kerry Group, DuPont, Corbion, DSM, Celanese Corporation, Kemin Industries, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preservatives Market Strategic Shifts & Innovations
Biotechnology-derived preservation actives are crossing cost parity thresholds with petrochemical synthetics in multiple application categories. This technological convergence is redrawing competitive boundaries between fermentation specialists and integrated chemical producers.
High-pressure processing equipment paired with reduced-dose chemical preservation is fragmenting the traditional shelf-life extension market. Premium juice and guacamole processors are adopting this hybrid approach to achieve 45-60 day refrigerated stability without full synthetic dependence. The capital intensity of HPP systems is concentrating adoption among contract manufacturers serving multiple brand portfolios.
EFSA's 2023 re-evaluation of sorbic acid and its salts is tightening maximum permitted levels across infant food and dietary supplement categories. Reformulation costs are falling disproportionately on mid-sized European supplement manufacturers lacking in-house stability testing infrastructure. The regulatory friction is accelerating interest in cultured dextrose and vinegar-based alternatives from Benelux and German suppliers.
Direct procurement relationships between preservative active producers and multinational food manufacturers are displacing traditional distributor intermediaries in high-volume categories. Category managers at North American beverage and sauce companies are negotiating multi-year supply agreements with fermentation-derived specialists. This channel compression is most visible in clean-label reformulation programs where technical service intensity exceeds distributor capabilities.
Preservatives Market Segmentation
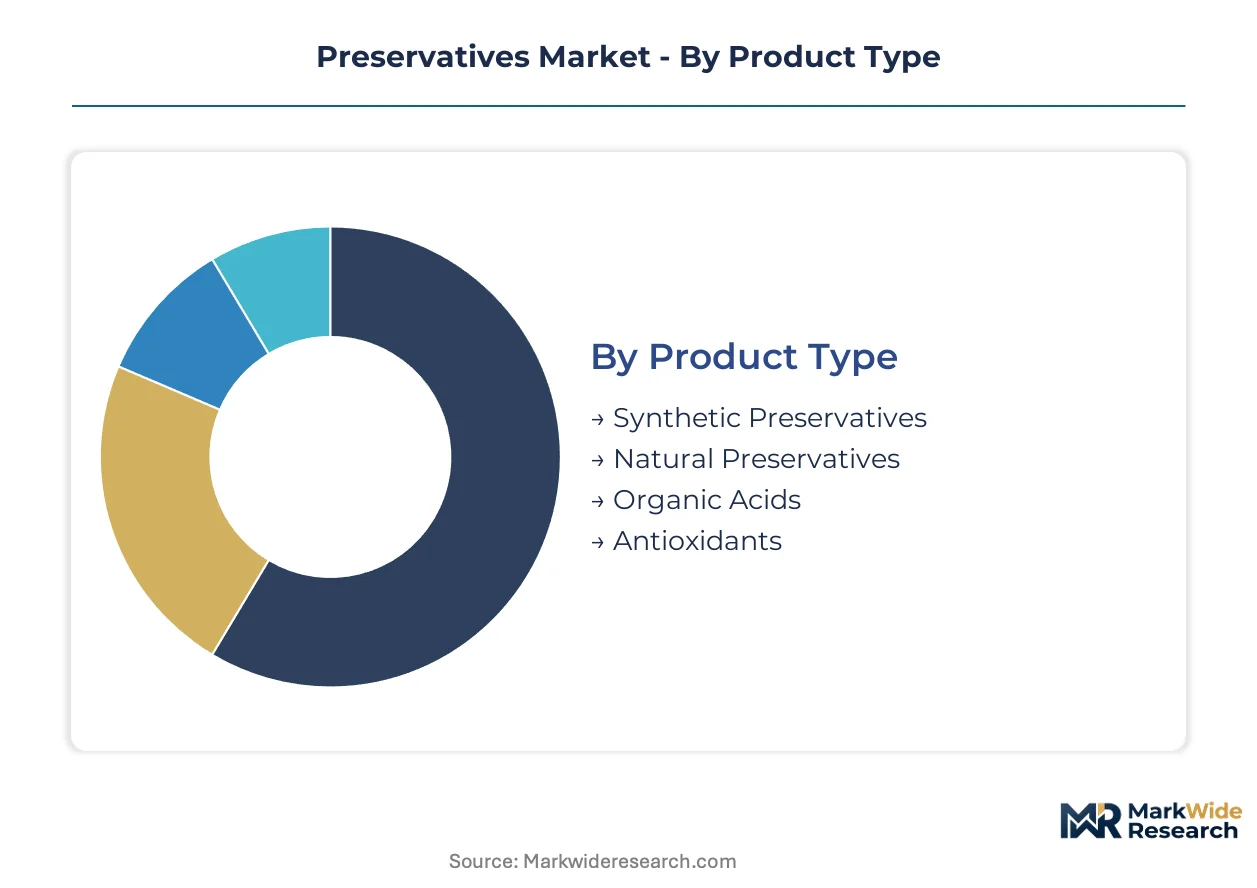
Preservative selection hinges on regulatory pathway complexity and end-use performance thresholds. Formulators weigh cost efficiency against clean-label positioning across divergent compliance environments.
Product Type:
REACH registration status and US FDA 21 CFR listing determine viable supplier pools for each chemistry class.
- Synthetic Preservatives:Petrochemical-derived benzoates, sorbates, and parabens deliver reliable microbial inhibition at 0.05-0.2% concentrations. US FDA 21 CFR 172 listings and EPA FIFRA registrations create dual compliance tracks that filter out smaller suppliers in North American beverage and bakery applications.
- Natural Preservatives:Plant extracts, rosemary oleoresins, and cultured dextrose formulations command premium slots in EU and North American clean-label programs. EFSA novel food evaluations and USDA organic certification requirements extend supplier qualification timelines to 18-36 months.
- Organic Acids:Acetic, propionic, and citric acid platforms dominate cost-sensitive bakery and sauce segments.
- Antioxidants:BHA, BHT, and tocopherol variants protect lipid oxidation in edible oils and personal care emulsions.
Synthetic Preservatives handle the majority of throughput; Natural Preservatives is the fastest mover on share.
Application:
End-use performance requirements stratify procurement criteria across pH tolerance, water activity thresholds, and sensory neutrality demands.
- Food Preservation:Bakery, dairy, and processed meat applications require mold inhibition and botulism control across pH 4.6-7.0 ranges. India's FSSAI additive approvals and cold chain infrastructure gaps drive preservative intensity in domestic processed fruit and spice value chains.
- Beverage Preservation:Aseptic packaging convergence with natural acidulants is displacing benzoates in premium ready-to-drink categories. pH control below 4.6 remains non-negotiable for ambient shelf stability.
- Personal Care:Korean and Japanese cosmetic microbiome-compatible preservation systems command premium positioning.
- Pharmaceuticals:USP-NF and EP compliance filters out commodity suppliers in injectable and ophthalmic formulations.
Food Preservation handles the majority of throughput; Pharmaceuticals is climbing the fastest on margin contribution.
Form:
Handling economics and dissolution kinetics determine format selection across manufacturing scale and application method.
- Liquid:Ready-to-dose solutions dominate high-volume beverage and sauce manufacturing where automated dosing systems require pumpable feedstocks.
- Powder:Spray-dried and crystalline formats reduce freight costs and extend ambient stability in dry bakery premixes and seasoning blends.
- Granules:Controlled particle size distribution improves dispersion in meat brine injections and pharmaceutical tablet granulation.
- Tablets:Unit-dose formats serve small-batch pharmaceutical compounding and institutional foodservice reconstitution.
Liquid handles the majority of throughput; Powder is gaining share fastest in freight-sensitive supply chains.
End User:
Scale concentration and technical service intensity fragment procurement relationships across direct and distributor channels.
- Food Industry:Multinational manufacturers with ISO 22000 certification requirements are consolidating direct procurement relationships with fermentation-derived specialists. Technical service teams co-develop reformulation protocols for clean-label transitions.
- Cosmetic Industry:Korean and Japanese formulators drive microbiome-compatible preservation R&D through dedicated supplier partnerships.
- Healthcare:Hospital pharmacies and compounding facilities require USP-grade documentation and lot traceability.
- Retail:Private-label and artisan producers purchase through distributor intermediaries with blended minimum order quantities.
Food Industry handles the majority of throughput; Healthcare is expanding most quickly on compliance-premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational food manufacturers with ISO 22000 certification requirements concentrate procurement authority in Germany, the United States, India, China, and Brazil. These five markets generate divergent formulation demands shaped by local regulatory stringency and cold chain maturity.
Germany
Benelux and German suppliers dominate cultured dextrose and vinegar-based alternatives as EFSA's 2023 sorbic acid re-evaluation tightens maximum permitted levels. REACH substance registration burdens favor incumbent registrants with dedicated toxicology dossiers. The Baden-Württemberg chemical cluster anchors fermentation-derived preservation capacity serving pan-European clean-label reformulation programs.
United States
Beverage manufacturers negotiate multi-year supply agreements with fermentation-derived specialists as aseptic packaging convergence opens premium ready-to-drink slots. US FDA 21 CFR 172 listings and EPA FIFRA registrations create dual compliance tracks that filter smaller suppliers. Chicago and Minneapolis food processing corridors drive preservative intensity in sauce and dairy value chains.
India
Domestic food processing capacity expansion and export compliance requirements accelerate preservative adoption in processed fruit and spice segments. FSSAI additive approval timelines averaging 18-24 months delay market entry for novel fermentation-derived actives. Maharashtra and Gujarat industrial zones concentrate bakery and dairy preservative formulation demand.
China
Acetic acid platform producers serve cost-sensitive bakery segments despite petrochemical feedstock pricing volatility. SAMR food additive standards and GB compliance requirements structure supplier qualification protocols. The Yangtze River Delta manufacturing belt houses integrated organic acid production serving domestic and export food processors.
Brazil
Processed meat and dairy sectors drive demand for mold inhibition and botulism control across pH-variable applications. ANVISA preservative approvals align with Mercosur harmonization pressures. São Paulo state anchors South American preservative distribution infrastructure serving Andean and Southern Cone markets.
Preservatives Market Key Industry Players
Player mix skews toward integrated chemical conglomerates and fermentation-derived specialists. The supplier base stratifies across three tiers: petrochemical-integrated acid producers with captive feedstock positions, biotechnology platforms leveraging cultured dextrose and bacteriocin streams, and regional compounders serving cost-sensitive emerging markets. Dominant competitive moves include backward integration into acetic acid feedstocks and strategic partnerships with aseptic packaging equipment manufacturers.
Within the integrated chemical tier, BASF SE and Celanese Corporation exemplify petrochemical-anchored positioning. Among fermentation-derived specialists, Kerry Group and Corbion occupy positions bridging clean-label formulation services with active production. DSM represents the nutrition-science conglomerate archetype, while Kemin Industries anchors the botanical-extract preservation segment. These five entities collectively span the technology spectrum from synthetic acid platforms to plant-derived antioxidant systems.
| Leading Market Players |
|---|
| BASF SE |
| Cargill |
| Kerry Group |
| DuPont |
| Corbion |
| DSM |
| Celanese Corporation |
| Kemin Industries |
| Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
Sixty-day REACH dossier review cycles concentrate pricing power among incumbent registrants with dedicated toxicology teams, while acetic acid feedstock volatility feeds directly into synthetic acid producer margins. Inventory buffers at German fermentation facilities insulate clean-label specialists from spot market swings, compressing cost-plus contract windows for commodity benzoate suppliers.
Pricing Analysis
Cost-plus contracts indexed to petrochemical derivative benchmarks dominate synthetic acid transactions, with price differentiation separating REACH-registered European supply from unregistered Asian spot material. Certification tier creates the widest spread: USP-NF pharmaceutical grades command substantial premiums over technical grades serving bakery applications. Pricing pressure stems from acetic acid feedstock volatility eroding margin predictability for synthetic producers. Beverage manufacturers with aseptic packaging partnerships show least price sensitivity; cost-sensitive bakery compounders in India and China absorb the highest share of input cost pass-through.
Supply Chain Analysis
Rotterdam-Antwerp chemical corridor chokepoints concentrate European preservative distribution, with supply anchored in Germany, the Netherlands, and China. Raw material flows draw from petrochemical naphtha streams, corn-derived dextrose fermentation feedstocks, and specialty botanical extracts. Tariff exposure on acetic acid intermediates creates structural risk for synthetic producers with cross-border supply chains. Distribution runs through integrated chemical distributors serving multinational food manufacturers, with direct procurement relationships displacing intermediaries in high-volume clean-label categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label biotechnology disruption accelerates as fermentation-derived actives cross cost parity with synthetic chemistries, with EFSA's sorbic acid re-evaluation compressing maximum permitted levels and forcing reformulation investment cycles.
For Market Incumbents: Compound technical service capabilities around clean-label reformulation protocols to defend against fermentation-derived specialists capturing multinational food manufacturer procurement. Deepen backward integration into acetic acid feedstocks to buffer margin volatility from petrochemical derivative swings. Prioritize REACH dossier maintenance and US FDA 21 CFR listing renewals as regulatory compliance becomes the primary supplier filtration mechanism. For New Entrants and Emerging Players: Technical service intensity gaps in mid-sized European supplement manufacturers lacking in-house stability testing infrastructure create white-space entry points. Target India's FSSAI approval pathway delays by establishing early-stage dossier relationships with domestic food processors seeking export compliance. Deploy fermentation-derived bacteriocin platforms through biopreservation partnerships with European meat processors pursuing label-friendly positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-premium consolidation play because REACH registration burdens and dual FDA-EPA compliance tracks filter out commodity competitors, concentrating viable supply bases. Acquisition focus should center on fermentation-derived specialists with established EFSA novel food evaluations and existing multinational technical service relationships. Monitor FSSAI additive approval timeline compression as the signal indicating India's market entry barriers are easing for clean-label alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid Feedstocks | Captive supply of petrochemical derivatives insulates synthetic acid producers from naphtha pricing volatility. |
| EFSA Novel Food Dossier Investment | Early-stage regulatory positioning captures clean-label formulation slots as sorbic acid maximum levels tighten. |
| Aseptic Packaging Equipment Partnerships | Technical convergence with packaging specialists opens premium beverage preservation categories for natural acidulants. |
| FSSAI Pre-Submission Consultations | Early regulatory engagement compresses India's 18-24 month additive approval timelines for fermentation-derived actives. |
| USP-NF cGMP Facility Certification | Pharmaceutical-grade compliance creates concentrated margin pools filtering out commodity preservative suppliers. |
Research Approach
A standing panel of plant managers at integrated acid production facilities, procurement leads at multinational food manufacturers, distribution channel partners serving European clean-label reformulation programs, and technical R&D directors at fermentation-derived specialists provided ongoing calibration. Primary interview insights combined with customs and trade data, Cefic sector reports, SEC 10-K filings from listed chemical conglomerates, and FDA 21 CFR additive listings. Bottom-up volume modeling across product type, application, and form segments triangulated against top-down value estimates.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon. The analytical framework modeled segmentation across synthetic versus natural chemistry classes, food versus pharmaceutical versus personal care applications, liquid versus powder versus granule formats, and regional regulatory cluster intensity. CAGRs derived from regression analysis of historical volume trajectories adjusted for EFSA regulatory re-evaluation impacts and India food processing capacity expansion curves. Industry-specific inputs included REACH registration status distributions and aseptic packaging adoption rates in premium beverage categories.
Underlying assumptions cover sustained clean-label formulation momentum, stable petrochemical feedstock availability, and gradual FSSAI process streamlining, with deviation risk concentrated in EFSA maximum permitted level adjustments and acetic acid pricing volatility. Practitioners should keep alternative scenarios live as biotechnology cost parity timelines and regional regulatory harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Disinfecting Wipes Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Nisin Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Fumigant Products Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Surface Disinfectants Market