
 Phenoxyethanol Preservatives Market | 2026-2036
Phenoxyethanol Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Phenoxyethanol Preservatives Market Analysis
Capital-intensity divergence between integrated glycol ether producers and specialty chemical blenders is bifurcating competitive returns in phenoxyethanol supply. BASF SE leverages backward integration into ethylene oxide feedstock to sustain margin stability across European personal care supply chains. Lonza Group Ltd. anchors its position through pharmaceutical-grade certification protocols that dominate contract manufacturing demand. Galaxy Surfactants Limited competes on formulation flexibility, extending its reach into emerging Asian cosmetic brands seeking customized preservative systems.
Phenoxyethanol is a glycol ether preservative (C8H10O2) synthesized through ethoxylation of phenol, functioning primarily as a broad-spectrum antimicrobial agent effective against Gram-negative bacteria in aqueous cosmetic and pharmaceutical formulations. Its industrial purpose centers on preventing microbial contamination in water-based products where paraben alternatives face consumer resistance. The personal care application segment leads volume consumption, with emulsion formulations capturing the deepest margin pools due to technical complexity in stabilizing oil-water interfaces. Powder formulation types represent the fastest-growing structural category, driven by dry shampoo and anhydrous cosmetic trends that require specialized phenoxyethanol delivery systems.
The European Chemicals Agency enforces REACH registration mandates that elevate purity thresholds for phenoxyethanol imports, while the FDA maintains preservative concentration limits in cosmetic formulations through its Code of Federal Regulations. China's National Medical Products Administration implements GB standards for cosmetic preservatives that condition market access for domestic and imported phenoxyethanol grades. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global specification strategies offer superior compliance economics.

Market Dynamics
REACH compliance costs are compressing margin structures for non-integrated phenoxyethanol suppliers while pharmaceutical-grade certification requirements concentrate procurement power among certified contract manufacturers serving European personal care formulators.
Growth Catalysts
- Water-based cosmetic formulation expansion:Personal care brands are replacing oil-phase preservatives in emulsion products, creating technical demand for phenoxyethanol's aqueous solubility profile.
- GB standards harmonization in China:NMPA alignment with international purity thresholds is accelerating domestic pharmaceutical-grade capacity expansion for export-qualified production.
- Ethoxylation process efficiency gains:Continuous reactor technology is reducing phenol conversion waste rates, lowering unit economics for mid-scale glycol ether producers.
Market Restraints
- Ethylene oxide feedstock volatility:Petrochemical price swings transmit directly to phenoxyethanol production costs, compressing blender margins during upstream spikes.
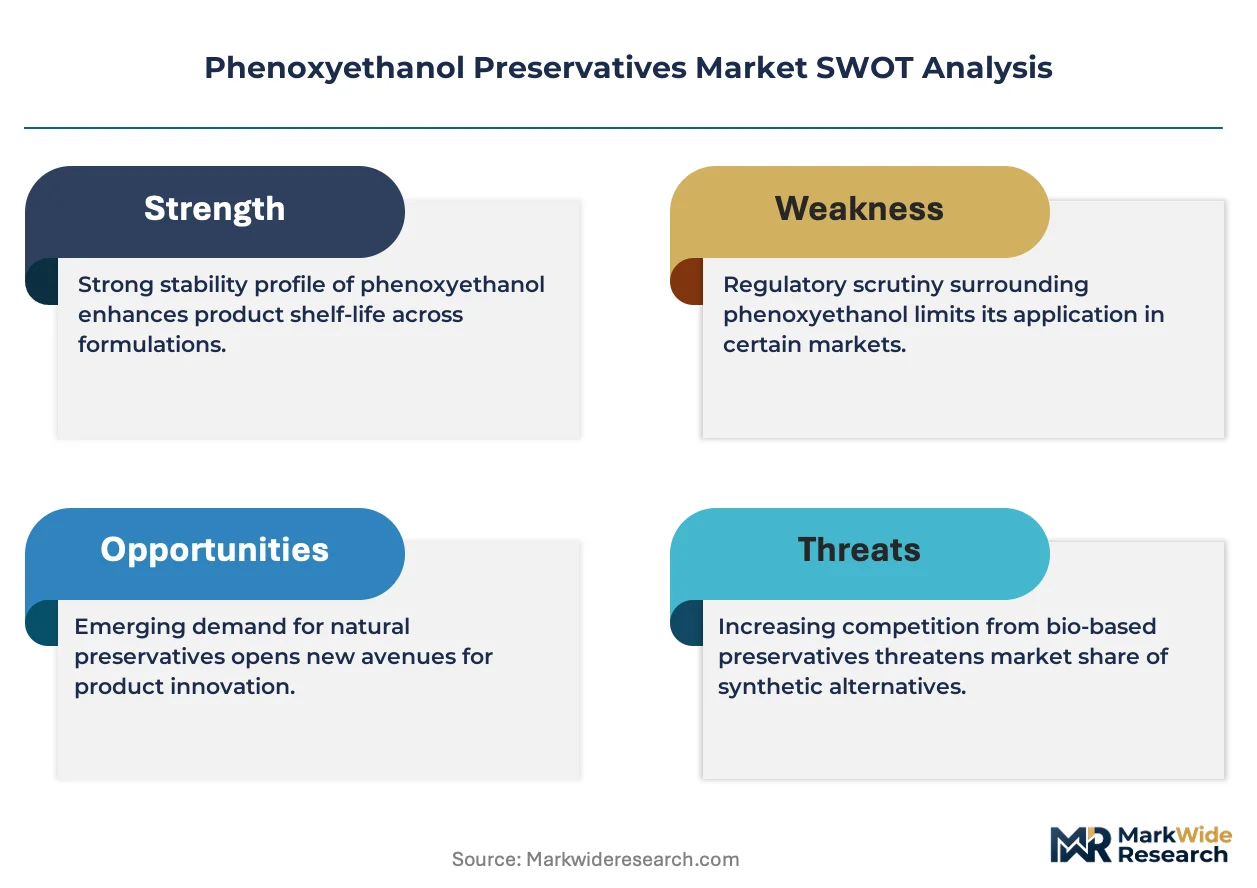
- Paraben revival in select segments:Regulatory clarity on methylparaben safety in the EU is slowing phenoxyethanol substitution momentum in mass-market skincare.
- Import purity barriers:ECHA registration thresholds exclude non-certified Asian producers from European pharmaceutical and premium cosmetic supply chains.
Strategic Opportunities
- Dry shampoo powder formulations:Anhydrous cosmetic trends in North America and Europe are creating demand for encapsulated phenoxyethanol delivery systems with specialized release profiles.
- Pharmaceutical-grade certification arbitrage:Contract manufacturers in India and China are investing in USP-grade compliance to capture European outsourcing demand from cost-constrained branded formulators.
- Green chemistry procurement mandates:EU Green Deal supplier criteria are rewarding phenoxyethanol producers with verified bio-based feedstock sourcing and carbon disclosure protocols.
Industry Challenges
- Ethoxylation reactor engineering talent scarcity:Specialized process safety expertise for high-pressure phenol handling is concentrating at integrated petrochemical groups, limiting independent producer scale-up.
- Multi-jurisdiction certification timelines:Simultaneous REACH, FDA, and NMPA registration processes extend product launch cycles for new phenoxyethanol grades by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenoxyethanol Preservatives Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Creams, Shampoos, Soaps Application: Personal Care, Cosmetics, Pharmaceuticals, Household Formulation Type: Emulsions, Gels, Powders, Aerosols End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | DowDuPont Inc., Lonza Group Ltd., BASF SE, Galaxy Surfactants Limited, Evonik Industries, Clariant AG, Ashland Global Holdings Inc., Liaoning Kelong Fine Chemical Co., Ltd., Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenoxyethanol Preservatives Market Emerging Trajectories
Encapsulation technologies are fragmenting traditional preservative procurement models as formulators seek targeted antimicrobial release rather than bulk chemical commodity purchasing.
Microencapsulated phenoxyethanol systems are decomposing the conventional bulk preservative supply relationship. Premium cosmetic brands in France and Germany are adopting time-release capsule formulations for anhydrous powder products. This technology is decomposing spot-market pricing power for standard-grade phenoxyethanol suppliers as formulation value migrates to delivery system integrators.
REACH authorization list expansion is tightening glycol ether preservative traceability requirements across European supply chains. Importers must now document full phenol sourcing pedigree and ethoxylation batch records for ECHA inspection. Contract manufacturers serving German and Swiss pharmaceutical customers are consolidating supplier bases to reduce compliance audit burden.
Direct procurement from certified phenoxyethanol producers is displacing distributor intermediaries among mid-sized Asian cosmetic brands. South Korean and Chinese skincare companies are establishing quality agreements with single-source suppliers to secure pharmaceutical-grade consistency. This channel compression is most visible in Shanghai and Seoul, where domestic brands are scaling premium product lines requiring documented preservative purity.
Phenoxyethanol Preservatives Market Segmentation
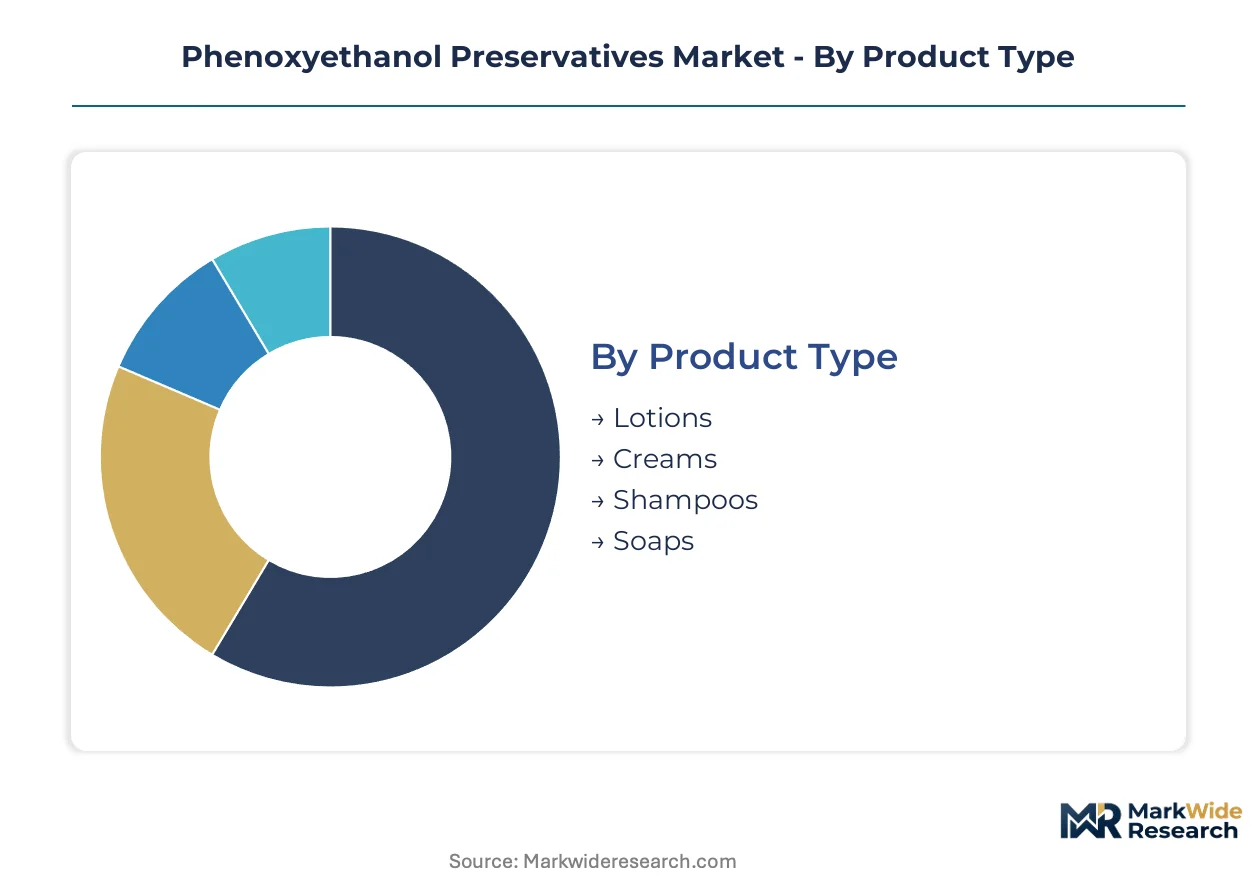
Phenoxyethanol procurement patterns diverge sharply across formulation architectures, with pharmaceutical-grade specifications commanding premium channel positioning while mass-market personal care drives volume throughput. Segmentation discipline reveals where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Channel economics favor liquid formats for contract manufacturing scale, while solid formats create specialized distribution requirements for temperature-stable logistics.
- Lotions:Water-based oil-in-water emulsions with phenoxyethanol solubility optimized for 0.5-1.0% concentration ranges. Demand concentrates in North American and European premium skincare brands replacing paraben systems, though methylparaben regulatory clarity in the EU has slowed substitution momentum in mass-market tiers.
- Creams:Thicker oil-phase formulations requiring phenoxyethanol stabilization at oil-water interfaces. German and Swiss pharmaceutical contract manufacturers capture the deepest margin pools here due to REACH-mandated purity documentation and batch traceability requirements that exclude non-certified Asian suppliers.
- Shampoos:High-throughput rinse-off applications where phenoxyethanol cost efficiency competes with isothiazolinone alternatives. Chinese domestic brands scaling premium haircare lines are the fastest-expanding demand segment for standard-grade material.
- Soaps:Alkaline pH environments limit phenoxyethanol efficacy, restricting use to syndet bars and liquid hand washes. South Korean formulation houses specialize in pH-adjusted preservative systems for this niche.
By volume, shampoos lead. By growth pace, creams are ahead.
Application:
Regulatory jurisdiction determines accessible segments, with pharmaceutical-grade certification creating the steepest barriers to entry.
- Personal Care:Emulsion-based skincare and haircare products where phenoxyethanol serves as the primary Gram-negative bactericide. Water-based formulation expansion across French and German premium brands is the dominant demand driver, with ECHA REACH registration excluding uncertified imports from pharmaceutical-adjacent supply chains.
- Cosmetics:Color cosmetics and decorative products requiring anhydrous or powder-phase preservative delivery. Dry shampoo trends in North America and Europe are accelerating encapsulated phenoxyethanol system adoption, fragmenting traditional bulk procurement relationships.
- Pharmaceuticals:Topical drug formulations subject to USP-grade purity mandates and FDA concentration limits under Code of Federal Regulations. Indian and Chinese contract manufacturers are investing in certification arbitrage to capture European outsourcing demand.
- Household:Surface cleaners and laundry applications where phenoxyethanol competes on cost with quaternary ammonium compounds. This segment concentrates in emerging Asian markets with less stringent purity requirements.
Personal care commands the largest volume position. Pharmaceuticals show the steepest expansion trajectory.
Formulation Type:
Technical complexity in stabilization mechanics determines supplier qualification tiers and pricing power distribution.
- Emulsions:Oil-water interface stabilization represents the most technically demanding phenoxyethanol application, with HLB balance requirements and co-preservative synergies. European personal care formulators pay premium pricing for documented batch consistency from REACH-registered producers.
- Gels:Hydroalcoholic and aqueous gel matrices where phenoxyethanol solubility in polar solvents enables broad-spectrum preservation. South Korean skincare brands are scaling hydrogel serum production for domestic and export markets.
- Powders:Anhydrous formulations requiring microencapsulated or surface-treated phenoxyethanol for controlled release. French and German premium cosmetic houses are adopting time-release capsule systems for dry shampoo and powder foundation applications.
- Aerosols:Pressurized delivery systems with propellant compatibility constraints limiting phenoxyethanol to specific solvent packages. This niche concentrates in North American sun care and body spray formulations.
Emulsions dominate current volume. Powders are climbing the fastest.
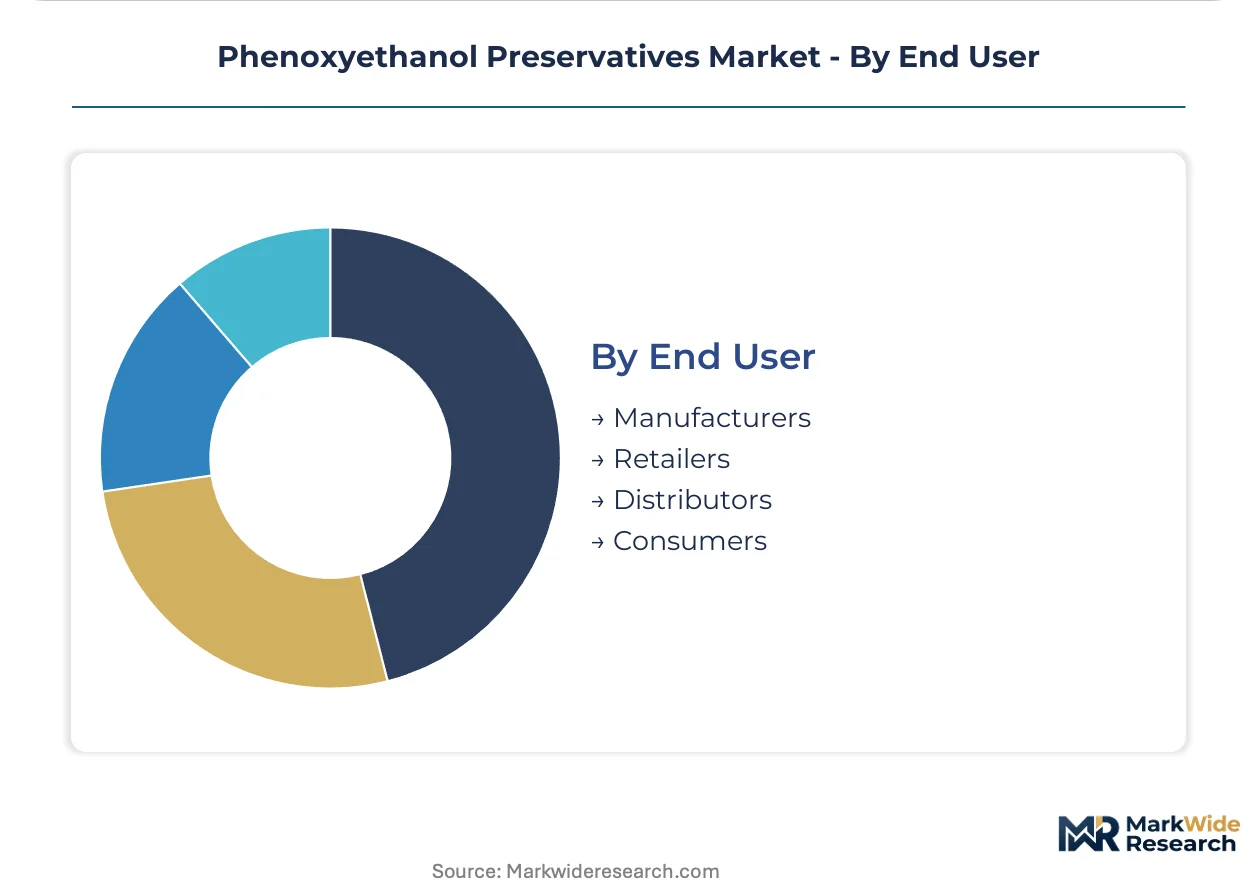
End User:
Procurement authority is shifting upstream as brands consolidate supplier bases to reduce compliance audit burden.
- Manufacturers:Brand owners and contract formulators with direct phenoxyethanol purchasing power. Mid-sized Asian cosmetic brands in Shanghai and Seoul are establishing single-source quality agreements to secure pharmaceutical-grade consistency for premium product lines.
- Retailers:Private-label skincare and personal care chains with formulation specification authority. European pharmacy retailers are tightening preservative disclosure requirements under EU Green Deal supplier criteria.
- Distributors:Chemical traders and regional wholesalers serving smaller formulators without direct producer relationships. Channel compression is most visible in China, where domestic brands are bypassing intermediaries for certified supply.
- Consumers:Direct purchasing of DIY cosmetic ingredients represents a marginal segment concentrated in North American and European hobbyist markets.
Manufacturers account for the largest volume share. Retailers are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass-market formulators in emerging Asian economies exhibit acute price sensitivity, while European pharmaceutical-grade buyers absorb premium costs for documented purity pedigree and REACH batch traceability.
China
Domestic cosmetic brands scaling premium skincare lines in Shanghai and Guangzhou are driving pharmaceutical-grade phenoxyethanol demand. NMPA GB standards alignment with international purity thresholds is accelerating export-qualified capacity expansion. The Yangtze River Delta cluster hosts concentrated glycol ether production serving both domestic formulators and contract manufacturers.
Germany
Swiss and German pharmaceutical contract manufacturers command the deepest margin pools through REACH-mandated documentation requirements. ECHA registration thresholds exclude non-certified Asian producers from pharmaceutical-adjacent supply chains. The Rhine-Ruhr industrial corridor anchors ethoxylation capacity with backward integration into ethylene oxide feedstock.
United States
Premium cosmetic brands in California and New York Metro are adopting encapsulated phenoxyethanol systems for dry shampoo and anhydrous powder formulations. FDA concentration limits under Code of Federal Regulations maintain preservative safety frameworks. The Gulf Coast petrochemical corridor supplies integrated phenoxyethanol producers with captive ethylene oxide.
South Korea
Hydrogel serum production for domestic and export markets is scaling phenoxyethanol demand in Seoul and Busan. MFDS cosmetic preservative regulations condition market access for imported and domestic grades. The Seoul Capital Area concentrates formulation R&D for K-beauty brands seeking customized preservative systems.
India
Contract manufacturers in Maharashtra and Gujarat are investing in USP-grade certification to capture European outsourcing demand. CDSCO alignment with international pharmaceutical-grade standards is accelerating compliance investments. The Mumbai-Pune industrial belt hosts emerging glycol ether capacity targeting export-qualified production.
Phenoxyethanol Preservatives Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into ethylene oxide feedstock separating margin-stable producers from cost-pressured blenders. The market structure concentrates procurement power among REACH-registered suppliers serving European pharmaceutical formulators. Three archetypes dominate: integrated petrochemical groups with captive feedstock, pharmaceutical-grade certification specialists, and formulation-flexible regional blenders. Competitive moves center on capacity expansion in Asia-Pacific and strategic partnerships for encapsulated delivery system technology.
Among integrated European producers, BASF SE exemplifies the backward-integrated archetype with ethylene oxide feedstock control. Lonza Group Ltd. anchors the pharmaceutical-grade certification tier through documented purity protocols. Galaxy Surfactants Limited occupies the formulation-flexible specialist position serving emerging Asian cosmetic brands. These three companies represent the structural segmentation between feedstock-integrated, certification-dominant, and customization-focused competitive positions.
| Leading Market Players |
|---|
| DowDuPont Inc. |
| Lonza Group Ltd. |
| BASF SE |
| Galaxy Surfactants Limited |
| Evonik Industries |
| Clariant AG |
| Ashland Global Holdings Inc. |
| Liaoning Kelong Fine Chemical Co., Ltd. |
| Symrise AG |
| Others |
Supply Flow & Price Mechanics
Paraben substitution in European mass-market skincare is simultaneously redrawing supply geography toward REACH-certified producers and compressing pricing power for uncertified Asian blenders. This input shift forces formulators to absorb pharmaceutical-grade premiums or risk ECHA import exclusion.
Pricing Analysis
After-sales technical service contracts with formulators drive lifetime value for phenoxyethanol suppliers more than spot chemical sales. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels separates certified contract manufacturers from commodity blenders. Pricing pressure stems from ethylene oxide feedstock volatility transmitting directly to blender margins during petrochemical spikes. Mass-market personal care brands in emerging Asia exhibit acute price sensitivity, while German and Swiss pharmaceutical formulators absorb premiums for documented batch traceability.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade phenoxyethanol extend significantly due to multi-jurisdiction certification documentation requirements. Supply concentrates in Germany, China, and India, with the Rhine-Ruhr corridor anchoring integrated ethoxylation capacity. Production draws from phenol and ethylene oxide feedstocks, with ethoxylation reactor engineering talent scarcity limiting independent scale-up. Single-source vulnerability concentrates in high-pressure phenol handling expertise at integrated petrochemical groups. Distribution runs through direct quality agreements between certified producers and mid-sized Asian cosmetic brands, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phenoxyethanol demand follows cosmetic formulation cycles, with water-based emulsion expansion driving recovery momentum after paraben substitution pauses. Ethylene oxide price volatility serves as the primary cyclical amplifier.
For Market Incumbents: Shield margin stability through backward integration into ethylene oxide feedstock and pharmaceutical-grade certification investments. Paraben regulatory clarity in the EU threatens substitution-driven volume growth. Captive feedstock supply and REACH-registered capacity in the Rhine-Ruhr corridor defend positioning against cost-pressured Asian blenders.
For New Entrants and Emerging Players: USP-grade certification fast-track investments unlock European pharmaceutical outsourcing demand from cost-constrained branded formulators. White-space targets include Indian contract manufacturers seeking export-qualified production and encapsulated delivery systems for dry shampoo applications. A go-to-market angle centered on formulation flexibility for emerging Asian cosmetic brands bypasses integrated producer scale disadvantages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical blenders lacking pharmaceutical-grade certification infrastructure. Long-term viability hinges on regulatory moat durability across REACH, FDA, and NMPA jurisdictions. Acquisition targets include mid-scale glycol ether producers with ethoxylation process efficiency gains. The signal to watch is ECHA authorization list expansion tightening traceability requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | REACH and USP compliance unlocks European pharmaceutical contract manufacturing demand. |
| Encapsulated Delivery System Development | Time-release phenoxyethanol capsules capture value from dry shampoo formulation trends. |
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates margin stability from petrochemical price volatility. |
| Direct Quality Agreements with Asian Brands | Channel compression in Shanghai and Seoul secures pharmaceutical-grade volume commitments. |
| Continuous Reactor Technology Deployment | Ethoxylation process efficiency gains reduce phenol conversion waste rates for mid-scale producers. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at glycol ether facilities, procurement leads at European personal care formulators, distribution channel partners, and technical R&D directors specializing in preservative systems, then refined through secondary validation. Sources included customs and trade data, chemical industry association reports, SEC filings from listed producers, ECHA registration databases, and NMPA GB standards documentation. Bottom-up capacity and demand modeling triangulated with top-down market sizing across producer segments.
Variance decomposition separated volume drivers from price effects across the projection horizon. Segmentation dimensions modeled include grade tier, end-use application, formulation type, and regional production hub. CAGRs were derived from segment-level growth rate aggregation weighted by base-year contribution. Forecast inputs incorporated ethoxylation capacity expansion timelines and regulatory compliance investment cycles.
The analysis sits within stated boundaries; outcomes outside sustained ethylene oxide supply stability or accelerated REACH authorization expansion would require recalibration. Forecasts reflect documented assumptions about certification timeline standardization and feedstock price regime continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Antibacterial Products Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Sulfuryl Fluoride Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Latin America Cosmetic Preservatives Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Disinfectant Chemicals Market