
 Asia Food Emulsifiers Market | 2026-2036
Asia Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Food Emulsifiers Market Analysis
Modular emulsifier blending is pivoting how Asian food manufacturers configure ingredient procurement, shifting from single-ingredient orders to bundled functional systems. Cargill Incorporated leverages its integrated oilseed processing footprint to supply lecithin variants tailored to regional bakery applications. Kerry Group anchors its position through flavor-emulsifier co-development platforms that reduce client formulation cycles. BASF SE competes on synthetic ester purity grades suited to high-stability confectionery demands.
Asia food emulsifiers comprise surface-active agents with hydrophilic-lipophilic balance values typically between 3 and 16, manufactured through glycerolysis of triglycerides or ethoxylation of sorbitan esters to stabilize heterogeneous food matrices. Their primary purpose spans texture modification, shelf-life extension, and fat-water dispersion in processed foods. Lecithin dominates volume flows due to its plant-derived positioning and broad regulatory acceptance across Asian jurisdictions. Mono- and diglycerides capture margin pools in dairy applications where aeration stability commands premium pricing. Polysorbates sustain growth in sauce and dressing segments requiring cold-process emulsification.
China's SAMR enforces GB standards on food additive usage levels, while India's FSSAI mandates quantitative ingredient declarations that pressure reformulation toward label-friendly emulsifier systems. Japan's MHLW maintains positive-list governance for synthetic emulsifiers that constrains new molecular introductions. Stakeholders must monitor divergence between national positive-list frameworks and the harmonization pressures emanating from Codex Alimentarius guidelines to avoid stranded product registrations.
Market Dynamics
Modular emulsifier blending systems are restructuring procurement relationships across Asian food manufacturing, compressing supplier counts while expanding functional complexity per contract. This shift from commodity ingredient trading to integrated solution partnerships concentrates margin capture among technical service providers.
Growth Catalysts
- Clean-label mandates:India's FSSAI quantitative declaration requirements push reformulation toward lecithin and plant-derived mono-diglycerides that satisfy label transparency demands without sacrificing emulsion stability.
- Processed food corridor expansion:China's Shanghai-Guangzhou manufacturing belt generates concentrated demand for high-HLB emulsifiers supporting extended shelf-life bakery and dairy applications.
- Ethoxylation process improvements:Advanced sorbitan ester manufacturing yields polysorbate variants with tighter hydrophilic-lipophilic balance tolerances, enabling cold-process sauce production that reduces energy costs for Southeast Asian condiment makers.
Market Restraints
- Soy lecithin supply concentration:Crushing capacity limitations in Argentina and Brazil transmit price volatility directly to Asian confectionery and chocolate manufacturers dependent on phospholipid feedstocks.
- Positive-list governance constraints:Japan's MHLW additive approval framework blocks rapid introduction of novel synthetic emulsifiers, forcing suppliers to rely on decades-old molecular architectures.
- Palm oil sustainability certification costs:RSPO compliance requirements for glycerolysis-derived emulsifiers add 8-12% raw material premiums that compress margins in mass-market bakery segments.
Strategic Opportunities
- Vietnam's underpenetrated bakery sector:Western-style bread consumption growth in Ho Chi Minh City and Hanoi creates demand for dough conditioners and crumb softeners previously absent from traditional rice-dominant diets.
- Flavor-emulsifier co-development platforms:Integrated formulation services that combine taste modulation with texture stabilization reduce client R&D cycles and lock in multi-year supply agreements.
- PLI scheme alignment:India's production-linked incentive structures for food processing equipment indirectly support domestic emulsifier manufacturing scale-up through improved local blending infrastructure.
Industry Challenges
- Clean-label formulation complexity:Removing synthetic polysorbates from dressing and sauce applications while maintaining freeze-thaw stability demands extensive client co-development that strains technical service bandwidth.
- Dual carbon compliance:China's MEE enforcement of energy intensity targets forces emulsifier plants to retrofit glycerolysis reactors with heat recovery systems, requiring capital deployment amid margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Food Emulsifiers Market |
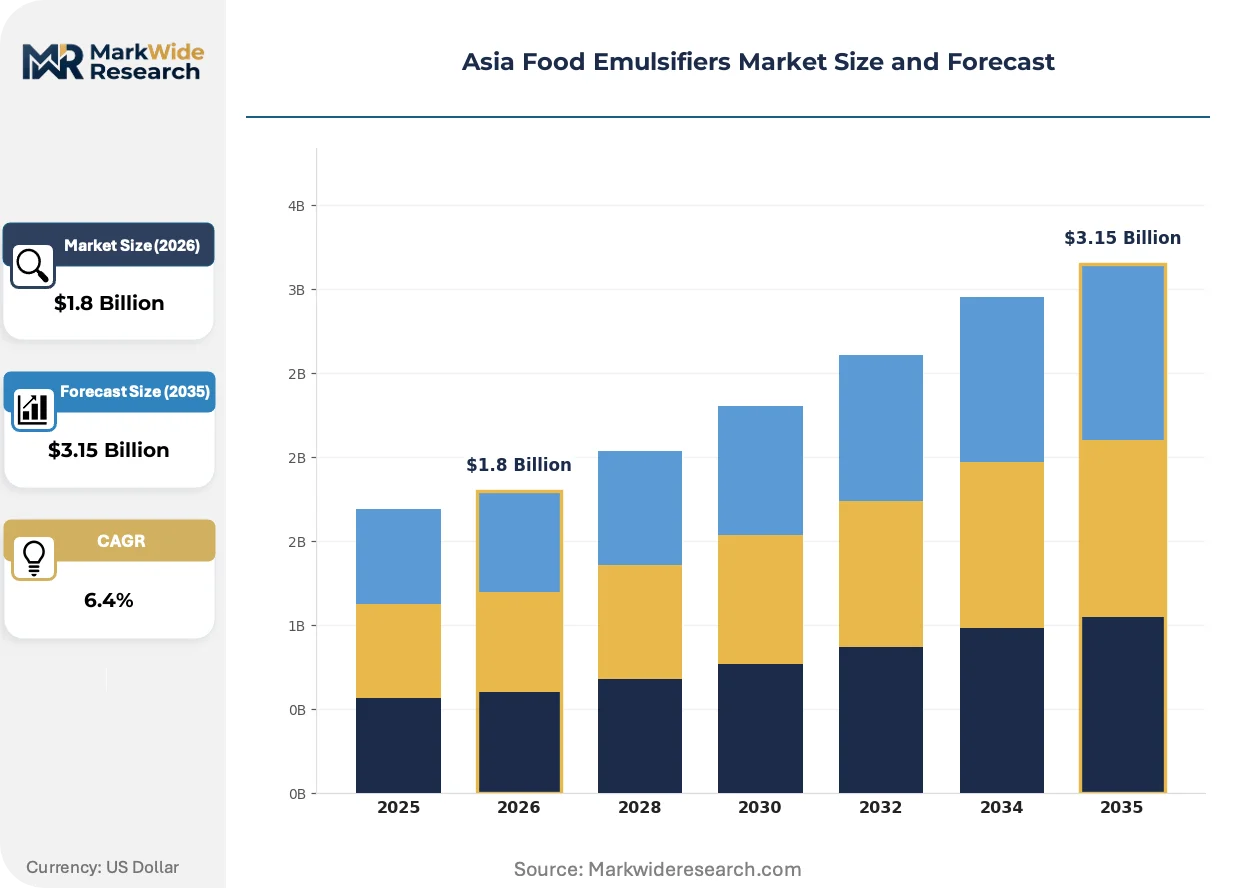
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Mono- and Diglycerides, Polysorbates, Glyceryl Esters Application: Bakery Products, Dairy Products, Sauces & Dressings, Confectionery End User: Food Manufacturers, Beverage Companies, Catering Services, Retail Outlets Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland, Ingredion Incorporated, DuPont de Nemours Inc., Kerry Group, Corbion N.V., Riken Vitamin, BASF SE, Lonza Group AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Food Emulsifiers Market Emerging Trajectories
Enzymatic interesterification is displacing chemical glycerolysis across Asian emulsifier manufacturing, yielding mono-diglyceride products with superior odor profiles and reduced processing residues. This biotechnology transition reconfigures capital allocation and technical hiring priorities throughout the supply base.
Enzymatic interesterification deploys lipase biocatalysts to rearrange triglyceride structures without the high temperatures and alkaline conditions of conventional processing. Southeast Asian palm oil refiners are retrofitting facilities to capture premium positioning for bakery clients demanding cleaner process credentials. The technology is overtaking chemical routes in new capacity investments, marginalizing legacy plants unable to justify conversion economics.
China's SAMR enforcement of updated GB 2760 additive standards is tightening maximum usage levels for synthetic emulsifiers in infant formula and specialized nutrition categories. Domestic manufacturers face reformulation timelines that compress product development windows while imported brands must reconcile dual compliance with Codex Alimentarius guidelines. Dairy and clinical nutrition segments bear the highest compliance burden, accelerating migration toward lecithin and citric acid ester alternatives.
Buyer consolidation among pan-Asian bakery chains is consolidating emulsifier procurement into centralized technical sourcing functions that demand application-specific performance guarantees rather than commodity specifications. Regional quick-service restaurant operators now specify finished-product texture outcomes, transferring formulation risk upstream to ingredient suppliers. Thailand and Indonesia display the most advanced procurement centralization, with multinational bakery groups leading contract restructuring.
Asia Food Emulsifiers Market Segmentation
Emulsifier selection in Asia hinges on regulatory acceptance thresholds that vary sharply across product categories. Manufacturers must map each segment against Japan's MHLW positive-list constraints, China's SAMR GB standards, and India's FSSAI declaration mandates before committing formulation resources.
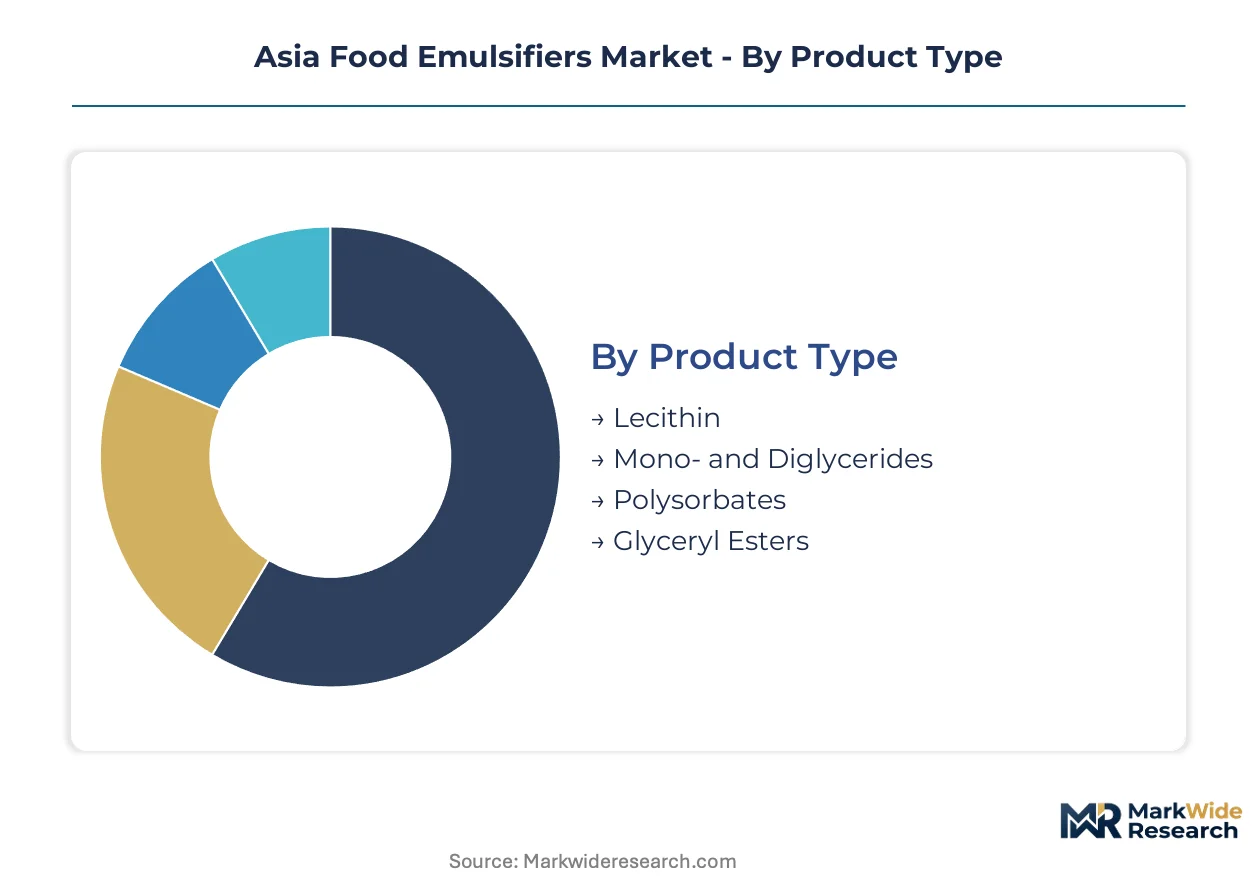
Product Type:
Certification burden falls heaviest on synthetic esters requiring novel food approvals, while plant-derived phospholipids navigate simpler pathways across Asian jurisdictions.
- Lecithin:Phospholipid mixtures extracted from soy or sunflower oil with HLB values between 3 and 8, prized for label-friendly positioning. Demand concentrates in China's chocolate and confectionery corridor from Shanghai to Suzhou, where clean-label mandates from SAMR accelerate substitution for synthetic alternatives. India's FSSAI quantitative declaration rules push bakery formulators toward lecithin to simplify ingredient panels.
- Mono- and Diglycerides:Partial glycerol esters of fatty acids manufactured through glycerolysis or enzymatic interesterification, delivering aeration stability in whipped dairy systems. Premium pricing prevails in Japan's condensed milk and whipped topping segments where MHLW-approved emulsifier lists restrict molecular innovation. Southeast Asian dairy processors specify these for UHT milk stability under tropical distribution conditions.
- Polysorbates:Ethoxylated sorbitan esters with HLB values above 15 enabling cold-process emulsification.
- Glyceryl Esters:Citric acid or lactic acid esters of mono-diglycerides providing antioxidant synergy.
Leading the category by volume: Lecithin. Growing fastest: Mono- and Diglycerides.
Application:
Cost tier stratification separates mass-market bakery from premium confectionery, with formulation complexity and raw material specifications driving procurement segmentation.
- Bakery Products:Dough conditioners, crumb softeners, and shelf-life extenders stabilizing fat-water interfaces in bread and pastry matrices. Vietnam's Ho Chi Minh City and Hanoi bakery clusters generate concentrated demand for emulsifier systems previously absent from rice-dominant diets. Western-style bread consumption growth outpaces traditional applications, pulling in lecithin and DATEM variants.
- Dairy Products:Aeration stabilizers and fat globule membrane modifiers in ice cream, whipped toppings, and processed cheese. Japan's specialized nutrition segment commands premium-grade emulsifiers with documented MHLW safety profiles, while China's infant formula manufacturers face compressed reformulation timelines under tightened GB 2760 usage limits.
- Sauces & Dressings:Cold-process emulsifiers maintaining stability through freeze-thaw cycles.
- Confectionery:Viscosity modifiers and bloom inhibitors in chocolate and compound coatings.
Dominant by volume: Bakery Products. Expanding most quickly: Dairy Products.
End User:
Customer type determines technical service intensity, with centralized procurement functions at multinational food manufacturers demanding application-specific performance guarantees.
- Food Manufacturers:Integrated processed food operations spanning bakery, dairy, and savory categories with consolidated ingredient sourcing functions. Thailand and Indonesia display the most advanced procurement centralization, where regional quick-service restaurant operators now specify finished-product texture outcomes rather than commodity emulsifier grades.
- Beverage Companies:Emulsion concentrate producers requiring high-HLB stabilizers for flavor oil suspension.
- Catering Services:Institutional and foodservice channels with standardized formulation requirements.
- Retail Outlets:Private-label and artisan producers with fragmented, specification-light procurement.
Volume concentration: Food Manufacturers. Fastest procurement evolution: Beverage Companies.
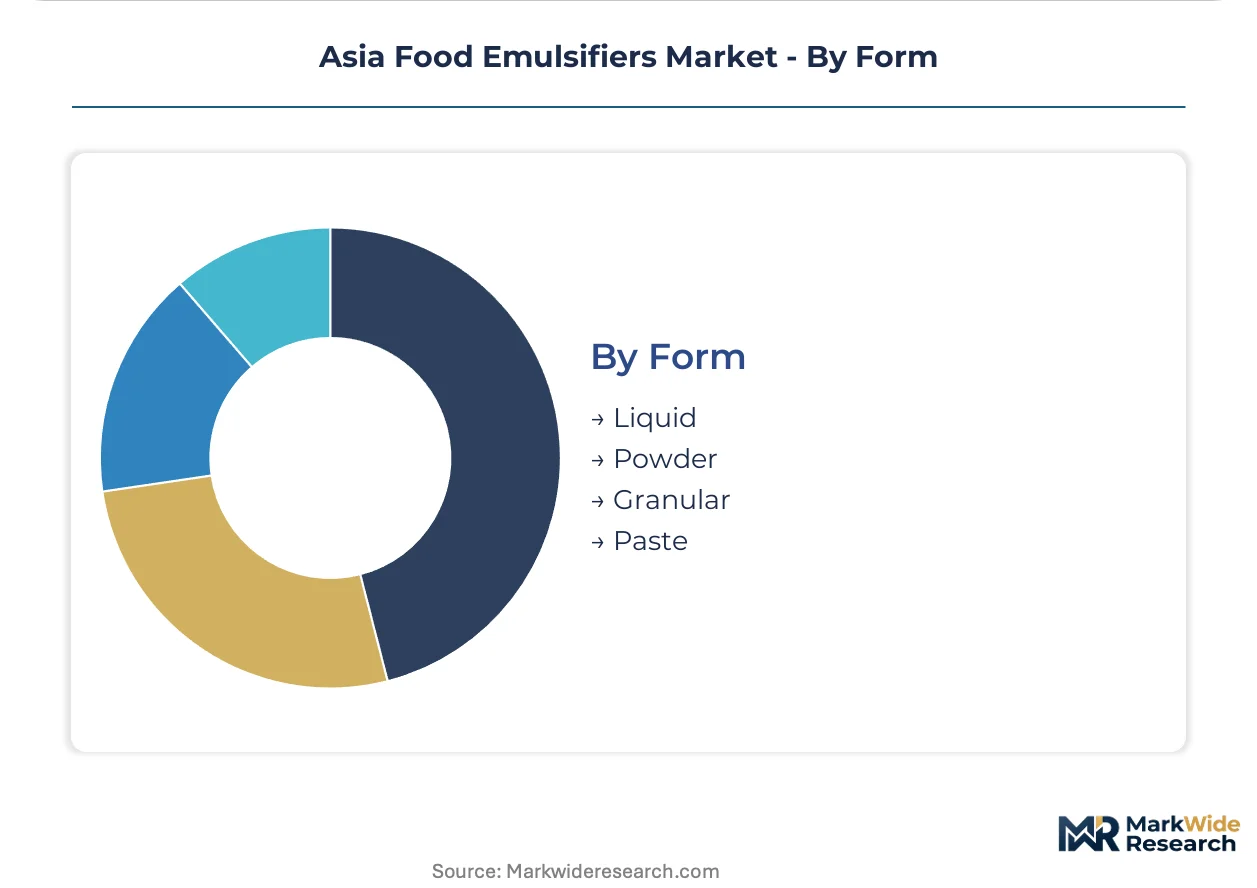
Form:
Supply concentration in liquid handling infrastructure favors fluid formats for high-volume bakery and dairy applications, while powder and granular forms capture specialized segments.
- Liquid:Pumpable emulsifier concentrates with standardized viscosities for automated dosing in continuous bakery lines. China's Shanghai-Guangzhou manufacturing belt prefers liquid lecithin for streamlined handling in high-throughput cracker and biscuit operations.
- Powder:Spray-dried or plated variants enabling dry-blend compatibility in instant mixes.
- Granular:Free-flowing formats for dusty environment compliance in Southeast Asian blending facilities.
- Paste:High-viscosity concentrates for artisan and small-batch confectionery applications.
Volume leader: Liquid. Steepest expansion trajectory: Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of emulsifier volumes across Asia while specialized production clusters concentrate in Japan and India. Domestic formulation capabilities lag import dependency in Vietnam and Indonesia. Regulatory fragmentation between national positive-list systems complicates cross-border product registration.
China
Shanghai-Guangzhou manufacturing belt drives concentrated demand for high-HLB emulsifiers in extended shelf-life bakery applications. SAMR enforces GB 2760 standards that tightened maximum usage levels for synthetic emulsifiers in infant formula during 2024. Suzhou chocolate processors accelerate lecithin substitution to satisfy clean-label procurement mandates from domestic confectionery brands.
Japan
Condensed milk and whipped topping segments command premium-grade emulsifiers with documented MHLW safety profiles. MHLW positive-list governance blocks rapid introduction of novel synthetic emulsifiers, forcing reliance on decades-old molecular architectures. Kansai dairy processors specify mono-diglyceride variants for UHT stability under tropical distribution conditions reaching Southeast Asian export markets.
India
FSSAI quantitative declaration requirements push bakery formulators toward lecithin and plant-derived mono-diglycerides. PLI scheme structures for food processing equipment indirectly support domestic emulsifier manufacturing scale-up through improved local blending infrastructure. Maharashtra and Gujarat food corridors attract multinational emulsifier suppliers establishing technical service laboratories for regional formulation support.
Vietnam
Western-style bread consumption growth in Ho Chi Minh City and Hanoi creates demand for dough conditioners and crumb softeners absent from traditional rice-dominant diets. National food safety authorities align additive approval frameworks with ASEAN harmonization guidelines. Da Nang and Hai Phong industrial zones host emerging bakery ingredient distribution hubs serving central and northern provinces.
Indonesia
Regional quick-service restaurant operators specify finished-product texture outcomes, transferring formulation risk upstream to ingredient suppliers. BPOM regulatory oversight maintains distinct positive-list requirements separate from ASEAN mutual recognition arrangements. Surabaya and Bandung manufacturing clusters concentrate procurement centralization among pan-Asian bakery chains operating across Java.
Asia Food Emulsifiers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across Asia's emulsifier supply base. The market structure tilts toward technical service intensity rather than commodity volume capture. Three archetypes dominate: integrated oilseed processors leveraging crushing assets, flavor-emulsifier co-development platforms, and synthetic ester purity specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek to lock in multi-year supply agreements with consolidating food manufacturers.
Among diversified agricultural processors, Cargill Incorporated and Archer Daniels Midland occupy positions anchored by integrated oilseed processing footprints. Kerry Group exemplifies the flavor-emulsifier co-development platform archetype, while BASF SE represents synthetic ester purity positioning. These three companies span the strategic spectrum from upstream raw material control through integrated formulation services to high-specification chemical manufacturing.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland |
| Ingredion Incorporated |
| DuPont de Nemours Inc. |
| Kerry Group |
| Corbion N.V. |
| Riken Vitamin |
| BASF SE |
| Lonza Group AG |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between RSPO-compliant and conventional glycerolysis-derived emulsifiers manifests in parallel supply chain configurations, with sustainability premiums compressing margins for mass-market bakery suppliers while concentrating procurement power among technical service providers capable of traceability documentation. This bifurcation forces manufacturers to choose between margin sacrifice and customer loss across Southeast Asian export corridors.
Pricing Analysis
Cost-down pressure on standard-grade lecithin accelerates because Argentine and Brazilian crushing capacity constraints transmit feedstock volatility directly to Asian confectionery buyers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates premium positioning in Japan's specialized nutrition segment from commodity spot trading in China's mass-market bakery belt. Price differentiation hinges on HLB specification tolerance and organic certification status. Volume-scale buyers in Thailand's centralized procurement functions command steepest discounts, while artisan confectioners in Vietnam display lowest price elasticity due to small-batch flexibility requirements.
Supply Chain Analysis
Reverse-logistics flows for enzymatic interesterification biocatalysts remain underdeveloped across Southeast Asian palm oil refiners, limiting catalyst reuse economics and inflating per-batch processing costs. Supply concentrates in Malaysia, Indonesia, and Thailand for glycerolysis-derived emulsifiers, while phospholipid feedstocks draw from Argentine soy crushing and Ukrainian sunflower oil processing. Raw material dependencies span crude palm oil, phosphatidylcholine-rich lecithin fractions, and lipase enzyme preparations. Single-source vulnerability in South American soy lecithin exposes chocolate manufacturers to price spikes. Distribution runs through regional blending hubs in Shanghai, Singapore, and Mumbai before final formulation at food manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where Japan's MHLW positive-list governance erects decade-long approval timelines that protect incumbents with existing molecular registrations while stranding novel synthetic entrants.
For Market Incumbents: Acquire enzymatic interesterification technology platforms to displace legacy chemical glycerolysis assets before biotechnology transition accelerates. Secure backward integration into RSPO-certified palm oil supply through long-term offtake agreements with Malaysian and Indonesian refiners. Cargill Incorporated and Kerry Group already leverage crushing footprints and co-development platforms respectively; smaller players must match these capabilities or exit premium segments. For New Entrants and Emerging Players: India's FSSAI quantitative declaration requirements open a window for clean-label lecithin specialists to capture bakery reformulation demand as domestic manufacturers scramble for label-friendly alternatives. Target Vietnam's Ho Chi Minh City and Hanoi bakery clusters where Western-style bread consumption growth outpaces local emulsifier supply infrastructure. Lead with technical service laboratories offering application-specific performance guarantees rather than commodity specifications. For Investors and Strategic Acquirers: Re-rating potential sits with flavor-emulsifier co-development platforms given buyer consolidation among pan-Asian quick-service restaurant operators transferring formulation risk upstream. Long-term viability favors suppliers locking multi-year supply agreements with centralized procurement functions in Thailand and Indonesia. Monitor enzymatic interesterification capacity buildout announcements as inflection signal for biotechnology transition pace.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Capacity Buildout | Captures premium positioning for bakery clients demanding cleaner process credentials in Southeast Asia. |
| RSPO Certification Program | Defends market access in EU-exporting confectionery segments amid tightening sustainability mandates. |
| Flavor-Emulsifier Co-Development Platform | Reduces client R&D cycles and locks multi-year agreements with consolidating food manufacturers. |
| Technical Service Laboratory Expansion | Supports regional formulation demands in Maharashtra and Gujarat food corridors under India's PLI scheme. |
| Long-Term Phospholipid Supply Agreement | Hedges Argentine soy lecithin volatility for chocolate manufacturers across China's Shanghai-Suzhou corridor. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with emulsifier plant managers, procurement leads at pan-Asian bakery chains, FSSAI regulatory consultants, and technical R&D directors at flavor houses. Bottom-up volume estimates derived from glycerolysis reactor capacity utilization and enzymatic interesterification retrofit announcements were cross-checked against top-down demand models built on processed food production indices. FSSAI additive approval databases, SAMR GB 2760 enforcement notices, ASEAN harmonization guideline drafts, and RSPO certification registries provided regulatory boundary conditions.
Data-stream reconciliation across supply-side capacity announcements and demand-side procurement contract disclosures shaped the analytical framework. Segmentation dimensions modeled include product type tier, application category, end-user procurement centralization level, and regional regulatory cluster. CAGRs were computed from fitted growth curves rather than extrapolated single-year momentum. Industry-specific forecast inputs incorporated ethoxylation process yield improvements and palm oil sustainability premium trajectories.
The model assumes a particular technology adoption path; alternative pathways for enzymatic interesterification diffusion would alter the outlook if chemical glycerolysis retrofit economics prove more favorable than projected. Forecasts reflect stated regulatory enforcement intensities and commodity feedstock availability assumptions. Practitioners should monitor MHLW positive-list amendment petitions and SAMR GB standard revision drafts for early signals of molecular architecture constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market