
 North America Everything As a Service (Xaas) Market | 2026-2036
North America Everything As a Service (Xaas) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Everything As a Service (Xaas) Market Insights
Arm-based silicon is displacing x86 dominance in hyperscale data centers and is realigning total cost of ownership for cloud infrastructure providers across North America. Amazon Web Services sustains the broadest IaaS footprint through custom Graviton processor development. Microsoft anchors enterprise hybrid demand via Azure Stack integration with on-premises Windows Server estates.
Everything As a Service denotes a consumption-based IT delivery model where computing resources, software applications, and development platforms are provisioned remotely via network connections with metered billing cycles rather than perpetual licensing. The architecture relies on virtualization layers, API orchestration, and multi-tenant infrastructure to pool hardware across clients while maintaining logical isolation through software-defined networking. Software as a Service commands the largest revenue pool due to low switching costs and recurring subscription economics, while Function as a Service represents the fastest-expanding segment as event-driven serverless architectures reduce idle capacity overhead for intermittent workloads. Hybrid Cloud deployment captures the most complex integration spend as enterprises straddle legacy on-premises systems with elastic public capacity.
FedRAMP authorization requirements from the US General Services Administration constrain which providers may contract with federal agencies, filtering the vendor landscape toward capital-intensive compliance investments. State-level data residency statutes in California and New York add secondary compliance layers that fragment cloud architecture decisions for multi-state operators. Stakeholders must weigh sovereignty-aligned infrastructure investments against the latency penalties of geographically dispersed workload placement.
Market Dynamics
FedRAMP authorization requirements from the US General Services Administration are filtering vendor eligibility for federal contracts, forcing capital-intensive compliance investments that reshape competitive positioning across the North American XaaS landscape.
Growth Catalysts
- Healthcare SaaS Expansion:Electronic health records management drives recurring subscription demand among US hospital systems seeking interoperability mandates under HIPAA.
- State Data Residency Statutes:California and New York impose secondary compliance layers that fragment cloud architecture decisions for multi-state operators.
- Arm-based Silicon Migration:Custom processor development by hyperscale providers reduces total cost of ownership for cloud infrastructure provisioning.
Market Restraints
- FedRAMP Compliance Capital Intensity:Authorization timelines and audit costs create barriers for mid-tier providers seeking federal agency contracts.
- Cross-Border Data Transfer Friction:Canadian provincial privacy laws and US state-level fragmentation complicate unified North American workload placement.
- Legacy System Integration Debt:On-premises Windows Server estates and mainframe dependencies slow hybrid cloud migration velocity for enterprise buyers.
Strategic Opportunities
- Texas Cloud Hub Emergence:Austin-Dallas corridor attracts secondary hyperscale facility investment as California power constraints intensify.
- Function as a Service White Space:Event-driven serverless architectures reduce idle capacity overhead for intermittent workloads in financial services.
- Azure Stack Hybrid Penetration:On-premises integration with existing Microsoft estates captures enterprise demand for workload portability.
Industry Challenges
- Multi-Cloud Orchestration Talent Scarcity:Kubernetes and API orchestration expertise shortages constrain enterprise deployment velocity.
- Graviton Migration Complexity:x86-to-Arm workload recompilation creates friction for software vendors supporting heterogeneous silicon environments.
- Software-Defined Networking Certification Delays:Logical isolation validation for multi-tenant infrastructure extends security audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Everything As a Service (Xaas) Market |
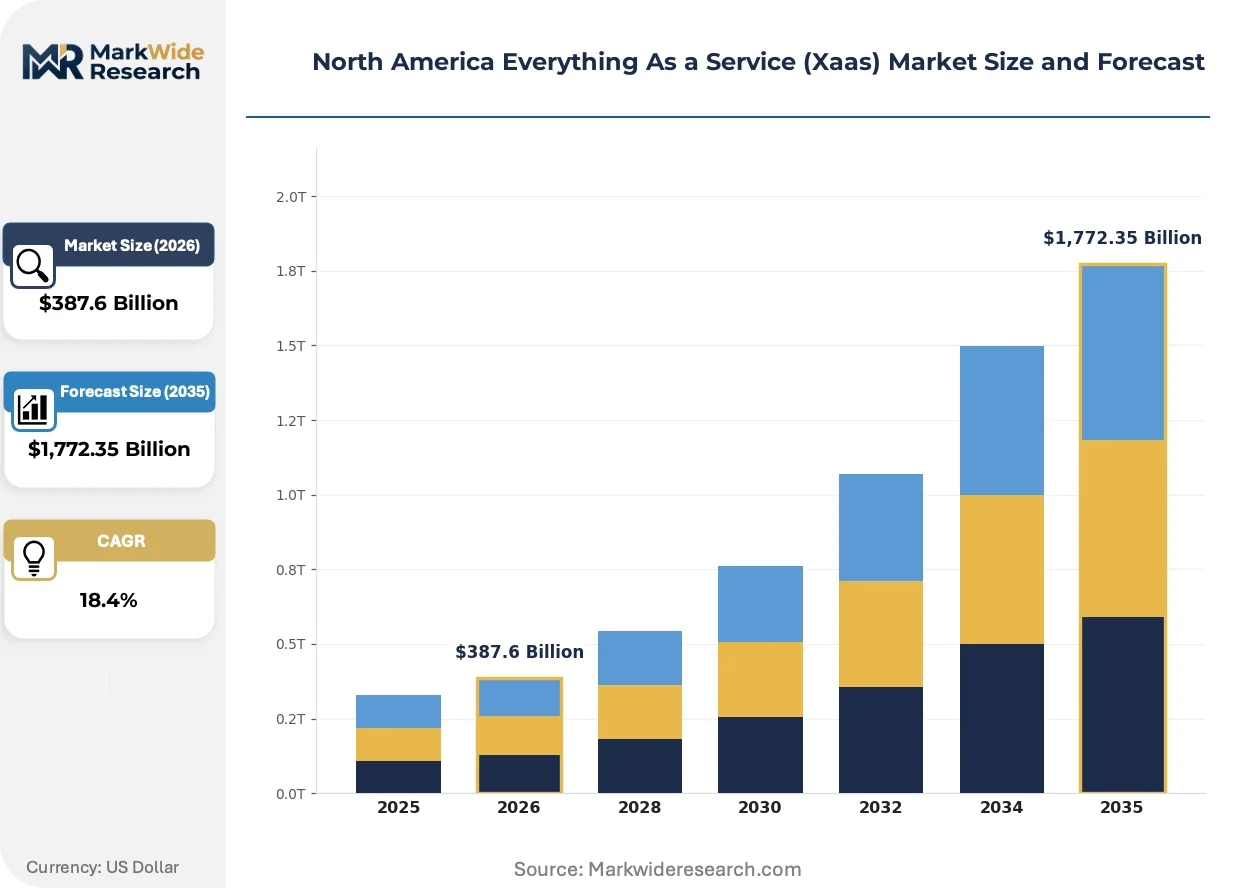
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,772.35 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Software as a Service, Infrastructure as a Service, Platform as a Service, Function as a Service End User: Small Businesses, Enterprises, Government Agencies, Nonprofits Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Industry Vertical: Healthcare, Retail, Financial Services, Education |
| Companies Covered | Amazon Web Services, Microsoft, Alphabet Inc., IBM Corporation, Oracle Corporation, Cisco Systems, Salesforce, Adobe Inc., AT&T Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Everything As a Service (Xaas) Market Trends and Innovations
Serverless computing architectures and sovereign cloud requirements are compressing traditional infrastructure procurement cycles while elevating compliance engineering to a core competitive differentiator.
Arm-based silicon is electrifying hyperscale data center economics through custom processor development that reduces per-workload power consumption. Cloud infrastructure providers across North America are adopting these designs to offset electricity cost inflation in California and Virginia facilities. The structural consequence is a realignment of total cost of ownership calculations that favors vertically integrated hardware-software stacks over commodity x86 procurement.
US FedRAMP authorization mandates from the General Services Administration constrain which providers may contract with federal agencies. The industrial consequence is a bifurcation between capital-intensive authorized vendors and excluded competitors. Government and defense-adjacent verticals are responding by consolidating procurement around pre-authorized provider lists, compressing vendor diversity.
Consumption-based billing models are displacing perpetual licensing across enterprise software procurement. Channel relationships with systems integrators are restructuring around managed service overlays rather than license resale. This pattern is most visible in US healthcare and financial services verticals where capital expenditure constraints favor operational expense treatment.
North America Everything As a Service (Xaas) Market Segmentation
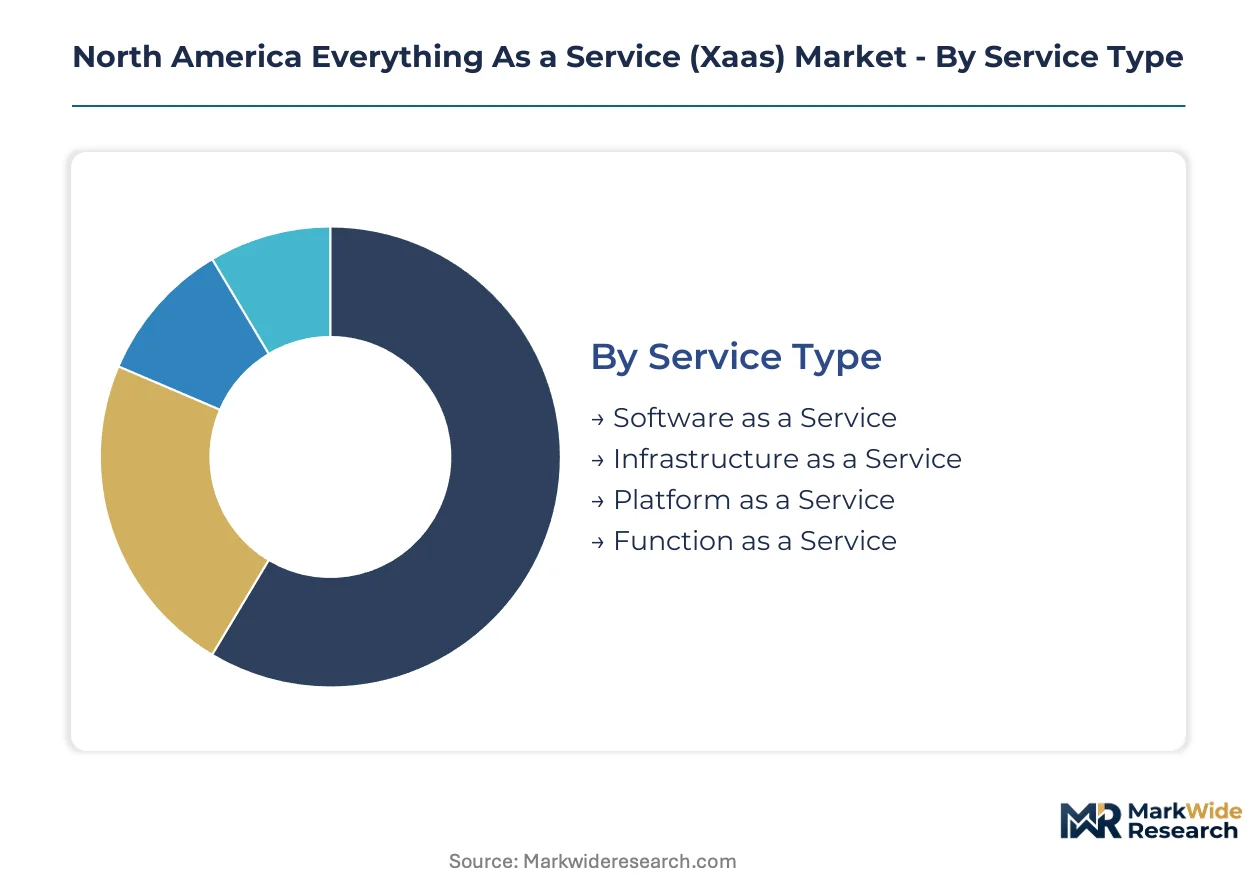
Service architecture and procurement patterns fragment the North America XaaS landscape into distinct investment profiles. Each segmentation dimension reveals divergent compliance burdens, contract structures, and infrastructure requirements that reshape vendor go-to-market strategies across the region.
Service Type:
Capital intensity concentrates in infrastructure-heavy segments where physical data center buildouts and silicon customization demand multi-billion-dollar commitments.
- Software as a Service:Application delivery via browser-based interfaces eliminates client-side infrastructure requirements. US hospital systems under HIPAA interoperability mandates drive recurring subscription demand for electronic health records management.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned through virtualized abstraction layers. Texas's Austin-Dallas corridor attracts hyperscale facility investment as California power constraints intensify, redirecting capacity expansion.
- Platform as a Service:Development environments and middleware services abstract underlying infrastructure complexity. Enterprise DevOps teams leverage container orchestration for accelerated deployment cycles.
- Function as a Service:Event-triggered serverless execution models meter billing at the individual request level. Financial services firms deploy intermittent workloads with minimal idle capacity overhead.
Software as a Service absorbs the bulk of installed capacity; Function as a Service is expanding most quickly.
End User:
Contract value and procurement sophistication create tiered vendor engagement models across organizational scale.
- Enterprises:Multi-year enterprise agreements with custom service-level agreements and dedicated support tiers. Hybrid cloud integration with legacy Windows Server estates sustains Microsoft Azure Stack penetration.
- Government Agencies:FedRAMP authorization mandates from the US General Services Administration filter eligible vendors through capital-intensive compliance investments. Defense-adjacent verticals consolidate procurement around pre-authorized provider lists.
- Small Businesses:Self-service provisioning through credit-card billing with minimal contract negotiation. Off-the-shelf SaaS configurations predominate over customized implementations.
- Nonprofits:Grant-funded technology budgets favor discounted or donated service tiers with restricted feature sets. Capacity planning aligns with unpredictable donation cycles.
Enterprises command the highest contract values; Government Agencies impose the steepest compliance barriers.
Deployment:
Architecture choices determine sovereignty alignment, latency positioning, and integration complexity for workload placement.
- Hybrid Cloud:Workload portability between on-premises infrastructure and elastic public capacity. California and New York state data residency statutes fragment architecture decisions for multi-state operators.
- Public Cloud:Shared multi-tenant infrastructure with metered consumption billing. Amazon Web Services sustains the broadest footprint through custom Graviton processor development.
- Private Cloud:Single-tenant dedicated infrastructure with enhanced logical isolation. FedRAMP authorization timelines extend procurement cycles for security-sensitive deployments.
- Multi-Cloud:Distributed workload placement across competing provider platforms. Kubernetes orchestration expertise scarcity constrains enterprise deployment velocity.
Hybrid Cloud captures the most complex integration spend; Multi-Cloud is gaining share fastest among risk-mitigation strategies.
Industry Vertical:
Regulatory density and data sensitivity create vertical-specific procurement patterns and vendor specialization.
- Healthcare:HIPAA-mandated interoperability requirements drive SaaS adoption for electronic health records management. Patient data residency constraints limit cross-border workload placement.
- Financial Services:Event-driven serverless architectures reduce idle capacity overhead for intermittent trading and risk calculation workloads. SEC audit trails impose retention and access logging requirements.
- Retail:Seasonal demand volatility favors elastic capacity scaling over fixed infrastructure commitments. Point-of-sale integration with inventory management systems drives API orchestration demand.
- Education:Semester-based enrollment cycles create predictable but lumpy capacity requirements. Federal student aid compliance imposes data handling restrictions on cloud providers.
Healthcare anchors regulatory complexity; Financial Services is climbing the fastest on event-driven architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where federal procurement mandates and hyperscale facility investments anchor regional capacity expansion. Canada and Mexico present distinct regulatory and infrastructure profiles that shape cross-border workload placement strategies.
United States
FedRAMP authorization requirements from the US General Services Administration filter vendor eligibility for federal agency contracts, forcing capital-intensive compliance investments. California's Silicon Valley tech corridor sustains primary hyperscale demand, though power constraints are redirecting capacity expansion toward Texas's emerging Austin-Dallas cloud hub.
Canada
Provincial privacy laws in Quebec and British Columbia impose data residency requirements that complicate unified North American workload placement. Health Canada guidelines intersect with provincial health authority procurement, creating layered compliance for healthcare SaaS providers. Toronto-Waterloo corridor attracts secondary cloud facility investment serving financial services verticals.
Mexico
Nearshoring manufacturing demand drives industrial IoT platform adoption among automotive and electronics exporters. The country's federal data protection authority imposes cross-border transfer restrictions that affect US-headquartered provider architectures. Mexico City metro area concentrates enterprise demand, while northern border states attract edge computing investment for latency-sensitive manufacturing applications.
North America Everything As a Service (Xaas) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale infrastructure providers commanding consolidated positions while SaaS application vendors fragment across vertical specializations. The vendor landscape exhibits tiered concentration: a handful of integrated platforms absorb majority infrastructure spend, while hundreds of niche application providers compete for departmental budgets. Three archetypes dominate: vertically integrated hyperscalers with custom silicon, enterprise software incumbents with hybrid cloud extensions, and vertical SaaS specialists with regulatory-compliant workflows. Competitive dynamics center on M&A-driven portfolio expansion and strategic partnerships for multi-cloud orchestration capabilities.
Within the vertically integrated tier, Amazon Web Services, Microsoft, and Alphabet Inc. occupy positions defined by capital intensity and custom processor development. Amazon Web Services exemplifies the custom silicon archetype through Graviton processor deployment. Microsoft anchors enterprise hybrid demand via on-premises integration capabilities. Alphabet Inc. represents the data-native platform approach with analytics-optimized infrastructure. These three entities collectively shape pricing benchmarks and compliance standards that cascade through the broader vendor ecosystem.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Alphabet Inc. |
| IBM Corporation |
| Oracle Corporation |
| Cisco Systems |
| Salesforce |
| Adobe Inc. |
| AT&T Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive silicon design by hyperscale providers anchors both supply security and pricing power across the North America XaaS landscape, as custom Arm-based processor development insulates infrastructure operators from commodity x86 cost volatility while enabling subscription-rate differentiation against mid-tier competitors lacking comparable vertical control.
Pricing Analysis
The volume-vs-margin split separates hyperscale infrastructure providers from application-layer SaaS vendors. Three-tier pricing structure across premium, standard, and economy levels dominates enterprise procurement, with FedRAMP authorization tier and consumption volume scale as primary differentiation drivers. Pricing pressure stems from Arm-based silicon migration reducing per-workload infrastructure costs. Small businesses exhibit highest price sensitivity through credit-card self-service channels; government agencies demonstrate lowest sensitivity given compliance-driven procurement consolidation.
Supply Chain Analysis
Direct-to-hyperscale channels handle enterprise and government buyer demand, bypassing traditional distribution intermediaries. Taiwan, South Korea, and the United States concentrate advanced semiconductor fabrication capacity. Custom processor development, specialized memory modules, and precision cooling systems constitute critical input dependencies. Single-source vulnerability around Taiwan-based foundry capacity presents structural supply risk. Distribution runs through direct provider-customer contracting with systems integrator overlays for hybrid deployment complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where custom silicon development and captive data center construction represent the decisive upstream levers separating tier-one providers from capital-constrained followers.
For Market Incumbents: Anchor federal agency relationships through accelerated FedRAMP authorization investments before mid-tier competitors close compliance gaps. Pursue backward integration into custom processor design to sustain TCO advantages against x86-dependent rivals. Defend against Function as a Service specialists by embedding serverless capabilities within existing platform ecosystems. For New Entrants and Emerging Players: Kubernetes-native orchestration tools offer a technology-first wedge into multi-cloud management white space where enterprise talent scarcity constrains incumbent response velocity. Target Texas cloud corridor expansion as secondary hyperscale geography where California power constraints delay incumbent capacity additions. Pursue channel partnerships with systems integrators lacking independent platform development capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical SaaS specialists with regulatory-compliant workflow automation and established hospital system or defense agency reference accounts. Long-term viability hinges on differentiation durability against platform consolidation. Watch Function as a Service penetration rates within financial services as inflection indicator for serverless architecture maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | Graviton-class processor deployment reduces per-workload power consumption and subscription pricing flexibility. |
| FedRAMP Authorization Acceleration | Pre-authorized status filters federal procurement toward capital-intensive compliant vendors. |
| Hybrid Cloud Platform Integration | Azure Stack-style on-premises extension captures enterprise workload portability requirements. |
| Serverless Architecture Expansion | Function as a Service capabilities address financial services intermittent workload economics. |
| Geographic Capacity Diversification | Texas corridor investment offsets California power constraint risks for hyperscale facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with cloud platform engineers, federal procurement officers, enterprise IT directors, and systems integrator practice leads. SEC 10-K disclosures, hyperscaler capital expenditure reports, FedRAMP authorization databases, and state-level data residency statute compilations supplied quantitative benchmarks. Bottom-up service-type demand modeling and top-down infrastructure capacity assessment enabled cross-validation.
Segment-level granularity modeled deployment architecture, organization scale, industry vertical, and integration complexity dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand curves and capacity expansion schedules. Forecast inputs incorporated FedRAMP authorization pipeline velocity, Arm-based silicon adoption curves, and state data residency statute enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated sovereign cloud mandates or disruptive processor architecture shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
India ICT Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Mobile Sharing Power Bank Rental Service Market
Digital Solutions
Asia-Pacific Smart Government Market