
 Global Silica Analyzer Market | 2026-2036
Global Silica Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silica Analyzer Market Outlook
Modular sensor-platform bundling is hardening as the dominant procurement pattern, with buyers favoring analyzers that integrate seamlessly into distributed control systems. Hach (Veralto) leverages its channel density in municipal water treatment to sustain recurring reagent revenue. ABB anchors large power-utility contracts through its automation ecosystem, while Swan Analytical Instruments specializes in high-purity water applications with proprietary optical architectures.
A silica analyzer measures dissolved and reactive silica concentrations in aqueous matrices, typically employing colorimetric detection with molybdate-blue chemistry at detection thresholds below 0.5 parts per billion to safeguard critical industrial water systems. Online analyzers command the largest installed base due to continuous monitoring mandates in thermal power cycles, whereas portable units represent the fastest-expanding configuration as field audits intensify under tightened discharge rules. UV-VIS spectrophotometry dominates technology selection for its balance of precision and operational simplicity, while ion chromatography captures premium positioning in semiconductor-grade water verification.
The EPA enforces silica limits under the Clean Water Act, compelling U.S. utilities to deploy certified continuous monitoring systems, while Japan's METI promotes analyzer upgrades through efficiency standards for thermal power fleets. The EU's Industrial Emissions Directive extends comparable obligations across member states, tightening product certification requirements through notified-body assessment. Stakeholders must weigh reagent-locked platform economics against open-architecture alternatives as regulatory stringency diverges across jurisdictions.
Market Dynamics
Continuous monitoring mandates in thermal power cycles are hardening procurement specifications, with buyers now requiring seamless distributed control system integration as a baseline qualification rather than a premium feature.
Growth Catalysts
- EPA Clean Water Act enforcement:U.S. utilities face binding silica discharge limits that compel certified analyzer deployment across coal and combined-cycle fleets.
- Semiconductor fabrication expansion:Ultra-high-purity water requirements in wafer processing drive ion chromatography analyzer adoption for sub-ppb detection thresholds.
- China power infrastructure buildout:Coal-fired and nuclear capacity additions sustain demand for online boiler water surveillance systems.
Market Restraints
- Reagent cost volatility:Molybdate and reducing agent price swings compress operating margins for colorimetric platform operators.
- Optical component supply concentration:Specialized UV-VIS photodetector manufacturing concentrates in German and Japanese supplier networks.
- Ion chromatography throughput limits:Sequential sample processing constrains deployment in high-frequency industrial process control loops.
Strategic Opportunities
- India thermal power modernization:CEA-mandated efficiency upgrades create procurement windows for continuous silica monitoring in aging coal plants.
- Predictive maintenance convergence:Integration of analyzer data streams with AI-driven asset management platforms enables new service revenue models.
- EU Industrial Emissions Directive:Notified-body certification requirements favor established vendors with existing CE-marked product portfolios.
Industry Challenges
- Analytical chemist scarcity:Specialized expertise in molybdate-blue method validation and optical calibration remains concentrated among aging workforce cohorts.
- Legacy DCS integration complexity:Proprietary communication protocols in installed automation infrastructure complicate seamless analyzer deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silica Analyzer Market |
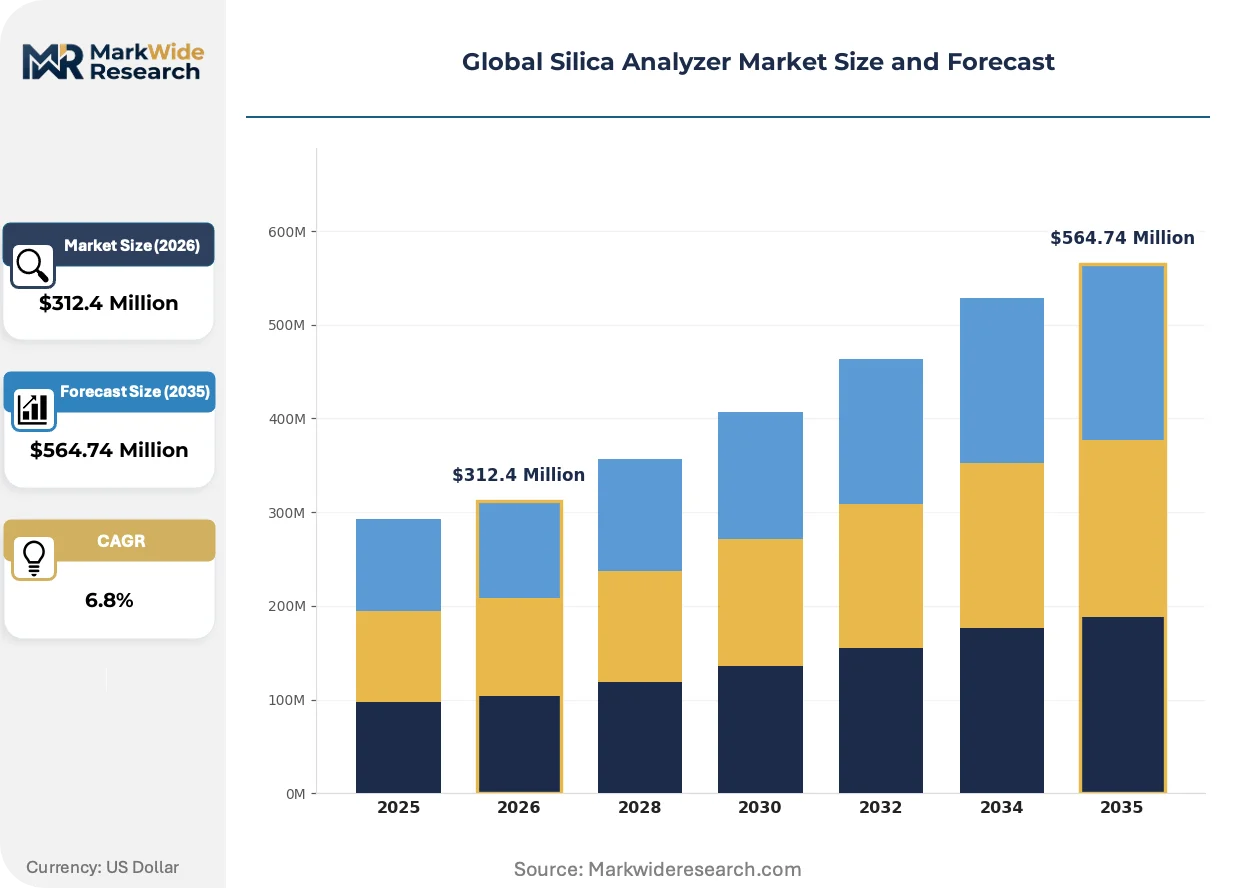
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Benchtop Analyzers, Online Analyzers, Laboratory Analyzers End Use Industry: Water Treatment, Oil & Gas, Power Generation, Chemical Processing Technology: UV-VIS Spectrophotometry, Ion Chromatography, Colorimetry, Titration Application: Environmental Monitoring, Quality Control, Research, Process Optimization |
| Companies Covered | Mettler Toledo, Horiba, Hach (Veralto), DKK-TOA Corporation, Waltron Bull & Roberts, ABB, Swan Analytical Instruments, Nikkiso, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silica Analyzer Market Strategic Shifts
Analyzer architectures are converging around modular sensor platforms that decouple hardware from reagent supply, enabling vendor switching and compressing traditional lock-in economics.
UV-VIS spectrophotometry is consolidating as the dominant detection modality for online silica measurement, offering sufficient precision for power cycle chemistry control without ion chromatography's operational complexity. Thermal utilities in China and the United States adopt this approach for continuous boiler water surveillance. The technology is consolidating market share by displacing laboratory-based grab sampling in all but semiconductor-grade verification applications.
Japan's METI efficiency standards for thermal power fleets mandate analyzer upgrade cycles tied to plant performance benchmarks. Operators must demonstrate continuous silica monitoring capability to qualify for operational permits. Coal and combined-cycle installations face the steepest compliance timelines, accelerating replacement demand for legacy electrochemical sensors.
Service unbundling is fragmenting traditional analyzer procurement, with end-users separating hardware acquisition from reagent supply and calibration contracts. Municipal water treatment authorities in Germany and the United States now source consumables through competitive tender rather than bundled platform agreements. This pattern compresses recurring revenue per unit for incumbent vendors while opening entry points for third-party reagent specialists.
Global Silica Analyzer Market Segmentation
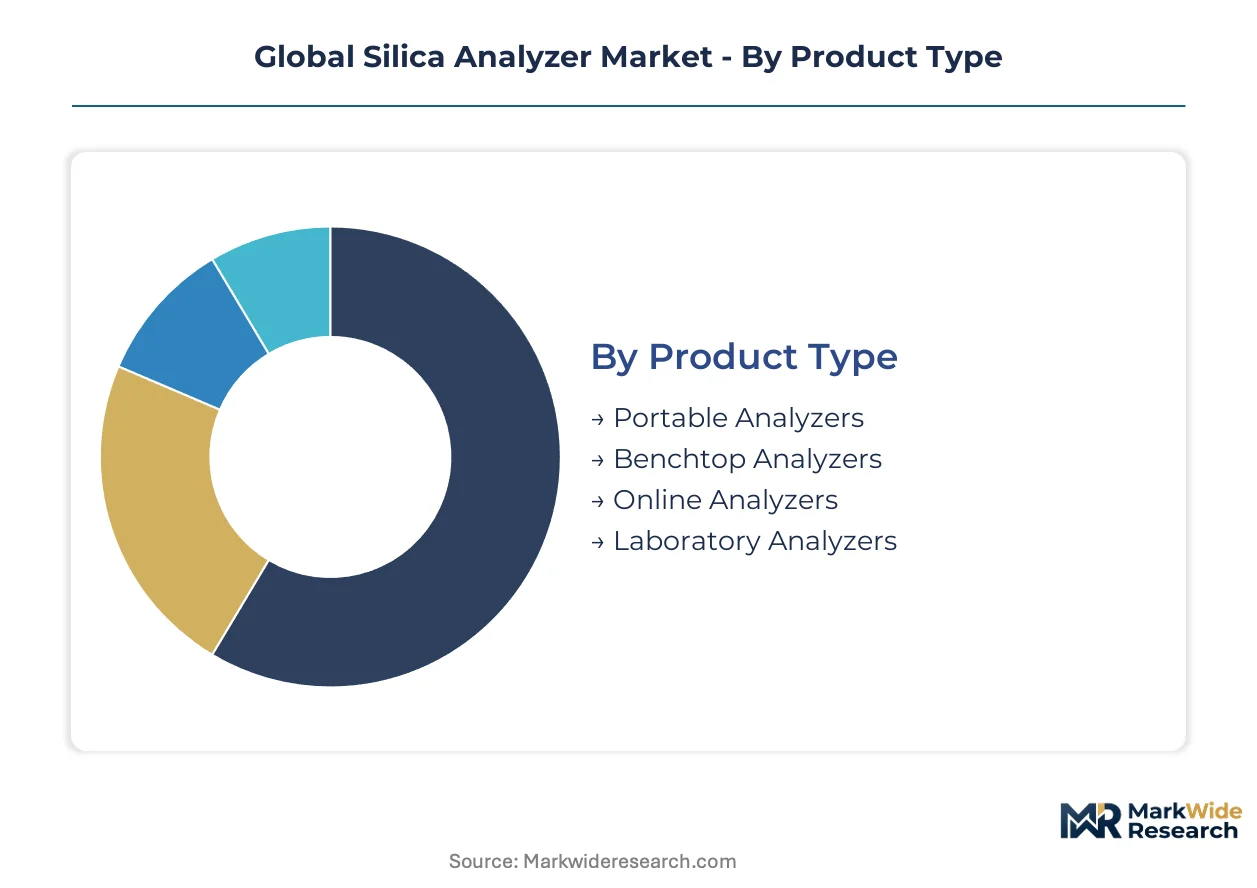
Silica analyzer procurement decisions hinge on detection threshold requirements, integration complexity, and regulatory compliance mandates. Buyers weigh continuous monitoring needs against capital constraints and operational expertise availability.
Product Type:
Procurement specifications diverge sharply based on monitoring frequency mandates and capital deployment flexibility.
- Online Analyzers:These systems perform continuous measurement through automated sampling loops with molybdate-blue chemistry, achieving detection thresholds below 0.5 parts per billion. Thermal power operators in China and the United States deploy these for boiler water surveillance under EPA Clean Water Act and METI efficiency standards.
- Portable Analyzers:Battery-powered field units enable spot-checking at discharge points and remote treatment facilities. German municipal water authorities and U.S. utility field crews are expanding procurement for audit-intensive compliance regimes.
- Benchtop Analyzers:Laboratory-grade systems serve centralized quality control facilities with higher throughput than portable alternatives.
- Laboratory Analyzers:Research-focused configurations support method development and reference standard calibration.
Online analyzers lead on scale; portable analyzers lead on momentum.
End Use Industry:
Water chemistry stringency and asset protection economics determine vertical penetration depth.
- Power Generation:Coal-fired and combined-cycle plants require continuous silica monitoring to prevent turbine scaling and membrane fouling. China's nuclear capacity expansion and India's CEA-mandated efficiency upgrades sustain procurement velocity.
- Water Treatment:Municipal utilities deploy analyzers for intake protection and discharge compliance. German authorities unbundle reagent contracts from hardware, compressing vendor lock-in economics.
- Oil & Gas:Produced water management and steam flood operations drive analyzer deployment in extraction and refining segments.
- Chemical Processing:High-purity water requirements in specialty chemical manufacturing support ion chromatography adoption.
Power generation commands the largest installed base; water treatment offers the most open procurement architecture.
Technology:
Detection modality selection trades precision against operational complexity and consumable cost exposure.
- UV-VIS Spectrophotometry:Dominates online applications through balanced precision and simplified maintenance. Thermal utilities favor this approach for continuous boiler water surveillance, displacing grab sampling in all but semiconductor-grade verification.
- Ion Chromatography:Captures premium positioning in sub-ppb detection requirements. Wafer fabrication facilities in Japan and the United States specify this technology for ultra-high-purity water verification despite sequential processing constraints.
- Colorimetry:Traditional molybdate-blue methods persist in cost-sensitive installations with moderate precision requirements.
- Titration:Limited to specialized applications where interferent profiles complicate spectrophotometric detection.
UV-VIS spectrophotometry leads on installed base; ion chromatography leads on value per unit.
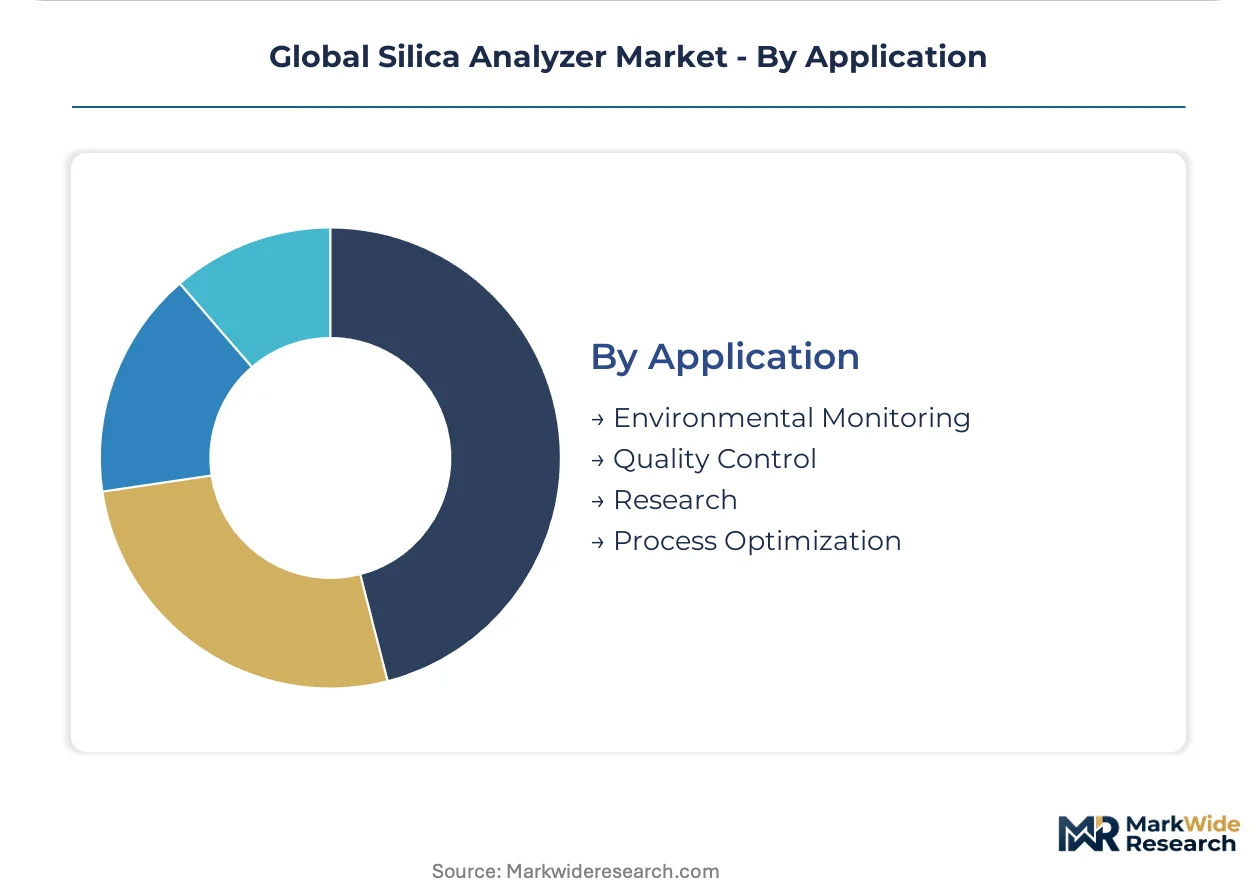
Application:
Regulatory enforcement intensity and process control integration depth shape demand patterns.
- Environmental Monitoring:Discharge permit compliance drives continuous analyzer deployment. EPA enforcement in the United States and EU Industrial Emissions Directive obligations mandate certified monitoring systems with audit trails.
- Quality Control:Semiconductor fabrication and pharmaceutical water systems require documented silica levels for batch release. Japanese and German manufacturers specify ion chromatography for critical applications.
- Process Optimization:Real-time silica data feeds into chemical dosing control loops, reducing reagent consumption and scaling incidents.
- Research:Academic and standards institutions develop reference methods and validate emerging detection technologies.
Environmental monitoring leads on regulatory compulsion; quality control leads on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica analyzer manufacturing originated in German and Swiss precision instrumentation clusters during the mid-20th century, with Japanese electronics specialists later scaling optical detection architectures for power utility applications.
United States
Coal-fired and combined-cycle fleets drive analyzer procurement under EPA Clean Water Act discharge mandates. The EPA enforces binding silica limits that compel certified continuous monitoring systems across utility infrastructure. Texas and Ohio host dense concentrations of thermal power installations where boiler water surveillance upgrades accelerate replacement cycles.
China
Coal-fired capacity expansion and nuclear power buildout sustain demand for online boiler water surveillance systems. The country's Ministry of Ecology and Environment (MEE) implements discharge standards that tighten monitoring requirements for thermal generators. Yangtze River Delta manufacturing clusters produce photodetector subassemblies for domestic and export analyzer assembly.
Germany
Municipal water treatment authorities unbundle reagent contracts from hardware procurement, compressing traditional vendor lock-in economics. The EU Industrial Emissions Directive extends certified monitoring obligations across member states through notified-body assessment protocols. Bavaria and North Rhine-Westphalia concentrate precision optics manufacturing for UV-VIS spectrophotometer components.
Japan
Wafer fabrication facilities specify ion chromatography analyzers for ultra-high-purity water verification in semiconductor manufacturing. METI efficiency standards for thermal power fleets mandate analyzer upgrade cycles tied to plant performance benchmarks. Kanto and Kansai industrial corridors host integrated electronics-water treatment supply chains serving fabrication plants.
India
Central Electricity Authority-mandated efficiency upgrades create procurement windows for continuous silica monitoring in aging coal plants. The country's national environmental regulator enforces discharge limits that drive analyzer deployment across state electricity boards. Gujarat and Maharashtra thermal clusters represent the primary near-term installation targets for online surveillance systems.
Global Silica Analyzer Market Competitive Environment
Premium-margin players sit above commodity-margin players across reagent-locked versus open-architecture platform economics. The vendor base organizes into three tiers: diversified automation conglomerates with integrated control system offerings, specialized water analytics firms with proprietary optical architectures, and regional instrumentation distributors with localized service networks. Dominant competitive moves include modular sensor-platform development to decouple hardware from consumable supply, and predictive maintenance service bundling to capture recurring revenue streams.
Among Swiss and German precision instrumentation specialists, Mettler Toledo and Swan Analytical Instruments occupy positions exemplifying high-purity water application focus. Japanese electronics conglomerates Horiba and DKK-TOA Corporation represent the scale-driven archetype with diversified analytical instrumentation portfolios. Hach (Veralto) anchors the recurring-reagent business model through channel density in municipal water treatment segments.
| Leading Market Players |
|---|
| Mettler Toledo |
| Horiba |
| Hach (Veralto) |
| DKK-TOA Corporation |
| Waltron Bull & Roberts |
| ABB |
| Swan Analytical Instruments |
| Nikkiso |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
EPA Clean Water Act discharge mandates gate both qualified supply and premium-tier pricing access, as certified continuous monitoring systems require CE-marked optical subassemblies and molybdate-reagent compatibility that only established vendors can guarantee. Buyers face a bifurcated market where regulatory compliance documentation commands substantial premiums over uncertified alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers capturing CE certification and METI-compliant documentation, standard tiers targeting municipal utilities with bundled reagent contracts, and economy tiers serving spot-check field applications. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because third-party reagent specialists are unbundling consumable supply. Municipal water treatment authorities in Germany exhibit the highest price sensitivity, while semiconductor fabrication facilities in Japan show minimal elasticity for sub-ppb ion chromatography systems.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns to serve power utility and municipal water treatment clusters. Manufacturing draws from specialized UV-VIS photodetector production concentrated in Bavarian and Kansai precision optics clusters, molybdate reagent synthesis in Chinese chemical processing zones, and reducing agent supply from Indian pharmaceutical chemical producers. Single-source vulnerability in German photodetector manufacturing creates structural exposure. Distribution runs through authorized service networks rather than direct OEM-to-end-user channels, with calibration and maintenance contracts anchoring recurring revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silica analyzer market functions as a regulatory compounder, where EPA Clean Water Act enforcement and Japan's METI efficiency standards create replacement cycles independent of underlying industrial demand.
For Market Incumbents: Extend platform modularity to decouple hardware from reagent lock-in, as German municipal authorities increasingly unbundle procurement and third-party reagent specialists threaten recurring revenue streams. Invest in predictive maintenance service bundling to capture AI-driven asset management revenue. Strengthen backward integration into optical subassembly production to reduce exposure to German and Japanese photodetector supply concentration. For New Entrants and Emerging Players: Portable analyzer architectures with simplified UV-VIS detection offer the most penetrable wedge, as field audit intensity rises under tightened discharge rules and incumbent vendors underinvest in battery-powered form factors. Target India's CEA-mandated efficiency upgrade window, where aging coal plants require continuous monitoring but procurement sophistication lags Chinese and U.S. utilities. Pursue competitive reagent supply contracts as a go-to-market angle, leveraging unbundling trends in German and U.S. municipal segments. For Investors and Strategic Acquirers: Roll-up economics work for specialized water analytics firms with proprietary optical architectures because the vendor base fragments across Swiss precision instrumentation heritage, Japanese electronics conglomerate diversification, and regional service networks lacking scale. Long-term viability rests on regulatory enforcement durability rather than technology disruption risk. Monitor EPA enforcement intensity and METI permit renewal timelines as inflection indicators for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Sensor-Platform Development | Decouples hardware from reagent supply, enabling vendor switching and compressing lock-in economics. |
| Predictive Maintenance Service Bundling | Captures recurring revenue through AI-driven asset management platforms integrated with analyzer data streams. |
| CE Marking and Notified-Body Certification | Qualifies vendors for EU Industrial Emissions Directive procurement under tightened assessment protocols. |
| Backward Integration into Optical Subassemblies | Reduces exposure to German and Japanese photodetector supply concentration and tariff vulnerability. |
| Geographic Expansion into India Thermal Clusters | Targets CEA-mandated efficiency upgrades in Gujarat and Maharashtra coal plants with localized service networks. |
Study Parameters
Multiple input streams — primary interviews with power plant chemistry managers, municipal water treatment procurement officers, and semiconductor fab water systems engineers; secondary validation through EPA enforcement databases, METI efficiency standard filings, and EU Industrial Emissions Directive notified-body registries; and customs trade data on photodetector and reagent imports — were reconciled through bottom-up installation tracking and top-down market sizing. Technical specifications from CE-marked product filings and METI permit documentation provided segmentation granularity.
Data-stream reconciliation across product type, technology modality, end-use vertical, and regional regulatory cluster dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from installed base replacement cycles, capacity expansion pipelines, and regulatory mandate compliance timelines. Forecast inputs incorporated coal-fired and nuclear power buildout trajectories in China, semiconductor fabrication capacity additions in Japan and the United States, and municipal water treatment infrastructure upgrade budgets in Germany.
The model holds under stable regulatory enforcement intensity and continued thermal power fleet operation; deviation in EPA enforcement posture, METI standard revision, or accelerated renewable energy substitution would shift replacement demand timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Paint Tester Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Solid Density Tester Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Laboratory Ware Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market