
 Valencene Market | 2026-2036
Valencene Market Size, Share, and Industry Trends Forecast 2026-2036
Valencene Market Analytics
The capability gap between precision fermentation specialists and conventional citrus extractors is collapsing as capital requirements for microbial production platforms fall. Givaudan leverages its integrated flavor creation network to secure consistent valencene supply chains. Firmenich anchors its position through deep biotechnology partnerships that sustain long-term fermentation yield improvements. Evolva competes by specializing in yeast-derived terpenoid platforms that reduce agricultural feedstock dependency.
Valencene is a bicyclic sesquiterpene hydrocarbon with the molecular formula C15H24, characterized by a fresh citrus aroma profile and boiling point near 123°C at reduced pressure; manufacturers isolate it from Valencia orange peel oil or produce it via engineered microbial fermentation for use as a fragrance precursor and flavoring agent. Natural valencene commands premium positioning in cosmetics and fine fragrances where clean-label sourcing drives purchasing decisions, while synthetic valencene dominates food flavoring applications where cost efficiency and batch consistency outweigh provenance claims. The liquid form leads volume shipments due to ease of blending into fragrance compounding workflows, though concentrate formats gain traction among agricultural product formulators seeking precise dosing control.
EPA registration requirements govern valencene use in insect repellent formulations, while FDA food additive standards and FEMA GRAS listings shape permissible applications in food and beverage markets. REACH compliance in Europe imposes rigorous substance registration and safety documentation burdens on importers and blenders alike. Stakeholders must monitor regulatory divergence between jurisdictions as bio-identical labeling claims face tightening scrutiny from multiple agencies.
Market Dynamics
Precision fermentation platforms are collapsing the cost gap with conventional citrus extraction, forcing fragrance houses to restructure supply strategies around microbial-derived terpenoid pipelines rather than agricultural feedstock dependency.
Growth Catalysts
- REACH compliance deadlines:European fragrance formulators face substance registration mandates that favor bio-identical valencene with documented safety dossiers over uncharacterized natural extracts.
- Florida citrus processing concentration:The state's orange peel oil distillation infrastructure provides established extraction capacity that anchors near-term supply security for natural valencene buyers.
- Engineered yeast platforms:Strain optimization advances in microbial terpenoid synthesis enable production independence from seasonal agricultural volatility and climate-exposed crop yields.
Market Restraints
- Agricultural feedstock concentration:Citrus greening disease pressure in Florida and Brazil threatens peel oil availability, concentrating supply risk in geographically narrow growing regions.
- Fermentation capex thresholds:Commercial-scale bioreactor installation and downstream purification systems require capital commitments that exclude mid-tier ingredient blenders from backward integration.
- EPA registration timelines:Insect repellent applications face multi-year efficacy and toxicology review cycles that delay market entry for novel valencene-based formulations.
Strategic Opportunities
- India personal care expansion:Domestic fragrance compounding growth and BIS standards alignment create entry pathways for certified bio-derived terpenoid suppliers.
- Japan METI biomanufacturing incentives:Government funding for precision fermentation scale-up supports technology partnerships targeting Asian cosmetic ingredient markets.
- Agricultural adjuvant applications:Valencene's insect repellent properties open formulation opportunities in crop protection products seeking botanical active ingredients.
Industry Challenges
- Fermentation scale-up expertise:Microbial terpenoid production requires specialized bioprocess engineering talent scarce among conventional citrus extractors.
- Cross-jurisdictional label claims:Divergent FDA, EFSA, and FEMA standards for natural versus bio-identical designation create compliance complexity for international product registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valencene Market |
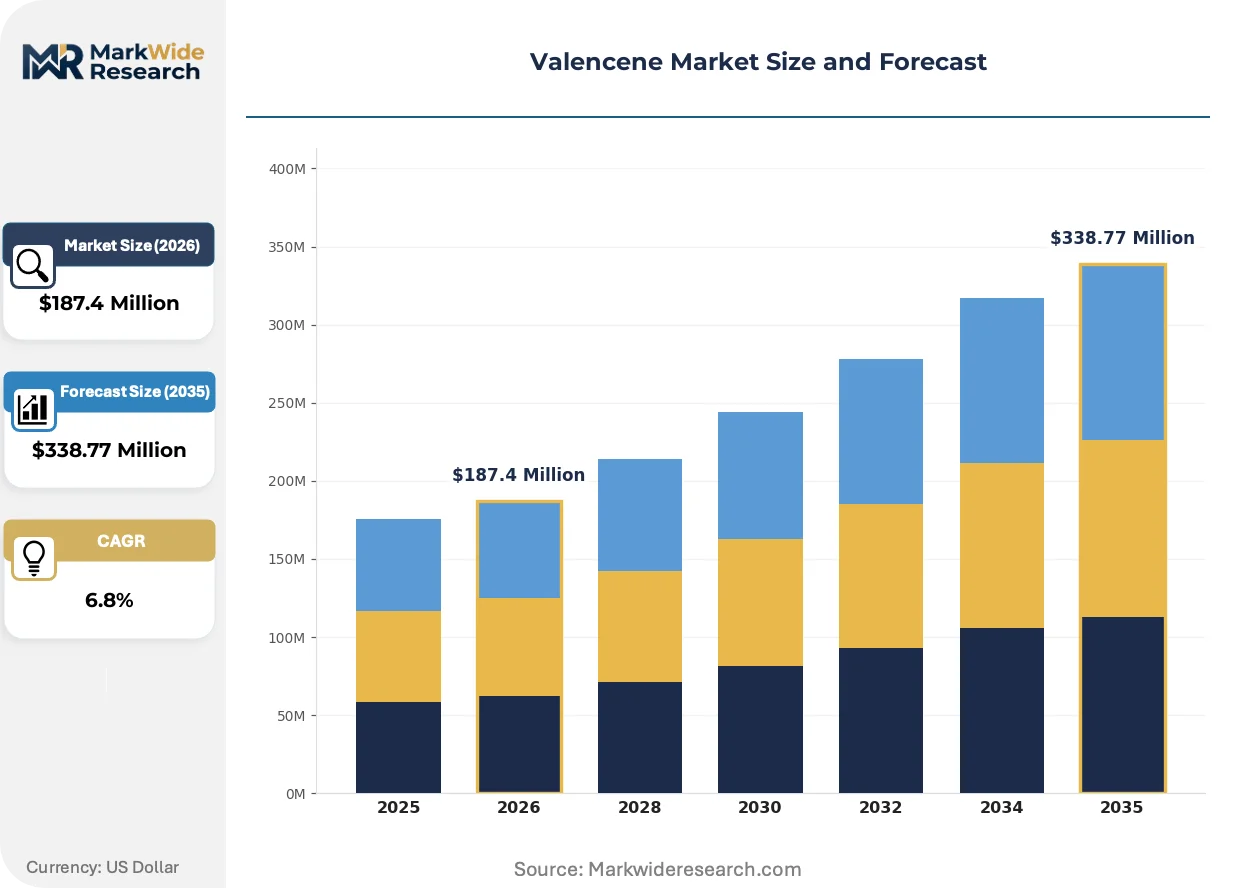
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Valencene, Synthetic Valencene, Blended Valencene, Food-Grade Valencene Application: Fragrances, Food Flavoring, Cleaning Products, Insect Repellents Form: Liquid, Powder, Concentrate, Emulsion Market Segment: Cosmetics, Pharmaceuticals, Food & Beverage, Agricultural Products |
| Companies Covered | Givaudan, Firmenich, International Flavors & Fragrances, Symrise, Sensient Technologies Corporation, Evolva, Isobionics, Citrus World, Florida Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valencene Market Evolving Landscape
Biotechnology adoption is fragmenting the valencene supply base into two distinct production paradigms, each demanding different technical capabilities and customer relationships from ingredient suppliers.
Precision fermentation infrastructure is bifurcating the supplier landscape between agricultural extractors and microbial production specialists. Fragrance houses with dedicated biotechnology partnerships now secure multi-year fermentation supply agreements. This technology compression is eroding the traditional premium commanded by cold-pressed Valencia orange oil in mid-market fragrance applications.
REACH substance registration requirements are tightening documentation burdens on imported natural extracts while streamlining pathways for characterized bio-identical molecules. European blenders increasingly specify fermentation-derived valencene to preempt regulatory scrutiny of botanical source variability. Cosmetic formulators in Germany and France now require batch-level substance identity verification that favors controlled microbial production over agricultural sourcing.
Clean-label purchasing specifications are rotating demand toward traceable supply chains with verified carbon footprints. Fine fragrance houses in Paris and Milan now audit terpenoid suppliers for agricultural provenance or fermentation energy sourcing. This behavioral shift disadvantages commodity peel oil traders lacking sustainability certification infrastructure, concentrating procurement relationships with vertically integrated producers offering documented lifecycle assessments.
Valencene Market Segmentation
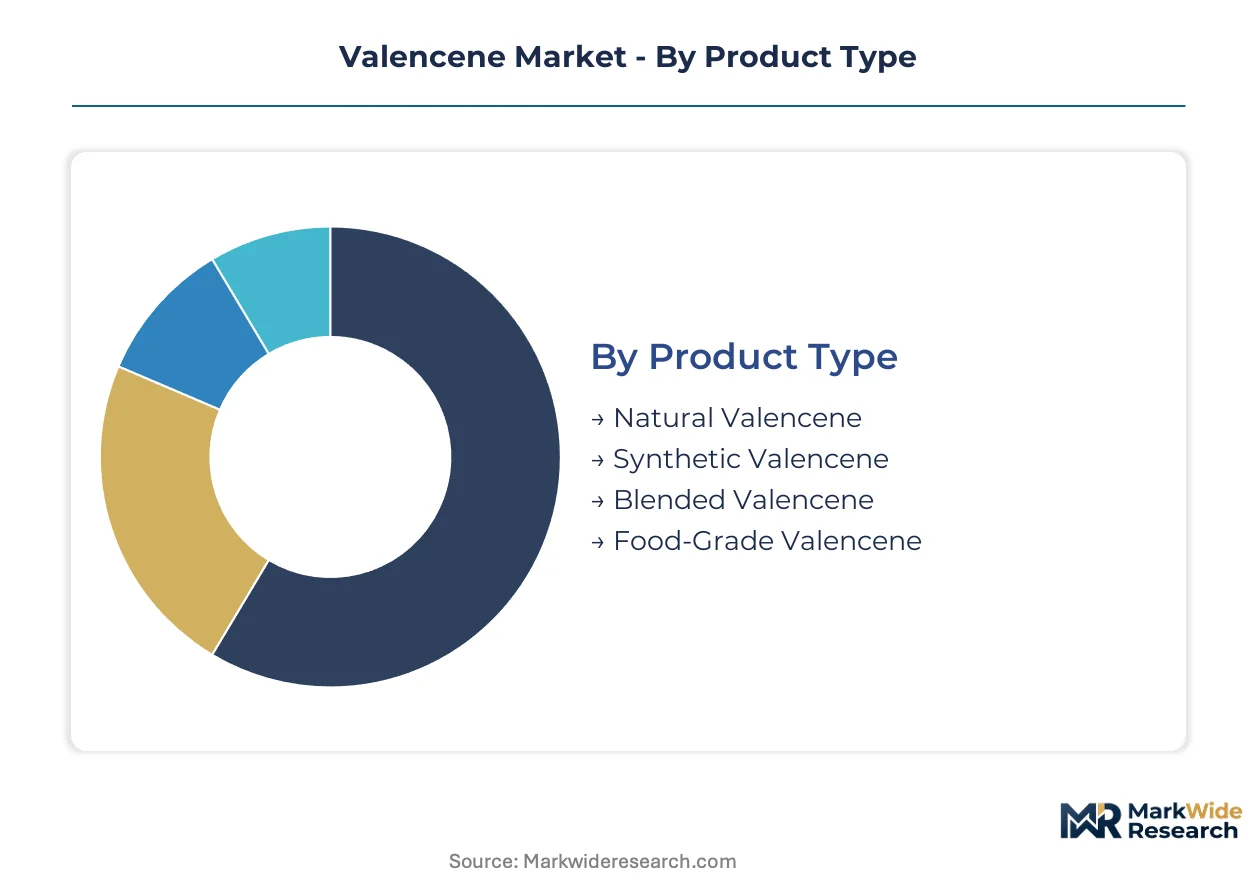
Valencene segmentation reveals distinct channel pathways where fragrance houses favor liquid concentrates for compounding workflows, while agricultural formulators seek powder formats for precise field dosing. Understanding these segment-channel linkages exposes where supply contracts concentrate and where microbial producers can displace citrus-derived supply.
Product Type:
Natural valencene flows through premium cosmetic channels demanding certified provenance, while synthetic variants serve food flavoring houses prioritizing batch consistency and cost predictability.
- Natural Valencene:Cold-pressed from Valencia orange peel oil with characteristic C15H24 sesquiterpene profile and fresh citrus aroma. Demand concentrates in French and Italian fine fragrance houses where clean-label sourcing mandates require documented agricultural provenance from Florida or Brazil citrus processing clusters.
- Synthetic Valencene:Chemically synthesized or bio-identical molecules produced via engineered microbial platforms. Food flavoring manufacturers in the United States specify this grade for FEMA GRAS compliance and elimination of seasonal supply volatility from citrus greening disease pressure.
- Blended Valencene:Hybrid formulations combining natural extracts with synthetic molecules to balance cost and sensory performance.
- Food-Grade Valencene:Refined to FDA and FSSAI purity standards for direct food contact applications.
By volume, synthetic valencene leads. By growth pace, natural valencene is gaining share fastest as REACH documentation requirements tighten.
Application:
Fragrance applications command margin premiums through Paris and Milan compounders, while insect repellent registrations face multi-year EPA review cycles that elongate revenue recognition timelines.
- Fragrances:Serves as a top-note citrus component in fine perfumes and personal care products. European fragrance houses specify valencene for its fresh, clean aroma profile and compatibility with biodegradable formulation mandates under EU Green Deal guidelines.
- Food Flavoring:Citrus flavor enhancement in beverages, confectionery, and savory applications. United States flavor houses drive volume through FEMA GRAS-listed applications where cost efficiency outweighs natural provenance claims.
- Cleaning Products:Fragrance masking and fresh scent delivery in household and industrial formulations.
- Insect Repellents:Botanical active ingredient leveraging valencene's natural repellent properties against mosquitoes and agricultural pests.
Fragrance applications generate the highest per-kilogram returns. Insect repellent registrations offer the steepest expansion trajectory pending EPA efficacy clearances.
Form:
Liquid formats dominate fragrance compounding throughput, while concentrate and emulsion forms capture agricultural adjuvant applications requiring precise active ingredient metering.
- Liquid:Standard presentation for fragrance house blending operations with immediate solubility in ethanol and dipropylene glycol carriers. German and French cosmetic formulators specify liquid valencene for streamlined manufacturing workflows and minimal handling complexity.
- Concentrate:High-potency format for agricultural product manufacturers seeking reduced shipping volumes and extended shelf stability. Japanese crop protection formulators favor concentrates under METI biomanufacturing incentives supporting precision fermentation feedstocks.
- Powder:Encapsulated or adsorbed formats for dry mix applications and controlled release formulations.
- Emulsion:Water-dispersible preparations for aqueous cleaning products and sprayable agricultural formulations.
Liquid forms anchor current shipment volumes. Concentrate formats are climbing the fastest as agricultural adjuvant applications scale.
Market Segment:
Cosmetics and food & beverage segments split procurement between natural and synthetic grades based on label claim requirements, while pharmaceuticals impose the most stringent purity documentation burdens.
- Cosmetics:Fine fragrances, skincare, and personal care products requiring traceable supply chains with verified carbon footprints. Italian and French beauty houses now audit suppliers for fermentation energy sourcing or agricultural sustainability certification.
- Food & Beverage:Flavor enhancement across beverage, confectionery, and savory categories. United States and Indian food manufacturers specify food-grade valencene meeting FDA and FSSAI additive standards respectively.
- Pharmaceuticals:Excipient and active ingredient applications demanding batch-level substance identity verification.
- Agricultural Products:Crop protection adjuvants and botanical insecticide formulations seeking EPA-registered active ingredients.
Food & beverage generates the largest absolute volume. Cosmetics offers the most favorable margin structure for certified sustainable supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fragrance formulators in France and Italy consume valencene primarily for fine perfume applications, while food manufacturers in the United States and India drive volume through flavoring applications where synthetic grades dominate procurement specifications.
United States
Florida citrus processing clusters anchor natural valencene extraction capacity, with peel oil distillation infrastructure concentrated around Orlando and Tampa Bay metropolitan areas. EPA registration requirements govern insect repellent formulations, creating multi-year review cycles that delay market entry for novel applications. Food flavoring houses in New Jersey and California specify FEMA GRAS-listed synthetic valencene to eliminate seasonal supply volatility from citrus greening disease pressure.
France
Fine fragrance compounders in Paris and Grasse drive premium natural valencene demand through clean-label sourcing mandates requiring documented agricultural provenance. REACH compliance deadlines imposed by ECHA favor bio-identical molecules with complete safety dossiers over uncharacterized botanical extracts. Cosmetic formulators in the Île-de-France region now audit suppliers for verified carbon footprints and fermentation energy sourcing documentation.
Germany
Fragrance houses in Hamburg and Cologne specify liquid valencene formats for streamlined manufacturing workflows with immediate solubility in ethanol carriers. EU Green Deal guidelines under the European Commission shape biodegradable formulation mandates that valencene satisfies as a top-note citrus component. Industrial clusters along the Rhine corridor concentrate blending operations for personal care products distributed across continental Europe.
India
Domestic fragrance compounding growth in Maharashtra and Gujarat creates entry pathways for certified bio-derived terpenoid suppliers aligned with BIS standards. FSSAI food additive regulations shape permissible applications in beverage and confectionery markets where cost efficiency outweighs natural provenance claims. Personal care manufacturers in Mumbai and Ahmedabad expand procurement of traceable supply chains with sustainability certification infrastructure.
Japan
METI biomanufacturing incentives support precision fermentation scale-up partnerships targeting Asian cosmetic ingredient markets. Government funding programs enable technology transfer agreements between domestic formulators and microbial production specialists. Crop protection manufacturers in the Kanto region favor concentrate valencene formats for agricultural adjuvant applications requiring precise active ingredient metering.
Valencene Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fragrance houses and biotechnology platforms occupying distinct competitive positions. The market structure bifurcates between agricultural extractors leveraging Florida and Brazil citrus processing infrastructure and microbial production specialists deploying engineered yeast platforms. Strategic archetypes include vertically integrated flavor houses securing captive terpenoid supply, precision fermentation pure-plays reducing feedstock dependency, and regional peel oil traders serving commodity food flavoring markets. Dominant competitive moves encompass multi-year fermentation supply agreements and backward integration into bioprocess engineering capabilities.
Within the integrated flavor house tier, Givaudan and Firmenich exemplify archetypes combining biotechnology partnerships with established compounding networks. Evolva occupies a position among precision fermentation specialists focused on yeast-derived terpenoid platforms. These three entities represent contrasting strategic postures: Givaudan anchors supply security through integrated creation networks, Firmenich sustains yield improvements through deep biotechnology partnerships, and Evolva reduces agricultural feedstock exposure through microbial production specialization.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| International Flavors & Fragrances |
| Symrise |
| Sensient Technologies Corporation |
| Evolva |
| Isobionics |
| Citrus World |
| Florida Chemical Company |
| Others |
Value Network & Pricing Analysis
REACH substance registration mandates gate both supplier qualification and price differentiation simultaneously, as European fragrance houses now demand batch-level documentation that only characterized bio-identical molecules or certified natural extracts can satisfy. This regulatory filter concentrates procurement relationships with vertically integrated producers capable of delivering verified carbon footprints and complete safety dossiers.
Pricing Analysis
Long-term offtake agreements dominate procurement between fragrance houses and fermentation specialists, locking in volume commitments that insulate against citrus greening disease volatility. Three-tier pricing structure across premium natural, certified bio-identical, and commodity synthetic grades separates French fine fragrance compounders from United States flavor manufacturers and agricultural formulators. Cost compression in synthetic grades is intensifying as engineered yeast platforms achieve commercial scale, while natural valencene maintains margin resilience through scarcity positioning. Food flavoring houses in New Jersey exhibit highest price sensitivity, whereas Parisian cosmetic formulators prioritize provenance documentation over unit cost.
Supply Chain Analysis
Florida and Brazil anchor natural valencene extraction through citrus peel oil distillation infrastructure concentrated around Orlando, Tampa Bay, and São Paulo processing clusters. Microbial production draws from engineered yeast strains, agricultural feedstock sugars, and downstream purification systems. Single-source vulnerability runs through Florida's concentrated orange processing capacity, where citrus greening disease threatens peel oil availability. Distribution runs through fragrance house compounding networks in France and Germany, biotechnology platform direct supply agreements, and regional peel oil traders serving commodity food markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Valencene procurement is shifting toward fermentation-derived supply agreements with attached technical service layers, as fragrance houses seek strain optimization support and regulatory documentation services that outpace raw ingredient margins.
For Market Incumbents: Consolidate biotechnology partnerships through multi-year fermentation supply agreements that preempt competitor access to engineered yeast platforms. Deepen backward integration into bioprocess engineering capabilities to capture yield improvement value that commodity peel oil traders cannot replicate. Anchor position through captive supply of characterized bio-identical molecules with complete REACH dossiers. For New Entrants and Emerging Players: FEMA GRAS certification fast-track offers entry pathway into United States food flavoring markets where synthetic valencene demand concentrates. Target agricultural adjuvant applications in Japan under METI biomanufacturing incentives, where concentrate formats command premium positioning. Lead with precision fermentation purity advantages over natural extract variability to differentiate from established citrus processors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation specialists holding commercial-scale bioreactor infrastructure but lacking fragrance house distribution relationships. Five-to-ten year viability hinges on microbial production cost curves falling below cold-pressed orange oil extraction economics. Watch EPA registration timelines for insect repellent applications as inflection indicator for agricultural adjuvant revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Engineered yeast platforms reduce dependency on Florida citrus greening-exposed peel oil supply. |
| REACH Compliance Investment | Complete substance dossiers unlock European fragrance house procurement specifications. |
| Backward Integration into Strain Development | In-house bioprocess engineering captures yield improvement value from microbial terpenoid synthesis. |
| Long-Term Supply Agreements | Multi-year contracts with Givaudan and Firmenich anchor revenue visibility against agricultural volatility. |
| Agricultural Adjuvant Registration | EPA clearance for insect repellent applications opens crop protection formulation partnerships. |
Research Methodology
A spread of perspectives from fragrance house procurement directors, biotechnology platform engineers, citrus processing plant managers, and regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ECHA substance registration databases, FDA GRAS notice filings, FEMA flavor ingredient lists, and customs trade records. Bottom-up volume estimates from individual production facilities triangulated against top-down market sizing from downstream consumption patterns.
Segmentation dimensions modeled include natural versus synthetic versus blended grade tiers, fragrance versus food flavoring versus agricultural adjuvant applications, liquid versus concentrate versus powder formats, and cosmetics versus food and beverage versus pharmaceutical market segments. CAGRs were derived from fitted growth curves across the projection horizon, incorporating strain yield improvement trajectories, REACH compliance deadline impacts, and citrus greening disease progression scenarios.
Underlying assumptions cover engineered yeast platform commercialization timelines, regulatory clearance pathways, and agricultural disease progression, with deviation risk concentrated in EPA registration delays and fermentation scale-up technical failures. Recalibration cycles align with material shifts in strain optimization breakthroughs, regulatory framework changes, and citrus crop yield disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Africa Food Flavor Market