
 ASEAN Satellite Communications Market | 2026-2036
ASEAN Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Satellite Communications Market Insights
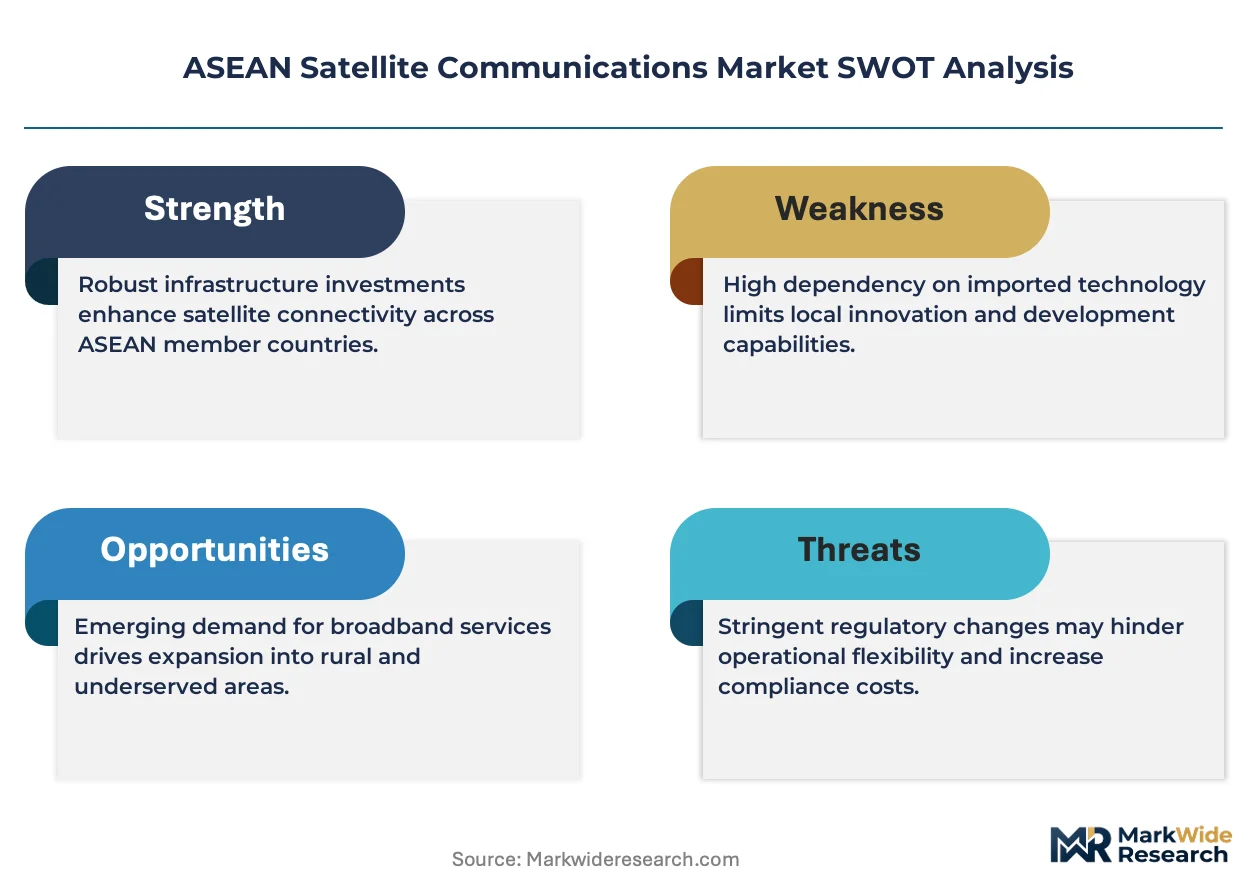
Ka-band capacity is repositioning C-band economics across ASEAN maritime and aero routes, compressing cost-per-bit benchmarks that governed legacy fleet contracts. Thaicom Public Company Limited leverages its orbital slots over Southeast Asia to anchor government backhaul programs in Thailand and neighboring states. SES S.A. sustains a multi-orbit strategy that competes directly with emerging LEO providers across Indonesian island chains. Mu Space and Advanced Technology Company specializes in domestic ground infrastructure, extending local manufacturing presence that insulates against import tariff volatility.
ASEAN satellite communications encompasses space-based and terrestrial-linked systems transmitting voice, video, and data across geostationary, medium earth, and low earth orbital altitudes, typically operating in Ku-band, Ka-band, and C-band frequency allocations with throughput rates scaling from megabits to gigabits per second depending on payload configuration and ground terminal sophistication. Television Broadcasting applications within the Application segment retain the largest revenue share due to entrenched content distribution agreements, while Internet Access exhibits the fastest structural expansion as national broadband plans in Indonesia and the Philippines prioritize satellite backhaul for last-mile coverage. Geostationary technology still dominates installed capacity, though Hybrid architectures combining GEO anchorage with LEO relay are capturing margin pools from latency-sensitive enterprise and defense clients.
Thailand's National Broadcasting and Telecommunications Commission, Indonesia's Ministry of Communication and Informatics, and the Philippines' National Telecommunications Commission each enforce spectrum allocation frameworks that determine which orbital services can operate in national waters and airspace, with licensing timelines directly shaping operator market entry speed. Malaysia's Communications and Multimedia Commission imposes local landing requirements that force foreign satellite operators to establish domestic ground gateway partnerships. Stakeholders must monitor evolving national security designations for space infrastructure as ASEAN states draft sovereign satellite procurement policies that could restrict vendor eligibility.
Market Dynamics
Ka-band frequency adoption is compressing legacy C-band economics across ASEAN maritime corridors, forcing fleet operators to renegotiate connectivity contracts as Low Earth Orbit constellations enter regional licensing frameworks.
Growth Catalysts
- Indonesia's Palapa Ring backbone:National broadband initiatives mandate satellite backhaul for outer island provinces, creating anchor tenancy for geostationary capacity.
- Thailand's NBTC spectrum reforms:Streamlined licensing timelines accelerate orbital slot utilization for domestic broadcast and government networks.
- LEO-GEO hybrid architectures:Latency-sensitive defense and enterprise clients are migrating to multi-orbit configurations that combine geostationary anchorage with low-altitude relay.
Market Restraints
- Ground terminal cost volatility:Import tariffs on phased-array antennas fluctuate with trade policy shifts, compressing equipment margins for domestic distributors.
- Singapore gateway concentration:Regional landing rights cluster through limited terrestrial fiber interconnection points, creating single-point vulnerability for traffic aggregation.
- C-band spectrum reallocation:Indonesia's Ministry of Communication and Informatics is compressing legacy frequency assignments for terrestrial 5G deployment, displacing incumbent satellite operators.
Strategic Opportunities
- Philippines archipelagic gaps:Over seven thousand islands lack economical fiber reach, positioning satellite for last-mile dominance in Visayas and Mindanao.
- Vietnam's maritime surveillance mandate:Coastal monitoring programs require persistent orbital coverage for fisheries enforcement and territorial awareness.
- Optical inter-satellite links:Laser-based relay between medium and low earth orbits is eliminating ground gateway dependencies for cross-border traffic.
Industry Challenges
- RF engineer scarcity:Specialized talent for Ka-band payload optimization and interference coordination remains concentrated in legacy C-band expertise pools.
- Legacy VSAT integration:Maritime fleets operating hybrid fleets face protocol fragmentation between geostationary terminals and flat-panel LEO arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Satellite Communications Market |
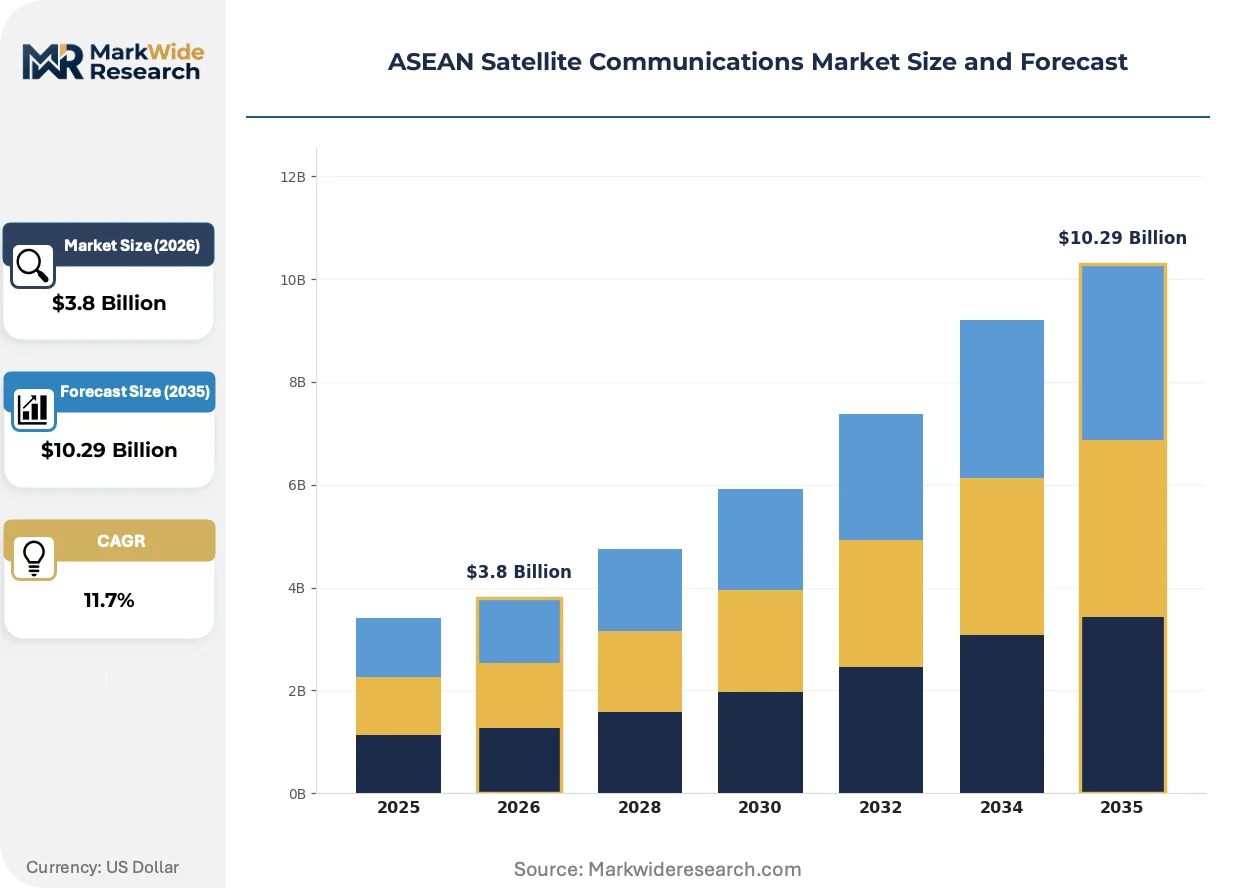
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite, Ground Equipment, Transponder Services, Network Services End User: Government, Telecommunications, Broadcasting, Maritime Application: Television Broadcasting, Internet Access, Defense, Remote Sensing Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Hybrid |
| Companies Covered | Viasat Inc., Thaicom Public Company Limited, Mu Space and Advanced Technology Company, Intelsat, SES S.A., Inmarsat Global Limited, L3Harris Technologies Inc, AsiaSat, Lockheed Martin, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Satellite Communications Market Trends and Innovations
Orbital altitude diversification is fragmenting procurement patterns as ASEAN national regulators issue divergent licensing frameworks for geostationary, medium, and low earth systems.
Software-defined payloads are integrating frequency agility and beam-hopping capabilities into geostationary satellites, allowing operators to reallocate capacity between maritime corridors and aero routes within minutes. Indonesian and Vietnamese fleet managers are adopting these flexible configurations to match seasonal fishing patterns. This dynamic resource allocation is integrating spot-beam economics into legacy wide-beam contract structures, compressing per-bit pricing benchmarks.
Malaysia's Communications and Multimedia Commission local landing requirements are mandating domestic gateway partnerships for all foreign orbital services entering national waters. Operators must establish terrestrial fiber handoff points within Malaysian territory, adding infrastructure capex but creating captive revenue streams for domestic telecom partners. The policy most affects Ku-band broadcast distributors serving peninsular Malaysia.
Maritime connectivity procurement is consolidating through fleet-wide managed service contracts rather than per-vessel bandwidth leases. Shipping lines based in Singapore and Bangkok are unbundling hardware ownership from operational expenditure, transferring terminal lifecycle risk to satellite operators. This preference shift is most pronounced in container segments operating Indonesia-Japan routes.
ASEAN Satellite Communications Market Segmentation
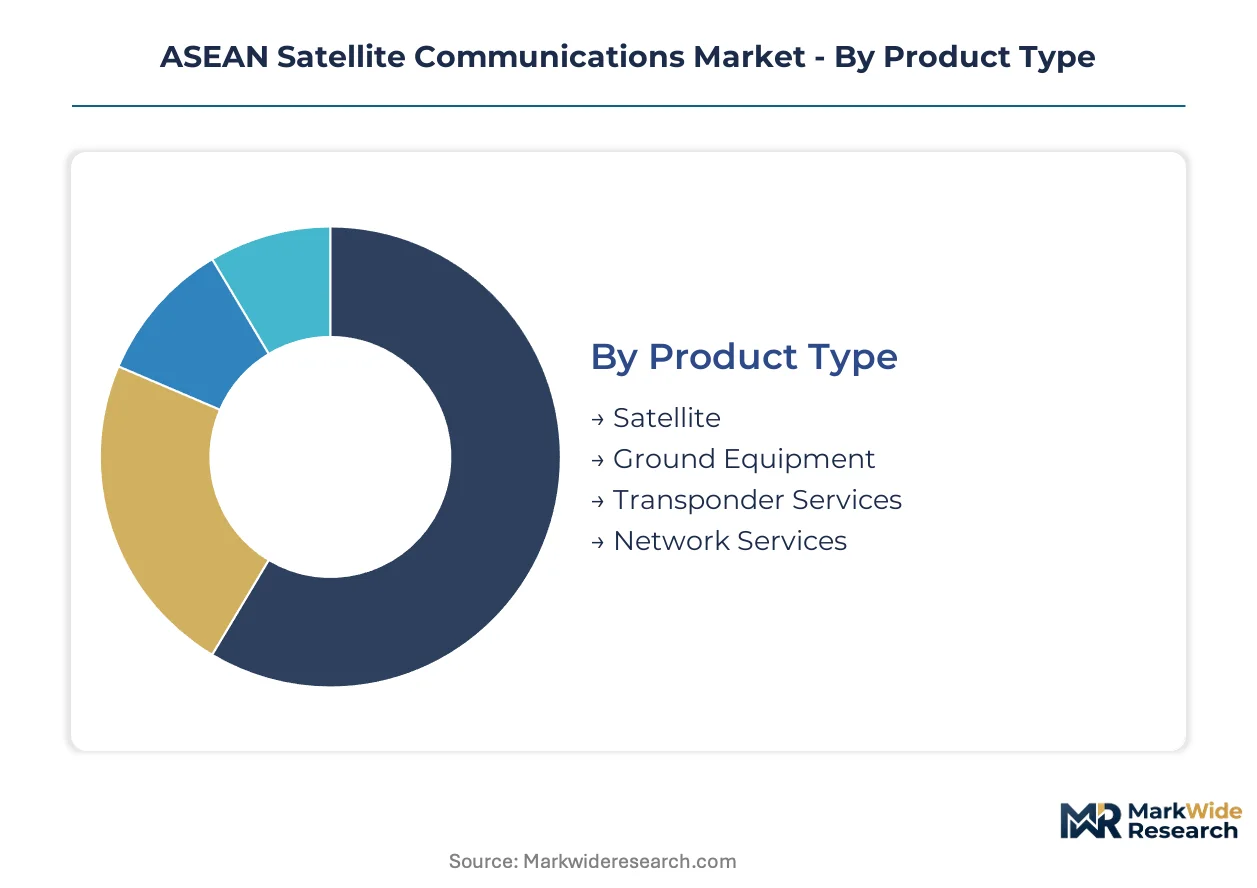
Segmentation reveals how procurement priorities diverge across ASEAN states. National broadband mandates, maritime surveillance programs, and spectrum reallocation policies each favor distinct technology configurations and service models.
Product Type:
Volume deployment concentrates in standardized hardware and bulk capacity leases. Premium margins attach to integrated network management and sovereign infrastructure programs.
- Satellite:Space-based assets deliver broadcast and broadband payloads across Ku-band, Ka-band, and C-band frequencies. Indonesia's Palapa Ring program anchors demand for geostationary platforms serving outer island provinces where terrestrial fiber cannot reach.
- Transponder Services:Leased orbital capacity provides flexible bandwidth procurement without capital-intensive satellite ownership. Thai government backhaul contracts and Philippine archipelagic connectivity gaps sustain demand for transparent and bent-pipe transponder configurations.
- Ground Equipment:Terminal hardware including antennas, modems, and RF chains enables signal transmission and reception. Vietnam's coastal monitoring mandates drive phased-array installations for persistent maritime surveillance.
- Network Services:Managed connectivity bundles hardware, bandwidth, and operational support under single-contract structures. Singapore-based shipping lines increasingly prefer fleet-wide service agreements over per-vessel procurement.
Mature deployment sits with Transponder Services. Newer deployment is concentrated in Network Services.
End User:
Government procurement emphasizes sovereign control and security clearances. Commercial segments prioritize cost-per-bit optimization and service flexibility.
- Telecommunications:Mobile network operators deploy satellite backhaul for rural cell towers and emergency restoration. Indonesian and Philippine carriers expand coverage into archipelagic zones beyond economical fiber reach.
- Maritime:Shipping lines, fishing fleets, and offshore platforms require continuous connectivity across international waters. Container operators on Indonesia-Japan routes are consolidating procurement through fleet-wide managed service contracts.
- Government:Defense ministries and civilian agencies mandate encrypted, sovereign-controlled orbital capacity. Thailand's NBTC spectrum reforms accelerate domestic broadcast and secure network licensing timelines.
- Broadcasting:Content distributors maintain entrenched agreements for direct-to-home television delivery. Ku-band satellite capacity retains dominance for free-to-air and subscription channels across peninsular Malaysia.
Broadcasting maintains the largest installed base. Maritime exhibits the steepest expansion trajectory as fleet digitization accelerates.
Application:
Latency tolerance and throughput requirements determine technology selection. Real-time applications favor low-altitude constellations while broadcast distribution tolerates geostationary delay.
- Television Broadcasting:Linear content distribution via direct-to-home and cable headend feeds retains substantial revenue concentration. Entrenched licensing agreements and established receiver penetration sustain C-band and Ku-band deployment across ASEAN households.
- Internet Access:Broadband backhaul for unserved communities and enterprise connectivity climbs fastest as national digital inclusion programs expand. Indonesia's Ministry of Communication and Informatics prioritizes satellite last-mile coverage for thousands of uneconomical islands.
- Defense:Military communications, intelligence dissemination, and command-and-control networks demand hardened, interference-resistant links. Vietnam's maritime surveillance programs require persistent orbital coverage for fisheries enforcement and territorial awareness.
- Remote Sensing:Earth observation payloads support agriculture, disaster response, and environmental monitoring applications. Optical and synthetic aperture radar instruments gain traction for ASEAN flood prediction and crop assessment.
Television Broadcasting anchors current capacity utilization. Internet Access is gaining share fastest as broadband penetration targets intensify.
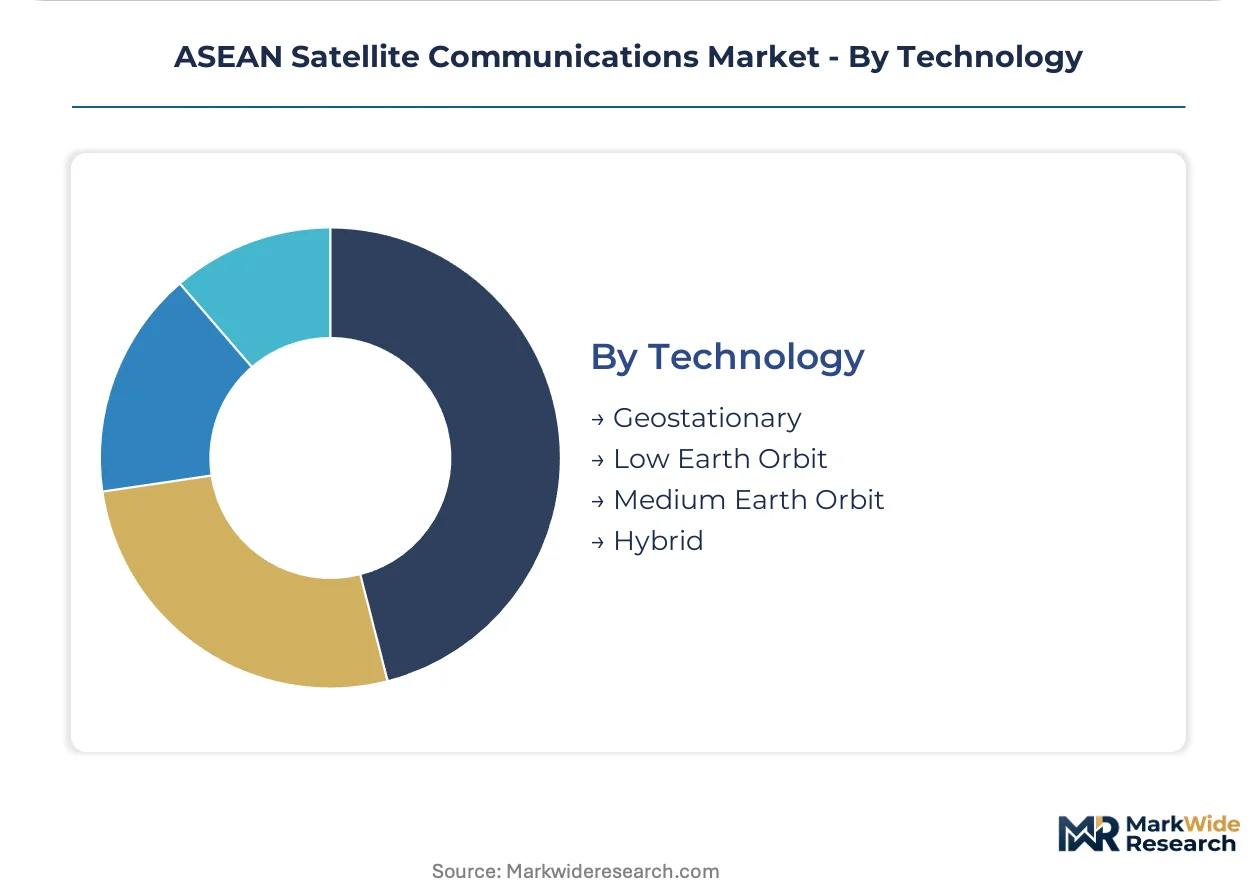
Technology:
Orbital altitude selection trades coverage persistence against latency performance. Hybrid architectures capture margin from clients requiring both attributes.
- Geostationary:Fixed orbital position at 35,786 kilometers enables continuous regional coverage with minimal ground tracking complexity. Thaicom and regional operators leverage established slots for broadcast anchorage and government backhaul programs.
- Hybrid:Combined GEO anchorage with LEO or MEO relay delivers low-latency performance alongside persistent coverage. Latency-sensitive enterprise and defense clients in Singapore and Bangkok migrate to multi-orbit configurations for competitive differentiation.
- Low Earth Orbit:Constellations below 2,000 kilometers offer sub-50 millisecond latency for real-time applications. Emerging providers compete directly with legacy operators across Indonesian island chains as licensing frameworks mature.
- Medium Earth Orbit:Intermediate altitude systems balance coverage footprint with propagation delay. Limited regional deployment concentrates on specialized navigation and timing augmentation services.
Geostationary platforms retain the deepest installed base. Hybrid architectures are expanding most quickly as procurement patterns fragment across latency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's archipelagic connectivity gap concentrates satellite demand across thousands of uneconomical islands. Thailand's spectrum reforms and Vietnam's maritime surveillance mandates reshape procurement patterns. The Philippines' broadband initiatives and Singapore's gateway infrastructure anchor regional capacity deployment.
Indonesia
Palapa Ring backbone mandates satellite backhaul for outer island provinces where terrestrial fiber cannot reach. The Ministry of Communication and Informatics compresses legacy C-band assignments for 5G deployment. Jakarta anchors government network procurement while Surabaya clusters maritime fleet management operations.
Thailand
National Broadcasting and Telecommunications Commission reforms accelerate orbital slot utilization for domestic broadcast networks. Streamlined licensing timelines benefit government backhaul and secure communications programs. Bangkok concentrates regional headquarters activity for operators serving Mekong sub-region contracts.
Vietnam
Maritime surveillance mandates drive persistent orbital coverage for fisheries enforcement and territorial awareness. Coastal monitoring programs require phased-array terminal installations at Da Nang and Hai Phong ports. Ho Chi Minh City clusters defense procurement coordination for sovereign satellite capacity.
Philippines
Over seven thousand islands lack economical fiber reach, positioning satellite for last-mile dominance in Visayas and Mindanao. The National Telecommunications Commission governs spectrum allocation for archipelagic connectivity gaps. Manila anchors broadcast distribution agreements while Cebu clusters maritime fleet digitization.
Singapore
Regional landing rights concentrate terrestrial fiber interconnection through limited gateway points, creating traffic aggregation vulnerability. The Maritime and Port Authority governs vessel connectivity standards for international shipping lanes. The city-state hosts managed service contract negotiations for Indonesia-Japan container routes.
ASEAN Satellite Communications Market Competitive Landscape
Capacity expansion dominates the current landscape as operators deploy hybrid GEO-LEO architectures to capture latency-sensitive contracts. The vendor base stratifies across established geostationary incumbents, emerging constellation providers, and domestic ground infrastructure specialists. Three archetypes define competitive positioning: orbital slot holders leveraging regulatory anchorage, multi-orbit strategists combining altitude layers, and local gateway operators exploiting landing right requirements. M&A activity and strategic partnerships between satellite operators and maritime fleet managers represent the dominant competitive moves reshaping contract structures.
Among established orbital slot holders, Thaicom Public Company Limited exemplifies the regulatory-anchored archetype through its Southeast Asian positioning. SES S.A. occupies the multi-orbit tier, while Mu Space and Advanced Technology Company represents domestic infrastructure specialization. These three entities illustrate how competitive positioning fragments across orbital altitude strategy, geographic licensing advantage, and ground segment control.
| Leading Market Players |
|---|
| Viasat Inc. |
| Thaicom Public Company Limited |
| Mu Space and Advanced Technology Company |
| Intelsat |
| SES S.A. |
| Inmarsat Global Limited |
| L3Harris Technologies Inc |
| AsiaSat |
| Lockheed Martin |
| Others |
Pricing and Supply Chain Analysis
Ka-band payload migration from legacy C-band architectures is compressing transponder lease rates while concentrating manufacturing of phased-array terminals in South Korea and Taiwan. This technology transition simultaneously erodes geostationary pricing power and reshapes component sourcing patterns as flat-panel antenna demand outstrips regional assembly capacity.
Pricing Analysis
Volume-vs-margin splits sharply between standardized transponder leases and integrated managed service bundles. Three-tier pricing structure across premium, standard, and economy levels separates latency-sensitive defense contracts from bulk maritime capacity and basic broadcast backhaul. Price differentiation hinges on orbital altitude selection and ground terminal sophistication tiers. Cost compression in C-band backhaul is intensifying because Indonesia's spectrum reallocation for 5G deployment displaces incumbent operators. Maritime fleet managers exhibit highest price sensitivity, while defense ministries prioritize sovereign control over per-bit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for high-frequency RF chip fabrication and South Korea for phased-array antenna substrate manufacturing. Component sourcing draws from Japan for precision optics, the United States for radiation-hardened processors, and China for rare earth magnet assemblies. Tariff exposure on ground terminal imports fluctuates with ASEAN trade policy shifts, compressing equipment margins for domestic distributors. Distribution runs through Singapore gateway facilities for regional traffic aggregation, with Bangkok and Jakarta serving secondary interconnection points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN satellite communications sits in a technology-transition phase as Low Earth Orbit constellations displace geostationary anchorage for latency-sensitive applications. Procurement patterns are fragmenting across orbital altitude strategies while national regulators issue divergent licensing frameworks.
For Market Incumbents: Deepen sovereign infrastructure partnerships with Thailand's NBTC and Indonesia's Ministry of Communication and Informatics to secure orbital slot anchorage against emerging LEO providers. Invest in Ka-band payload optimization and software-defined beam-hopping capabilities to match seasonal demand patterns in maritime corridors. Control domestic gateway partnerships in Malaysia and Vietnam to exploit local landing requirements that foreign operators cannot bypass. For New Entrants and Emerging Players: Launch via fleet-wide managed service contracts rather than per-vessel bandwidth leases to capture Singapore-based shipping lines consolidating procurement. Target Philippine archipelagic gaps in Visayas and Mindanao where over seven thousand islands lack economical fiber reach. Pursue optical inter-satellite link deployments to eliminate ground gateway dependencies for cross-border traffic relay. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multi-orbit operators seeking domestic gateway footholds and maritime fleet management platforms. Long-term viability favors vertically integrated players controlling both orbital capacity and ground segment manufacturing. Watch for Indonesia's C-band spectrum reallocation timeline as the inflection signal for geostationary asset impairment risk.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Architecture Deployment | Hybrid GEO-LEO configurations capture latency-sensitive defense contracts from Singapore and Bangkok. |
| Domestic Gateway Partnership | Malaysia's local landing requirements create captive revenue streams for terrestrial fiber handoff operators. |
| Software-Defined Payload Integration | Beam-hopping capabilities allow Indonesian fleet managers to match seasonal fishing pattern shifts. |
| Maritime Managed Service Contract | Fleet-wide agreements transfer terminal lifecycle risk from Singapore shipping lines to satellite operators. |
| Sovereign Infrastructure Procurement | Vietnam's coastal monitoring mandates drive phased-array installations at Da Nang and Hai Phong ports. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with satellite fleet procurement managers, RF engineering directors, maritime connectivity specialists, and national spectrum regulators combined with bottom-up and top-down triangulation. Secondary sources included NBTC licensing databases, Indonesia's Ministry of Communication and Informatics spectrum allocation records, ASEAN customs import statistics for ground terminal equipment, and operator orbital slot registration filings with the International Telecommunication Union.
Granularity-level modeling distinguished geostationary, hybrid, and low earth orbit technology configurations across Indonesia, Thailand, Vietnam, Philippines, Singapore, and Malaysia. Segmentation dimensions included product type, end user, application, and orbital altitude strategy. CAGRs were derived from capacity deployment trajectories and procurement pattern shifts across the analysis window. Industry-specific forecast inputs incorporated Palapa Ring backbone mandates, maritime surveillance program timelines, and spectrum reallocation policy developments.
Spectrum reallocation acceleration, LEO constellation licensing delays, and ground terminal import tariff volatility are the dominant revision risks for forecast trajectories. Forecasts reflect documented assumptions about national broadband penetration targets and maritime fleet digitization rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Military Satellite Market
Satellite
Europe Satellite IoT Market
Satellite
Europe Satellite Bus Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Satellite Signal Meter Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Tactical Satellite Market
Satellite
Japan Satellite Communication Market
Satellite
UAE Satellite Imagery Services Market
Satellite
South Korea Satellite Communication Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Low-Cost Satellite Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Satellite Gateway Market
Satellite
Asia-Pacific Remote Sensing Satellites Market