
 Global Float Level Switches Market | 2026-2036
Global Float Level Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Float Level Switches Market Intelligence
IEC 61508 functional safety certification is unwinding competitive access across the Global Float Level Switches Market, raising engineering barriers for new entrants. Magnetrol (AMETEK) leverages its SIL-rated product portfolio to anchor positions in oilfield services. Emerson Electric sustains R&D intensity across ultrasonic and capacitive sensing platforms. Endress+Hauser dominates European specification channels through factory-calibrated instrumentation.
Float level switches detect liquid surface position through buoyant magnetic or optical mechanisms, translating mechanical displacement into electrical switching signals at defined elevation thresholds. Reed switch variants employ hermetically sealed contacts rated for temperatures exceeding 150°C, serving chemical tank farms and boiler feedwater systems. Magnetic float switches retain the largest installed base across water treatment and utilities, while ultrasonic float switches capture the fastest expansion in food and beverage applications where hygienic clamp fittings prevent contamination. Capacitive technologies occupy premium niches in aggressive media where mechanical wear accelerates failure.
EPA effluent regulations in the United States mandate redundant level control in wastewater discharge systems, directly expanding specification demand for dual-float configurations. REACH substance restrictions in Europe constrain elastomer and coating selections for wetted components, forcing reformulation cycles among switch manufacturers. FDA 21 CFR Part 117 sanitary design rules govern food and beverage installations, requiring crevice-free construction and clean-in-place compatibility. Stakeholders must monitor how IEC, EPA, and FDA standard revisions converge on material traceability and predictive maintenance integration.
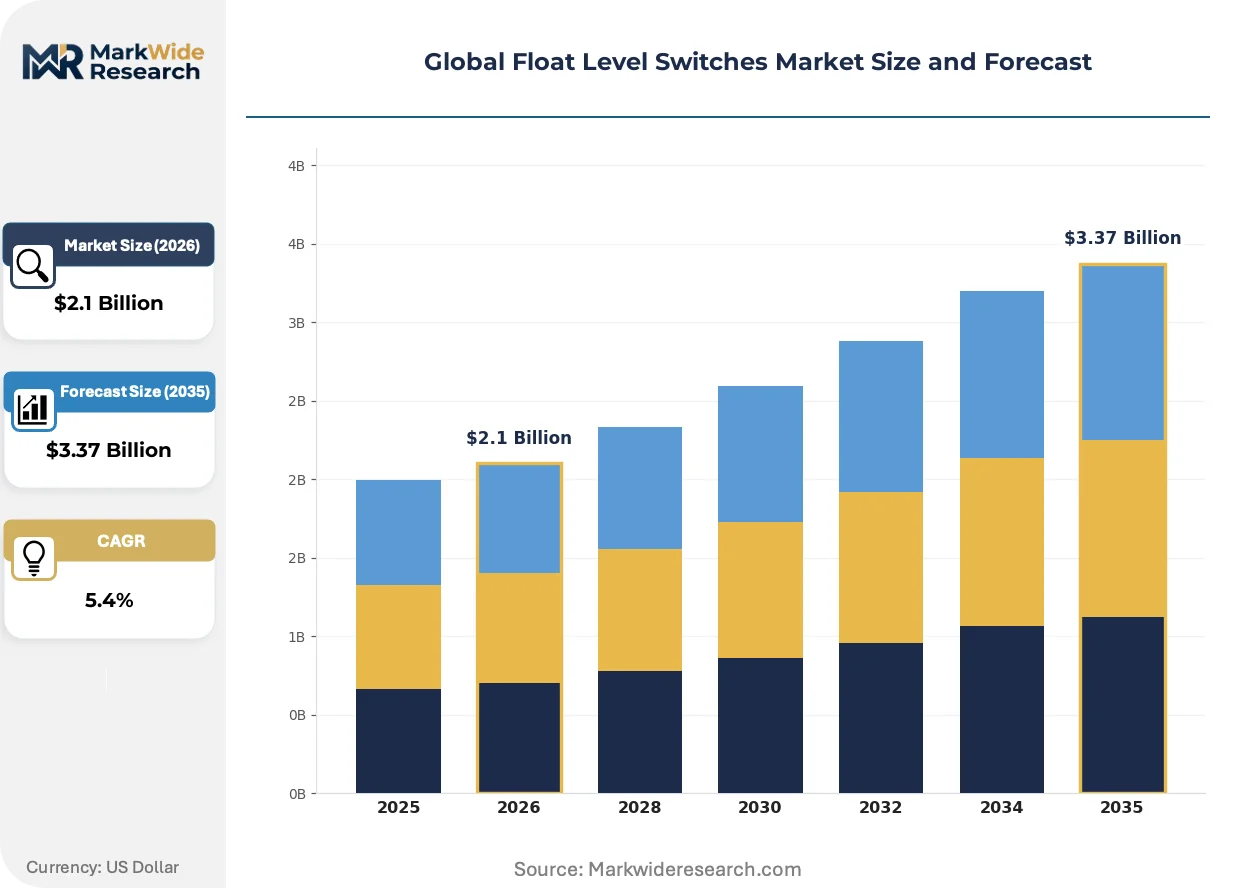
Market Dynamics
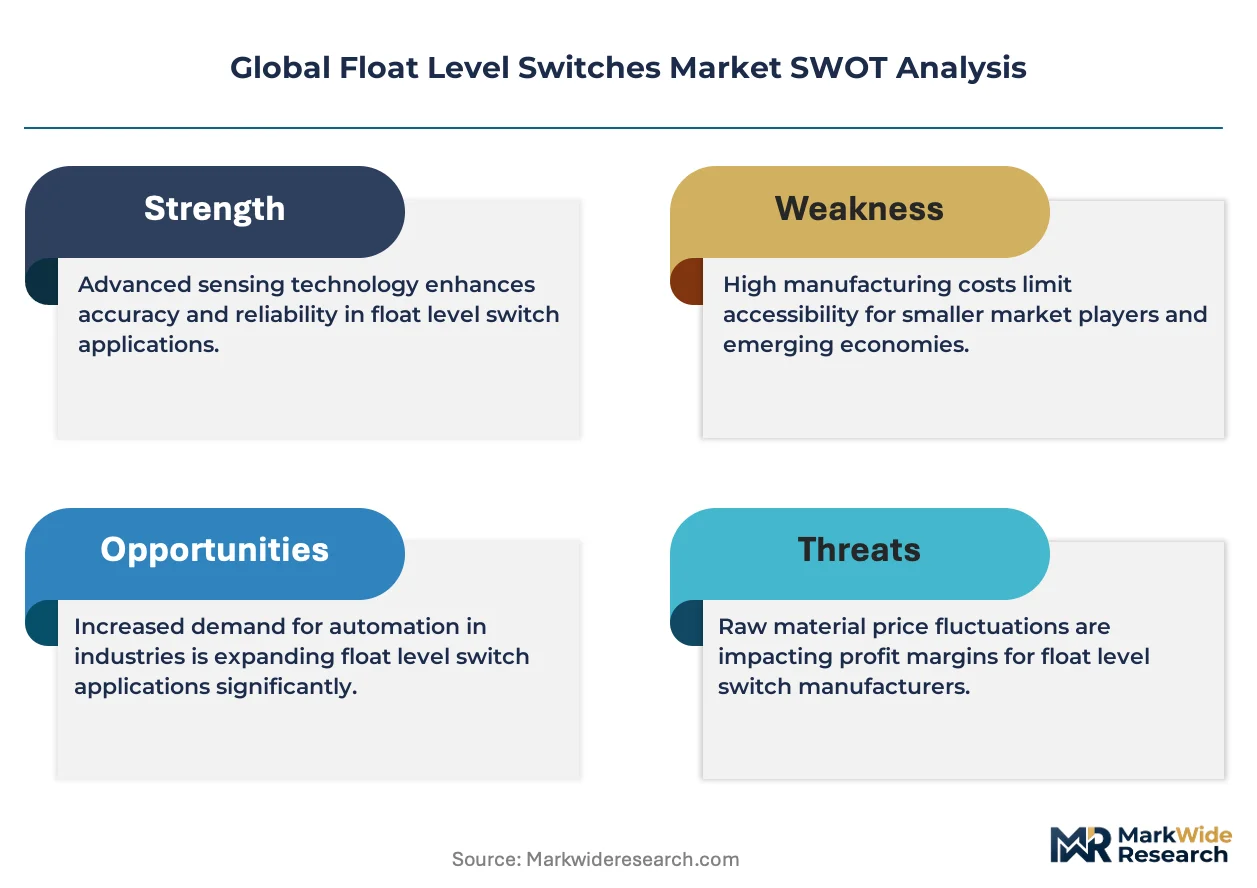
IEC 61508 SIL certification requirements are compressing vendor participation in process industries, concentrating specification authority among instrument manufacturers with embedded safety engineering capabilities.
Growth Catalysts
- EPA effluent mandates:Redundant level control requirements in US wastewater discharge systems directly expand dual-float procurement specifications for municipal utilities.
- Food and beverage hygiene protocols:FDA 21 CFR Part 117 sanitary design rules accelerate ultrasonic float switch adoption with crevice-free clamp fittings.
- German chemical processing clusters:Specification-grade procurement concentrated in Ludwigshafen and Leverkusen drives demand for magnetically coupled reed switch variants.
Market Restraints
- Rare earth magnet supply concentration:Neodymium price volatility and Chinese export quota restrictions compress margin stability for magnetic float switch producers.
- REACH substance restrictions:ECHA reformulation mandates for wetted elastomers force multi-year material qualification cycles, delaying new product introductions.
- Capacitive sensing substitution:Non-contact technologies eliminate mechanical wear in aggressive chemical media, displacing traditional float mechanisms in premium applications.
Strategic Opportunities
- Indian water infrastructure:Central Electricity Authority mandates for automated reservoir management create specification demand for electronic float switches in thermal power cooling systems.
- Predictive maintenance integration:IO-Link digital communication protocols enable condition monitoring data streams, opening aftermarket service revenue for switch manufacturers.
- Brazilian bioethanol expansion:ANVISA sanitary requirements in sugar-alcohol processing drive hygienic float switch specification in fermentation tank farms.
Industry Challenges
- SIL certification engineering scarcity:Functional safety assessment expertise concentrates in TÜV Rheinland and SGS certification bodies, creating bottlenecks for mid-tier vendors seeking IEC 61508 compliance.
- Legacy 4-20mA integration friction:Digital-native float switches face retrofit complexity in brownfield installations with analog control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Float Level Switches Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Float Switch, Reed Switch, Optical Float Switch, Ultrasonic Float Switch, Capacitive Float Switch Technology: Mechanical, Electronic, Pneumatic, Ultrasonic, Resistive Application: Water Treatment, Chemical Processing, Food & Beverage, Oilfield Services, Pulp & Paper End User Industry: Manufacturing Plants, Utilities, Marine Operations, Waste Management, Power Generation |
| Companies Covered | Honeywell, Magnetrol (AMETEK), Emerson Electric, Baumer, Gems Sensors, Endress+Hauser, Siemens, Schneider Electric, ABB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Float Level Switches Market Strategic Shifts & Innovations
Sensor fusion and edge computing capabilities are redefining float switch value propositions, shifting competition from hardware reliability toward data-enabled process optimization.
Magnetostrictive position sensing is miniaturizing into compact float switch housings, enabling sub-millimeter resolution in boiler drum level applications. Power generation utilities in Japan and South Korea are specifying these hybrid devices for critical feedwater control. The technology is miniaturizing cost structures that previously required separate continuous level transmitters alongside discrete switches.
REACH substance restrictions are forcing reformulation of FKM and EPDM wetted seals across European supply chains. Chemical compatibility databases must now document full material traceability from compound suppliers. German tank farm operators are accelerating qualification of perfluoroelastomer alternatives to maintain emissions compliance.
Buyer consolidation among multinational water utilities is compressing vendor lists and unbundling aftermarket service contracts from initial hardware procurement. Suez and Veolia framework agreements now specify ten-year spare parts availability as a mandatory bid criterion. This pattern is most visible in French and UK municipal water privatization markets.
Global Float Level Switches Market Segmentation
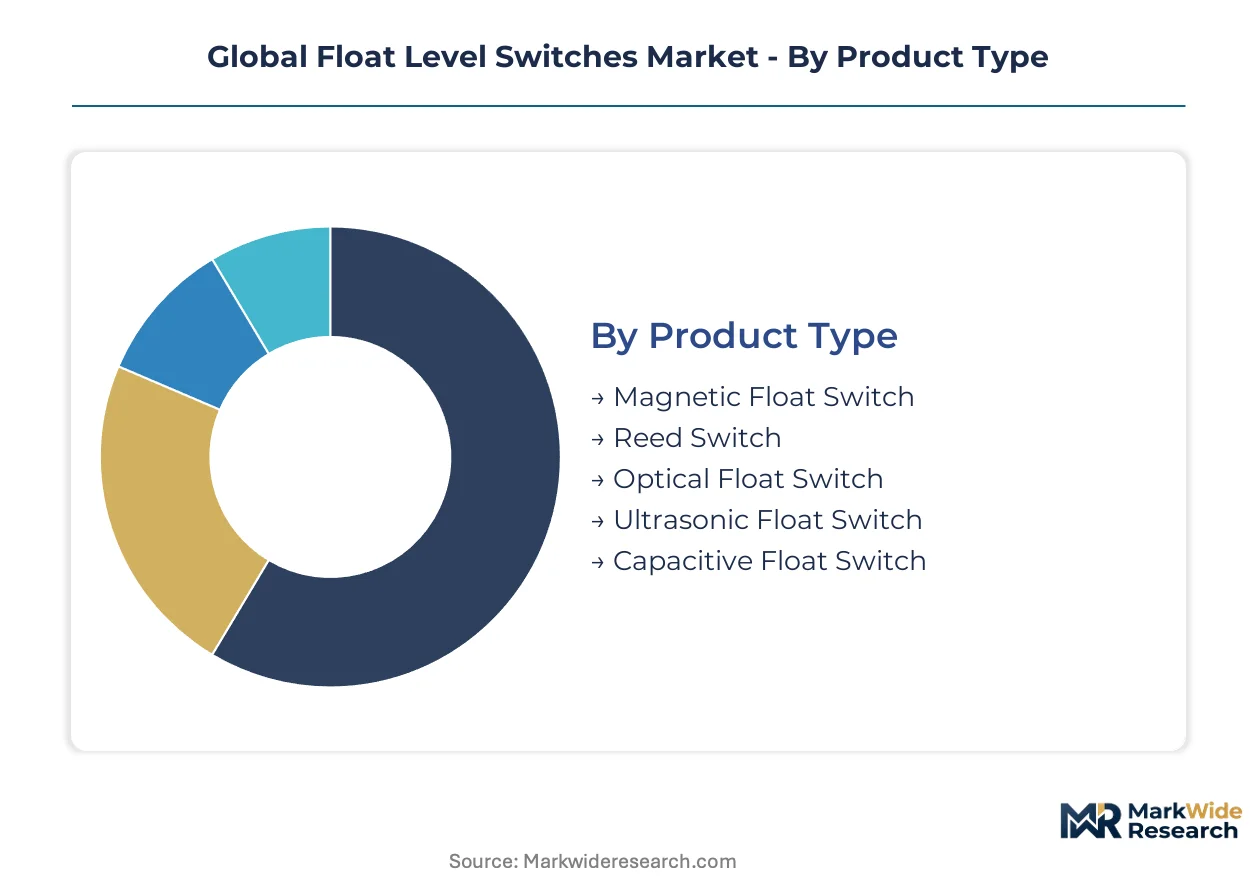
Float level switch procurement patterns diverge sharply across product architectures and end-use environments. Specification-grade buyers in chemical processing and water utilities drive tiered demand structures that reward certified performance over commodity pricing.
Product Type:
Magnetic float switches dominate domestic installation bases across municipal water systems, while optical and ultrasonic variants concentrate in export-led pharmaceutical and semiconductor fabrication markets.
- Magnetic Float Switch:Buoyant magnetic collars actuate hermetically sealed reed contacts as liquid levels rise. German chemical processing clusters in Ludwigshafen specify these for redundant tank farm monitoring under IEC 61508 SIL requirements.
- Reed Switch:Magnetically coupled dry reed elements provide snap-action electrical switching without mechanical wear. Japanese power utilities deploy these in boiler feedwater systems where temperature cycling exceeds 150°C.
- Optical Float Switch:Infrared LED and phototransistor pairs detect liquid presence through prism refraction changes. Semiconductor fabs in South Korea specify these for ultrapure chemical delivery.
- Ultrasonic Float Switch:Piezoelectric transducers emit high-frequency pulses to detect liquid surfaces without media contact. Food and beverage processors in Brazil adopt these for hygienic tank monitoring under ANVISA sanitary rules.
- Capacitive Float Switch:Electrode pairs measure dielectric constant changes between air and liquid. Aggressive chemical handlers in US Gulf Coast refineries specify these where mechanical floats corrode.
Magnetic float switches hold the largest share; momentum sits with ultrasonic variants expanding most quickly in hygienic processing applications.
Technology:
Cost tier stratification separates mature mechanical implementations from premium electronic platforms with embedded diagnostics and digital communication.
- Mechanical:Purely buoyant or displacer-actuated mechanisms without electrical amplification. Municipal utilities in India specify these for automated reservoir management in thermal power cooling systems.
- Electronic:Microprocessor-conditioned signals with programmable setpoints and fault diagnostics. European water treatment operators demand these for predictive maintenance integration via IO-Link protocols.
- Pneumatic:Air-logic switching for explosion-hazard environments where electrical ignition risks are prohibitive. Offshore oil platforms in the North Sea deploy these for ballast tank control.
- Ultrasonic:Time-of-flight measurement eliminating mechanical components in the measurement path. Pharmaceutical tank farms in Switzerland specify these for CIP/SIP compatibility.
- Resistive:Conductivity-based detection for conductive liquids with simple on-off output. Wastewater lift stations across US municipalities install these for cost-sensitive level alarm functions.
Mechanical technology retains the dominant installed base; electronic platforms are climbing the fastest as digitalization penetrates process industries.
Application:
Volume concentration in water infrastructure contrasts with margin-rich specialization in chemical and food processing segments.
- Water Treatment:Reservoir, clarifier, and filtration vessel level control for municipal and industrial water systems. EPA effluent mandates in the United States mandate redundant dual-float configurations in wastewater discharge systems.
- Chemical Processing:Aggressive media handling in tank farms, reactors, and storage vessels. REACH substance restrictions force reformulation of wetted elastomers across European supply chains.
- Food & Beverage:Hygienic tank level monitoring with crevice-free construction and clean-in-place compatibility. FDA 21 CFR Part 117 sanitary design rules govern fermentation and dairy processing installations.
- Oilfield Services:Separator, heater-treater, and produced water tank level control. SIL-rated specifications dominate offshore platform procurement in the Norwegian North Sea.
- Pulp & Paper:Black liquor, stock chest, and whitewater level management in fiber processing. Brazilian bioethanol expansion drives parallel demand in sugar-alcohol fermentation tanks.
Water treatment commands the greatest unit volume; food and beverage applications generate the steepest expansion trajectory on hygiene protocol tightening.
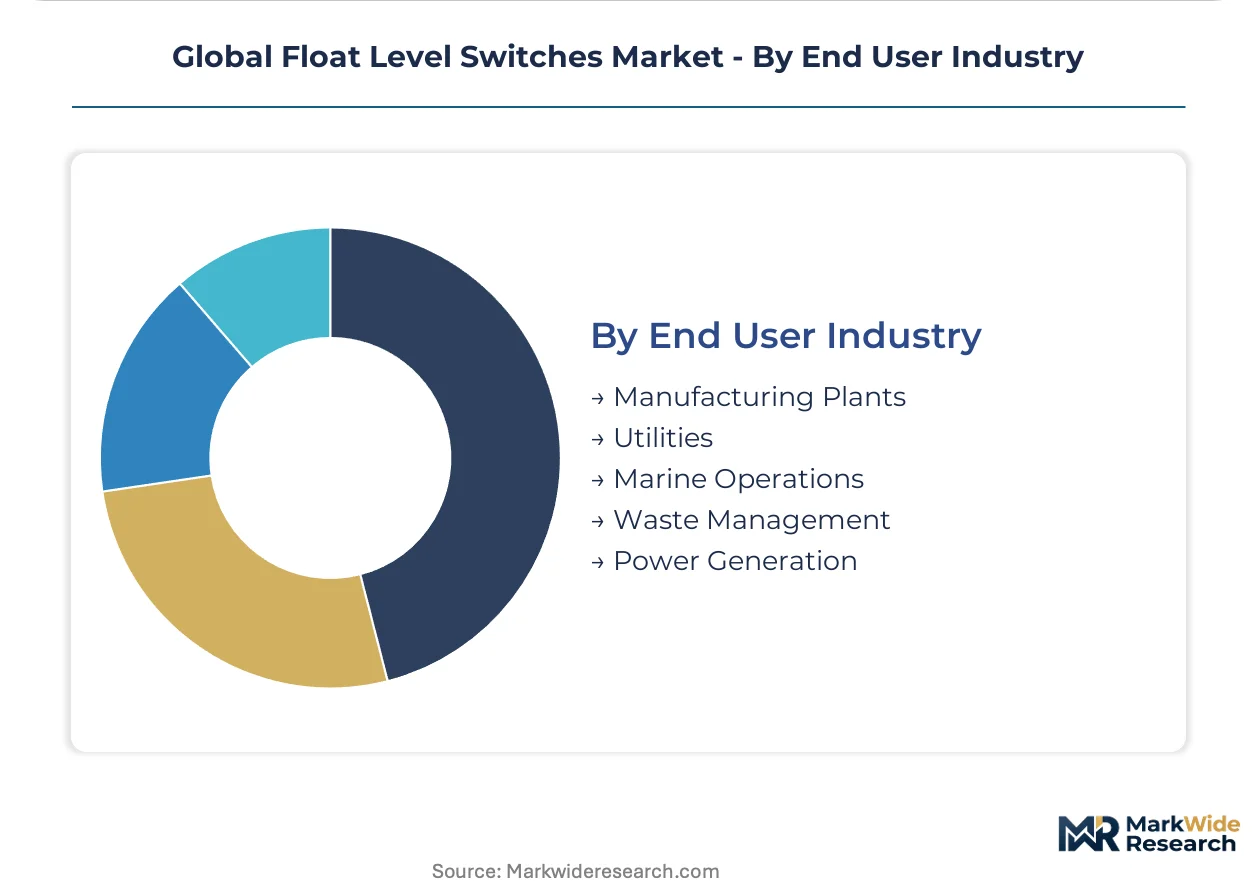
End User Industry:
Customer type determines procurement channel structure, with utilities favoring framework agreements and manufacturing plants emphasizing specification-grade qualification.
- Manufacturing Plants:Discrete and process manufacturing facilities with batch or continuous production level control. German automotive paint shops specify magnetostrictive hybrid switches for precise solvent tank monitoring.
- Utilities:Municipal water, wastewater, and district energy operators with standardized equipment lists. Suez and Veolia framework agreements in France and the UK now mandate ten-year spare parts availability.
- Marine Operations:Ballast, bilge, and fuel tank level monitoring for commercial shipping and offshore platforms. Lloyd's Register and DNV classification rules drive type-approved switch specifications.
- Waste Management:Landfill leachate, biogas digester, and hazardous waste tank level control. EPA RCRA requirements in the United States mandate secondary containment leak detection systems.
- Power Generation:Boiler drum, condensate, and cooling tower level control in thermal and nuclear plants. Japan's METI efficiency standards accelerate adoption of high-resolution magnetostrictive position sensing.
Manufacturing plants represent the broadest segment; utilities are gaining share fastest through multinational consolidation and framework contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specification-grade buyers concentrate in German chemical processing clusters, while water infrastructure investment drives procurement across India and Brazil. Regional demand patterns diverge sharply between mature markets emphasizing SIL certification and emerging economies prioritizing cost-effective automation.
United States
Municipal utilities drive dual-float procurement for EPA-mandated redundant wastewater discharge control. The EPA effluent regulations directly expand specification demand across US water treatment infrastructure. Gulf Coast refineries specify capacitive switches for aggressive chemical media handling.
Germany
Ludwigshafen and Leverkusen chemical clusters anchor European demand for magnetically coupled reed switch variants. REACH substance restrictions force multi-year elastomer reformulation cycles among switch manufacturers. Factory-calibrated instrumentation dominates specification channels through embedded safety engineering capabilities.
India
Thermal power cooling systems create automated reservoir management demand per Central Electricity Authority mandates. The CEA requirements expand electronic float switch specification across water infrastructure projects. Maharashtra and Gujarat industrial corridors concentrate manufacturing plant procurement.
Japan
Boiler feedwater systems deploy high-temperature reed switches where temperature cycling exceeds 150°C. METI efficiency standards accelerate magnetostrictive position sensing adoption in power generation. Kanto and Kansai industrial belts concentrate precision instrumentation demand.
Brazil
Sugar-alcohol fermentation tank farms drive hygienic float switch specification under ANVISA sanitary requirements. The bioethanol expansion creates parallel demand across pulp and paper black liquor applications. São Paulo state processing clusters anchor South American procurement volume.
Global Float Level Switches Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with embedded instrumentation divisions, compressing mid-tier specialist participation. Consolidation pressure intensifies as IEC 61508 SIL certification requirements raise engineering barriers. Two strategic archetypes dominate: safety-certified specification leaders and scale-driven component fabricators. Competitive moves concentrate on portfolio diversification into predictive maintenance platforms and strategic partnerships for IO-Link protocol integration.
Within the safety-certified tier, Magnetrol (AMETEK) and Endress+Hauser exemplify archetypes anchoring specification authority through embedded functional safety capabilities. Emerson Electric occupies a position spanning electronic platforms with diagnostic integration. Honeywell and Siemens represent diversified conglomerates leveraging cross-divisional automation portfolios. These players sit within a structure where certification concentration rewards integrated safety engineering over commodity hardware supply.
| Leading Market Players |
|---|
| Honeywell |
| Magnetrol (AMETEK) |
| Emerson Electric |
| Baumer |
| Gems Sensors |
| Endress+Hauser |
| Siemens |
| Schneider Electric |
| ABB Group |
| Others |
Cost & Logistics Intelligence
Capacity utilization at German instrumentation factories shapes price floors across specification-grade float switch tiers, concentrating supply authority among IEC 61508-certified manufacturers while compressing margins for commodity magnetic variants. Neodymium magnet price indexation in long-term supply agreements ties cost structures to Chinese export quota volatility, forcing dual-source strategies for magnetic float producers.
Pricing Analysis
Cost-plus contracts with neodymium price indexation dominate procurement frameworks for magnetic float switches, with quarterly adjustments tied to Shanghai Metal Market spot references. Pricing stratifies across SIL-certified premium tiers, standard industrial grades, and economy reed switch variants, with certification level and volume scale as primary differentiation drivers. Cost compression in economy tiers intensifies because Indian municipal utilities prioritize per-unit pricing over predictive maintenance integration. Water treatment operators exhibit highest price sensitivity, while German chemical clusters demonstrate lowest sensitivity due to safety-critical specification requirements.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Hamburg spiked during container capacity crunches, compressing margin structures for European distributors dependent on Asian component sourcing. Manufacturing concentrates in Germany, China, and Japan, with rare earth magnet processing anchored in Chinese Inner Mongolia facilities. Supply chains draw from neodymium permanent magnets, hermetically sealed reed contacts, and fluorocarbon elastomer compounds. Single-source vulnerability concentrates in rare earth magnet supply, with distribution running through factory-calibrated instrumentation channels and industrial distributor networks serving specification-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Float Level Switches Market sits in early-cycle recovery following capital expenditure freezes in process industries, with EPA effluent mandate enforcement and Indian water infrastructure investment providing cyclical lift.
For Market Incumbents: Secure SIL certification maintenance through TÜV Rheinland recertification cycles to defend specification authority against emerging electronic platform competitors. Deepen backward integration into neodymium magnet sourcing through offtake agreements with Australian rare earth developers, reducing exposure to Chinese export quota restrictions.
For New Entrants and Emerging Players: Differentiate on IO-Link predictive maintenance integration targeting Brazilian bioethanol fermentation tank farms, where ANVISA sanitary requirements create specification entry points absent entrenched incumbent relationships. Target Indian thermal power cooling systems through CEA-mandated electronic float switch procurement, leveraging cost advantages against European specification leaders.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electronic platform specialists with embedded diagnostic capabilities over mechanical switch fabricators facing capacitive sensing substitution. Long-term viability rests on predictive maintenance software recurring revenue attachment rates. Acquisition target archetype: mid-tier electronic float switch manufacturers with IO-Link protocol certification and established food and beverage channel relationships. Signal to watch: EPA effluent regulation enforcement intensity in US municipal wastewater markets.
| Strategic Initiative | Industry Significance |
|---|---|
| IO-Link Protocol Integration | Enables predictive maintenance data streams for European water utilities demanding condition monitoring. |
| Perfluoroelastomer Seal Qualification | Satisfies REACH substance restrictions for German tank farm operators maintaining emissions compliance. |
| Magnetostrictive Hybrid Miniaturization | Captures Japanese METI efficiency-driven boiler feedwater specification from separate transmitter installations. |
| Dual-Float Configuration Certification | Meets EPA effluent redundant control mandates expanding procurement across US municipal utilities. |
| Ten-Year Spare Parts Availability Guarantee | Aligns with Suez and Veolia framework agreement requirements in French and UK water privatization markets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with instrumentation procurement managers, plant engineers at chemical processing facilities, and aftermarket service directors at water utilities; and secondary validation through IEC certification databases, EPA effluent compliance filings, and customs trade records. Stakeholder input combined with SEC filings from diversified industrial conglomerates and trade association shipment data enabled bottom-up and top-down triangulation across product architectures and regional demand clusters.
Across the projection horizon, the analytical framework modeled demand across product type, technology tier, application environment, and end-user industry vertical. CAGRs derived from segment-level volume trajectories indexed to named regulatory enforcement schedules and infrastructure investment cycles. Forecast inputs incorporated REACH substance restriction implementation timelines and Central Electricity Authority mandate penetration rates in Indian thermal power capacity additions.
Forecasts assume regulatory continuity in EPA effluent enforcement and REACH substance restriction regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in rare earth magnet supply quotas and IEC 61508 standard revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Oil Level Switches Market
Switches
Zero Speed Switch Market
Switches
Low Voltage Disconnect Switch Market
Switches
United States X by Wire Systems Market
Switches
Residual Current Circuit Breaker Market
Switches
Disconnect Switch Market
Switches
Smart Circuit Breaker Market
Switches
Low Voltage Switchgear Market
Switches
Japan Reed Sensors Switches Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Global Light Control Switches Market
Switches
Rotary Limit Switches Market
Switches
Contactor-based Transfer Switch Market
Switches
Saudi Arabia Switchgear Market
Switches
Level Switches Market
Switches
Middle-East and Africa Low Voltage Switchgear Market