
 North America Digital Forensics Market | 2026-2036
North America Digital Forensics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Forensics Market Analytics
Certified digital forensics examiners is redrawing competitive boundaries across the North America Digital Forensics Market as talent scarcity limits service scalability. IBM Corporation leverages its hybrid cloud infrastructure to anchor enterprise-scale incident response operations. Magnet Forensics specializes in mobile device extraction tools that dominate law enforcement procurement channels. Cellebrite DI Ltd. competes aggressively on integrated hardware-software workflows that shorten evidence processing cycles.
North America Digital Forensics encompasses the scientific recovery, preservation, and analysis of digital evidence from computers, mobile devices, network logs, and cloud repositories using write-blocking hardware, hash verification protocols, and chain-of-custody documentation to support legal admissibility. The discipline serves criminal prosecution, civil litigation, regulatory compliance, and corporate internal investigations across public and private sectors. Incident Response services command premium pricing due to time-critical engagement structures and specialized staffing requirements. Cloud-based deployment is expanding fastest as organizations migrate evidence repositories to elastic infrastructure that reduces capital expenditure on forensic workstations. E-discovery applications sustain mature revenue streams tied to predictable litigation support cycles in legal firms and corporations.
The SEC mandates incident disclosure timelines that directly expand corporate demand for rapid forensic triage and documentation capabilities. State-level breach notification laws in California, New York, and Texas create fragmented compliance obligations that drive localized service procurement across multiple jurisdictions. FBI digital evidence protocols and Department of Justice charging guidelines shape technical standards for evidence handling that vendors must embed in product design. Stakeholders must weigh build-versus-buy decisions for forensic capabilities as regulatory velocity outpaces internal skills development.
Market Dynamics
Certified examiner scarcity is compressing service scalability across the North America Digital Forensics Market, forcing organizations to choose between premium outsourced retainers and multi-year internal capability builds that rarely match regulatory disclosure velocity.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Public companies must report material incidents within four business days, mandating rapid forensic triage and documentation workflows that expand corporate demand for external specialists.
- State Breach Notification Laws:California, New York, and Texas maintain distinct notification timelines and content requirements, fragmenting compliance obligations and driving localized procurement across multiple jurisdictions.
- Cloud Evidence Migration:Elastic infrastructure adoption reduces capital expenditure on forensic workstations while enabling distributed analyst teams to access centralized evidence repositories.
Market Restraints
- Specialized Hardware Concentration:Write-blocking devices and mobile extraction hardware rely on concentrated semiconductor supply chains, exposing procurement to component availability volatility.
- Certification Bottlenecks:EnCE, CFCE, and vendor-specific credentials require 12-24 month completion timelines, throttling talent pipeline expansion below service demand growth.
- Open-Source Tool Substitution:Autopsy, Sleuth Kit, and Volatility provide zero-license alternatives that commoditize basic forensic functions and compress entry-level service pricing.
Strategic Opportunities
- Canadian Provincial Expansion:Ontario and Quebec lag US state-level forensic capacity despite comparable technology sector density, creating first-mover advantage for cross-border service providers.
- IoT Forensic Applications:Connected vehicle telemetry, industrial sensor logs, and smart home device extraction represent underdeveloped evidence categories with minimal established tooling.
- FBI RCFL Partnership Models:Regional Computer Forensics Laboratory affiliate programs offer federal credentialing pathways that validate commercial service providers for law enforcement subcontracting.
Industry Challenges
- Chain-of-Custody Documentation:Multi-cloud evidence spanning AWS, Azure, and Google Cloud environments complicates custody transfer protocols and admissibility standards.
- Encryption Key Recovery:Full-disk and end-to-end encryption on mobile devices and messaging platforms creates technical dead-ends that limit extraction success rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Forensics Market |
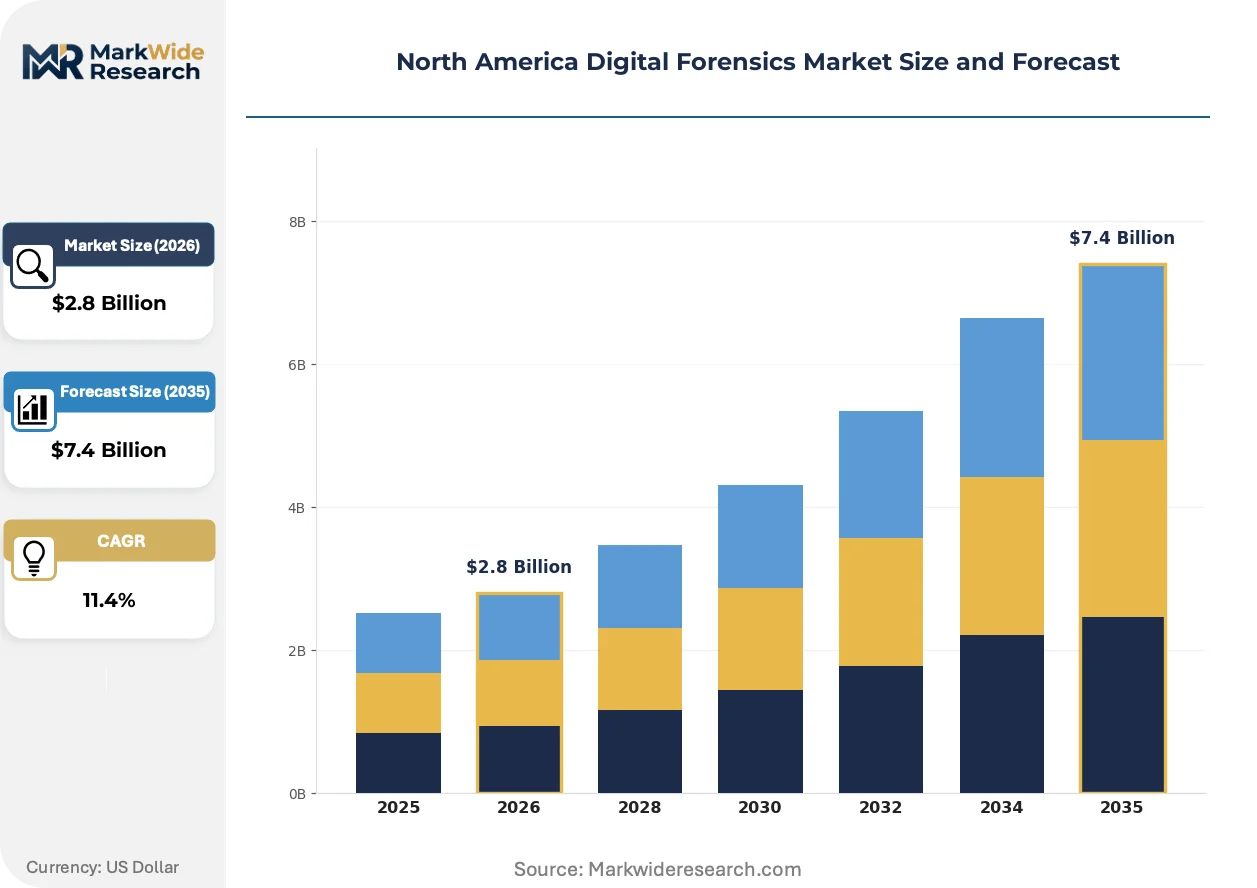
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Recovery, Incident Response, Malware Analysis, Cybersecurity Consulting End User: Government Agencies, Law Enforcement, Corporations, Legal Firms Deployment: On-premise, Cloud-based, Hybrid, Remote Application: Fraud Detection, Cybercrime Investigations, Compliance, E-discovery |
| Companies Covered | IBM Corporation, Cisco Systems Inc., Open Text Corporation, Cellebrite DI Ltd., Magnet Forensics, Oxygen Forensics, Paraben Corporation, KLDiscovery Inc., LogRhythm Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Forensics Market Evolving Landscape
Artificial intelligence is reshaping evidence processing velocity across the North America Digital Forensics Market, compressing analyst review cycles while introducing new authentication requirements for machine-generated findings.
Automated artifact classification is bifurcating the examiner workforce into technicians who operate AI-assisted triage platforms and specialists who validate algorithmic findings for court presentation. Large law enforcement agencies and corporate security teams are adopting these tools fastest, deploying them for initial image and document categorization. The technology is compressing entry-level analyst roles while expanding premium demand for credentialed validators who can defend AI-assisted conclusions under cross-examination.
State-level privacy legislation in California and Virginia is mandating data minimization practices that directly conflict with forensic preservation requirements. Organizations must now document retention limitations while maintaining complete evidence integrity for litigation hold purposes. Financial services and healthcare verticals face the sharpest compliance tension, investing in ephemeral communication platforms that complicate post-incident reconstruction.
Subscription-based forensic platform licensing is displacing perpetual software purchases across mid-market security teams. Channel partners and managed security service providers are capturing procurement decisions previously owned by internal IT procurement. Texas and Florida enterprise buyers show the fastest adoption velocity, consolidating vendor relationships under annual forensic-as-a-service contracts that bundle software, cloud storage, and analyst hours.
North America Digital Forensics Market Segmentation
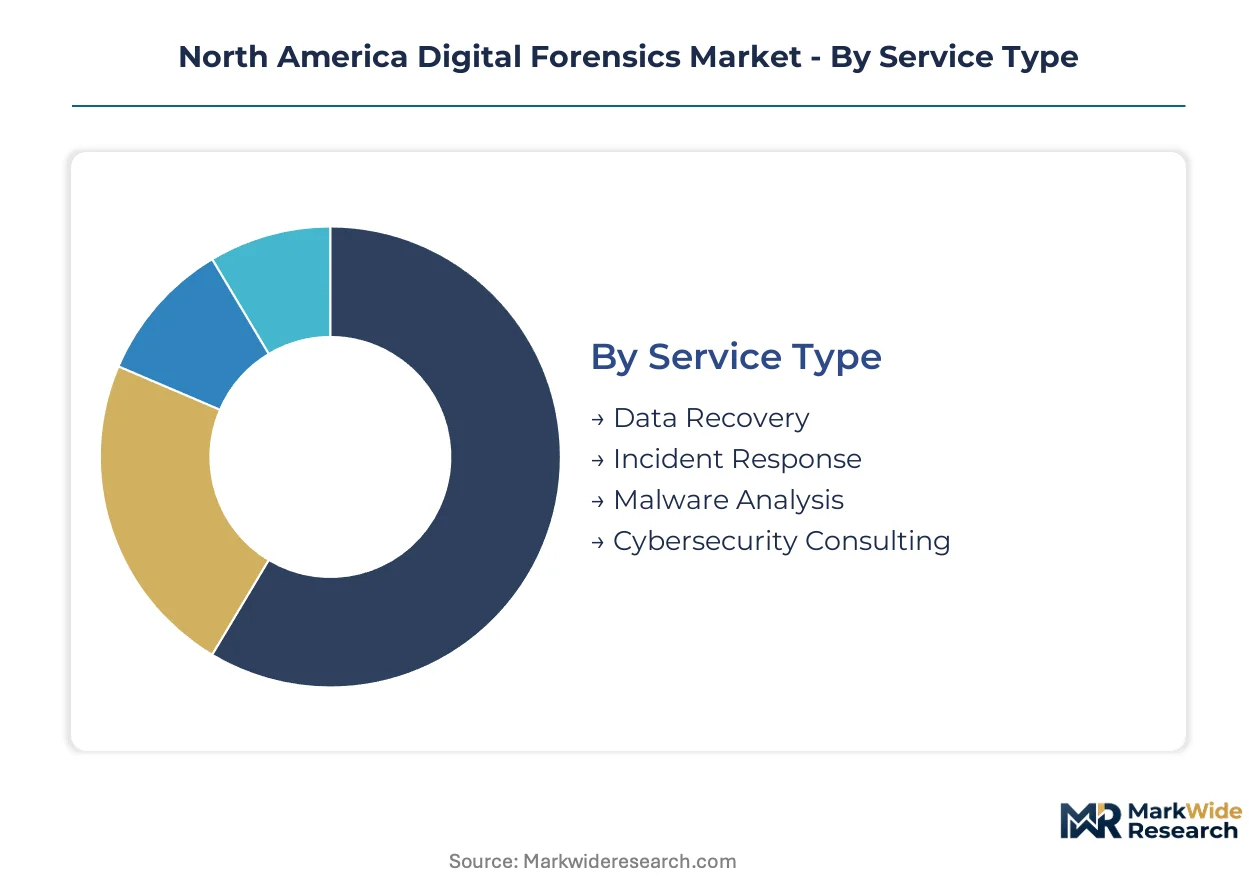
Segmentation in the North America Digital Forensics Market reveals how procurement patterns split between domestic public sector buyers and cross-border commercial clients. Each dimension exposes distinct capability requirements that vendors must address through specialized tooling and service architectures.
Service Type:
Domestic demand concentrates in U.S. federal and state contracts, while Canadian provincial buyers increasingly source cross-border expertise for specialized engagements.
- Incident Response:Time-critical engagement structures with 4-hour SLA commitments for material breach containment. Texas and California financial services firms drive premium pricing through mandatory SEC disclosure timelines.
- Data Recovery:Physical media restoration from damaged storage devices using cleanroom facilities and specialized read/write head replacement. Enterprise IT departments in New York and Ontario sustain steady demand for ransomware recovery operations.
- Malware Analysis:Reverse engineering of executable code to identify command-and-control infrastructure.
- Cybersecurity Consulting:Advisory services for forensic readiness and evidence preservation policy development.
Incident Response commands the established base. The steepest expansion runs through Malware Analysis.
End User:
Cost tier segmentation separates premium federal contractors from budget-constrained municipal buyers and mid-market corporate security teams.
- Law Enforcement:Regional Computer Forensics Laboratory networks and state police digital evidence units requiring CJIS-compliant chain-of-custody protocols. FBI credentialing standards shape vendor selection across all 50 states.
- Corporations:Fortune 500 security operations centers building internal forensic capabilities alongside external retainer relationships. Healthcare and financial verticals in Illinois and Massachusetts show the fastest internal hiring velocity.
- Government Agencies:Federal departments with classified network requirements and distinct procurement vehicles.
- Legal Firms:Litigation support departments managing e-discovery workflows and expert witness preparation.
Law Enforcement anchors procurement volume. Corporate buyers are gaining share fastest as SEC disclosure obligations expand.
Deployment:
Volume patterns reflect infrastructure maturity gaps between early cloud adopters and regulated industries with data sovereignty constraints.
- Cloud-based:Elastic compute resources for distributed analyst teams accessing centralized evidence repositories. Mid-market security teams in Florida and Arizona show fastest adoption velocity under managed security service provider bundles.
- Hybrid:Split architectures preserving sensitive evidence on-premise while leveraging cloud analytics for non-sensitive data classification. Federal contractors in Virginia and Maryland favor this model for CMMC compliance.
- On-premise:Air-gapped forensic workstations for classified or highly sensitive investigations.
- Remote:Secure tunneling protocols enabling analyst access without physical evidence transport.
On-premise retains the regulated core. Hybrid deployments are climbing the fastest as compliance frameworks evolve.
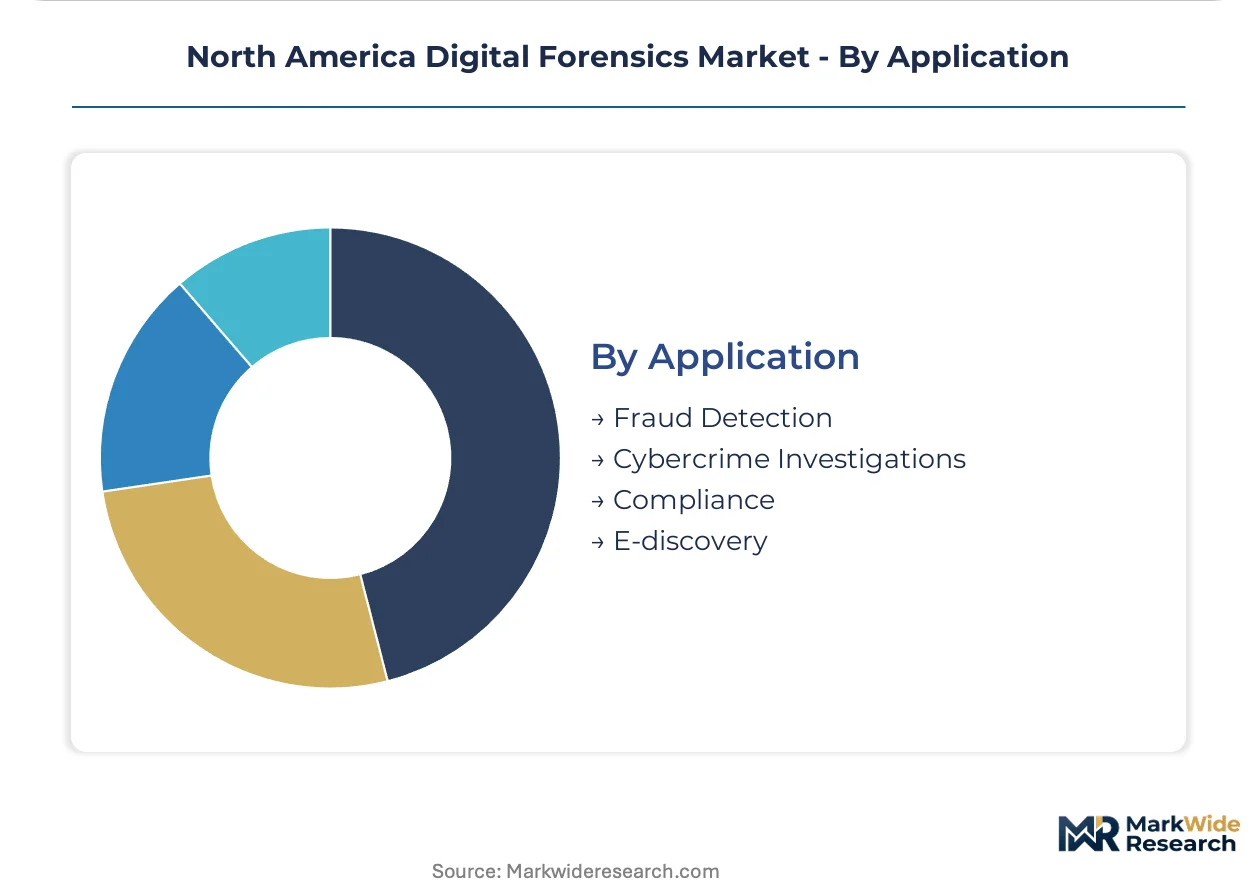
Application:
Customer type segmentation separates reactive incident-driven procurement from predictable litigation support cycles with annual contract structures.
- E-discovery:Structured data processing for civil litigation with predictable review timelines and established judicial precedent. New York and Delaware legal markets sustain mature revenue streams through recurring corporate engagements.
- Cybercrime Investigations:Criminal prosecution support spanning identity theft, financial fraud, and nation-state attribution. FBI field offices and state attorneys general in Texas and California generate concentrated case volume.
- Fraud Detection:Internal investigations of employee misconduct and financial statement manipulation.
- Compliance:Regulatory examination preparation and documentation for HIPAA, PCI-DSS, and state privacy laws.
E-discovery holds the recurring revenue base. Cybercrime Investigations show the steepest trajectory as state breach notification laws proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States law enforcement agencies prioritize mobile device extraction capabilities, while Canadian provincial buyers emphasize cross-border data sovereignty compliance and cloud evidence handling protocols.
United States
California, Texas, and New York generate the highest incident volumes due to technology sector density and financial services concentration. SEC cybersecurity disclosure rules mandate four-day reporting timelines for material incidents, accelerating forensic triage procurement. FBI Regional Computer Forensics Laboratory networks in these states establish technical standards that shape vendor product design across all fifty states.
Canada
Ontario and Quebec technology corridors drive demand comparable to US state levels, yet provincial forensic capacity remains underdeveloped relative to incident frequency. Health Canada and provincial privacy commissioners enforce data residency requirements that complicate cross-border evidence sharing. Toronto and Montreal legal markets increasingly source specialized expertise from US-based providers for complex cross-border litigation.
Mexico
Mexico City financial district and Monterrey industrial corridor generate concentrated demand for fraud detection and internal investigation services. The country's national data protection authority imposes breach notification obligations that expand corporate compliance budgets. Baja California and Chihuahua manufacturing clusters near the US border show fastest adoption velocity as multinational corporations extend North American security operations.
North America Digital Forensics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hybrid cloud providers and mobile extraction specialists occupying distinct competitive positions. The market structure reflects capability fragmentation across hardware-software workflows, cloud infrastructure, and certified examiner services. Three archetypes dominate: enterprise-scale platform vendors, law enforcement-focused tool developers, and boutique incident response consultancies. Competitive moves concentrate on strategic partnerships with federal credentialing programs and portfolio expansion into adjacent cybersecurity services.
Within the enterprise platform tier, IBM Corporation anchors hybrid cloud infrastructure deployments that support distributed forensic operations. Cisco Systems Inc. occupies a position bridging network security and evidence collection workflows. Among specialized tool developers, Magnet Forensics exemplifies the mobile device extraction archetype that dominates law enforcement procurement channels, while Cellebrite DI Ltd. represents integrated hardware-software workflow providers focused on evidence processing velocity.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems Inc. |
| Open Text Corporation |
| Cellebrite DI Ltd. |
| Magnet Forensics |
| Oxygen Forensics |
| Paraben Corporation |
| KLDiscovery Inc. |
| LogRhythm Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day component lead times for write-blocking hardware and mobile extraction chipsets concentrate procurement leverage among semiconductor distributors, compressing margin flexibility for forensic workstation assemblers while amplifying pricing power at the component tier.
Pricing Analysis
Subscription-based SaaS licensing dominates enterprise procurement, displacing perpetual software purchases across mid-market security teams. Price differentiation separates EnCE-certified examiner services from uncredentialed technician support, with CJIS-compliant chain-of-custody documentation commanding substantial premiums. Cost compression in entry-level forensic tooling intensifies as Autopsy and Sleuth Kit provide zero-license alternatives, forcing commercial vendors toward bundled analyst-hour contracts. Municipal law enforcement agencies exhibit highest price sensitivity due to fixed budget cycles, while Texas and California financial services firms absorbing SEC disclosure mandates show lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of specialized forensic hardware persists among federal contractors and RCFL network affiliates, insulating evidence processing capacity against semiconductor availability volatility. Component sourcing draws from Taiwan for advanced chipsets, South Korea for memory modules, and domestic US facilities for classified-grade assembly. Single-source vulnerability concentrates in proprietary mobile extraction chipsets from Cellebrite and Magnet Forensics. Distribution runs through channel partners and managed security service providers capturing procurement decisions previously owned by internal IT departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forensic-as-a-service subscription layers expand faster than hardware sales, creating service-attach economics that favor recurring revenue models over one-time workstation deployments.
For Market Incumbents: Secure examiner certification pipelines through university partnerships and RCFL affiliate programs to defend against open-source tool commoditization. Deepen backward integration into cloud evidence repositories to capture subscription renewals as hybrid deployment preferences solidify among federal contractors. For New Entrants and Emerging Players: Anchor in Canadian provincial markets where Ontario and Quebec technology corridors generate incident volumes comparable to US states yet local forensic capacity remains underdeveloped. Target healthcare verticals in Illinois and Massachusetts through HIPAA-compliant evidence handling certifications. For Investors and Strategic Acquirers: Carve-out targets emerge from cybersecurity conglomerates divesting non-core forensic tooling divisions. Long-term viability hinges on AI-assisted triage platform differentiation. Watch for inflection signals in FBI RCFL partnership expansion rates as validation of commercial provider credentialing pathways.| Strategic Initiative | Industry Significance |
|---|---|
| RCFL Partnership Expansion | Federal credentialing validates commercial providers for law enforcement subcontracting pipelines. |
| AI-Assisted Triage Platform Launch | Machine learning compression of analyst review cycles reshapes examiner workforce tiering. |
| Canadian Provincial Market Entry | Ontario and Quebec technology density supports first-mover service provider positioning. |
| Cloud Evidence Repository Integration | Elastic infrastructure reduces capital expenditure while enabling distributed analyst access. |
| IoT Forensic Tooling Development | Connected vehicle telemetry and industrial sensor logs represent underdeveloped evidence categories. |
Research Methodology
A standing panel of FBI digital evidence unit supervisors, corporate security operations center directors, litigation support managers at AmLaw 100 firms, and CJIS compliance officers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against SEC cybersecurity disclosure filings, state attorney general breach notification databases, and RCFL procurement records. Bottom-up service provider revenue aggregation triangulated against top-down enterprise IT security spending estimates.
Consistency checks validated volume and value outputs against hyperscaler forensic cloud capex disclosures and managed security service provider contract announcements across the projection horizon. Segmentation modeling covered service type, end-user archetype, deployment architecture, and application vertical. CAGRs derived from regression analysis of historical incident response retainer pricing and examiner wage inflation patterns.
Underlying assumptions cover regulatory disclosure timeline stability and semiconductor supply normalization, with deviation risk concentrated in encryption standard evolution and state privacy law fragmentation. Practitioners should keep alternative scenarios live as SEC enforcement patterns and AI authentication standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Managed Detection and Response (MDR) Market
Cybersecurity
Middle East and Africa Cybersecurity Market
Cybersecurity
Dark Web Intelligence Market
Cybersecurity
Smart Grid Cyber Security Market
Cybersecurity
Botnet Detection Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
India Network Security and Cyber Risk Management Market
Cybersecurity
Retail Cybersecurity Market
Cybersecurity
Cloud Workload Protection Market
Cybersecurity
Artificial Intelligence-Based Cybersecurity Market
Cybersecurity
South Korea Ransomware Protection Market
Cybersecurity
Data Center Logical Security Market
Cybersecurity
DNS Security Market
Cybersecurity
Europe Web Application Firewall Market
Cybersecurity
Cognitive Security Market
Cybersecurity
Hong Kong Cybersecurity Market