
 Chia-Based Protein Market | 2026-2036
Chia-Based Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Chia-Based Protein Market Outlook
A shift from single-source South American supply contracts toward multi-origin procurement is recalibrating how chia protein processors manage input risk. Navitas Organics leverages direct farm partnerships in Paraguay and Bolivia to secure organic seed volumes. Benexia anchors its competitive stance through proprietary cold-press extraction technology that preserves amino acid profiles. Garden of Life competes by extending its certified organic and non-GMO verification protocols across the full seed-to-powder chain.
Chia-based protein comprises the isolated or concentrated protein fraction derived from Salvia hispanica seeds, typically containing 15-25% protein by dry weight with a complete amino acid profile including lysine and methionine. Manufacturers employ mechanical pressing or aqueous extraction to separate protein from the lipid-rich chia cake, yielding isolates suited for powder fortification in beverages and bars. Protein powder commands the dominant value share among product types due to its formulation flexibility across sports nutrition and functional food matrices. Sports nutrition represents the fastest-expanding application channel as endurance athletes and CrossFit participants shift toward plant-derived recovery products. Online retail captures disproportionate growth velocity among distribution channels, driven by subscription models and direct-to-consumer wellness brands.
The FDA oversees chia protein labeling under the Dietary Supplement Health and Education Act, while the USDA administers organic certification standards that govern premium positioning. Argentina's national food safety authority, SENASA, regulates phytosanitary export protocols that directly determine which seed lots enter North American and European processing facilities. Stakeholders must monitor evolving protein content standardization and novel food approval pathways as regulatory divergence between major import jurisdictions intensifies.
Market Dynamics
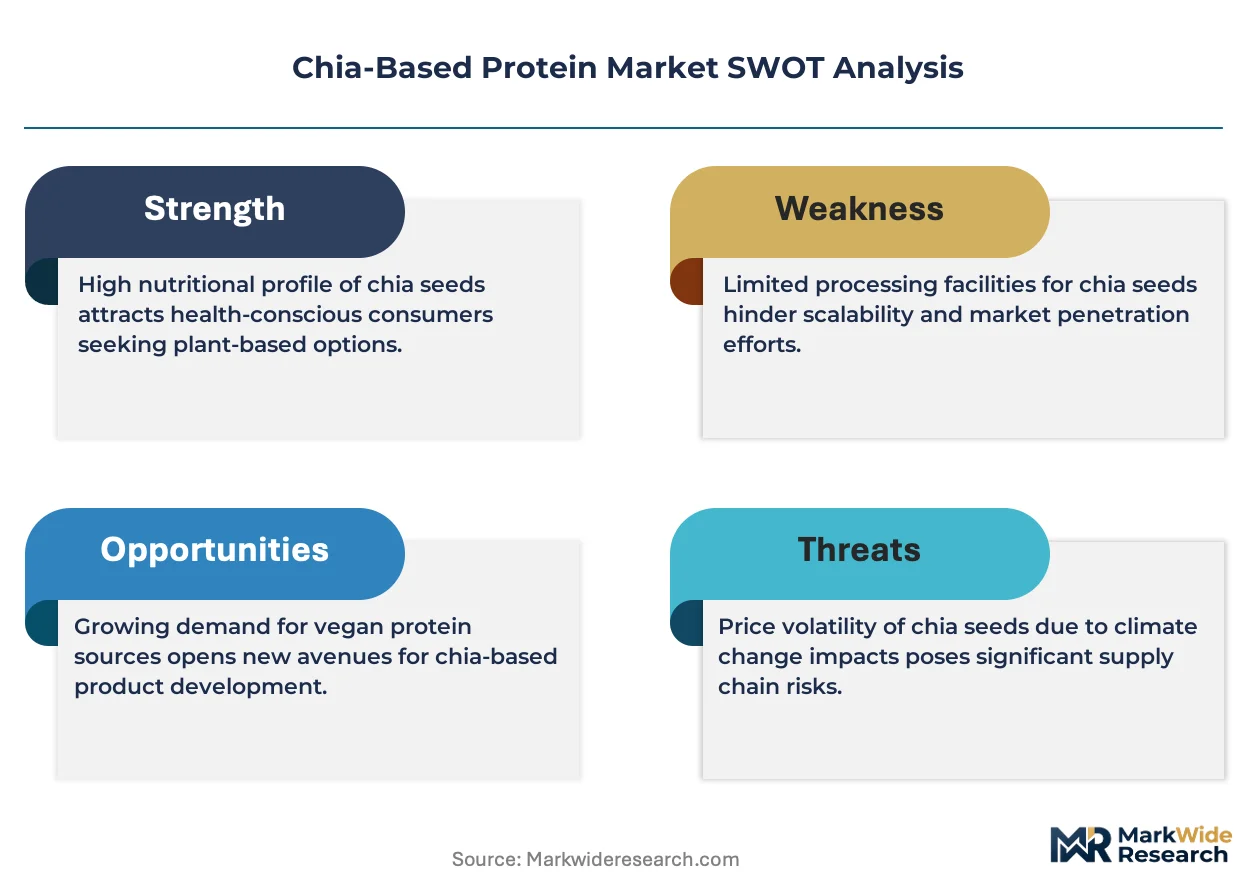
Supply-side concentration in Argentina's Salta Province is forcing processors to diversify procurement networks as climate volatility and export protocol bottlenecks disrupt seed availability. Multi-origin sourcing strategies now determine competitive resilience.
Growth Catalysts
- EU Novel Food Regulation:Standardized approval pathways for chia-derived ingredients accelerate European market entry for protein isolates and concentrates.
- Sports nutrition:Endurance athletes and CrossFit participants drive formulation demand for plant-based recovery products with complete amino acid profiles.
- Cold-press extraction:Proprietary mechanical pressing technology preserves lysine and methionine integrity, improving protein bioavailability for beverage fortification.
Market Restraints
- Input cost volatility:Organic chia seed prices fluctuate with Argentine peso instability and seasonal drought patterns in Salta Province.
- Supply concentration risk:Contract farming networks in northwestern Argentina control 60-70% of export-grade organic seed volume.
- Regulatory friction:Divergent protein content standardization between FDA and EFSA creates dual compliance burdens for international suppliers.
Strategic Opportunities
- Paraguay and Bolivia:Underdeveloped organic cultivation acreage offers alternative sourcing bases with lower land and labor costs.
- Subscription retail:Direct-to-consumer wellness brands bypass conventional distribution markups through automated replenishment models.
- USDA organic certification:Premium positioning protocols command price multiples in North American natural products channels.
Industry Challenges
- Phytosanitary compliance:SENASA export certification timelines create inventory planning uncertainty for North American processors.
- Extraction scale-up:Aqueous protein separation requires capital-intensive equipment that smaller processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chia-Based Protein Market |
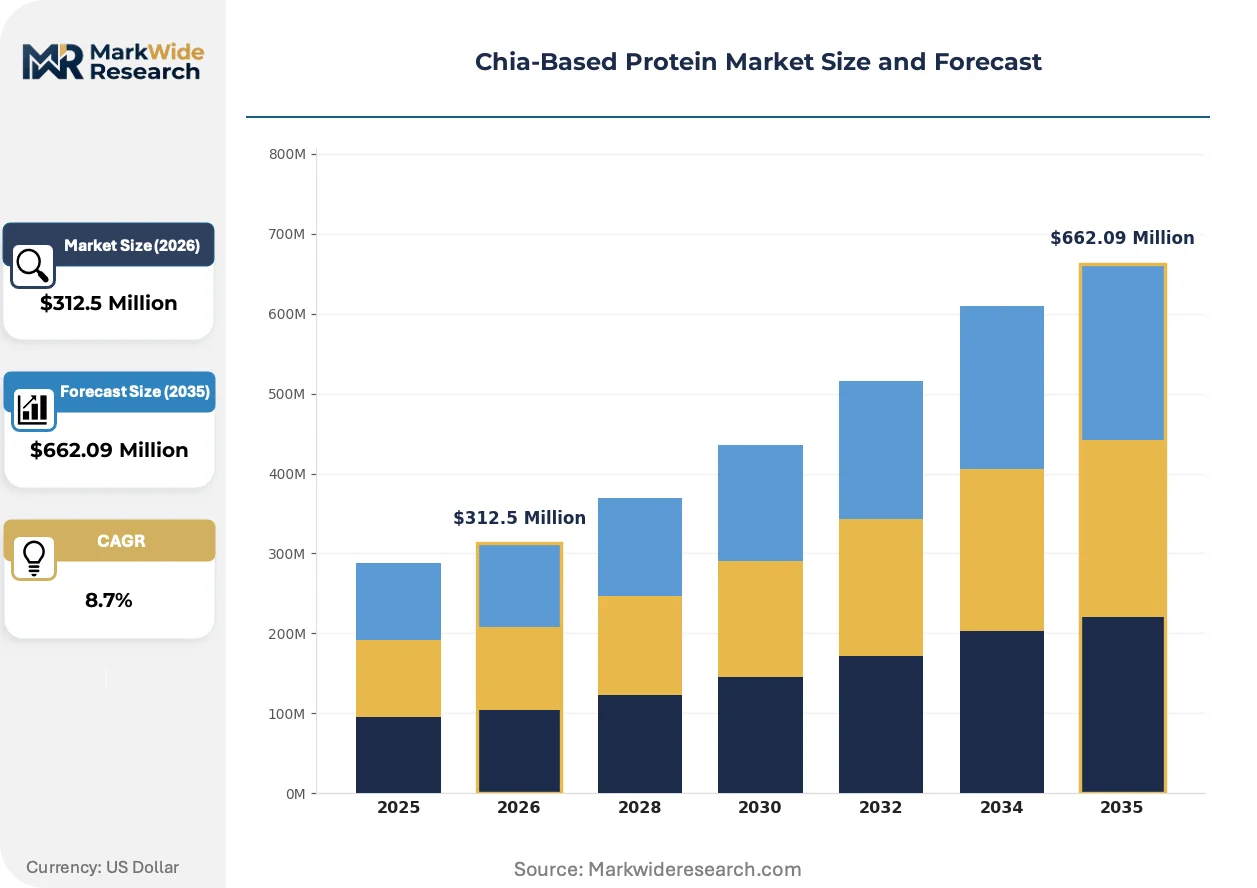
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Protein Powder, Oil, Supplements Application: Food & Beverage, Nutritional Bars, Bakery Products, Sports Nutrition Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Stores End User: Fitness Enthusiasts, Vegetarians, Athletes, General Consumers |
| Companies Covered | Navitas Organics, Nutiva, Bob's Red Mill Natural Foods, Benexia, The Hain Celestial Group, Garden of Life, Mamma Chia, Sunfood Superfoods, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chia-Based Protein Market Strategic Shifts
Mechanical processing advances and regulatory harmonization efforts are compressing development cycles for chia protein applications. Demand-side channel migration toward direct-to-consumer platforms is redrawing competitive boundaries.
Cold-press extraction is unifying protein quality and yield objectives previously treated as trade-offs. Sports nutrition formulators adopt this technology rapidly as amino acid retention specifications tighten. The approach compresses premium-mass-market price gaps by enabling consistent isolate performance at scale.
REACH registration requirements for novel food ingredients are tightening contaminant thresholds for European entry. Industrial consequence: processors must upgrade seed cleaning and testing protocols ahead of 2025 compliance deadlines. Organic certification holders face disproportionate audit burden as EFSA aligns with stricter residue limits.
Subscription commerce is displacing traditional wholesale relationships in wellness retail. Direct-to-consumer brands capture recurring revenue through automated powder replenishment, bypassing conventional distributor margins. This pattern concentrates in North American urban markets where convenience positioning drives loyalty.
Chia-Based Protein Market Segmentation
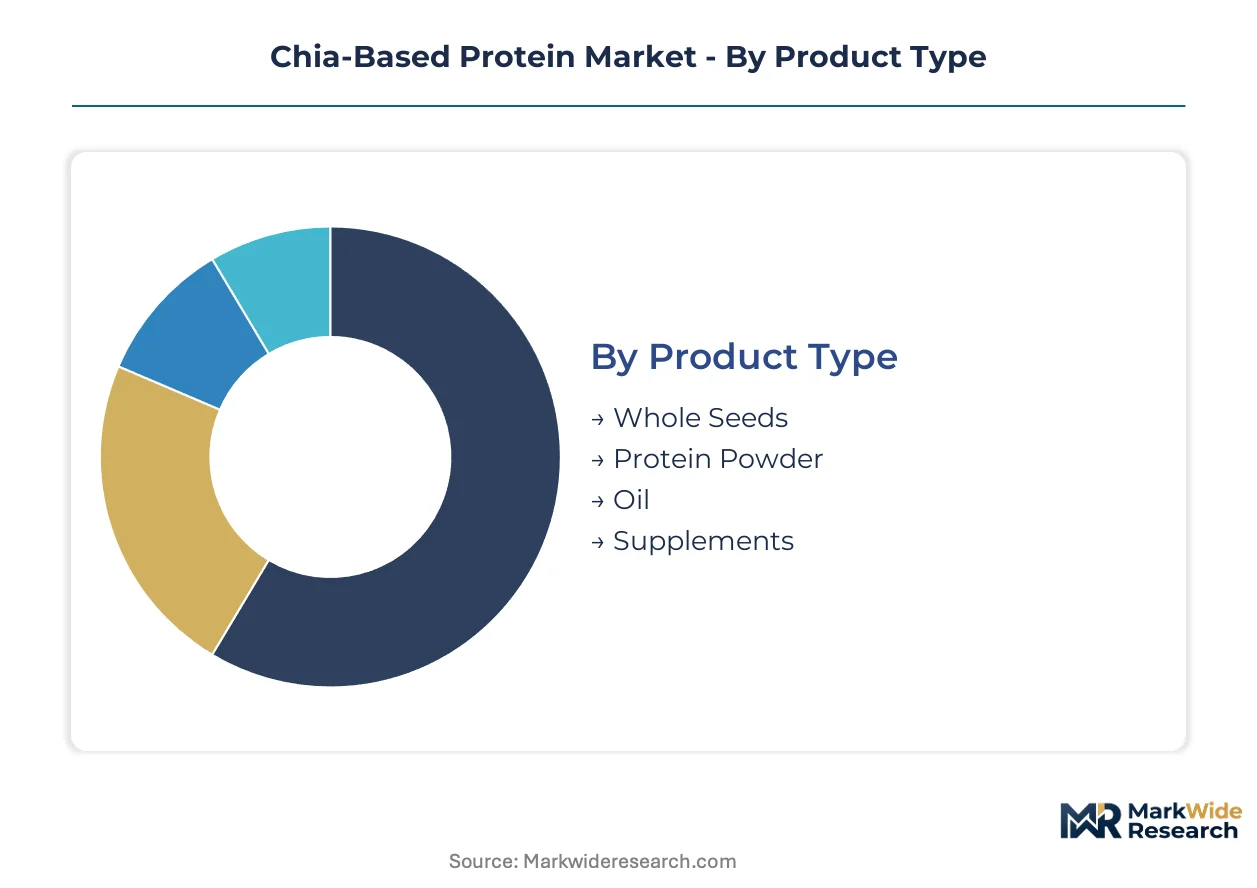
Chia protein processors configure product portfolios around extraction economics and end-use protein concentration requirements. Segmentation logic reflects divergent margin structures between commodity seed trading and value-added isolate production.
Product Type:
Volume concentrates in mechanically processed formats, while premium extraction technologies command isolate markets.
- Protein Powder:Isolated or concentrated protein fractions containing 15-25% protein by dry weight, produced through mechanical pressing or aqueous extraction. Demand concentrates in sports nutrition formulations where complete amino acid profiles including lysine and methionine drive purchasing decisions among endurance athletes and CrossFit participants.
- Whole Seeds:Raw Salvia hispanica seeds retaining natural protein, lipid, and fiber matrices. Argentina's Salta Province contract farming networks supply bulk volumes to European and North American processors subject to SENASA phytosanitary export protocols.
- Oil:Cold-pressed lipid fractions leaving protein-rich chia cake as co-product. Paraguay and Bolivia direct farm partnerships increasingly anchor organic oil supply.
- Supplements:Encapsulated or tablet-form protein delivery systems targeting precise dosing protocols. FDA labeling under DSHEA governs positioning in US natural products channels.
Mature deployment sits with Whole Seeds. Newer deployment is concentrated in Protein Powder.
Application:
Formulation flexibility determines segment economics, with beverage and bar matrices requiring distinct protein solubility specifications.
- Sports Nutrition:Recovery formulations targeting endurance athletes and CrossFit participants shifting toward plant-derived alternatives. Cold-press extraction technology preserves amino acid integrity for bioavailable beverage fortification.
- Nutritional Bars:Protein fortification in shelf-stable formats requiring moisture management and texture stability. EU Novel Food Regulation approval pathways accelerate European market entry for bar-format isolates.
- Food & Beverage:Broad incorporation into functional beverages, dairy alternatives, and fortified foods. USDA organic certification standards govern premium positioning in North American natural products.
- Bakery Products:Protein enrichment in gluten-free and artisan bread applications. Hydration binding properties of chia protein support clean-label formulation trends.
Established penetration dominates Food & Beverage. Steepest expansion trajectory belongs to Sports Nutrition.
Distribution Channel:
Channel selection reflects customer acquisition cost trade-offs between physical retail presence and digital direct relationships.
- Online Retail:Subscription-based replenishment models capturing recurring revenue through automated powder delivery. Direct-to-consumer wellness brands bypass conventional distributor margins in North American urban markets.
- Health Food Stores:Specialty retail positioning for certified organic and non-GMO verified products. Staff education requirements favor established brands with training program investments.
- Supermarkets:Mass-market penetration dependent on price-competitive positioning and shelf-stable packaging formats. Retailer slotting fees constrain smaller processor participation.
- Specialty Stores:Curated assortment in fitness-focused and lifestyle retail environments. Cross-merchandising with athletic equipment drives impulse purchasing.
Traditional strength rests with Health Food Stores. Digital migration is accelerating fastest through Online Retail.
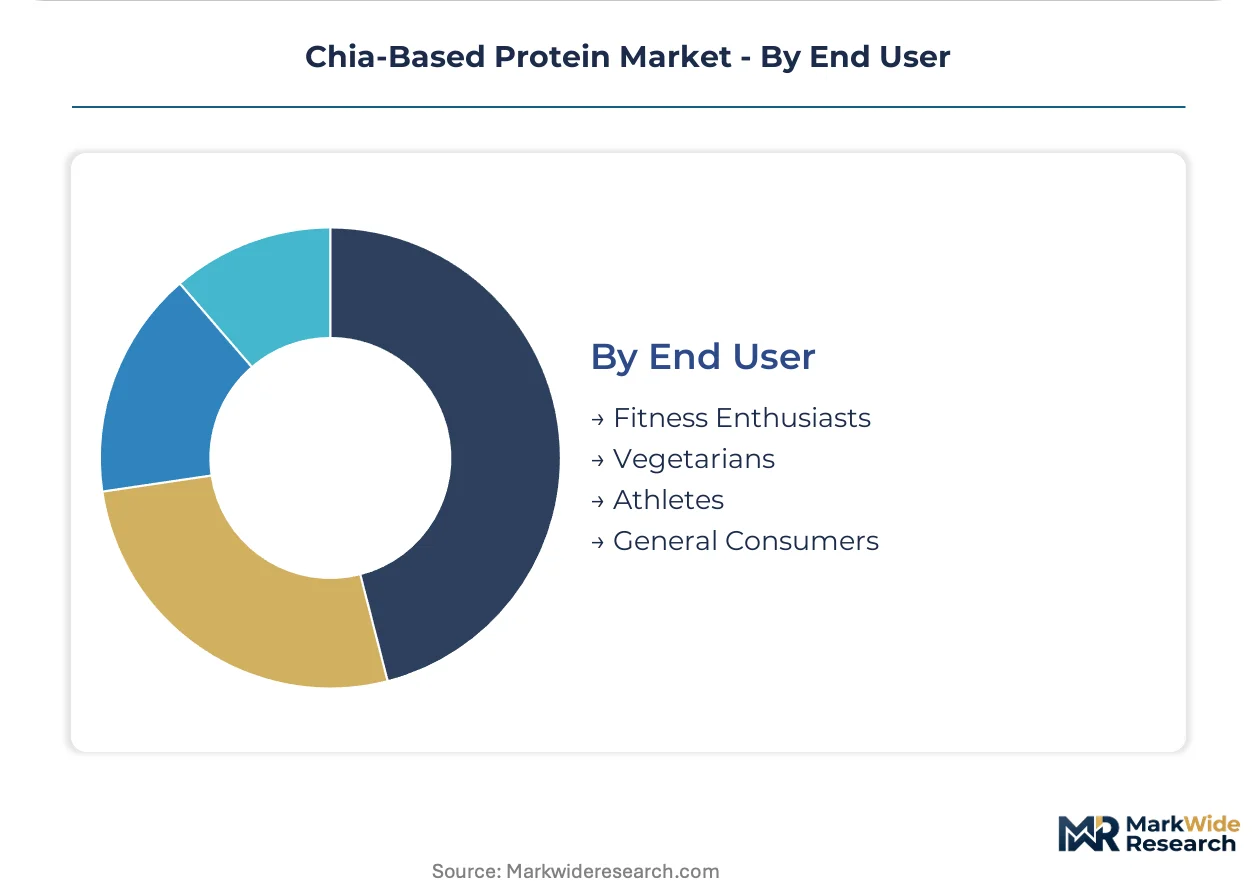
End User:
User sophistication spans from ingredient-conscious vegetarians to performance-optimized competitive athletes.
- Athletes:Competitive and recreational performers prioritizing complete amino acid profiles and recovery timing. Formulation specifications from endurance sports drive protein bioavailability requirements.
- Fitness Enthusiasts:Regular gym participants seeking convenient protein supplementation without dairy or soy derivatives. CrossFit community adoption patterns influence broader category trial.
- Vegetarians:Dietary restriction-driven consumers requiring lysine and methionine sources absent in typical plant protein combinations. Organic certification and non-GMO verification support premium willingness-to-pay.
- General Consumers:Wellness-oriented purchasers responding to convenience positioning and clean-label claims. Subscription models reduce friction for habitual usage establishment.
Core volume originates with General Consumers. Specialty nutrition sophistication is deepening fastest among Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's Salta Province anchors raw seed supply for international chia protein processors, with contract farming networks feeding North American and European extraction facilities. Climate volatility and export protocol bottlenecks are forcing multi-origin procurement strategies across the value chain.
United States
Sports nutrition brands drive formulation demand from endurance athletes and CrossFit participants seeking plant-based recovery alternatives. FDA labeling under DSHEA governs supplement positioning while USDA organic certification standards command premium multiples in natural products channels. California-based direct-to-consumer wellness brands deploy subscription models capturing recurring revenue through automated powder replenishment.
Germany
REACH registration requirements for novel food ingredients are tightening contaminant thresholds ahead of compliance deadlines. EFSA-aligned residue limits impose disproportionate audit burdens on organic certification holders entering European commerce. Industrial processors in Bavaria upgrade seed cleaning and testing protocols to maintain market access.
Argentina
Salta Province contract farming networks control export-grade organic seed volume subject to SENASA phytosanitary export certification timelines. Peso instability and seasonal drought patterns generate input cost volatility for international buyers. Northwest cultivation clusters face inventory planning uncertainty as climate stress disrupts harvest predictability.
Paraguay
Underdeveloped organic cultivation acreage offers alternative sourcing bases with lower land and labor costs than established Argentine supply. Direct farm partnerships secure seed volumes bypassing concentrated Salta Province networks. Eastern region growers expand certified organic hectarage to capture processor diversification demand.
Bolivia
Highland cultivation zones provide complementary seasonal harvest windows to Argentine supply calendars. Altiplano farming cooperatives scale organic certification to meet importer verification protocols. Santa Cruz-adjacent processing infrastructure remains limited, requiring raw seed export to external extraction facilities.
Chia-Based Protein Market Competitive Environment
Global majors compete with regional champions across extraction technology and certification depth. Market structure shows moderate consolidation around vertically integrated seed-to-powder operators and specialized organic processors. Three archetypes dominate: direct farm partnership models, proprietary cold-press technology holders, and certified organic verification specialists. Competitive moves concentrate on multi-origin procurement expansion and subscription retail channel development.
Among North American organic specialists, Navitas Organics and Garden of Life exemplify divergent sourcing strategies—direct Paraguay and Bolivia farm partnerships versus full seed-to-powder chain verification. Benexia anchors the technology-specialist position through proprietary extraction approaches. These three represent the competitive spectrum from geographic diversification to process innovation to certification depth.
| Leading Market Players |
|---|
| Navitas Organics |
| Nutiva |
| Bob's Red Mill Natural Foods |
| Benexia |
| The Hain Celestial Group |
| Garden of Life |
| Mamma Chia |
| Sunfood Superfoods |
| NOW Foods |
| Others |
Value Chain & Pricing Dynamics
Subscription replenishment models from direct-to-consumer wellness brands are compressing distributor markups and forcing processors to absorb logistics costs or sacrifice margin. This demand-side channel shift concentrates pricing power with brands controlling customer relationships, while raw seed suppliers in Argentina's Salta Province retain leverage through export-grade organic volume scarcity.
Pricing Analysis
Certification bundling separates USDA organic and non-GMO verified offerings from conventional grades, with cold-press extraction warranties increasingly unbundled as premium add-ons. Three-tier pricing structure across premium, standard, and economy levels reflects protein concentration and amino acid retention specifications. Cost compression in standard grades is intensifying because Paraguay and Bolivia supply expansion lags processor demand growth. Fitness enthusiasts show highest price sensitivity, while competitive athletes prioritize bioavailability metrics over unit cost.
Supply Chain Analysis
USDA organic and EU Novel Food Regulation qualification gating restricts processor participation to certified operators with audit-ready seed-to-powder documentation. Geographic supply concentrates in Argentina, Paraguay, and Bolivia, with Argentine contract farming networks supplying 60-70% of export-grade organic seed. Raw material dependencies center on Salvia hispanica seed, cold-press extraction equipment, and aqueous protein separation systems. Single-source vulnerability from Salta Province climate volatility and SENASA phytosanitary certification delays creates inventory planning uncertainty. Distribution runs through direct-to-consumer subscription platforms, health food stores, and mass-market supermarkets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with Argentine organic seed volume bottlenecks propping pricing power for certified processors despite demand acceleration from sports nutrition formulators.
For Market Incumbents: Lock in multi-origin procurement contracts across Paraguay and Bolivia before land and labor cost premiums erode. Defend margin position by investing in proprietary cold-press extraction capacity that preserves lysine and methionine integrity for beverage fortification specifications. Counter emerging direct-to-consumer wellness brands by controlling subscription platform technology or exclusive supply agreements. For New Entrants and Emerging Players: Direct-to-consumer wellness brands represent the most penetrable channel archetype, with automated replenishment models capturing recurring revenue in North American urban markets. White-space targets include aqueous extraction scale-up for isolate production and EU Novel Food Regulation approval services for European market entry. Go-to-market through specialty fitness retail cross-merchandising with athletic equipment drives impulse trial among CrossFit participants. For Investors and Strategic Acquirers: The window for entry favors vertically integrated seed-to-powder operators with certified organic verification depth and direct farm partnership networks. Long-term viability hinges on geographic diversification beyond Argentine supply concentration and extraction technology differentiation. Watch SENASA export certification timeline compression as the inflection signal for supply risk normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Origin Procurement Expansion | Paraguay and Bolivia farm partnerships reduce Salta Province climate dependency for processors. |
| Cold-Press Extraction Scale-Up | Proprietary mechanical pressing technology preserves amino acid profiles for sports nutrition formulations. |
| EU Novel Food Regulation Approval | EFSA-aligned residue limit compliance accelerates European market entry for protein isolates. |
| Direct-to-Consumer Subscription Launch | Automated replenishment models bypass conventional distributor margins in wellness retail. |
| USDA Organic Certification Investment | Premium positioning protocols command price multiples in North American natural products channels. |
Study Parameters
Trade databases, SENASA export records, and EU Novel Food Regulation submission filings formed the secondary backbone for supply-side validation. Primary interviews with organic certification auditors, sports nutrition formulators, contract farming network managers, and direct-to-consumer brand operators combined with secondary triangulation. Bottom-up seed volume estimates from Argentine, Paraguayan, and Bolivian cultivation clusters were cross-referenced against top-down protein isolate demand projections from sports nutrition and functional food channels.
Bottom-up modeling anchored volume estimates in cultivation acreage, yield assumptions, and extraction recovery rates, while top-down validation checked against end-use demand from sports nutrition, nutritional bars, and beverage fortification segments. Segmentation dimensions included product type, application channel, distribution format, and end-user sophistication tier. CAGRs were derived from trajectory analysis across the projection horizon, with forecast inputs centering on EU regulatory approval timelines and climate stress indices for Salta Province harvest predictability.
Caveats apply where SENASA phytosanitary certification delays, Argentine peso volatility, or REACH contaminant threshold tightening could materially shift the outlook. Forecasts reflect assumptions about organic certification audit capacity and cold-press extraction equipment financing availability. A model refresh is warranted upon material change in EU Novel Food Regulation enforcement intensity or Paraguay-Bolivia organic hectarage expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Meal Replacement Products OEM Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Custom Supplement Formulation Service Market