

Basic Violet 10 Market Size, Share, and Industry Trends Forecast 2026-2036
Basic Violet 10 Market Insights
Buyer concentration across Asia's textile dyeing sector is broadening as mid-sized fabric finishers in Bangladesh and Vietnam multiply order volumes. Ranbar Chemical Corporation leverages its pigment synthesis expertise to serve leather tanneries requiring batch-to-batch color stability. KIWA Chemical Industry Co., Ltd. anchors supply relationships with Japanese ink formulators through ISO-certified production protocols. Tianjin Xiangrui Dyestuff Co., Ltd. competes on powder-grade customization for plastic compounders seeking specific dispersion rates.
Basic Violet 10 is a triarylmethane basic dye with a CAS registry number of 2390-59-2, typically supplied as a chloride salt exhibiting strong affinity for acrylic fibers and tannin-mordanted substrates; manufacturers synthesize it via condensation of Michler's ketone derivatives followed by salt formation to achieve standardized tinctorial strength. The powder form dominates volume shipments to textile manufacturers due to extended shelf stability and freight efficiency, while liquid formulations are gaining traction among ink manufacturers seeking reduced dust exposure and faster dissolution kinetics. Leather coloring applications sustain premium pricing for crystal-grade variants that offer superior penetration into chrome-tanned hides.
REACH registration requirements enforced by ECHA mandate full substance dossiers for EU market access, while China's SAMR oversees GB standard compliance for dye imports through mandatory testing at designated laboratories. India's BIS certification for textile chemicals is tightening purity thresholds for heavy metal content, forcing reformulation investments among export-oriented suppliers. Stakeholders must monitor evolving substance restriction lists across these jurisdictions to anticipate product line obsolescence and redirect R&D spending toward compliant chromophore architectures.
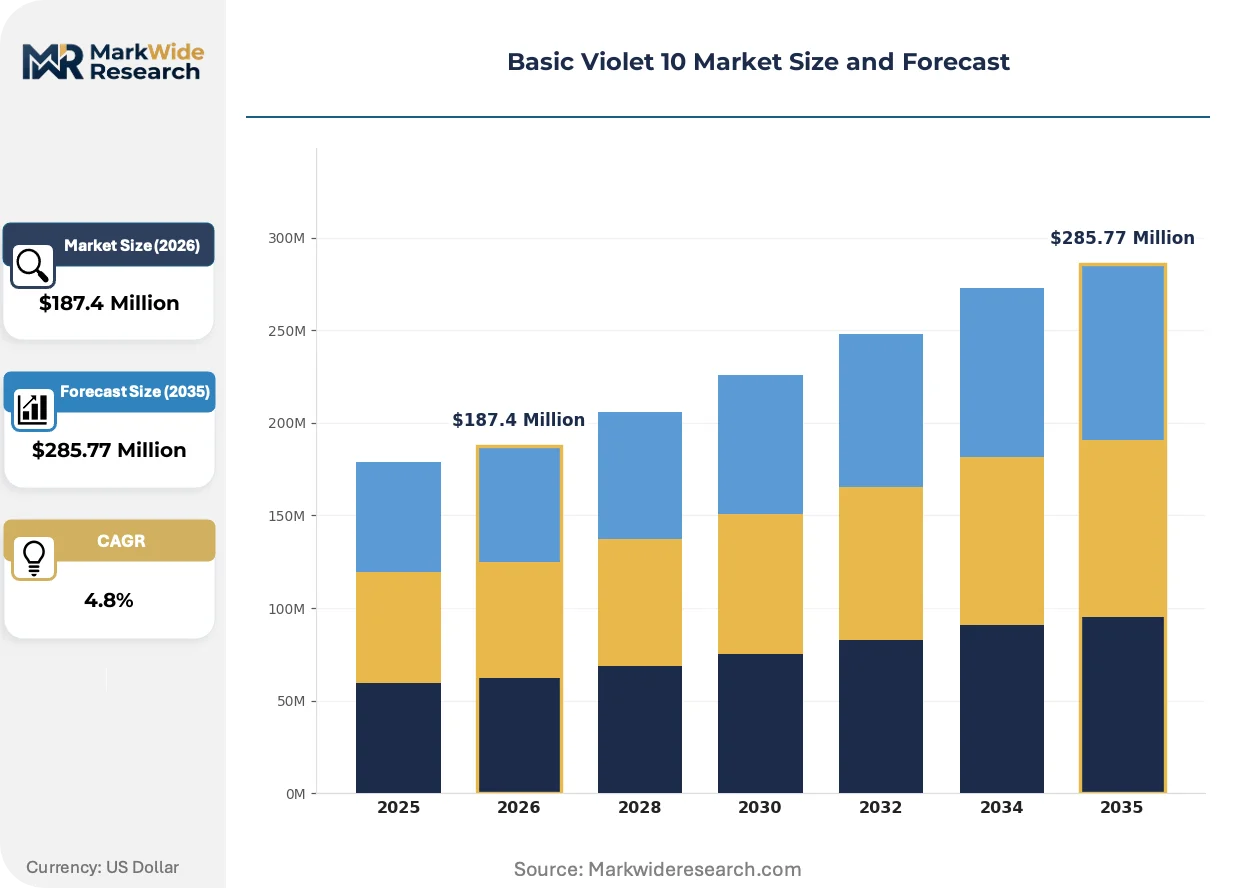
Market Dynamics
REACH registration dossiers and China's GB standard updates are forcing dyestuff suppliers to requalify purity specifications, while Bangladesh and Vietnam textile clusters concentrate purchase volumes to secure batch consistency.
Growth Catalysts
- REACH Compliance:ECHA substance dossier requirements are filtering out non-compliant suppliers, consolidating demand among certified manufacturers with established EU market access.
- Acrylic Fiber Expansion:Synthetic fiber production in Bangladesh and Vietnam is absorbing larger dye volumes as regional apparel manufacturing scales.
- Leather Tannery Premiumization:Chrome-tanning operations in Italy and India are sustaining crystal-grade demand for superior hide penetration and color stability.
Market Restraints
- Michler's Ketone Input Volatility:Condensation precursor costs fluctuate with aromatic chemical feedstock pricing, compressing synthesis margins.
- Supplier Concentration Risk:Powder-grade production clusters in eastern China create single-source vulnerability for international formulators.
- Substitution Pressure:Reactive dyes and pigment dispersions are displacing basic dyes in certain textile applications where wash-fastness requirements intensify.
Strategic Opportunities
- India BIS Certification Gap:Export-oriented suppliers investing in heavy metal threshold compliance can capture share from reformulation-lagged competitors.
- Liquid Formulation Ink Channel:Dust-reduced dissolution systems are opening dedicated supply relationships with ink manufacturers seeking faster kinetics.
- PLI Scheme Alignment:India's production-linked incentive framework for specialty chemicals offers capital subsidy pathways for compliant chromophore investments.
Industry Challenges
- Analytical Chemist Scarcity:Tinctorial strength standardization and impurity profiling require specialized synthetic organic expertise that commands premium compensation.
- Multi-Jurisdiction Certification Timelines:Parallel ECHA dossier preparation, SAMR testing protocols, and BIS documentation create 18-24 month product launch cycles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basic Violet 10 Market Trends and Innovations
Process automation and regulatory data digitization are compressing batch release timelines, while buyer consolidation across South Asia's textile belt is reshaping supplier relationship structures.
Closed-loop synthesis systems with real-time spectroscopic monitoring are automating impurity detection during Michler's ketone condensation. Mid-scale dyestuff manufacturers in Gujarat and Shandong are adopting these systems to reduce off-spec batches. The technology is automating quality assurance workflows that previously required manual sampling and external laboratory verification.
China's SAMR enforcement of updated GB standards for industrial chemical imports is mandating testing at designated laboratories before customs clearance. Foreign suppliers must pre-register substance compositions and purity certificates to avoid port detention. Powder-grade exporters to plastic compounding houses face the steepest compliance burden under these protocols.
Long-term offtake agreements with fixed pricing tiers are displacing spot-market purchasing among Bangladesh fabric finishers. Regional dye houses are consolidating orders through purchasing cooperatives to secure volume discounts and technical service priority. This contractual shift is most visible in Dhaka's export-oriented garment supply chain, where lead time predictability outweighs price flexibility.
Basic Violet 10 Market Segmentation
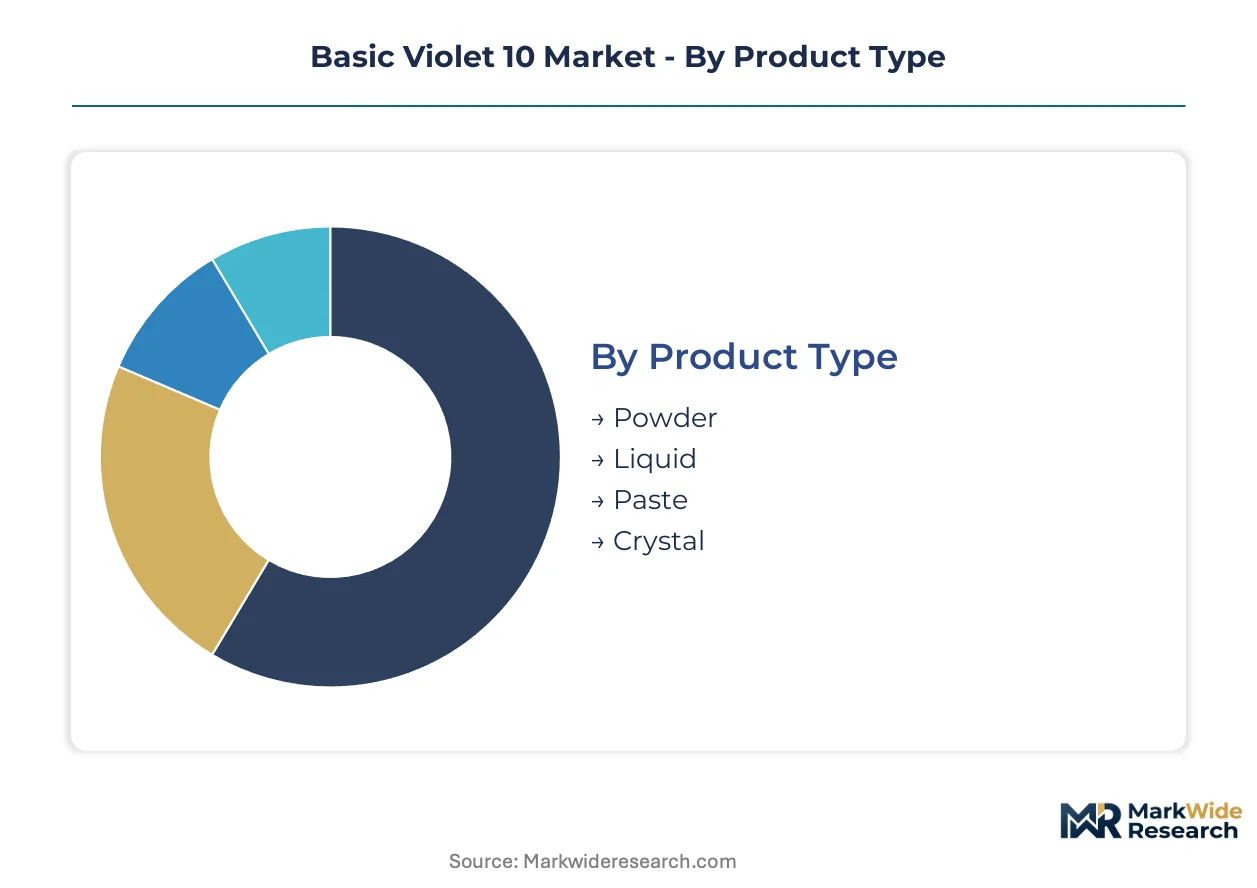
Basic Violet 10 procurement decisions hinge on dissolution kinetics, substrate compatibility, and regulatory certification tiers. Formulators across textile, leather, and ink channels select physical formats and purity grades based on specific end-use performance thresholds rather than commodity pricing alone.
Product Type:
Buyers prioritize freight economics and shelf stability against dissolution speed and dust exposure limits when selecting physical formats.
- Powder:The chloride salt in granular form offers extended stability and containerized shipping efficiency. Textile manufacturers in Bangladesh absorb the largest volumes, though dust handling costs are pushing some ink formulators toward alternatives.
- Liquid:Pre-dissolved aqueous solutions eliminate dust exposure and accelerate production line integration. Ink manufacturers in Japan specify liquid grades for continuous feed systems where dissolution kinetics directly determine throughput rates.
- Paste:Semi-solid concentrates serve leather tanneries requiring controlled viscosity for hide penetration.
- Crystal:High-purity crystalline grades command premium positioning for chrome-tanned leather applications demanding batch-to-batch color stability.
Volume sits with powder shipments; growth tilts toward liquid formulations.
Application:
Substrate chemistry and fastness requirements partition demand across fundamentally different value chains.
- Textile Dyeing:Acrylic fiber affinity drives the dominant consumption channel, with cationic dye sites binding the triarylmethane chromophore. Fabric finishers in Vietnam are consolidating purchase volumes to secure batch consistency and technical service priority.
- Leather Coloring:Chrome-tanned hide penetration requires crystal-grade purity for uniform color development without mottling. Italian tanneries sustain premium pricing for specialized grades with superior light-fastness profiles.
- Paper Printing:Specialty packaging applications utilize basic violet for security and decorative finishes.
- Ink Production:Solvent-based and aqueous inkjet formulations incorporate liquid grades for reduced particulate contamination.
- Plastic Staining:Acrylic and polystyrene compounding houses specify powder grades with defined dispersion rates for masterbatch production.
Textile dyeing absorbs the largest volume share; leather coloring maintains the steepest margin structure.
End User:
Scale economies and technical service requirements stratify the customer base into distinct procurement segments.
- Textile Manufacturers:Integrated dye houses and commission finishers in South Asia dominate order volumes, with purchasing cooperatives in Dhaka consolidating demand for pricing leverage.
- Leather Goods Producers:Full-grain upholstery and automotive hide suppliers in Italy and India specify certified grades for luxury positioning.
- Ink Manufacturers:Japanese formulators anchor supply relationships through ISO-certified production protocols and dedicated liquid formulation supply agreements.
- Plastic Fabricators:Masterbatch compounders seek powder-grade customization with specific particle size distributions for extrusion compatibility.
Procurement scale concentrates with textile manufacturers; technical service intensity peaks with ink manufacturers.
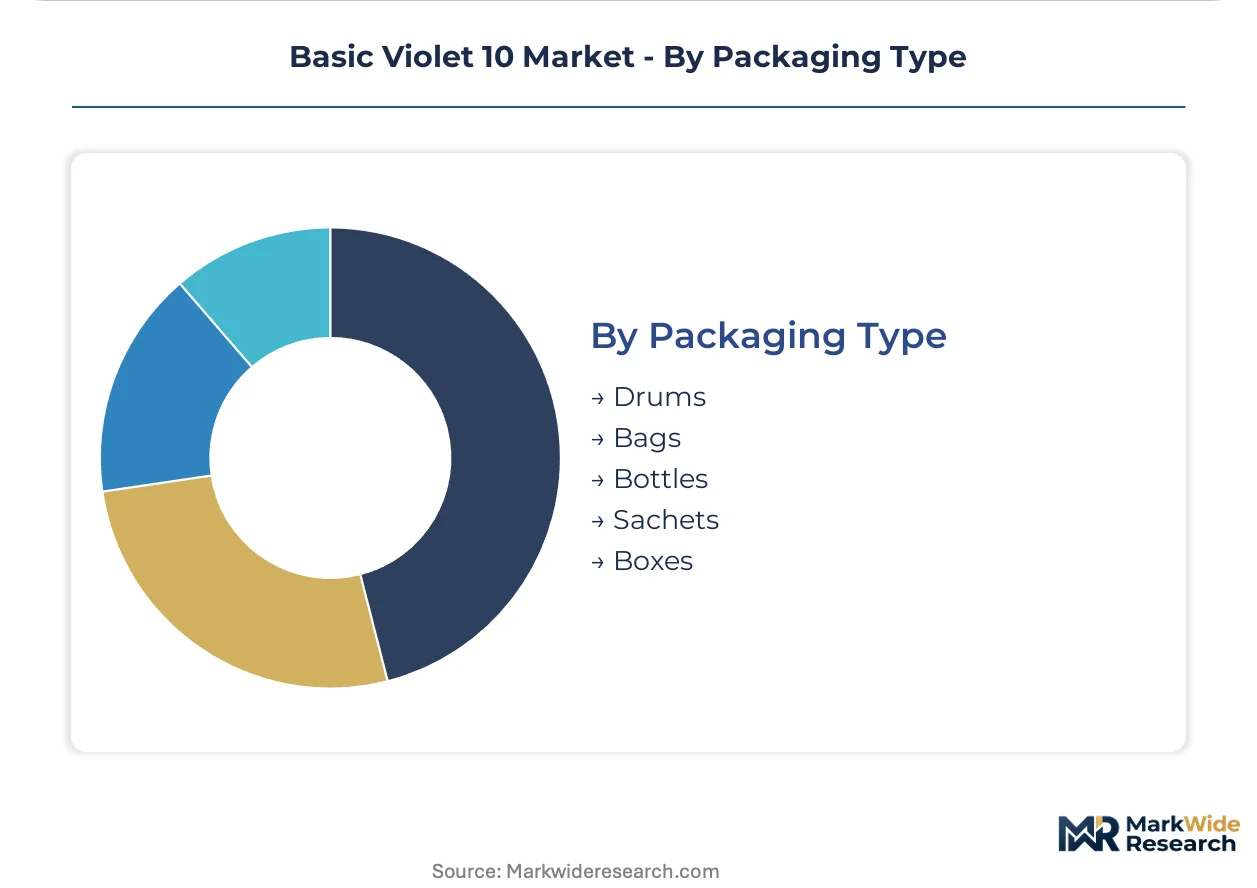
Packaging Type:
Container selection balances contamination risk, handling automation, and order fragmentation across customer tiers.
- Drums:Steel and fiber drums serve bulk textile and leather operations with automated dispensing systems.
- Bags:Multi-layer paper and woven polypropylene sacks dominate powder shipments to large-scale dye houses.
- Bottles:Laboratory and sample quantities for formulation development and quality verification.
- Sachets:Pre-weighed single-batch units for small tanneries and specialty finishers lacking bulk handling infrastructure.
- Boxes:Corrugated containers with inner liners for crystal-grade variants requiring physical protection.
Drums and bags capture industrial volume; sachets address fragmentation in the long tail of small-batch users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Textile dyeing operations in Bangladesh and Vietnam are absorbing larger Basic Violet 10 volumes as regional apparel manufacturing scales, while regulatory tightening across Europe and China is reshaping supplier qualification criteria.
China
Powder-grade production clusters in Shandong and Jiangsu provinces supply international formulators with standardized chloride salt grades. SAMR enforcement of updated GB standards mandates pre-registration of substance compositions at designated laboratories before customs clearance. Tianjin's dyestuff chemical factories are consolidating batch release workflows through automated spectroscopic monitoring systems.
Bangladesh
Fabric finishing houses in Dhaka's export-oriented garment supply chain are multiplying order volumes to secure pricing leverage and technical service priority. The country's national textile regulator maintains import quality protocols for industrial dye shipments. Purchasing cooperatives in Gazipur and Narayanganj are displacing spot-market purchasing with long-term offtake agreements featuring fixed pricing tiers.
Vietnam
Acrylic fiber expansion in Binh Duong and Dong Nai provinces is driving cationic dye absorption as regional synthetic textile output climbs. The Ministry of Industry and Trade oversees chemical import licensing with purity documentation requirements. Ho Chi Minh City-based dye houses are consolidating purchase volumes to secure batch consistency from certified suppliers.
India
Leather tanneries in Kanpur and Kolkata sustain crystal-grade demand for chrome-tanned hide penetration with superior color stability. BIS certification for textile chemicals is tightening heavy metal content thresholds, forcing reformulation investments among export-oriented suppliers. Gujarat's mid-scale dyestuff manufacturers are adopting closed-loop synthesis systems to reduce off-spec batches.
Italy
Full-grain upholstery and automotive hide suppliers specify certified grades for luxury positioning in Milan and Tuscany tanning corridors. ECHA REACH registration dossiers filter out non-compliant suppliers, consolidating demand among certified manufacturers with established EU market access. Arzignano's leather industrial district maintains premium pricing for specialized grades with superior light-fastness profiles.
Basic Violet 10 Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue liquid formulation specialization and regional certification compliance. The supplier base concentrates among Chinese powder-grade manufacturers with captive Michler's ketone condensation capacity, while Japanese and Indian specialists anchor premium segments through ISO-certified protocols. Three archetypes dominate: scale-driven bulk suppliers, purity-focused crystal-grade specialists, and formulation-integrated ink channel partners. Competitive moves center on backward integration into aromatic feedstocks and geographic expansion through BIS and REACH pre-certification investments.
Within the formulation-integrated tier, KIWA Chemical Industry Co., Ltd. and Ranbar Chemical Corporation exemplify supply relationships anchored through certified production protocols. Among Chinese scale producers, Tianjin Xiangrui Dyestuff Co., Ltd. occupies a position representing powder-grade customization capabilities. Veeraco Colourants Private Limited sits within the India-based specialist archetype pursuing heavy metal compliance certification gaps.
| Leading Market Players |
|---|
| Veeraco Colourants Private Limited |
| KIWA Chemical Industry Co., Ltd. |
| Ranbar Chemical Corporation |
| Mayur Dye Chem |
| Tianjin Xiangrui Dyestuff Co., Ltd. |
| Dezhou Hongqiao Dyestuff Chemical Co., Ltd. |
| Hebei Ruixin Chemical Co., Ltd. |
| Xincheng Weiye Chemical Co., Ltd. |
| Tianjin No.3 Dyestuff Chemical Factory |
| Others |
Pricing and Supply Chain Analysis
REACH registration dossiers and China's GB standard updates gate qualified supply access while simultaneously stratifying premium-tier pricing for compliant manufacturers serving EU and China-bound channels. Buyers without certified supplier relationships face port detention risks and reformulation costs that compress their pricing flexibility against established competitors.
Pricing Analysis
Volume concentrates in powder-grade shipments to Bangladesh textile houses while margins peak with crystal-grade variants for Italian leather tanneries. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered crystal grades from BIS-compliant powder grades and uncertified economy tiers. Cost compression in standard powder grades is intensifying because Michler's ketone feedstock volatility squeezes synthesis margins. Commission finishers in Dhaka's purchasing cooperatives exhibit highest price sensitivity; Japanese ink formulators anchored through ISO-certified protocols show lowest sensitivity due to dissolution kinetics requirements.
Supply Chain Analysis
Dual-sourcing requirements from formulators in Japan and Italy mandate multi-supplier qualification across Chinese powder-grade producers and Indian crystal-grade specialists. Geographic supply concentration centers on China, India, and Bangladesh for production and formulation respectively. Raw material dependencies draw from aromatic chemical feedstocks, Michler's ketone condensation precursors, and chloride salt reagents. Single-source vulnerability persists in eastern China's captive condensation capacity clusters. Distribution runs through containerized bulk shipments to textile dye houses, with liquid formulations moving through dedicated chemical logistics channels to ink manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop synthesis automation is displacing manual quality assurance workflows, compressing batch release timelines and resetting competitive thresholds for mid-scale manufacturers across Gujarat and Shandong.
For Market Incumbents: Acquire automated spectroscopic monitoring systems to defend batch consistency premiums against emerging entrants with digitized quality assurance. Backward integration into Michler's ketone condensation capacity anchors margin control against aromatic feedstock volatility. Prioritize parallel ECHA dossier maintenance and BIS heavy metal compliance investments to preempt regulatory obsolescence of legacy product lines. For New Entrants and Emerging Players: Capture India's BIS certification gap by investing in heavy metal threshold compliance ahead of reformulation-lagged export-oriented competitors. Liquid formulation specialization for Japanese ink channels offers the most penetrable entry point, with dust-reduced dissolution systems opening dedicated supply relationships unavailable to powder-grade incumbents. Pursue technical service partnerships with Ho Chi Minh City dye houses consolidating purchase volumes. For Investors and Strategic Acquirers: Adoption rates of closed-loop synthesis systems among Gujarat mid-scale manufacturers is the leading indicator that automation-enabled quality assurance will consolidate share from manual-process competitors. Long-term viability favors producers with captive feedstock integration and multi-jurisdiction certification portfolios rather than spot-market suppliers. Target acquisition archetype: ISO-certified regional specialists with pre-qualified ECHA or BIS dossiers and established technical service relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Feedstocks | Michler's ketone condensation capacity anchors margin control against volatile precursor pricing from Shandong chemical suppliers. |
| Closed-Loop Synthesis Automation | Real-time spectroscopic monitoring reduces off-spec batches for Gujarat manufacturers competing on batch consistency. |
| Multi-Jurisdiction Certification Investment | Parallel REACH and BIS dossier preparation opens EU and India channels that filter out non-compliant competitors. |
| Liquid Formulation Specialization | Dust-reduced dissolution systems secure dedicated supply relationships with Japanese ink formulators seeking faster kinetics. |
| Long-Term Offtake Agreements | Fixed pricing tiers with Dhaka purchasing cooperatives displace spot-market volatility for volume-priority textile finishers. |
Research Methodology
Multi-period observation of regulatory dossier filings, customs clearance patterns, and purchasing cooperative formation anchored the trend analysis, supplemented by interviews with dye house procurement leads, leather tannery technical directors, ink formulation chemists, and chemical distribution channel managers. Secondary validation drew from ECHA registration databases, SAMR GB standard update notices, BIS certification records, and trade flow documentation. Bottom-up volume estimates from individual producer capacities and top-down demand calibration from end-use consumption patterns were triangulated to cross-verify market sizing.
Segment-weighting across product type, application, and end-user dimensions informed the analytical framework throughout the projection horizon. Grade tier stratification, regional production hub classification, and packaging format differentiation were modeled alongside purity certification levels and dissolution kinetics specifications. CAGRs were derived from trend extrapolation of volume absorption rates in Bangladesh and Vietnam textile clusters, adjusted for regulatory compliance timeline impacts on qualified supply availability.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Michler's ketone feedstock price volatility, REACH substance restriction list expansions, and substitution acceleration by reactive dyes in wash-fastness-intensive applications. Deviation in BIS heavy metal threshold enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.