
 United States Iodine Market | 2026-2036
United States Iodine Market Size, Share, and Industry Trends Forecast 2026-2036
United States Iodine Market Analytics
Capital-intensity divergence between brine extraction specialists and chemical processors is reorganizing competitive tiers in domestic iodine supply. Iofina plc leverages its vertical integration across Oklahoma brine fields and downstream halogen chemistry. American Elements sustains a differentiated position through high-purity iodine compounds for electronic and pharmaceutical grades. Deepwater Chemicals Inc. anchors its operations in Tennessee manufacturing corridors with specialized iodine derivative production.
Iodine is a halogen element with atomic number 53, typically recovered from caliche ore or brine aquifers through blowout reduction or ion exchange, then refined to purity levels exceeding 99.8% for pharmaceutical and electronic applications. The element serves as an essential feedstock for X-ray contrast media, biocides, and catalytic intermediates. Crystalline iodine and iodine derivatives command premium positioning due to stringent USP and ACS certification requirements that limit qualified suppliers. Pharmaceutical applications absorb the largest value share, while disinfectant formulations face margin compression from substitute chemistries.
FDA pharmaceutical standards, EPA toxic substance reporting under TSCA, and OSHA workplace exposure limits collectively shape iodine handling protocols and product liability frameworks across the value chain. These requirements elevate compliance costs for smaller distributors while reinforcing barriers around direct sales channels to regulated end users. Stakeholders must track evolving EPA risk evaluations for halogenated compounds and FDA guidance on iodinated contrast agent safety signals.
Market Dynamics
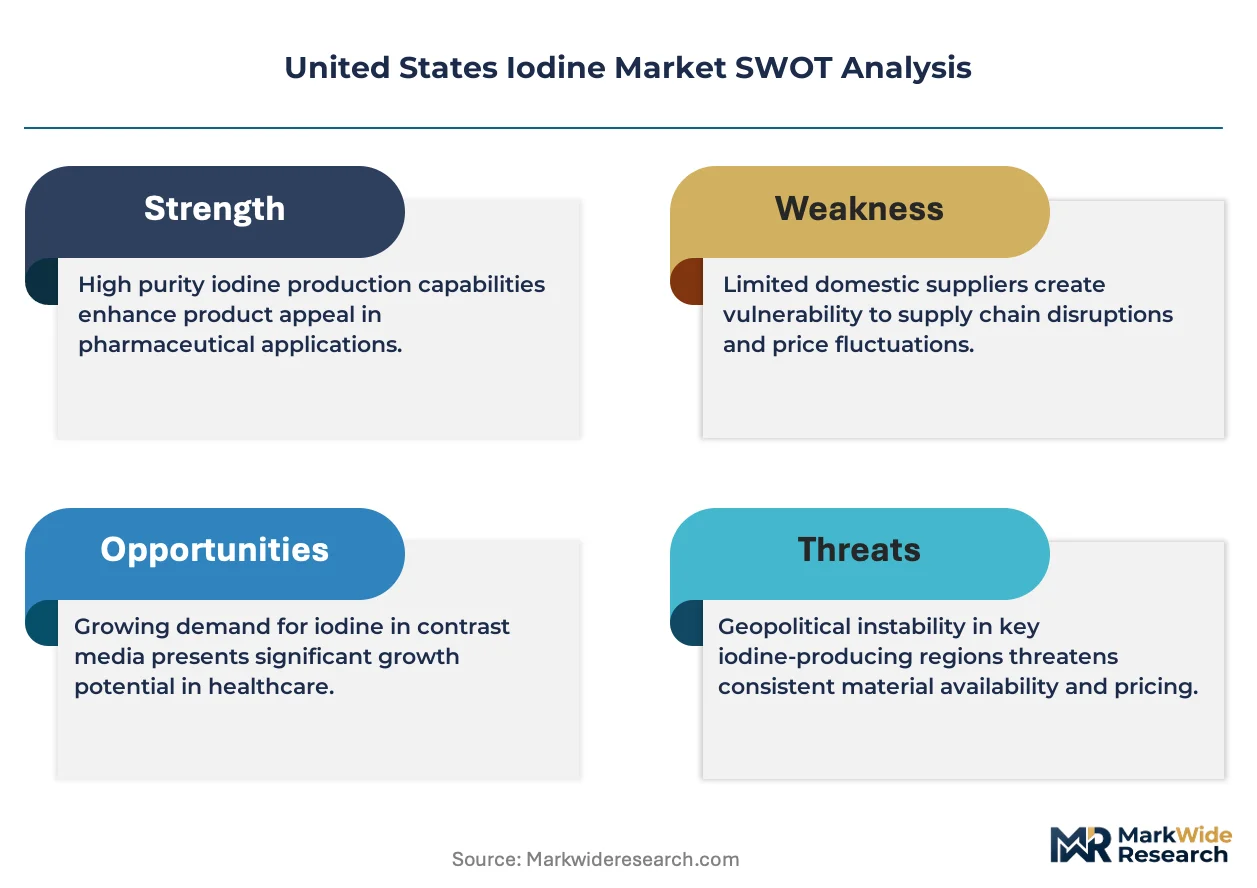
Pharmaceutical purity mandates from the FDA are compressing qualified supplier pools while concentrating procurement authority among vertically integrated chemical processors with captive brine assets.
Growth Catalysts
- Diagnostic imaging expansion:X-ray contrast media formulations are absorbing record iodine volumes as hospitals replace older imaging suites with digital angiography systems across the Great Lakes corridor.
- EPA biocide registrations:Updated antimicrobial efficacy protocols are widening approved iodine-based disinfectant applications in food processing and municipal water treatment.
- Oklahoma brine field development:Deep aquifer access in the Anadarko Basin is expanding domestic feedstock security for downstream halogen chemistry operations.
Market Restraints
- Caliche ore import dependence:Chilean nitrate deposits supply the majority of global iodine feedstock, exposing US processors to Andean supply disruptions and currency volatility.
- Chlorine-based substitution:Quaternary ammonium compounds and peracetic acid formulations are displacing iodine in surface disinfection protocols across institutional cleaning markets.
- OSHA permissible exposure limits:Workplace vapor concentration caps below 0.1 ppm are elevating abatement capital requirements for Tennessee and Texas manufacturing facilities.
Strategic Opportunities
- Gulf Coast petrochemical integration:Corpus Christi and Lake Charles halogen derivative clusters offer co-location synergies for iodine recovery from brine co-produced with oil and gas extraction.
- IRA clean manufacturing credits:Inflation Reduction Act provisions for low-carbon chemical processing are incentivizing electrolytic iodine reduction technology retrofits.
- Electronic-grade iodine demand:Semiconductor etchant and LED phosphor applications are opening premium pricing tiers for 99.99% purity material beyond pharmaceutical specifications.
Industry Challenges
- Halogen chemist scarcity:Specialized expertise in brine chemistry and redox process engineering is concentrating among retiring specialists at Tennessee Valley Authority corridor facilities.
- USP-NF certification timelines:Pharmaceutical-grade iodine qualification cycles now exceed 18 months, freezing new entrants from regulated medical applications.
- Legacy ERP integration:Batch manufacturing execution systems at established Gulf Coast plants resist real-time traceability upgrades demanded by FDA pharmaceutical quality agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Iodine Market |
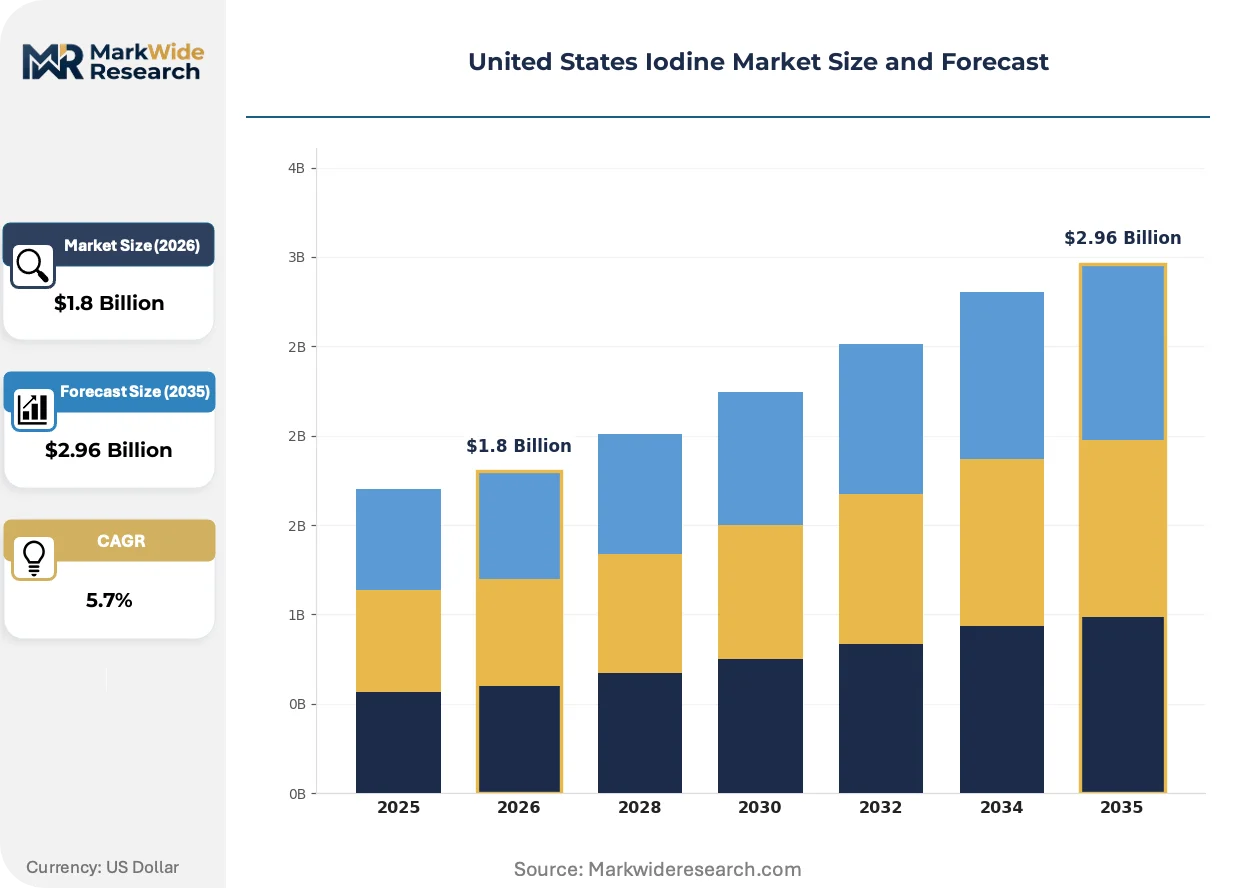
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Iodine, Iodine Solutions, Iodine Powders, Iodine Derivatives Application: Pharmaceuticals, Food Additives, Chemical Intermediates, Disinfectants End User: Healthcare, Agriculture, Chemical Industry, Viticulture Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Iofina plc, American Elements, IOCHEM Corporation, Deepwater Chemicals Inc., KIVA Holding Inc., ISE Chemicals Corporation, Merck KGaA, Thermo Fisher Scientific Inc., SQM S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Iodine Market Evolving Landscape
Process intensification and regulatory digitization are reshaping how iodine moves from brine extraction through pharmaceutical formulation, with automation investments concentrating in the highest-purity tiers.
Ion exchange resin technology is bifurcating the extraction landscape. Blowout reduction methods still dominate Oklahoma brine operations, but selective resin systems are capturing dissolved iodine at lower concentrations. Pharmaceutical manufacturers with direct offtake agreements are specifying resin-derived material for contrast media synthesis. This technology is bifurcating supplier tiers between integrated resin operators and traditional blowout reduction facilities.
FDA pharmaceutical excipient guidance updates are tightening elemental impurity thresholds. The 2023 revisions to USP <232> and <233> chapters are forcing iodine refiners to install ICP-MS detection systems for heavy metal traces. Contract manufacturers serving generic drugmakers face the steepest compliance capital requirements. Tennessee and Puerto Rico formulation facilities are consolidating supplier lists to pre-qualified refiners with documented validation packages.
Hospital procurement consortia are consolidating iodine-based antiseptic purchasing. Group purchasing organizations now negotiate multi-year supply agreements for povidone-iodine formulations across integrated delivery networks. Independent distributors are losing shelf space to direct manufacturer relationships. This consolidation is most visible in the Texas Medical Center and Cleveland Clinic system supply chains, where standardized formularies now specify single-source iodine compound suppliers.
United States Iodine Market Segmentation
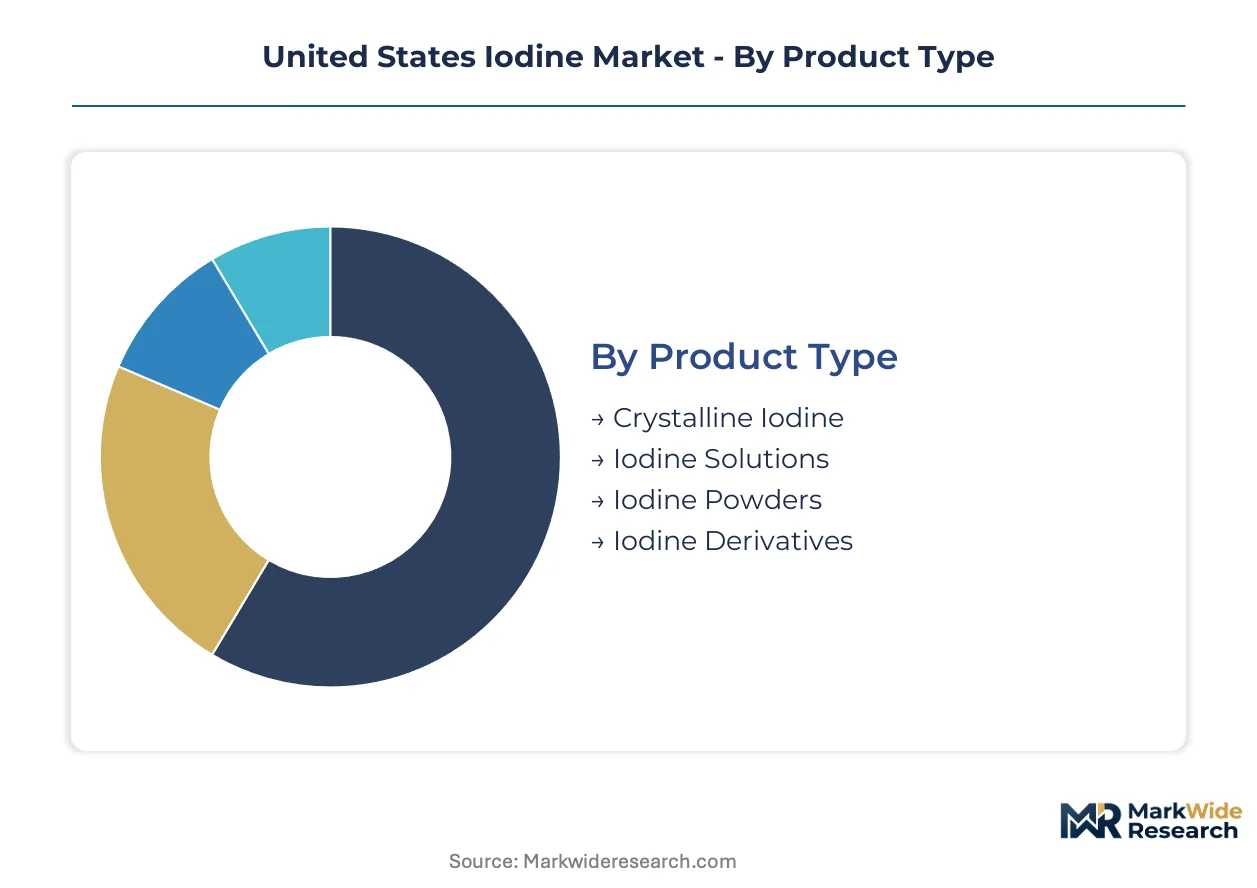
Iodine value pools fragment across purification grades, end-use specifications, and channel access tiers. Understanding where margin concentrates within each dimension reveals procurement leverage points and supplier differentiation strategies.
Product Type:
Premium margin pools concentrate in pharmaceutical-grade derivatives and high-purity crystalline forms, while commodity powders compete on scale economies.
- Crystalline Iodine:Elemental iodine recovered through blowout reduction or ion exchange, refined to 99.8% purity for USP certification. Oklahoma brine field operators and Tennessee refiners supply this grade for contrast media synthesis. FDA excipient standards now mandate ICP-MS trace detection, elevating qualified supplier barriers.
- Iodine Derivatives:Organoiodine compounds including povidone-iodine, potassium iodide, and iodoform serve as antiseptic actives and catalytic intermediates. Pharmaceutical manufacturers in the Great Lakes corridor absorb the largest volumes for X-ray contrast formulations. Resin-derived material commands premium positioning over traditional blowout reduction feedstock.
- Iodine Solutions:Aqueous and alcoholic preparations for laboratory and disinfection applications.
- Iodine Powders:Ground elemental iodine for industrial blending and feed additive compounding.
The dominant share belongs to Iodine Derivatives, while Crystalline Iodine is closing the gap fastest as resin extraction technology expands.
Application:
Application value correlates inversely with substitution risk — pharmaceutical uses resist displacement while surface disinfection faces chlorine-based erosion.
- Pharmaceuticals:Contrast media for digital angiography systems, antiseptic formulations, and thyroid therapeutics. Hospital procurement consortia in the Texas Medical Center and Cleveland Clinic system now negotiate multi-year supply agreements for povidone-iodine, consolidating purchasing authority among integrated delivery networks.
- Disinfectants:Iodophore formulations for food processing, municipal water treatment, and institutional cleaning. EPA biocide registration updates are widening approved applications, though quaternary ammonium compounds and peracetic acid continue displacing iodine in surface protocols.
- Food Additives:Iodized salt fortification and animal feed supplementation.
- Chemical Intermediates:Catalytic reagents for halogenation and oxidation reactions.
Pharmaceuticals captures the largest value pool, with Disinfectants expanding most quickly on EPA registration tailwinds.
End User:
End-user procurement sophistication determines channel access — healthcare systems demand validated supply chains while agriculture tolerates commodity sourcing.
- Healthcare:Hospitals, diagnostic imaging centers, and pharmaceutical manufacturers requiring USP-NF certified material with 18-month qualification cycles. Group purchasing organizations now specify single-source iodine compound suppliers across standardized formularies.
- Chemical Industry:Halogen derivative processors and specialty chemical manufacturers in the Gulf Coast petrochemical corridor.
- Agriculture:Feed additive compounders and soil amendment distributors.
- Viticulture:Winery sanitation and grape processing applications.
Healthcare dominates procurement value, while Chemical Industry is gaining share fastest on Gulf Coast integration projects.
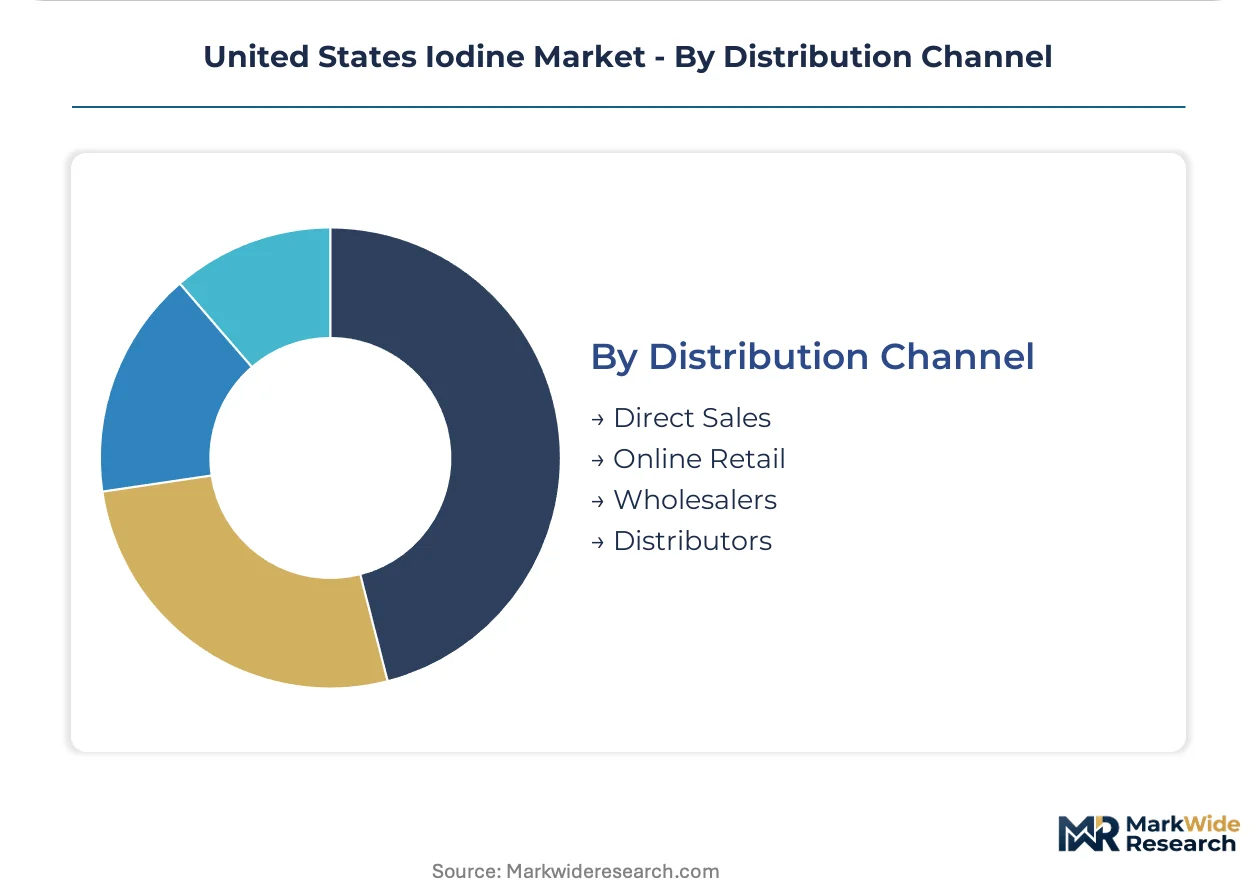
Distribution Channel:
Channel economics invert with purity tier — direct sales capture pharmaceutical premiums while wholesalers handle commodity flows.
- Direct Sales:Manufacturer relationships with pharmaceutical formulators, hospital consortia, and electronic-grade buyers. FDA quality agreements and real-time traceability requirements favor this channel for regulated applications.
- Distributors:Regional chemical distributors serving smaller compounders and industrial blenders.
- Online Retail:Laboratory supply and small-volume specialty chemical platforms.
- Wholesalers:Bulk commodity movements for agricultural and industrial feedstock.
Direct Sales holds the largest margin pool, with Distributors climbing fastest as mid-tier chemical processors consolidate supplier lists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across US sub-regions. Healthcare procurement consortia in Great Lakes metro areas show low price sensitivity for pharmaceutical-grade material, while agricultural buyers in the Mountain West tolerate commodity sourcing with minimal specification requirements.
Oklahoma and the Anadarko Basin
Deep aquifer brine operations anchor domestic feedstock security. Oklahoma Corporation Commission permitting for Class II injection wells shapes extraction economics. Iofina plc operates integrated blowout reduction facilities across Woodward and Alfalfa counties, supplying crystalline iodine to Tennessee refiners.
Tennessee Valley Manufacturing Corridor
Specialized halogen chemistry plants concentrate iodine derivative production. EPA Region 4 air quality permits limit expansion timelines for vapor-intensive processes. Deepwater Chemicals Inc. maintains Tennessee operations serving pharmaceutical formulators with USP-certified material.
Texas Gulf Coast Petrochemical Hub
Corpus Christi and Lake Charles halogen derivative clusters offer brine co-production synergies with oil and gas extraction. Texas Commission on Environmental Quality flare reduction mandates are accelerating electrolytic technology retrofits. Hospital procurement consortia in the Texas Medical Center negotiate multi-year povidone-iodine supply agreements.
Great Lakes Chemical Corridor
Digital angiography system deployments across Cleveland Clinic and University of Michigan Health networks drive contrast media absorption. FDA pharmaceutical excipient standards enforcement concentrates purchasing authority among pre-qualified refiners. Chicago-area group purchasing organizations standardize iodine compound formularies across integrated delivery networks.
Puerto Rico Pharmaceutical Manufacturing
FDA-regulated formulation facilities serve as a secondary demand node for high-purity iodine imports. USP-NF certification timelines exceeding 18 months freeze new supplier entry. San Juan-area contract manufacturers consolidate supplier lists to validated refiners with documented ICP-MS validation packages.
United States Iodine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Brine extraction specialists with captive aquifer access compete on feedstock security, while downstream refiners compete on purity certification and pharmaceutical customer relationships. Three archetypes dominate: vertically integrated brine-to-derivative processors, high-purity specialty refiners, and import-dependent commodity distributors. Competitive moves center on backward integration into brine assets and qualification timeline acceleration for FDA-regulated customers.
Within the integrated extraction-and-refining tier, Iofina plc and Deepwater Chemicals Inc. exemplify the brine-field-to-pharmaceutical-supply-chain model. American Elements occupies a position among high-purity compound specialists serving electronic and pharmaceutical grade specifications. These three companies represent the dominant competitive archetypes: captive feedstock control, premium purity positioning, and regulated-channel access concentration.
| Leading Market Players |
|---|
| Iofina plc |
| American Elements |
| IOCHEM Corporation |
| Deepwater Chemicals Inc. |
| KIVA Holding Inc. |
| ISE Chemicals Corporation |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| SQM S.A. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Oklahoma brine field operations shapes feedstock economics and downstream price floors. Blowout reduction facilities running above 80% utilization anchor crystalline iodine pricing, while ion exchange resin operators extract premiums from pharmaceutical offtake agreements.
Pricing Analysis
Extended supply contracts with hospital procurement consortia drive lifetime value for iodine derivative manufacturers. Three-tier pricing structure across pharmaceutical-grade, electronic-grade, and industrial-grade levels separates USP-certified material from commodity feedstock. Pricing pressure stems from Chilean caliche ore import volatility and currency exposure. Agricultural feed additive buyers exhibit highest price sensitivity, while healthcare systems accept premium positioning for validated supply chains.
Supply Chain Analysis
Strategic stockpiling of resin feedstock dominates pharmaceutical-tier procurement, while just-in-time delivery suffices for industrial blending applications. Domestic supply draws from Oklahoma brine fields, Tennessee refining corridors, and Gulf Coast petrochemical co-production. Key inputs include deep aquifer brine, sulfuric acid for reduction processes, and ion exchange resins. Single-source vulnerability concentrates in Chilean nitrate deposit dependence. Distribution runs through direct manufacturer relationships for regulated grades and regional chemical distributors for commodity flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resin extraction technology and FDA pharmaceutical excipient digitization are accelerating competitive restructuring. The Inflation Reduction Act's clean manufacturing credits create additional inflection pressure.
For Market Incumbents: Consolidate backward integration into captive brine assets in the Anadarko Basin to secure feedstock against Chilean supply disruptions. Deepen pharmaceutical customer relationships through accelerated USP-NF qualification packages, compressing 18-month timelines where possible. Chlorine-based disinfectant substitution and quaternary ammonium compound displacement threaten iodine market share in surface sanitation applications. For New Entrants and Emerging Players: FDA fast-track certification for electronic-grade iodine specifications offers the most penetrable entry path, as semiconductor etchant demand outpaces qualified supplier capacity. Target LED phosphor manufacturers and specialty chemical compounders in the Gulf Coast corridor. Lead with ion exchange resin technology positioning to differentiate from legacy blowout reduction incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors brine-field operators with downstream halogen chemistry capabilities over pure-play refiners. Long-term viability rests on captive aquifer access and pharmaceutical channel lock-in. Monitor EPA risk evaluation timelines for halogenated compounds as the critical inflection signal for regulatory-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Oklahoma Corporation Commission permitting secures Class II injection well access for captive feedstock. |
| ICP-MS Detection System Installation | FDA USP <232> and <233> compliance enables pharmaceutical-grade material qualification. |
| Resin Extraction Technology Deployment | Ion exchange systems capture dissolved iodine at lower concentrations than blowout reduction methods. |
| Hospital Consortium Direct Contracts | Texas Medical Center and Cleveland Clinic system agreements bypass independent distributor channels. |
| Electrolytic Reduction Retrofit | IRA clean manufacturing credits subsidize low-carbon iodine processing technology upgrades. |
Research Methodology
Desk research of FDA pharmaceutical excipient guidance, EPA TSCA reporting databases, and OSHA permissible exposure limit documentation preceded structured interviews with halogen chemistry plant managers, pharmaceutical procurement leads at group purchasing organizations, ion exchange technology specialists, and Tennessee Valley Authority corridor process engineers. Primary fieldwork combined with secondary validation from customs trade records, SEC chemical company filings, and American Chemistry Council halogen sector reports. Bottom-up brine field capacity estimates triangulated against top-down pharmaceutical demand projections.
Variance decomposition across grade tier, end-use industry, and regional production hub segmentation dimensions shaped analytical framework development over the projection horizon. CAGRs derived from electrolytic technology adoption curves, hospital imaging suite deployment schedules, and EPA biocide registration approval timelines. Modeled inputs included Oklahoma brine field extraction economics, Chilean peso-denominated caliche ore import costs, and resin technology capital expenditure requirements.
Decision-makers should treat outputs as directional under stable FDA excipient standards and continued IRA credit availability; material deviation would warrant model refresh. Specific risk factors include Andean supply disruptions, OSHA vapor concentration limit revisions, and chlorine-based disinfectant substitution acceleration. Revision becomes warranted when EPA halogenated compound risk evaluations cross regulatory action thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Triazine Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Fine Hydrate Market