
 Carbide Grinding Wheel Market | 2026-2036
Carbide Grinding Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Carbide Grinding Wheel Market Insights
Asset-light leasing models for precision grinding equipment is narrowing the capital barrier for mid-tier fabricators seeking superabrasive capability. Saint-Gobain Abrasives leverages captive ceramic grain technology to sustain premium positioning across vitrified bond lines. Tyrolit Group anchors Central European supply through vertically integrated diamond synthesis operations. Klingspor AG differentiates via specialized resin formulations for tungsten carbide tool reconditioning.
Carbide grinding wheels are precision abrasive tools engineered with synthetic diamond or cubic boron nitride grains bonded to steel or aluminum cores, typically operating at peripheral speeds exceeding 35 m/s for material removal rates below 0.1 mm per pass. These tools perform critical dimensional finishing on cemented carbide cutting inserts, rotary tools, and wear-resistant components where conventional alumina abrasives fail. Vitrified bond wheels dominate high-volume manufacturing lines where thermal stability during flood-cooled creep-feed grinding protects carbide substrates from cobalt binder phase degradation. Metal bond segments capture aerospace blade root profile grinding where extended wheel life outweighs higher initial cost. Resin bond systems lead electronics sector demand for dicing and edge profiling of carbide substrate wafers.
OSHA permissible exposure limits for respirable crystalline silica directly shape bonded abrasive formulation choices and on-machine ventilation requirements in US fabrication shops. REACH restrictions on phenolic resin precursors and cobalt dust classifications under ECHA guidelines compel European manufacturers toward water-based bond chemistries and sealed cabin designs. EPA hazardous waste rules for spent wheel disposal influence aftermarket service economics and wheel reclamation program adoption. Stakeholders must track evolving MEE emissions standards in China and their downstream effects on carbide tool export certification costs.
Market Dynamics
Hybrid ceramic bond matrices are compressing wheel life cycles and forcing resin bond incumbents to defend installed base positions through rapid formulation turnover.
Growth Catalysts
- Aerospace turbine blade finishing:OEM tolerance tightening on root profiles and airfoil surfaces drives superabrasive wheel consumption for creep-feed grinding operations.
- REACH phenolic precursor restrictions:ECHA pressure on formaldehyde-based resins accelerates water-based and hybrid ceramic bond adoption across European precision machining clusters.
- Carbide tool regrinding services:Stuttgart-Solingen concentration of precision reconditioning shops anchors aftermarket wheel procurement with predictable replacement cycles.
Market Restraints
- Synthetic diamond feedstock volatility:HPHT and CVD diamond synthesis energy intensity ties wheel cost structures to electricity pricing swings in major producing regions.
- Cobalt binder dust classification:ECHA carcinogen designation for respirable cobalt elevates sealed-cabin grinding system costs and extends capital approval timelines.
- Metal bond wheel premium:Extended aerospace blade grinding life comes at 40-60% initial cost penalty versus vitrified alternatives, compressing adoption in price-sensitive segments.
Strategic Opportunities
- Asset-light precision grinding leasing:Equipment-as-a-service models lower capital barriers for mid-tier fabricators seeking superabrasive capability without ownership risk.
- Electronics sector dicing demand:Carbide substrate wafer edge profiling for semiconductor packaging creates high-volume resin bond wheel consumption outside traditional metalworking.
- MEE emissions standards compliance:China's tightening industrial air quality rules create certification service opportunities for wheel manufacturers with verified low-emission bond systems.
Industry Challenges
- Creep-feed grinding process engineering:Flood-cooled thermal management demands specialized application expertise scarce outside German and Japanese precision machining clusters.
- Spent wheel hazardous waste handling:EPA classification rules for vitrified and metal bond wheel disposal complicate aftermarket reclamation program economics and logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbide Grinding Wheel Market |
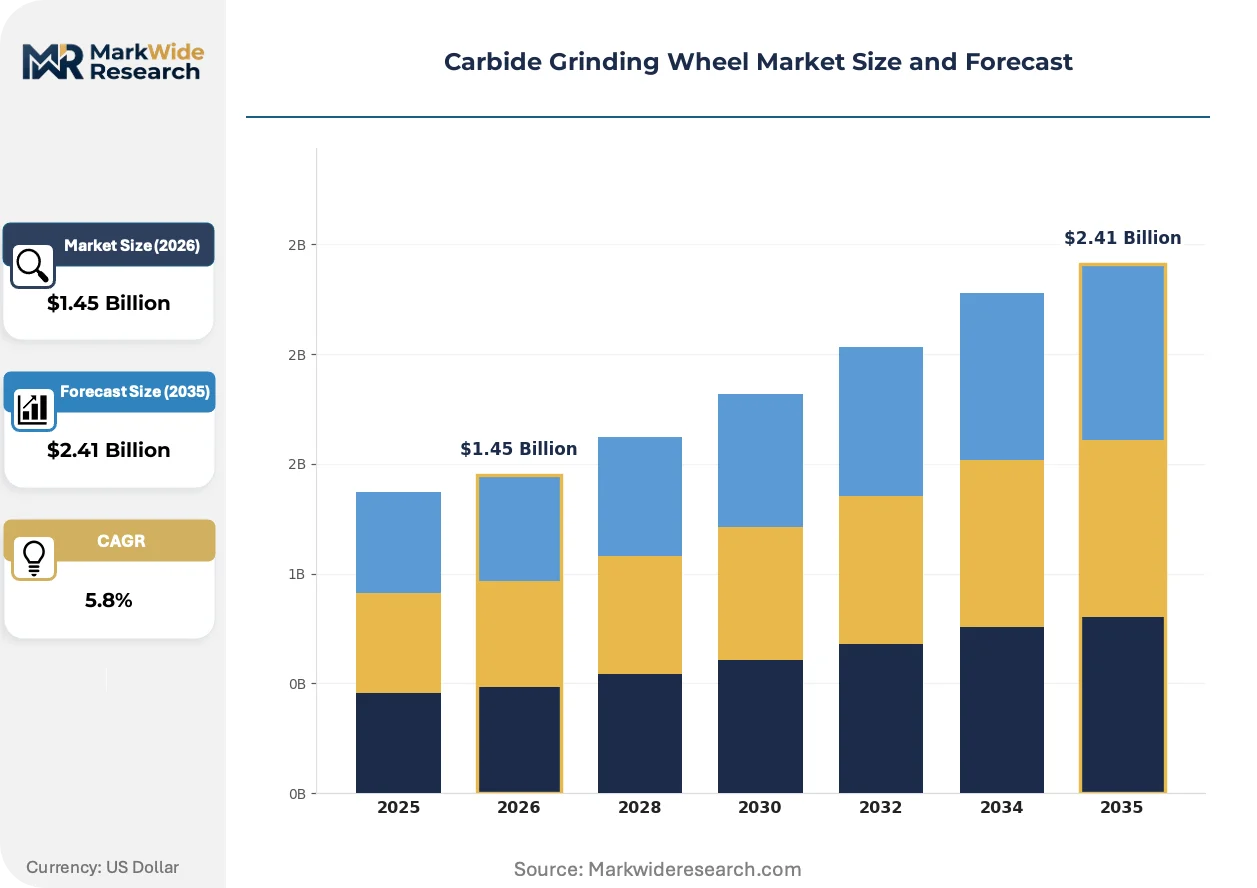
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin Bond, Vitrified Bond, Metal Bond, Electroplated Application: Manufacturing, Automotive, Aerospace, Electronics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fabricators Size: Small Wheels, Medium Wheels, Large Wheels, Custom Sizes |
| Companies Covered | Saint-Gobain Abrasives, 3M Company, Tyrolit Group, Norton Abrasives, Klingspor AG, Noritake, Carborundum Universal Limited, Asahi Diamond Industrial Co. Ltd, Abrasive Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbide Grinding Wheel Market Trends and Innovations
Active bond formulation chemistry advances and grinding process digitization are compressing traditional equipment replacement cycles and reshaping supplier-customer technical relationships.
Hybrid ceramic bond systems incorporating sol-gel alumina and engineered pore structures are rendering obsolete conventional resin bonds in high-load creep-feed applications. Aerospace blade manufacturers in Germany and the United States adopt these formulations within 18-24 month qualification windows. The technology is rendering obsolete thermal damage-prone grinding processes that previously required multiple roughing and finishing wheel changes.
OSHA respirable crystalline silica permissible exposure limits are tightening bonded abrasive workplace ventilation mandates. Fabrication shops now face capital outlays for on-machine extraction systems or bonded wheel formulation switches to low-silica alternatives. US precision grinding operations serving medical device and aerospace verticals bear the steepest compliance costs and fastest adoption timelines.
Grinding wheel specification is migrating from catalog-based procurement to collaborative process development partnerships. Tier-one aerospace OEMs now embed wheel suppliers in early-stage turbine blade manufacturing process design rather than sourcing commoditized products through distribution. This pattern concentrates most visibly in Stuttgart's precision machining ecosystem and Connecticut's aerospace corridor.
Carbide Grinding Wheel Market Segmentation
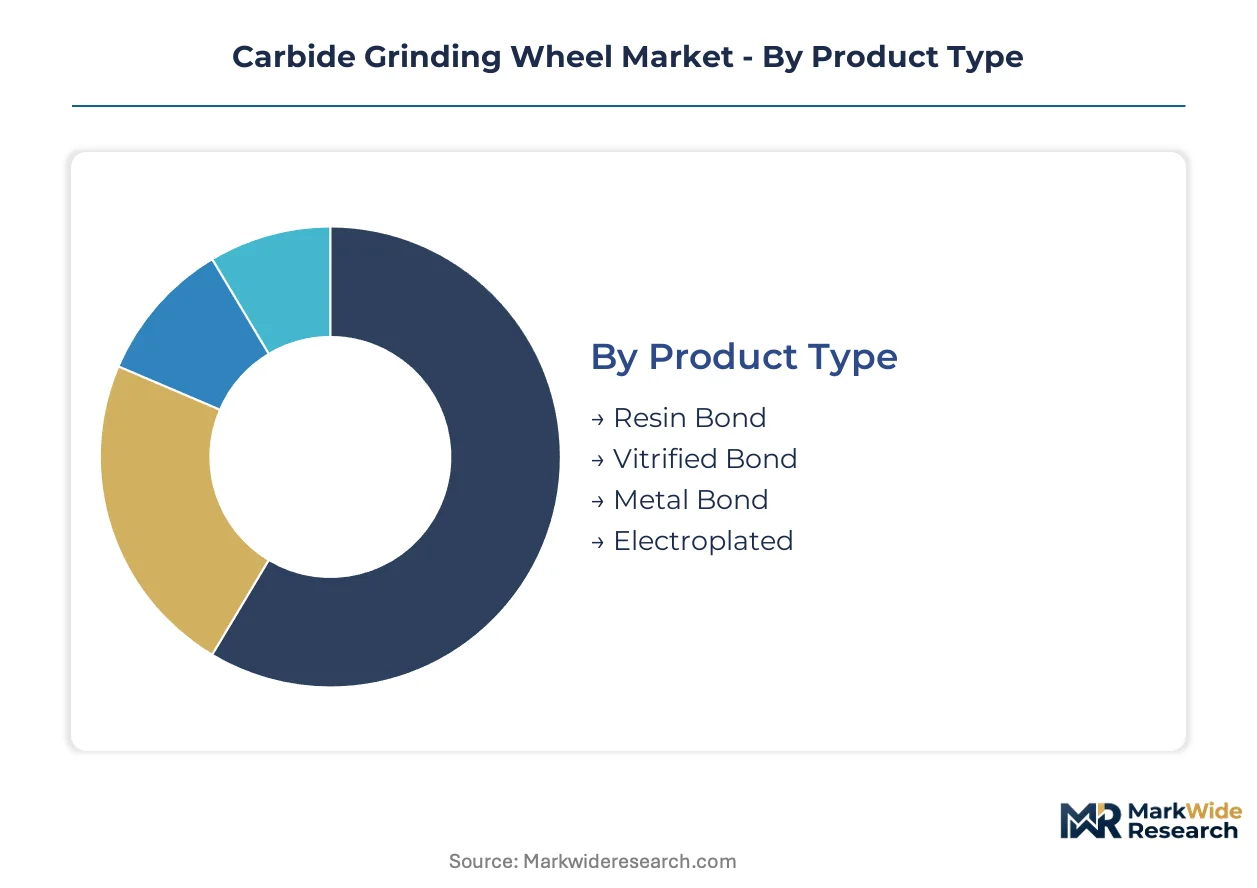
Carbide grinding wheel procurement patterns diverge sharply across bond chemistry, end-use precision requirements, and wheel geometry. Each segmentation axis reveals distinct margin structures and technical qualification barriers that shape supplier-customer relationships.
Product Type:
Mature vitrified formulations now compete against emerging hybrid ceramic matrices in high-load aerospace applications.
- Resin Bond:Phenolic and polyimide matrices provide elasticity for intricate form grinding and thermal shock resistance. Electronics sector dicing operations in Japan and Taiwan concentrate demand for thin-rim resin wheels where edge chipping must stay below 5 microns. REACH formaldehyde restrictions are forcing European manufacturers toward water-based alternatives.
- Vitrified Bond:Glass-ceramic matrices fuse aluminum oxide or silicon carbide grains with engineered porosity for coolant flow. German precision machining clusters around Stuttgart deploy these for creep-feed grinding of cemented carbide cutting inserts where thermal stability prevents cobalt binder phase degradation. Flood-cooled operations demand application expertise scarce outside German and Japanese technical centers.
- Metal Bond:Bronze or nickel matrices embed diamond grains for extended wear resistance in aerospace blade root profiling.
- Electroplated:Single-layer nickel bonding delivers aggressive material removal for rapid stock removal in tool reconditioning.
Vitrified bond retains volume leadership; hybrid ceramic matrices hold the steepest expansion curve.
Application:
Cost tiers separate commodity manufacturing from premium aerospace qualification requirements.
- Manufacturing:General metalworking shops grind cemented carbide wear parts and cutting tools with standard specification wheels. Chinese fabrication centers in Guangdong and Jiangsu provinces drive volume procurement of resin bond systems for price-sensitive regrinding operations. MEE emissions standards compliance now filters supplier selection.
- Automotive:Powertrain component finishing demands consistent dimensional control for camshaft and crankshaft tooling. German OEM supplier parks in Baden-Württemberg specify vitrified bond wheels for transmission gear carbide cutting tool reconditioning with tight geometric tolerances.
- Aerospace:Turbine blade airfoil and root profile grinding requires superabrasive wheels qualified to OEM process specifications. Connecticut and Stuttgart aerospace corridors embed wheel suppliers in early-stage manufacturing design rather than catalog procurement.
- Electronics:Carbide substrate wafer dicing and edge profiling creates high-volume resin bond consumption outside traditional metalworking.
Manufacturing captures the widest volume base; aerospace commands the highest specification premiums.
End User:
Customer type determines procurement sophistication and technical partnership depth.
- OEMs:Original equipment manufacturers specify wheels during cutting tool design and maintain approved supplier lists with 18-24 month qualification windows. Boeing and Rolls-Royce turbine blade operations in the United States and United Kingdom drive superabrasive formulation development.
- Tier-1 Suppliers:Precision machining subcontractors serving aerospace and automotive verticals purchase through distribution with technical support requirements.
- Aftermarket Providers:Specialized carbide tool regrinding services in Solingen and Stuttgart anchor predictable replacement cycles for vitrified and resin bond wheels.
- Fabricators:Independent job shops face capital barriers to superabrasive capability and increasingly access equipment through asset-light leasing models.
Aftermarket providers generate the most predictable replacement demand; OEMs drive the steepest technology adoption.
Size:
Wheel diameter correlates with machine tool capital intensity and application specialization.
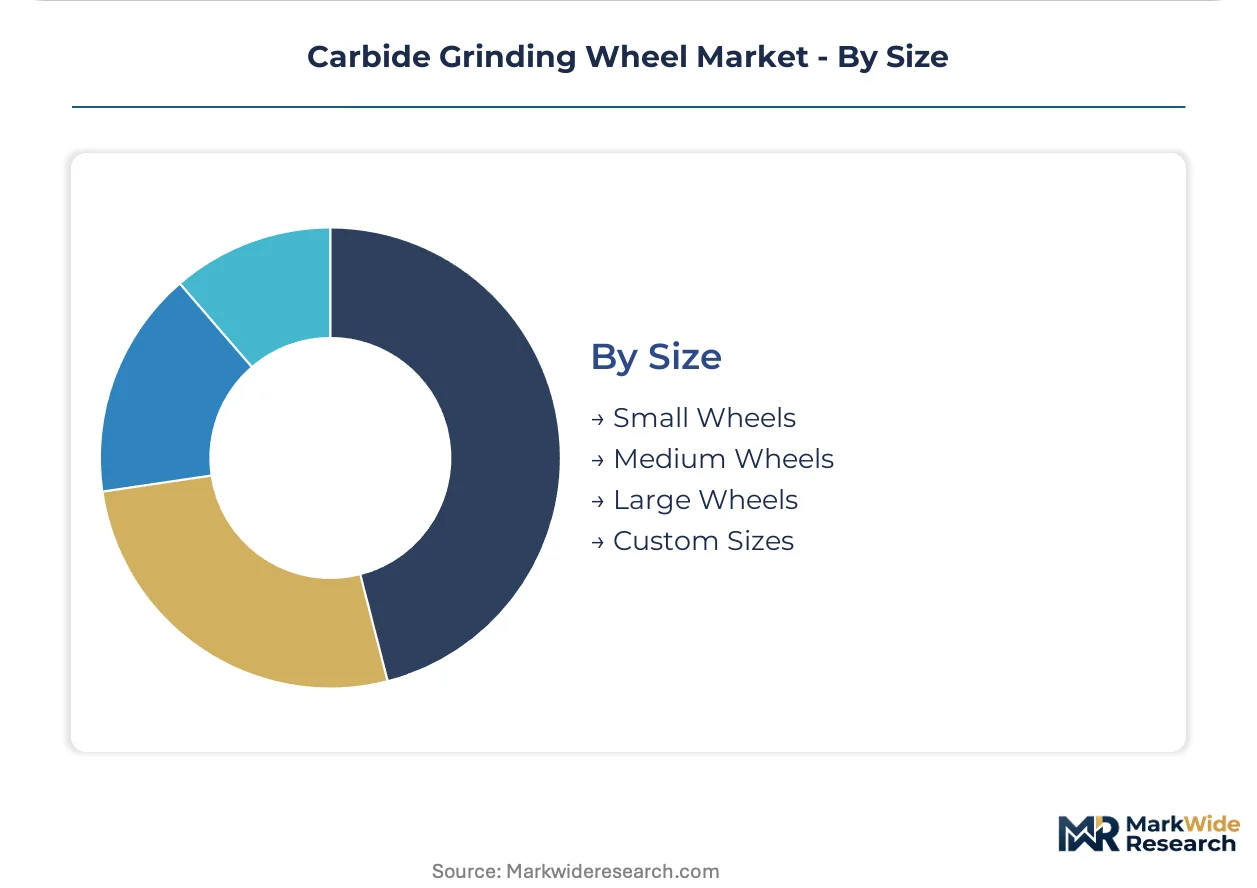
- Small Wheels:Diameters below 150mm serve tool and cutter grinding machines for rotary tool reconditioning. Japanese precision grinding equipment manufacturers dominate this specification band with integrated wheel and spindle systems.
- Medium Wheels:150-300mm diameters balance stock removal and surface finish for general carbide grinding.
- Large Wheels:Exceeding 300mm, these support creep-feed grinding of aerospace blade roots and heavy cutting inserts.
- Custom Sizes:Application-specific geometries for dedicated production lines require collaborative wheel specification and extended lead times.
Medium wheels retain the broadest installed base; custom sizes command the highest engineering margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision machining clusters anchor the highest-value procurement, while Chinese fabrication centers drive volume consumption and Japanese equipment manufacturers control small-wheel specification standards.
United States
Boeing turbine blade operations in Connecticut and Rolls-Royce engine manufacturing in Indiana drive superabrasive wheel qualification cycles. OSHA respirable crystalline silica limits tighten ventilation mandates for bonded abrasive operations. Hartford aerospace corridor embeds wheel suppliers in early-stage manufacturing process design rather than catalog procurement.
Germany
Baden-Württemberg automotive supplier parks specify vitrified bond wheels for transmission gear carbide cutting tool reconditioning. REACH formaldehyde restrictions under ECHA accelerate water-based bond chemistry adoption across European precision machining clusters. Stuttgart-Solingen concentration of tool regrinding services anchors predictable aftermarket wheel replacement cycles.
China
Guangdong and Jiangsu fabrication centers drive volume procurement of resin bond systems for price-sensitive carbide tool regrinding. MEE tightening industrial air quality standards filter supplier selection toward verified low-emission bond systems. Yangtze River Delta carbide cutting tool manufacturers face export certification cost pressure from downstream emissions compliance requirements.
Japan
Electronics sector dicing operations in Tokyo-Osaka corridor concentrate demand for thin-rim resin wheels with sub-5-micron edge chipping tolerance. METI industrial technology roadmaps prioritize grinding process digitization partnerships. Nagoya precision grinding equipment manufacturers dominate small-wheel specification bands with integrated wheel and spindle systems.
India
Bangalore and Pune automotive component suppliers expand carbide cutting tool reconditioning capacity for OEM supplier parks. BIS abrasive product standards shape import substitution patterns for bonded wheel procurement. Gujarat diamond processing hub feeds synthetic diamond feedstock into domestic wheel manufacturing operations.
Carbide Grinding Wheel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where premium qualification barriers separate aerospace-certified suppliers from commodity fabrication distributors. The vendor base organizes around three strategic archetypes: captive ceramic grain technology holders, vertically integrated diamond synthesis operators, and specialized resin formulation developers. Consolidation pressure concentrates in hybrid ceramic bond capabilities where aerospace qualification windows favor incumbents with existing OEM relationships. Geographic expansion and strategic partnerships dominate competitive moves as European and Japanese players seek Chinese market access.
Among European-headquartered suppliers, Tyrolit Group and Klingspor AG occupy distinct positioning archetypes within the premium tier. Tyrolit exemplifies the vertically integrated diamond synthesis model with Central European manufacturing concentration. Klingspor represents specialized resin formulation expertise targeting tungsten carbide tool reconditioning applications. Saint-Gobain Abrasives anchors the captive ceramic grain technology archetype across vitrified bond lines. These three structures illustrate how bond chemistry specialization and raw material control separate competitive tiers in aerospace-qualified supply.
| Leading Market Players |
|---|
| Saint-Gobain Abrasives |
| 3M Company |
| Tyrolit Group |
| Norton Abrasives |
| Klingspor AG |
| Noritake |
| Carborundum Universal Limited |
| Asahi Diamond Industrial Co. Ltd |
| Abrasive Technology |
| Others |
Pricing and Supply Chain Analysis
Stuttgart-Solingen precision machining clusters anchor European wheel supply, with captive ceramic grain technology and vertically integrated diamond synthesis creating asymmetric pricing power against resin bond competitors. MEE emissions compliance costs and REACH formaldehyde restrictions feed into bond chemistry selection, compressing margins for water-based formulation laggards while hybrid ceramic innovators capture aerospace qualification premiums.
Pricing Analysis
Certification level (ISO/CE-grade) creates the primary spread between aerospace-qualified superabrasive wheels and commodity fabrication alternatives. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified vitrified bonds from aftermarket resin systems and Chinese import alternatives. Pricing pressure stems from synthetic diamond feedstock volatility tied to electricity pricing in HPHT synthesis regions. Tier-1 aerospace suppliers demonstrate lowest price sensitivity; Guangdong job shops exhibit highest.
Supply Chain Analysis
Export-control restrictions on high-pressure high-temperature diamond synthesis equipment limit technology transfer to emerging wheel manufacturers. Supply concentrates in Germany, Japan, and China for finished wheels, with synthetic diamond feedstock drawing from Russian, Botswana, and Australian rough sources. Bronze and nickel matrix materials for metal bond wheels hinge on copper concentrate flows from Chile and Indonesia. Single-source vulnerability sits with Nagoya precision grinding equipment manufacturers controlling small-wheel spindle integration. Distribution runs through specialized industrial abrasives distributors with application engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one aerospace OEMs embedding wheel suppliers in early-stage manufacturing design, fragmenting catalog-based procurement channels. This consolidation among specification-setting customers elevates qualification barriers and compresses margin capture for non-embedded suppliers.
For Market Incumbents: Entrench aerospace certification positions through captive ceramic grain R&D investment and Stuttgart-Solingen technical service density. Hybrid ceramic bond patent estates provide defensive moats against resin bond incumbents facing REACH formaldehyde displacement. Capacity addition in Baden-Württemberg reinforces proximity to automotive OEM supplier parks. For New Entrants and Emerging Players: Pursue electronics sector dicing applications in Japan and Taiwan where sub-5-micron edge chipping tolerance creates specification barriers lower than aerospace qualification. Resin bond thin-rim wheels for carbide substrate wafer processing offer penetrable white space outside German-dominated creep-feed grinding. Go-to-market through precision grinding equipment OEMs as bundled spindle-wheel systems bypasses distributor channel control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid ceramic bond specialists with existing aerospace OEM relationships over resin formulation legacy players facing regulatory chemistry turnover. Five-to-ten year viability hinges on water-based bond patent estates and MEE emissions certification capabilities in China. The signal to watch is qualification window compression at Boeing and Rolls-Royce turbine blade operations as active bond chemistry advances accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Ceramic Bond R&D Investment | Aerospace OEMs in Connecticut and Stuttgart compress qualification windows to 18-24 months. |
| Water-Based Bond Chemistry Transition | REACH formaldehyde restrictions force European manufacturers toward ECHA-compliant alternatives. |
| Precision Grinding Equipment Leasing | Asset-light models lower capital barriers for mid-tier fabricators seeking superabrasive capability. |
| Electronics Sector Dicing Partnership | Tokyo-Osaka corridor demand for thin-rim resin wheels creates high-volume consumption outside metalworking. |
| MEE Emissions Certification Program | China's tightening air quality rules filter supplier selection toward verified low-emission bond systems. |
Research Methodology
A spread of perspectives from grinding process engineers, carbide tool regrinding service operators, aerospace OEM manufacturing specialists, bonded abrasive R&D directors, and industrial distribution channel managers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings of publicly traded abrasive manufacturers, German engineering association VDMA technical reports, Japanese METI industrial technology roadmaps, and Chinese MEE emissions compliance disclosures. Bottom-up segmentation modeling and top-down macroeconomic anchoring provided triangulation across the analysis window.
Demand-supply balance framing anchored the forecast framework, with carbide cutting tool production volumes, aerospace turbine blade manufacturing rates, and electronics wafer dicing capacity expansion serving as demand-side drivers. Modeled dimensions spanned bond chemistry type, end-use application precision tier, wheel diameter specification, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and technology adoption curve positioning, with synthetic diamond feedstock cost structures and REACH compliance timelines as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in electricity pricing for HPHT diamond synthesis, cobalt concentrate supply disruptions, or aerospace production rate adjustments would shift the trajectory. Forecasts reflect documented assumptions on hybrid ceramic bond adoption rates and MEE emissions standard enforcement intensity. Material shifts in ECHA carcinogen classification scope or export control expansion on synthesis equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Abrasive Grains Market
Abrasives
Liquid Sandpaper Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Boron Carbide Bulletproof Plate Market
Abrasives
Grinding Wheels Market
Abrasives
RDP Powder Market
Abrasives
Anthracite Fines Market
Abrasives
Boron Carbide Market
Abrasives
Super Abrasives Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Metal Abrasives Market
Abrasives
North America Abrasives Market
Abrasives
Abrasive Base Paper Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Tile Abrasion Testing Market