
 Dry Electrostatic Wipes Market | 2026-2036
Dry Electrostatic Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Electrostatic Wipes Market Foresight
Polyester-microfiber hybridization is rewriting material specifications for dry electrostatic wipes, replacing single-fiber constructions with engineered blends that trap sub-micron particles without leaving residue. SDI Systems Division Inc. leverages captive nonwoven production to control substrate consistency across electronics-grade product lines. Kimberly-Clark Worldwide Inc. sustains R&D intensity in antimicrobial surface treatments that extend wipe utility in medical environments. Procter & Gamble Co. competes through retail channel density, occupying shelf space in consumer electronics accessories segments.
Dry electrostatic wipes are engineered nonwoven or woven substrates, typically polyester or microfiber compositions, treated to generate or dissipate electrostatic charge for particle capture in controlled environments; their primary purpose is removing contaminants from sensitive surfaces without introducing static damage or chemical residue. Industrial wipes dominate volume shipments due to cleanroom maintenance cycles in semiconductor and pharmaceutical facilities, while antimicrobial wipes command premium positioning in medical equipment sterilization protocols where FDA device-surface standards apply. Spunlace manufacturing processes are displacing needlepunch methods in premium tiers because softer hand-feel reduces scratching on coated optical and display surfaces.
The EPA regulates volatile organic compound thresholds in wipe pretreatments, pushing manufacturers toward solvent-free electrostatic charging processes that comply with 40 CFR standards. OSHA cleanroom worker exposure limits shape product selection in pharmaceutical and biotechnology facilities, where particulate shedding below specified thresholds determines procurement eligibility. Stakeholders must monitor evolving ISO 14644 cleanroom classifications and RoHS material restrictions, as these frameworks increasingly specify allowable substrate chemistries and surface treatment compositions that determine market access across regulated end-use sectors.
Market Dynamics
Semiconductor fabrication expansion in East Asian manufacturing clusters is compressing procurement cycles for electrostatic discharge control materials, forcing substrate suppliers to synchronize production with fab construction timelines rather than aftermarket replacement schedules.
Growth Catalysts
- EPA 40 CFR Solvent Limits:US environmental mandates on volatile organic compound thresholds in wipe pretreatments accelerate solvent-free electrostatic charging process adoption across electronics-grade suppliers.
- ISO 14644 Cleanroom Reclassifications:Tightening international particulate standards in pharmaceutical and biotechnology facilities expand addressable demand for sub-micron particle capture substrates.
- Taiwan Semiconductor Cluster Density:Concentrated fab construction in Hsinchu and Tainan Science Parks generates synchronized bulk procurement windows for electrostatic control material vendors.
Market Restraints
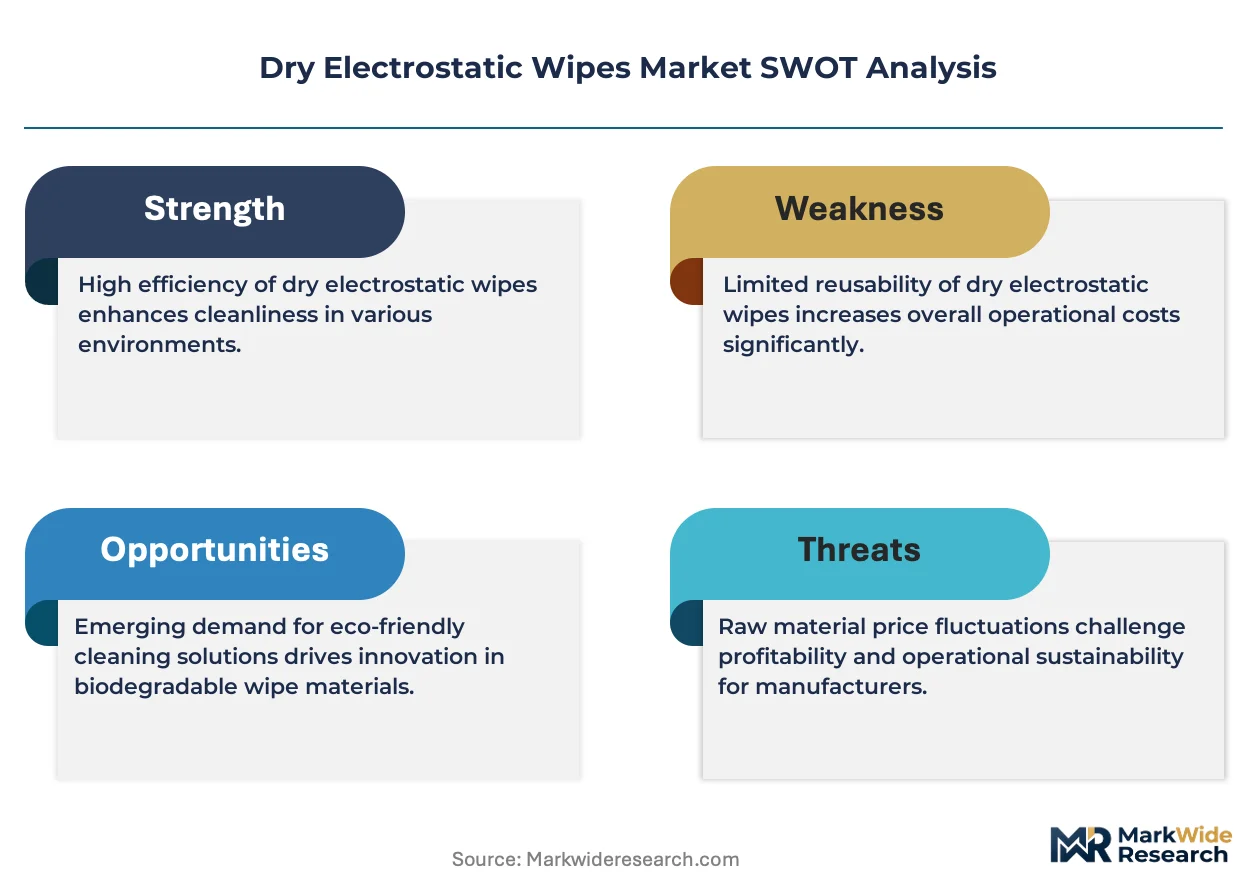
- Polyester Feedstock Volatility:Crude oil price fluctuations directly transmit to engineered microfiber substrate costs, compressing margin buffers for nonwoven converters without captive polymer supply.
- East Asian Supply Concentration:Over 70% of premium spunlace capacity sits in South Korea and Taiwan, creating geographic vulnerability to regional logistics disruptions or trade friction.
- Reusable Wipe Substitution:Launderable cleanroom garment systems with integrated static control properties capture maintenance budget share in pharmaceutical facilities with established sterilization infrastructure.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentive frameworks for semiconductor and display manufacturing create first-mover positioning for wipe suppliers establishing local substrate finishing operations.
- Antimicrobial-Static Convergence:Hybrid surface treatments combining particle capture with FDA device-surface sterilization protocols open medical equipment OEM specification channels previously segmented from industrial suppliers.
- Direct Mill Procurement Platforms:Bypassing distributor layers through B2B portals serving fab facility management teams captures margin previously allocated to regional industrial supply houses.
Industry Challenges
- Cleanroom Certification Timelines:ISO 14644-1 compliance documentation for new substrate formulations extends qualification cycles 12-18 months, delaying revenue recognition from R&D investments.
- Electrostatic Charging IP Complexity:Patent thickets around solvent-free charge-imparting processes require licensing negotiations or in-house process engineering that strains technical staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Electrostatic Wipes Market |
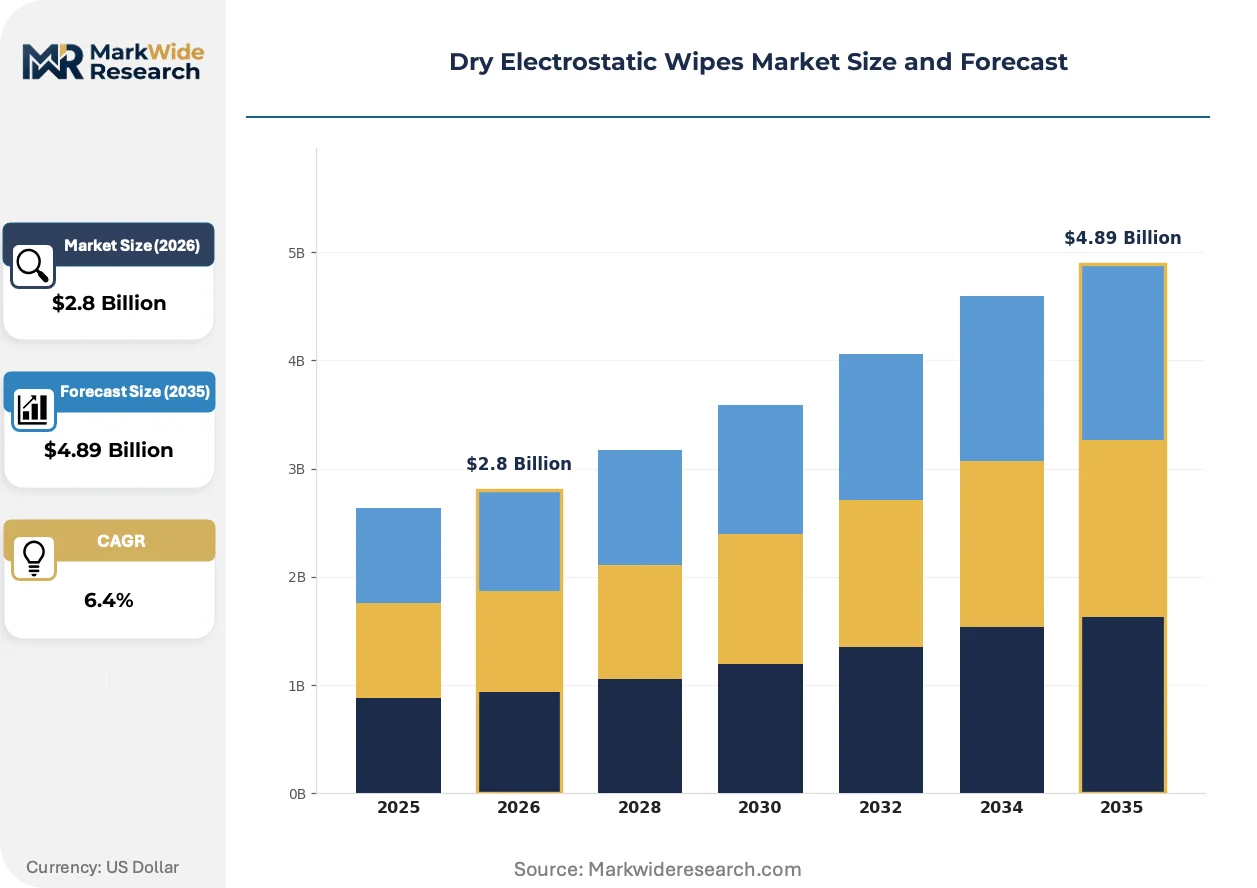
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wipes, Antimicrobial Wipes, Heavy-Duty Wipes, Industrial Wipes Material: Polyester, Microfiber, Spunlace, Nonwoven Application: Electronics Cleaning, Medical Equipment, Automotive Interiors, Industrial Machinery Customer Type: Retailers, Wholesalers, Manufacturers, End Users |
| Companies Covered | SDI Systems Division Inc., Procter & Gamble Co., Kimberly-Clark Worldwide Inc., Butler Home, Contec Inc., Chemtronics Company, Pascoes Pty Ltd., Certainty Brands, ElectroPackagings PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Electrostatic Wipes Market Shifts & Advancements
Material science convergence with digital process control is compressing development cycles for substrate performance optimization, enabling real-time charge distribution monitoring during manufacturing rather than post-batch quality testing.
Spunlace hydroentanglement with precision water-jet patterning is digitizing surface texture engineering for dry electrostatic wipes. Taiwan-based fab maintenance teams specify these substrates for coated display surface cleaning where scratch resistance outweighs cost minimization. Real-time jet pressure telemetry enables lot-to-lot charge retention consistency that needlepunch methods cannot replicate.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy anti-static surface treatments from European medical device supply chains. German pharmaceutical manufacturers now require full material disclosure documentation extending to substrate finishing chemistries. Suppliers without ECHA-compliant formulation portfolios face automatic disqualification from EU procurement tenders regardless of technical performance.
Consolidated procurement through fab facility management platforms is compressing supplier bases serving semiconductor maintenance operations. South Korean memory manufacturers now mandate single-source electrostatic control material contracts covering wipes, garments, and flooring. This bundling displaces specialized wipe vendors who lack integrated cleanroom product portfolios, concentrating specification authority with full-line suppliers.
Dry Electrostatic Wipes Market Segmentation
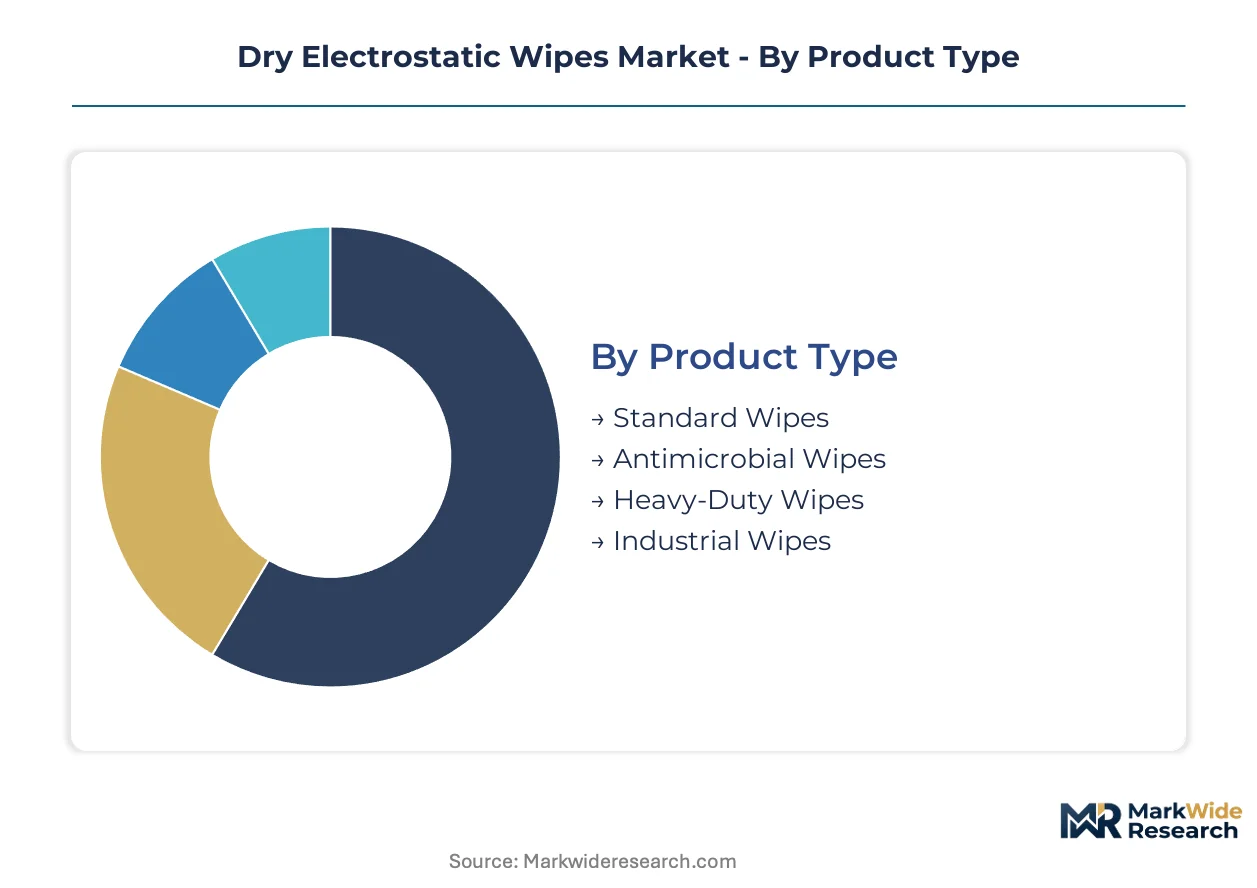
Dry electrostatic wipes serve divergent performance requirements across semiconductor fabs, hospital sterilization suites, and consumer electronics maintenance. Segmentation reveals how substrate engineering and distribution channel selection determine margin capture and specification authority in each vertical.
Product Type:
Use-case spectrum spans sterile medical protocols to heavy industrial degreasing, with each tier demanding distinct electrostatic charge retention and particle capture specifications.
- Standard Wipes:Polyester-microfiber substrates without antimicrobial finishing dominate electronics retail and general facility maintenance. Taiwan semiconductor fabs specify these for non-critical surface prep where cost minimization outweighs sterilization requirements.
- Antimicrobial Wipes:Hybrid surface treatments combining electrostatic particle capture with FDA device-surface sterilization protocols command premium positioning in hospital equipment sterilization workflows. German pharmaceutical manufacturers mandate full ECHA-compliant formulation disclosure for these products under REACH Annex XVII.
- Heavy-Duty Wipes:Dense needlepunch constructions with enhanced tear resistance serve automotive assembly line degreasing where solvent exposure degrades standard substrates.
- Industrial Wipes:Spunlace hydroentanglement with precision water-jet patterning delivers scratch-resistant cleaning for coated optical surfaces in South Korean display manufacturing clusters.
The dominant share belongs to Industrial Wipes, while Antimicrobial Wipes is closing the gap fastest.
Material:
Cost tier stratification separates premium spunlace substrates from commodity needlepunch alternatives, with raw material sourcing geography determining landed cost differentials.
- Polyester:Virgin polymer and recycled PET feedstocks form the backbone of electronics-grade electrostatic wipes, with crude oil price volatility transmitting directly to converter margins. Captive polymer supply at SDI Systems Division insulates against feedstock cost spikes.
- Microfiber:Split-fiber constructions with engineered denier profiles trap sub-micron particles without residue, specified by Taiwan fab maintenance teams for display surface cleaning where optical clarity is paramount.
- Spunlace:Hydroentangled cellulosic-synthetic blends achieve softer hand-feel than mechanical bonding methods, displacing needlepunch in premium tiers despite higher energy inputs during manufacturing.
- Nonwoven:Meltblown and spunbond substrates serve cost-sensitive industrial applications where electrostatic performance requirements are less stringent than in semiconductor environments.
Polyester retains the largest volume position, though Microfiber is expanding share most rapidly in specification-driven electronics applications.
Application:
Customer type concentration shapes procurement pattern divergence between bulk industrial contracts and fragmented retail purchasing.
- Electronics Cleaning:Sub-micron particle capture specifications align with ISO 14644 cleanroom classifications in semiconductor and display manufacturing facilities. South Korean memory manufacturers now bundle electrostatic control materials into single-source facility management contracts.
- Medical Equipment:FDA device-surface standards and OSHA worker exposure limits determine product selection in hospital sterilization protocols, with full material disclosure documentation extending to substrate finishing chemistries.
- Automotive Interiors:Scratch-resistant formulations for coated touchscreens and instrument panels match consumer electronics specifications while tolerating wider temperature cycling during vehicle assembly.
- Industrial Machinery:Heavy solvent exposure and metal particulate loads drive shorter wipe lifecycles, favoring cost-optimized substrates over performance-engineered alternatives.
Electronics Cleaning commands the dominant revenue share, with Medical Equipment exhibiting the steepest expansion trajectory as antimicrobial-static hybrid treatments penetrate hospital procurement specifications.
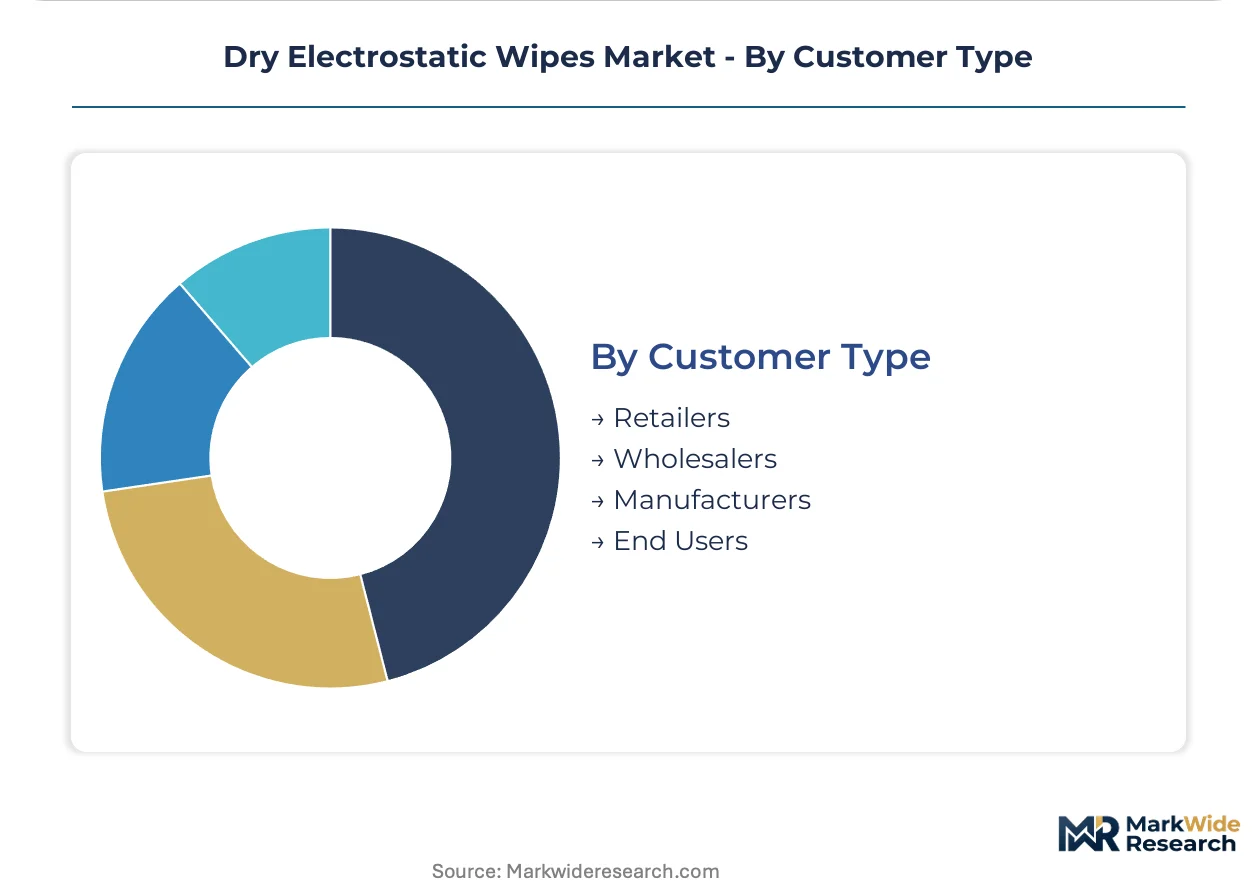
Customer Type:
Supply concentration in East Asian manufacturing clusters compresses procurement cycles and favors direct mill relationships over distributor intermediaries.
- Retailers:Consumer electronics accessories segments demand packaged wipe formats with brand recognition, where Procter & Gamble leverages shelf space density against specialized industrial suppliers.
- Wholesalers:Regional industrial supply houses aggregate demand from smaller pharmaceutical and biotechnology facilities, though consolidated fab procurement platforms are displacing this channel in semiconductor clusters.
- Manufacturers:OEM specification authority for medical device and automotive assembly line integration requires substrate consistency documentation and ISO 14644-1 compliance certification.
- End Users:Direct procurement through B2B portals serving fab facility management teams captures margin previously allocated to distribution layers, particularly in Taiwan and South Korean manufacturing parks.
Manufacturers hold the dominant procurement volume, while End Users are gaining share fastest as direct mill platforms bypass traditional distribution infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean spunlace substrate exports supply Taiwan semiconductor fabs and Chinese display manufacturers, creating a trade corridor that concentrates procurement authority in East Asian manufacturing clusters.
United States
Semiconductor fabrication expansion in Arizona and Texas drives EPA 40 CFR compliance requirements for solvent-free electrostatic charging processes. OSHA cleanroom worker exposure limits shape procurement specifications in pharmaceutical facilities across Massachusetts and North Carolina. Boston-area biotech clusters now mandate full material disclosure documentation extending to substrate finishing chemistries.
Germany
REACH Annex XVII restrictions on perfluorinated compounds eliminate legacy anti-static treatments from medical device supply chains. ECHA-compliant formulation portfolios determine EU procurement tender eligibility regardless of technical performance. Bavarian pharmaceutical manufacturers lead adoption of hybrid antimicrobial-static surface treatments for hospital equipment sterilization protocols.
South Korea
Memory manufacturer bundling of electrostatic control materials into single-source facility management contracts displaces specialized wipe vendors. Korean spunlace hydroentanglement capacity serves premium display manufacturing specifications across the region. Busan-Ulsan industrial corridors concentrate precision water-jet patterning expertise for scratch-resistant optical surface cleaning.
Taiwan
Hsinchu and Tainan Science Park fab construction generates synchronized bulk procurement windows for substrate suppliers. Taiwan Semiconductor Manufacturing Co. facility expansion compresses procurement cycles from aftermarket replacement to construction-timeline synchronization. Local maintenance teams specify microfiber constructions for sub-micron particle capture on coated display surfaces.
India
Production-linked incentive schemes for semiconductor and display manufacturing create first-mover positioning opportunities for wipe suppliers establishing local substrate finishing. Karnataka and Telangana electronics manufacturing clusters attract electrostatic control material vendors seeking to bypass East Asian supply concentration. BIS standards for cleanroom materials increasingly reference ISO 14644 classifications in procurement specifications.
Dry Electrostatic Wipes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent route-to-market strategies. The vendor base separates into three tiers: multinational consumer goods conglomerates with retail shelf dominance, captive nonwoven producers serving industrial specification channels, and regional converters supplying cost-optimized alternatives. Consolidation pressure intensifies as fab procurement platforms bypass distributor intermediaries. Strategic moves center on backward integration into substrate production and geographic expansion into emerging electronics manufacturing clusters.
Within the industrial specification tier, SDI Systems Division Inc. and Contec Inc. represent archetypes of captive manufacturing control. SDI Systems Division exemplifies vertical integration into nonwoven substrate production, insulating against polyester feedstock volatility. Contec Inc. occupies a position among specialty cleanroom material suppliers. Procter & Gamble Co. anchors the retail-channel vector, leveraging consumer electronics accessories distribution density against industrial-focused competitors. These three entities collectively illustrate the competitive structure: substrate control versus channel control versus brand recognition.
| Leading Market Players |
|---|
| SDI Systems Division Inc. |
| Procter & Gamble Co. |
| Kimberly-Clark Worldwide Inc. |
| Butler Home |
| Contec Inc. |
| Chemtronics Company |
| Pascoes Pty Ltd. |
| Certainty Brands |
| ElectroPackagings PLC |
| Others |
Supply & Pricing Matrix
Busan-Ulsan freight corridors transmit Korean spunlace substrate costs directly to Taiwan fab procurement offices, compressing margin buffers for non-captive converters while amplifying price differentiation between solvent-free electrostatic charging tiers and legacy pretreatment alternatives.
Pricing Analysis
Spunlace hydroentanglement versus needlepunch versus next-generation precision water-jet patterning defines the technology-generation pricing gap. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 14644 certification grade and substrate finishing chemistry disclosure depth. Pricing pressure stems from polyester feedstock volatility transmitting crude oil fluctuations to converter margins. Pharmaceutical facilities with sterilization infrastructure exhibit lowest price sensitivity, while automotive assembly maintenance teams drive cost-optimized procurement.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities anchor Korean and Taiwanese substrate suppliers to consolidated fab procurement platforms. Virgin PET and recycled polyester feedstocks draw from crude oil and post-consumer waste streams respectively. Single-source vulnerability concentrates in South Korean spunlace capacity serving regional display manufacturers. Distribution runs through direct mill B2B portals displacing regional industrial supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry electrostatic wipes function as a service-attach opportunity where ISO 14644-1 compliance documentation and substrate certification cycles generate recurring revenue layers expanding faster than hardware shipment volumes.
For Market Incumbents: Pre-empt reusable wipe substitution in pharmaceutical facilities by bundling antimicrobial-static hybrid treatments with sterilization protocol consulting. Captive nonwoven production insulates against polyester feedstock volatility while accelerating solvent-free process R&D to meet EPA 40 CFR thresholds.
For New Entrants and Emerging Players: Build out local substrate finishing operations in Karnataka and Telangana electronics clusters under India's PLI scheme for semiconductors. Direct mill procurement platforms serving fab facility management teams offer the most penetrable channel, bypassing entrenched distributor relationships through B2B portal integration.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer goods conglomerates with underutilized cleanroom material divisions lacking ISO 14644-1 certification infrastructure. Long-term viability hinges on substrate control rather than channel density. Watch for REACH Annex XVII enforcement acceleration in European medical device supply chains as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nonwoven Substrate Production | Captive polymer supply at SDI Systems Division insulates converters against crude oil price transmission. |
| Solvent-Free Electrostatic Charging Process Development | EPA 40 CFR compliance opens US semiconductor fabrication procurement specifications previously closed to pretreatment-dependent suppliers. |
| Antimicrobial-Static Hybrid Surface Treatment Launch | FDA device-surface sterilization protocol alignment penetrates hospital equipment OEM channels segmented from industrial suppliers. |
| Direct Mill B2B Procurement Platform Deployment | Bypassing distributor layers captures margin allocated to regional industrial supply houses in Taiwan Science Parks. |
| Local Substrate Finishing Operations in India | Karnataka and Telangana PLI scheme positioning establishes first-mover supply to emerging electronics manufacturing clusters. |
Research Methodology
The analysis maps spunlace hydroentanglement, needlepunch construction, and polyester-microfiber hybrid substrates, each validated through cleanroom facility managers, nonwoven converter procurement leads, pharmaceutical sterilization protocol officers, and semiconductor fab maintenance directors. Primary interview data triangulates against EPA 40 CFR regulatory filings, ISO 14644 classification databases, Korean trade export statistics, and SEC 10-K disclosures from listed nonwoven producers. Bottom-up substrate volume estimates reconcile with top-down electronics manufacturing capex projections.
Assumptions held fixed include current EPA solvent limits and REACH Annex XVII perfluorinated compound restrictions, while polyester feedstock cost trajectories and East Asian fab construction timelines varied across scenarios. Segmentation dimensions span product type, material composition, application vertical, and customer channel. CAGRs derive from installed base replacement cycles and new facility provisioning ratios. Forecast inputs incorporate semiconductor equipment spend patterns and pharmaceutical cleanroom reclassification schedules.
Practitioners should monitor EPA 40 CFR enforcement intensity, REACH Annex XVII expansion to additional compound classes, and India PLI scheme disbursement velocity for early signals. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Liquid Detergent Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market