
 Mexico Video Surveillance Market | 2026-2036
Mexico Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Video Surveillance Market Insights
Market Context
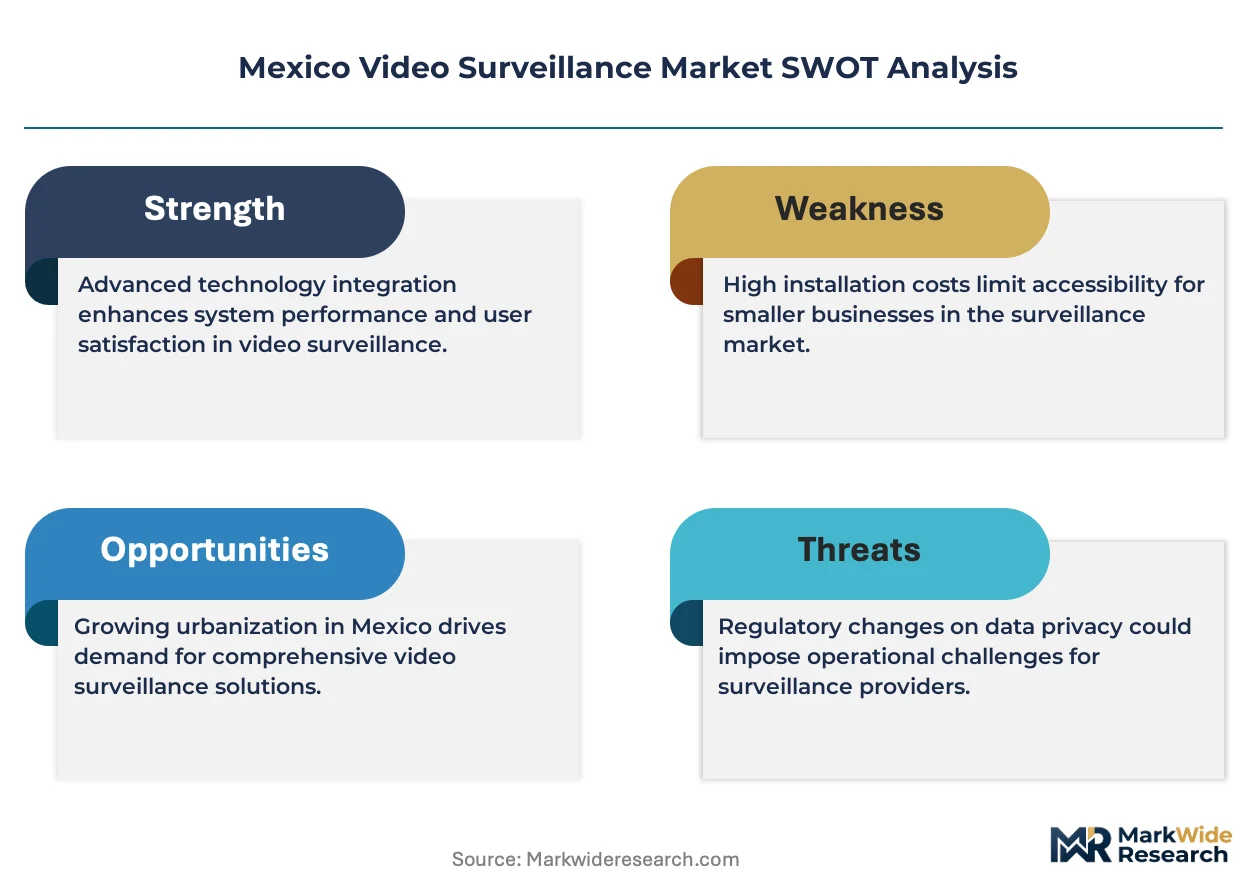
China is reconfiguring export logistics for video surveillance components bound for Latin American integrators. Hangzhou Hikvision Digital Technology Co., Ltd leverages its vertically integrated sensor fabrication to sustain cost leadership across mid-tier municipal contracts. Axis Communications AB differentiates through edge-computing firmware that reduces bandwidth loads for remote Mexican deployments. Bosch Security Systems Incorporated anchors premium positioning with explosion-certified housings serving Pemex industrial facilities.
Technical Definition and Structural Segments
Video surveillance encompasses camera hardware, video management software, and storage infrastructure that captures, transmits, and archives visual data for security monitoring, operational oversight, and forensic analysis. IP Cameras dominate new installations as Power-over-Ethernet simplifies cabling in retail and logistics environments across Guadalajara and Monterrey. Cloud-Based Solutions represent the fastest-expanding technology segment as Mexican enterprises shift from on-premise NVRs to subscription-based remote access. The Government end-user category commands the largest project values through federal public safety tenders, though Commercial adoption spreads fastest among banking and hospitality chains requiring centralized multi-site visibility.
Regulatory Framework
Mexico's Federal Law on Protection of Personal Data Held by Private Parties and the National Institute of Transparency, Access to Information and Personal Data Protection impose strict retention and consent protocols on facial recognition deployments. The Ministry of the Interior coordinates technical specifications for federal security camera networks through the National Public Security System. Stakeholders must monitor pending amendments to the Federal Telecommunications and Broadcasting Law that could reclassify encrypted video traffic under critical infrastructure cybersecurity obligations.
Market Dynamics
Federal mandates for encrypted video transmission are restructuring procurement specifications across Mexican municipalities, forcing integrators to requalify entire product portfolios around cybersecurity compliance rather than hardware cost alone.
Growth Catalysts
- Smart City Infrastructure:Municipal investments in networked camera systems across Mexico City and Guadalajara are accelerating deployment timelines for integrated public safety platforms.
- Federal Security Mandates:The National Public Security System is tightening technical specifications for government tenders, creating standardized demand pools for compliant vendors.
- Power-over-Ethernet Adoption:Simplified cabling requirements in retail and logistics environments are lowering installation barriers for IP camera upgrades.
Market Restraints
- Import Dependency:Sensor module supply concentrates among Asian fabricators, exposing Mexican integrators to shipping volatility and currency fluctuation risks.
- Data Protection Compliance:The Federal Law on Protection of Personal Data Held by Private Parties imposes costly consent and retention protocols on facial recognition deployments.
- Legacy Analog Infrastructure:Existing coaxial cable installations in aging commercial buildings create technical friction for full IP migration.
Strategic Opportunities
- Cloud Video Management:Subscription-based remote access models are penetrating mid-market enterprises previously locked out of enterprise-grade surveillance capabilities.
- Industrial Hazard Certification:Explosion-certified camera housings for Pemex facilities and petrochemical clusters command premium pricing with limited domestic competition.
- State-Level Procurement Consolidation:The State of Mexico and Nuevo León are centralizing municipal purchasing through framework agreements, favoring vendors with regional service networks.
Industry Challenges
- Cybersecurity Skill Scarcity:Network hardening and encrypted transmission configuration require specialized technician training that outpaces current certification pipeline capacity.
- Interoperability Fragmentation:Proprietary video management protocols from incumbent vendors complicate multi-brand integration for open-architecture municipal tenders.
Report Scope
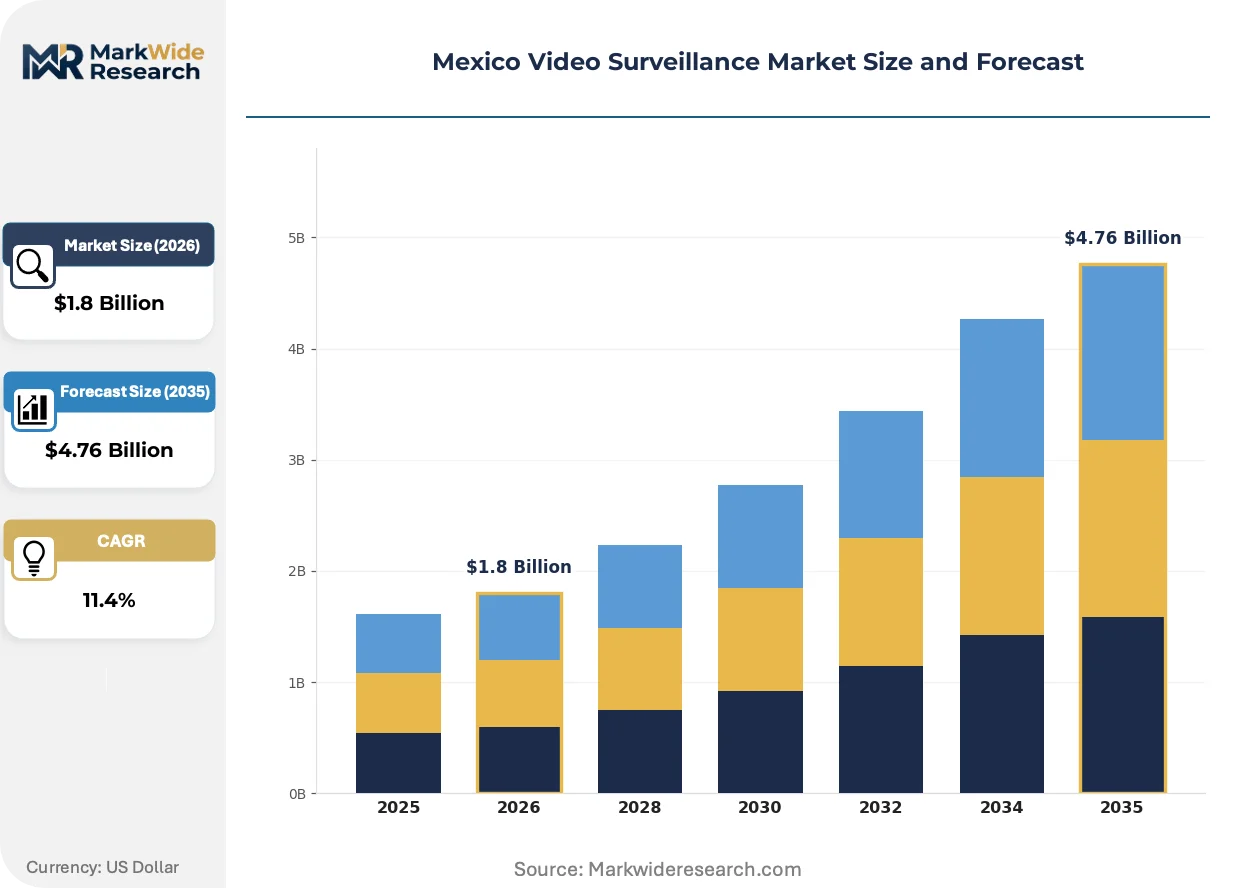
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Video Surveillance Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Cameras, IP Cameras, Hybrid Cameras, Video Recorders Installation Type: Indoor, Outdoor, Wireless, Wired End User: Commercial, Residential, Industrial, Government Technology: CCTV, 4K Surveillance, Infrared, Cloud-Based Solutions |
| Companies Covered | Axis Communications AB, Zhejiang Uniview Technologies Co., Ltd, Hangzhou Hikvision Digital Technology Co., Ltd, Hanwha Vision Co., Ltd, Honeywell Security Group, Dahua Technology Co., Ltd, Panasonic Corporation, Motorola Solutions, Inc, Bosch Security Systems Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Video Surveillance Market Trends and Innovations
Edge-computing architectures and AI-enabled analytics are compressing the traditional separation between camera hardware and backend processing, redistributing value capture across the technology stack.
On-camera video analytics with embedded GPU chipsets is rendering obsolete the centralized server farms previously required for real-time facial detection and behavioral analysis. Banking and hospitality chains across Monterrey are deploying these units to reduce bandwidth consumption on constrained last-mile connections. The shift compresses infrastructure spend toward lens-side hardware while shrinking recurring data center commitments.
The National Institute of Transparency, Access to Information and Personal Data Protection is tightening audit protocols for biometric data retention, forcing operators to demonstrate explicit consent chains or purge archived footage. This regulatory pressure is accelerating demand for edge-based processing that minimizes cloud storage of identifiable imagery. Financial services deployers in Mexico City are prioritizing vendors with local data residency certifications.
Enterprise buyers are unbundling hardware procurement from multi-year managed service agreements, treating cameras as depreciable assets while sourcing analytics and storage through separate SaaS contracts. This disaggregation pressures traditional integrators to restructure margin capture toward software subscriptions and remote monitoring fees. The pattern is most pronounced among retail chains with centralized IT governance functions.
Mexico Video Surveillance Market Segmentation
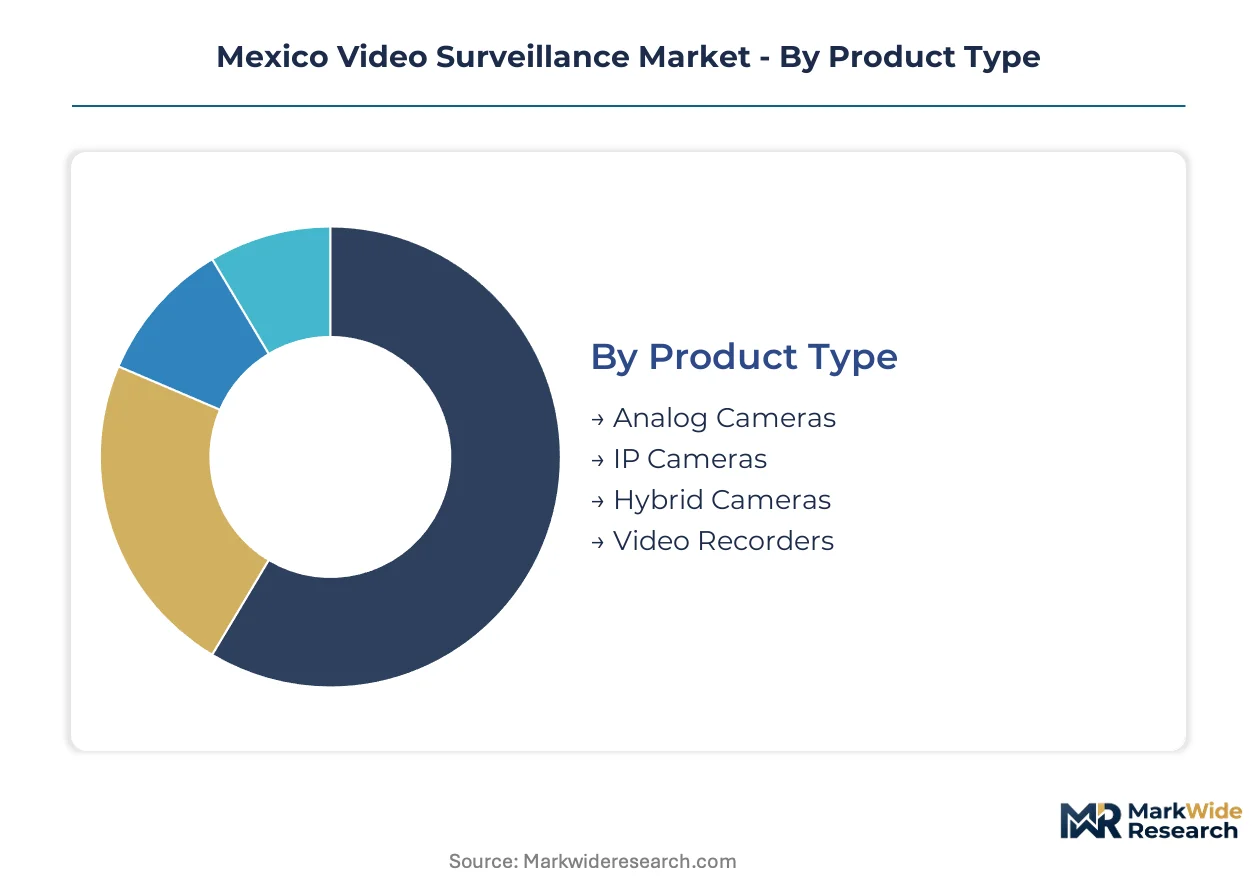
Segmentation reveals how procurement cycles, technical requirements, and compliance obligations fragment demand across distinct buyer profiles. Each dimension carries implications for product configuration, channel strategy, and margin capture.
Product Type:
Replacement cycles vary dramatically across hardware categories, with some segments turning over every 3-4 years while others persist for 7-10 years in legacy deployments.
- IP Cameras:Network-addressable units with Power-over-Ethernet capability dominate new installations across Guadalajara retail parks and Monterrey logistics hubs. Banking chains in Mexico City prioritize these for centralized multi-site visibility and encrypted transmission compliance.
- Analog Cameras:Coaxial-based legacy hardware persists in aging commercial buildings where full infrastructure replacement remains cost-prohibitive. State of Mexico municipalities with constrained budgets continue phased analog-to-IP migrations rather than wholesale replacement.
- Hybrid Cameras:Dual-protocol units bridge transitional deployments, supporting both analog and IP output to protect existing cabling investments.
- Video Recorders:Network Video Recorders and Digital Video Recorders serve as archival backends, with NVRs displacing DVRs as IP camera penetration deepens.
IP Cameras anchors the volume base while Cloud-Based Solutions (within Technology) gains share at the steepest rate.
Installation Type:
Cost tiers separate premium ruggedized outdoor deployments from standardized indoor commodity installations, with wireless commanding significant installation labor savings.
- Outdoor:Weather-sealed housings with IP66+ ratings and explosion certification serve Pemex petrochemical facilities and Nuevo León industrial corridors. These units carry 3-4x hardware premiums over indoor equivalents due to hazardous environment compliance.
- Wireless:Cellular and Wi-Fi backhaul eliminates trenching and conduit costs for remote mining operations and temporary construction sites across Sonora and Chihuahua. Bandwidth constraints limit real-time analytics deployment on these connections.
- Indoor:Standard dome and bullet form factors dominate office, retail, and hospitality environments with controlled climate conditions.
- Wired:Ethernet and coaxial infrastructure remains preferred for high-availability government and financial services deployments where wireless reliability risks are unacceptable.
Indoor deployments anchor the volume base while Wireless gains share at the steepest rate.
End User:
Customer type determines procurement modality, with government tenders favoring framework agreements and commercial buyers shifting toward subscription-based consumption.
- Government:Federal and state public safety programs drive the largest project values through National Public Security System-coordinated tenders. Mexico City and State of Mexico metropolitan crime prevention initiatives concentrate institutional purchasing power.
- Commercial:Banking, hospitality, and retail chains across Monterrey and Guadalajara demand centralized visibility across distributed sites. These buyers are unbundling hardware from managed service agreements, treating cameras as depreciable assets while sourcing analytics separately.
- Industrial:Pemex facilities and petrochemical clusters require explosion-certified housings and corrosion-resistant materials, creating premium pricing pools with limited domestic competition.
- Residential:Gated communities and high-end condominiums in Mexico City metropolitan area represent emerging demand for integrated access control and video verification.
Commercial deployments anchor the volume base while Industrial gains share at the steepest rate.
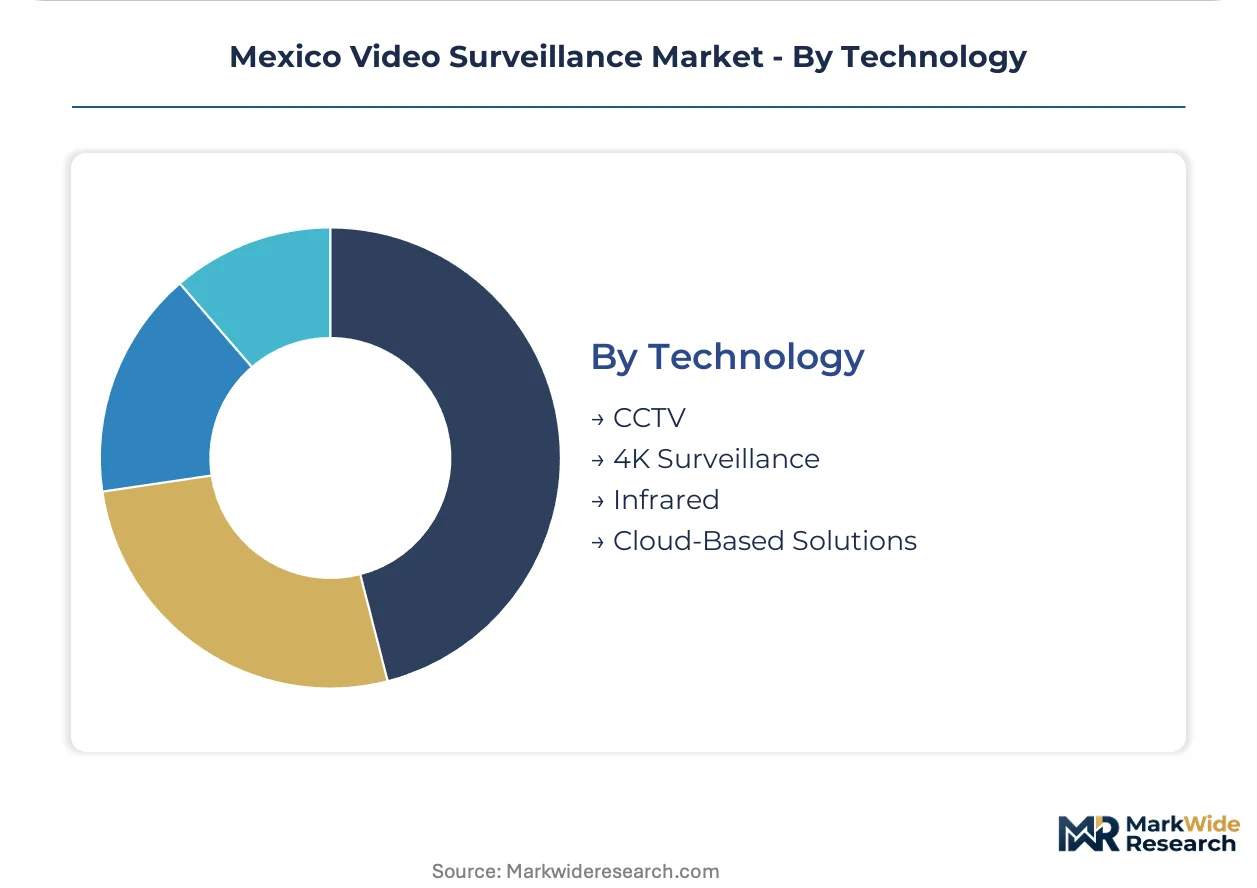
Technology:
Maturity curves separate established CCTV infrastructure from emerging cloud architectures, with 4K and infrared representing intermediate upgrade paths.
- Cloud-Based Solutions:Subscription video management eliminates on-premise server maintenance and enables remote access for mid-market enterprises previously locked out of enterprise-grade capabilities. Financial services deployers in Mexico City prioritize vendors with local data residency certifications to satisfy National Institute of Transparency audit protocols.
- 4K Surveillance:Ultra-high-definition sensors with advanced compression codecs serve forensic identification requirements in critical infrastructure and high-security financial facilities. Bandwidth and storage costs constrain deployment scale.
- CCTV:Traditional closed-circuit systems with coaxial infrastructure persist in legacy analog environments awaiting full IP migration.
- Infrared:Night-vision capability extends operational coverage for perimeter security and low-light industrial monitoring across remote installations.
CCTV anchors the volume base while Cloud-Based Solutions gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City Metro and the State of Mexico consume video surveillance infrastructure differently from northern industrial states, with metropolitan crime prevention programs driving bulk institutional purchases while Nuevo León and Jalisco prioritize industrial hazard certification and logistics visibility.
Mexico City Metro
The metropolitan crime prevention initiative concentrates federal and municipal procurement power through the National Public Security System. The Federal Law on Protection of Personal Data Held by Private Parties imposes strict retention protocols on facial recognition deployments. Banking chains and hospitality operators across the capital prioritize encrypted transmission compliance and local data residency certifications.
Nuevo León
Explosion-certified camera housings serve Pemex petrochemical facilities and industrial clusters with premium pricing and limited domestic competition. The Ministry of the Interior coordinates technical specifications for federal security networks. Monterrey anchors demand for centralized multi-site visibility across banking and hospitality chains unbundling hardware from managed service agreements.
Jalisco
Power-over-Ethernet adoption accelerates IP camera deployment across Guadalajara retail parks and logistics hubs. State-level procurement consolidation through framework agreements favors vendors with regional service networks. The Guadalajara metropolitan area drives mid-market enterprise demand for cloud-based video management with subscription-based remote access.
Bajío Region
Automotive manufacturing corridors and aerospace suppliers require perimeter security and operational oversight with integration into existing IT governance functions. The National Digital Strategy tightens cybersecurity obligations for encrypted video traffic. Querétaro and Guanajuato industrial parks deploy edge-computing architectures to reduce bandwidth loads on constrained last-mile connections.
Northern Border States
Wireless backhaul eliminates trenching costs for remote mining operations and temporary construction sites across Sonora and Chihuahua. Cellular and Wi-Fi deployments face bandwidth constraints that limit real-time analytics. Customs and logistics infrastructure at Tijuana and Ciudad Juárez drives demand for hybrid camera systems bridging transitional analog-to-IP migrations.
Mexico Video Surveillance Market Competitive Landscape
Capability concentration sits with premium-tier specialists commanding hazardous environment certifications; scale advantage sits with vertically integrated sensor fabricators serving mid-tier municipal contracts. The vendor base stratifies across three functional tiers: explosion-certified industrial specialists, edge-computing firmware providers, and cost-optimized volume suppliers. Dominant competitive moves include strategic partnerships with regional integrators and portfolio diversification into cloud-managed service layers.
Among Chinese fabricators, Hangzhou Hikvision Digital Technology Co., Ltd and Dahua Technology Co., Ltd occupy positions anchored by captive sensor production and municipal contract scale. Axis Communications AB exemplifies the edge-computing tier with firmware differentiation for bandwidth-constrained deployments. Bosch Security Systems Incorporated represents the premium industrial specialist archetype with hazardous environment certification authority.
| Leading Market Players |
|---|
| Axis Communications AB |
| Zhejiang Uniview Technologies Co., Ltd |
| Hangzhou Hikvision Digital Technology Co., Ltd |
| Hanwha Vision Co., Ltd |
| Honeywell Security Group |
| Dahua Technology Co., Ltd |
| Panasonic Corporation |
| Motorola Solutions, Inc |
| Bosch Security Systems Incorporated |
| Others |
Pricing and Supply Chain Analysis
The Manzanillo-Lázaro Cárdenas container corridor channels sensor modules and lens assemblies from Asian fabrication centers into Mexican distribution networks, with freight cost volatility transmitting directly into hardware pricing tiers and integrator margin structures across municipal and enterprise procurement cycles.
Pricing Analysis
Long-term framework agreements with state-level procurement consolidations anchor volume pricing for compliant vendors, while spot-market component sourcing serves fragmented commercial installations. Three-tier pricing structure across explosion-certified industrial, edge-computing enterprise, and cost-optimized municipal levels reflects certification grade and after-sales bundling intensity. Cost compression in mid-tier IP camera segments is intensifying because Hangzhou Hikvision Digital Technology Co., Ltd and Dahua Technology Co., Ltd leverage captive sensor production. State of Mexico municipalities with constrained budgets exhibit highest price sensitivity; Pemex industrial facilities with hazardous environment requirements demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Chinese fabricators to Mexican systems integrators bridge working capital gaps across the Pacific logistics chain, with supply-chain finance facilities increasingly standard for containerized electronics shipments. Sensor module and GPU chipset production concentrates in China, South Korea, and Taiwan; Mexican assembly draws from these inputs for final integration. Single-source vulnerability in advanced image sensor fabrication rests on concentrated Taiwanese foundry capacity. Distribution runs through Guadalajara and Monterrey regional logistics hubs serving integrator networks and direct enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico video surveillance market sits at a platform-economics inflection where unbundling of hardware from SaaS analytics is reshaping value capture, with the National Public Security System's interoperability mandates accelerating open-architecture consolidation.
For Market Incumbents: Insulate recurring revenue streams by deepening managed service penetration among banking chains unbundling hardware procurement, while accelerating edge-computing firmware R&D to defend against bandwidth-optimization challengers. Certification investment in explosion-rated housings for Pemex facilities preserves premium positioning against Chinese volume competitors. For New Entrants and Emerging Players: Mid-market commercial buildings in Jalisco and Nuevo León with aging analog infrastructure represent the most penetrable entry point, particularly hospitality chains requiring centralized multi-site visibility without enterprise IT budgets. Cloud-native subscription models with local data residency certifications bypass incumbent integrator relationships. For Investors and Strategic Acquirers: Regional service networks with state-level framework agreement qualifications and cybersecurity technician training pipelines anchor acquisition attractiveness. Long-term viability hinges on federal encryption mandate compliance breadth. The signal to watch is consolidation velocity in State of Mexico and Nuevo León municipal purchasing centralization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open-architecture VMS interoperability satisfies National Public Security System tender requirements across Mexico City metro. |
| Geographic Expansion | Regional service networks in Jalisco and Nuevo León capture state-level procurement consolidation benefits. |
| Acquisition of Specialist Firm | Explosion-certified housing manufacturers command premium pricing with limited domestic competition in Pemex corridors. |
| Product Launch | Edge-computing cameras with embedded GPU chipsets reduce bandwidth loads for constrained last-mile connections. |
| Strategic Partnership | Cloud residency certifications with local data centers satisfy National Institute of Transparency audit protocols for financial services. |
Research Methodology
A spread of perspectives from municipal procurement officers, systems integrators, cybersecurity technicians, and federal security coordinators converged on the working assumptions underlying segmentation splits and growth trajectory estimates. Primary interviews with these stakeholders combined with secondary validation against SEC filings of listed component suppliers, Mexican federal procurement databases, and customs import records for video surveillance hardware. Bottom-up channel checks across Guadalajara and Monterrey integrator networks triangulated against top-down federal budget allocation analysis.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with modeled dimensions spanning installation type, end-user category, technology architecture, and regional adoption intensity. CAGRs were derived from regression analysis of historical procurement cycles and forward-looking tender pipelines. Forecast inputs incorporated Power-over-Ethernet adoption curves and cloud migration patterns among mid-market enterprises.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates or Pacific shipping lane disruption would shift the trajectory of hardware cost structures and project deployment timelines. Forecasts reflect documented assumptions about federal mandate implementation pace and municipal budget continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market