
 Cemetery Management Software Market | 2026-2036
Cemetery Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cemetery Management Software Market Analysis
Consolidation among municipal cemetery operators into multi-site management networks is realigning vendor priorities toward enterprise-grade interoperability. PlotBox leverages cloud-native architecture to anchor large-scale public cemetery deployments across North American jurisdictions. Cemify competes through specialized mobile-first interfaces that extend field-data capture for smaller family-owned burial grounds. Chronicle differentiates via integrated genealogical mapping tools that occupy a niche between operational software and public historical record platforms.
Cemetery management software encompasses digital platforms that automate plot inventory, burial record administration, and maintenance scheduling through geospatial databases and workflow engines. These systems typically integrate GIS mapping layers with perpetual-care trust accounting modules to ensure regulatory compliance over multi-decade maintenance obligations. Cloud-based solutions dominate new procurement as public cloud deployment reduces capital expenditure for budget-constrained cemetery operators, while SaaS licensing models shift revenue toward recurring subscription streams. On-premise software retains relevance among government agencies with stringent data sovereignty requirements, though hybrid models are gaining traction where sensitive burial records demand localized storage while permitting remote staff access.
HIPAA-informed data handling protocols shape product development as funeral homes integrate deceased patient records from hospital systems, while state cemetery regulators enforce perpetual-care audit trails that mandate immutable financial ledgers. The FTC Funeral Rule additionally governs pre-need sales documentation, forcing software vendors to embed compliant contract generation tools. Stakeholders must weigh interoperability investments against the risk of fragmented municipal procurement standards that could lock cemetery districts into isolated technology ecosystems.
Market Dynamics
Cloud migration mandates from state-level records-keeping authorities are compressing replacement cycles and forcing municipal cemetery operators toward multi-site digital consolidation. This structural pressure is reshaping vendor priorities around enterprise interoperability and recurring revenue models.
Growth Catalysts
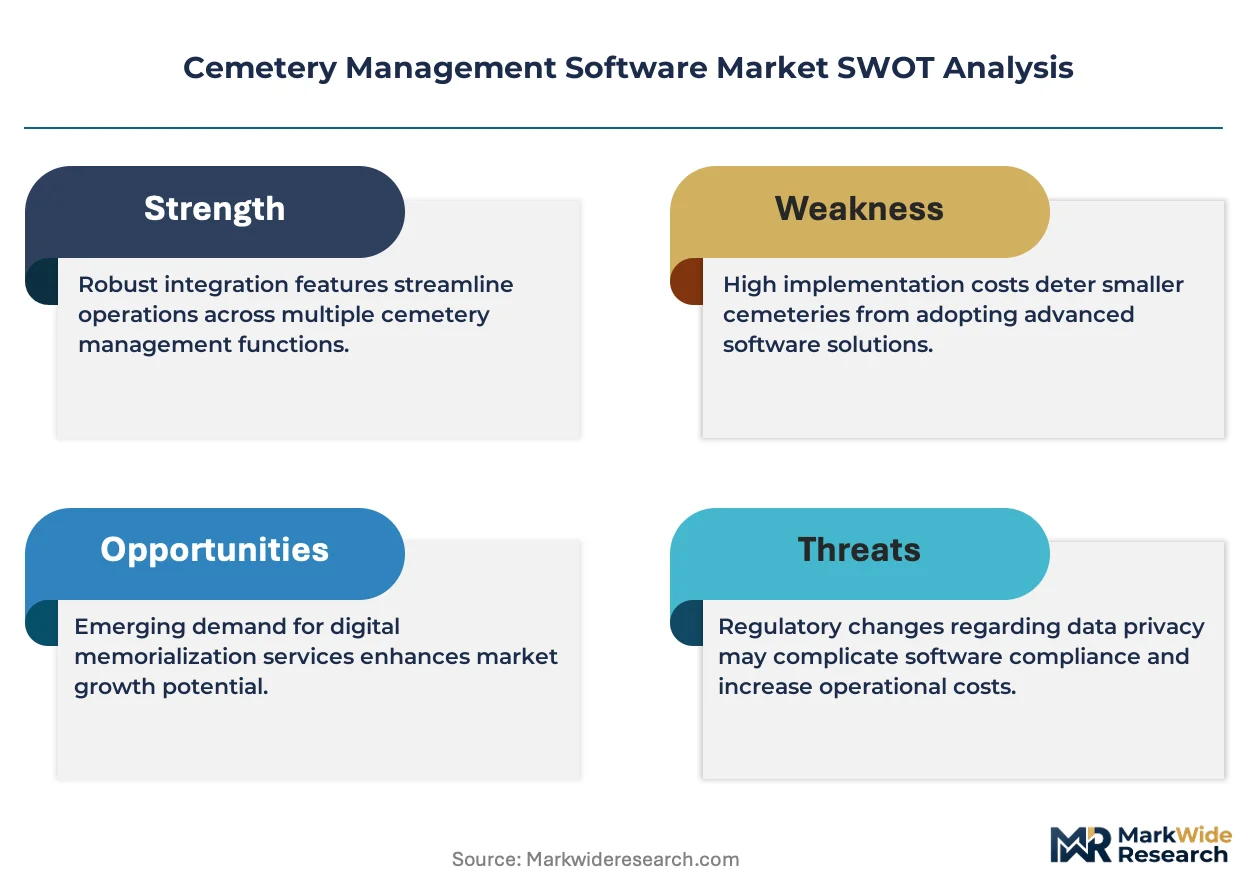
- HIPAA-informed data protocols:Hospital-funeral home data integration requirements are pulling cemetery software toward health-record compliance standards, expanding addressable functionality.
- Perpetual-care trust accounting:State cemetery regulators mandate immutable financial ledgers for maintenance obligations, embedding software deeper into regulatory infrastructure.
- GIS-enabled plot inventory:Geospatial database adoption is accelerating as operators replace paper-based cemetery maps with searchable digital layers.
Market Restraints
- Data sovereignty requirements:Government agencies with localized burial record storage needs resist full cloud migration, fragmenting deployment architectures.
- Budget-constrained procurement:Municipal cemetery districts face capital expenditure limitations that stretch replacement timelines despite mandate pressures.
- Hybrid infrastructure complexity:Sensitive record localization combined with remote staff access demands creates dual-environment maintenance burdens.
Strategic Opportunities
- Genealogical platform convergence:Integration between operational cemetery software and public historical record databases opens subscription revenue from family researchers.
- Mobile field-data capture:Smartphone-based grave condition documentation and maintenance ticketing remains underdeployed in smaller family-owned burial grounds.
- FTC Funeral Rule compliance tooling:Embedded pre-need contract generation modules address regulatory documentation requirements for funeral home integration partners.
Industry Challenges
- Interoperability investment risk:Fragmented municipal procurement standards threaten to lock cemetery districts into isolated technology ecosystems with limited vendor switching.
- Multi-decade maintenance obligation tracking:Perpetual-care scheduling across generational timeframes strains database architecture and succession planning workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cemetery Management Software Market |
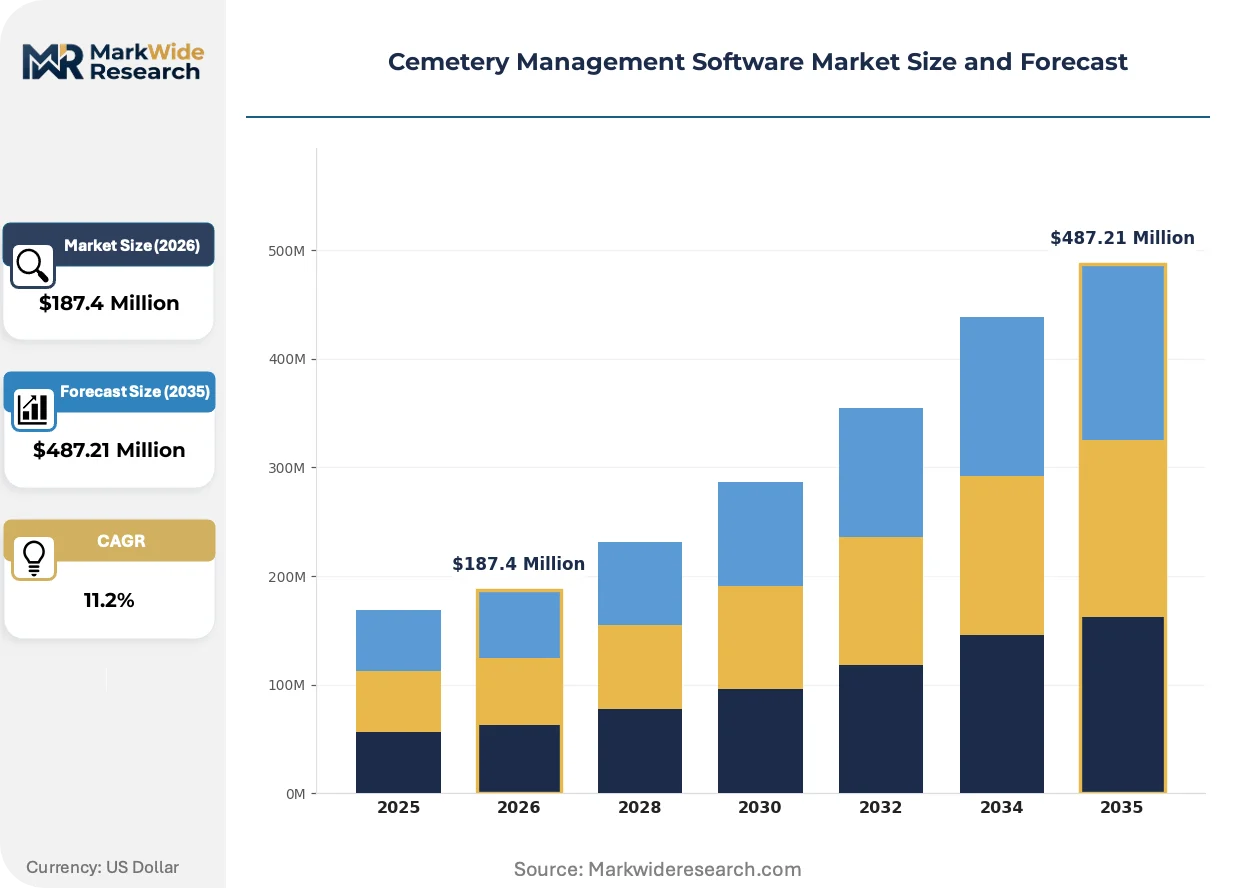
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premise Software, Hybrid Models, Mobile Applications End User: Cemeteries, Funeral Homes, Government Agencies, Family-Owned Businesses Deployment: Public Cloud, Private Cloud, On-premise, SaaS Feature: Plot Management, Grievance Handling, Reporting Tools, Burial Record Tracking |
| Companies Covered | Cemify, Everspot, PlotBox, Nexus, CemeteryFind, Chronicle, Cemetery Workstation, byondpro, CIMS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cemetery Management Software Market Emerging Trajectories
Artificial intelligence and machine learning capabilities are penetrating cemetery management platforms, automating record transcription and predictive maintenance scheduling. These advances are compressing labor intensity while raising data quality expectations.
Natural language processing for historical burial record digitization is electrifying archival conversion projects. Municipal operators with century-old paper registers are deploying automated transcription tools to accelerate database backfill. This technology is compressing decades of manual data entry into months, enabling rapid GIS layer completion and searchable public portals.
State-level cloud migration mandates are forcing deployment architecture decisions. Cemetery districts must reconcile regulatory deadlines with data sovereignty requirements, often selecting hybrid models that localize sensitive records while permitting SaaS functionality. Jurisdictions with aging burial infrastructure and digitization grant availability are experiencing the most acute implementation pressure.
Buyer concentration among multi-site municipal networks is altering vendor engagement models. Procurement officers now demand enterprise-grade interoperability across cemetery districts rather than single-site solutions. This behavioral shift is visible most acutely in regions where consolidation into regional management authorities has centralized technology decisions away from individual groundskeepers.
Cemetery Management Software Market Segmentation
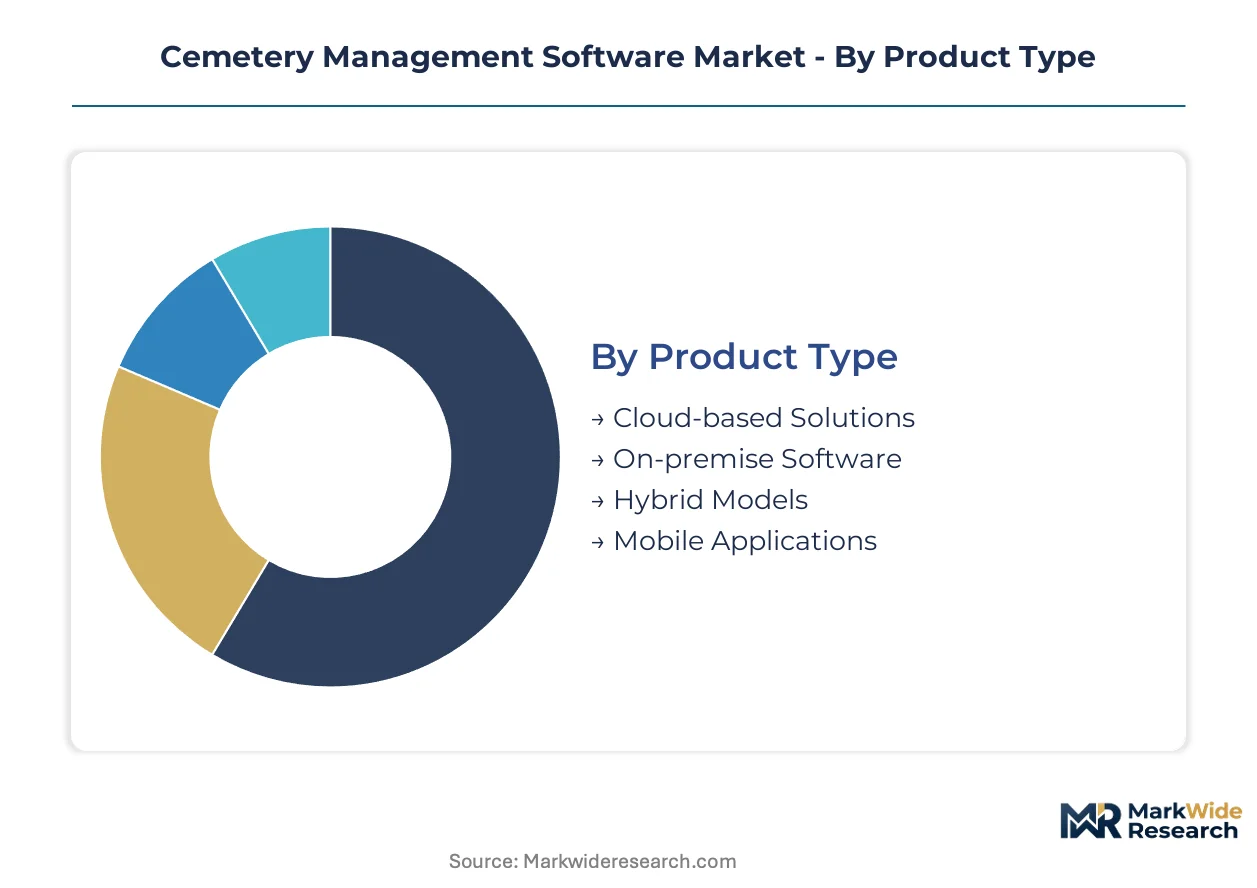
Cemetery management software segments diverge sharply by capital requirements and compliance burdens. Procurement patterns track regulatory deadlines, data sovereignty mandates, and the technical sophistication of cemetery operator IT infrastructure.
Product Type:
Capital intensity varies dramatically across deployment architectures, with upfront infrastructure costs separating enterprise-grade platforms from lightweight alternatives.
- Cloud-based Solutions:Multi-tenant SaaS architectures eliminate server procurement for municipal cemetery districts. State-level cloud migration mandates in the United States are compressing replacement cycles toward these subscription models.
- On-premise Software:Perpetual licenses demand substantial hardware investment and dedicated IT staffing. Government agencies with HIPAA-informed data sovereignty requirements retain this architecture for localized burial record control.
- Hybrid Models:Dual-environment deployments balance sensitive record localization with remote SaaS functionality. Municipal operators facing compressed regulatory deadlines select this architecture to satisfy audit requirements while enabling field staff mobility.
- Mobile Applications:Smartphone-native interfaces for grave condition documentation and maintenance ticketing. Family-owned burial grounds with minimal IT infrastructure deploy these for streamlined field-data capture.
Cloud-based solutions absorb the bulk of installed capacity; mobile applications are expanding most quickly among smaller operators.
End User:
Customer type determines contract value, integration complexity, and sales cycle duration across the vendor landscape.
- Cemeteries:Municipal and religious burial grounds requiring plot inventory, perpetual-care trust accounting, and GIS-enabled mapping. Multi-site consolidation trends in the United States are elevating procurement toward enterprise interoperability requirements.
- Funeral Homes:Pre-need sales documentation and deceased patient record integration with hospital systems. FTC Funeral Rule compliance tooling embeds these operators deeper into cemetery software ecosystems.
- Government Agencies:State cemetery regulators and municipal authorities enforcing immutable financial ledgers for maintenance obligations. Data sovereignty requirements fragment deployment architectures despite cloud migration mandates.
- Family-Owned Businesses:Smaller burial grounds with constrained capital expenditure and limited technical staffing. Mobile-first interfaces and simplified SaaS licensing address their procurement limitations.
Cemeteries command the largest contract values; funeral homes are climbing the fastest as hospital-system integration requirements expand.
Deployment:
Technical architecture selection tracks regulatory pressure, budget constraints, and workforce mobility needs across operator categories.
- Public Cloud:Shared infrastructure with subscription pricing eliminates capital expenditure. Digitization grant availability in the United States accelerates municipal adoption despite data sovereignty hesitations.
- Private Cloud:Dedicated cloud environments for agencies with stringent burial record isolation requirements. State cemetery regulators with audit trail mandates favor this architecture for controlled access provisioning.
- On-premise:Localized server infrastructure with perpetual licensing. Aging burial infrastructure in budget-constrained districts extends replacement timelines for this legacy architecture.
- SaaS:Software-as-a-service delivery with recurring subscription revenue models. Vendor priorities are shifting toward this deployment as municipal procurement consolidates into multi-site networks.
Public cloud dominates new procurement; private cloud is gaining share fastest among regulatory-sensitive agencies.
Feature:
Functional module prioritization reflects operational pain points, regulatory documentation requirements, and public-facing service demands.
- Plot Management:Geospatial database layers replacing paper-based cemetery maps with searchable digital inventory. GIS-enabled adoption is accelerating as operators complete archival backfill projects.
- Grievance Handling:Workflow engines for family complaints, maintenance disputes, and service issue resolution. Customer service expectations are elevating this module toward real-time response capabilities.
- Reporting Tools:Audit-ready documentation for state cemetery regulators and perpetual-care trust oversight. Immutable financial ledger requirements embed these tools deeper into compliance infrastructure.
- Burial Record Tracking:Core database functionality spanning deceased identification, interment location, and genealogical linkage. Natural language processing for historical record digitization is electrifying archival conversion demand.
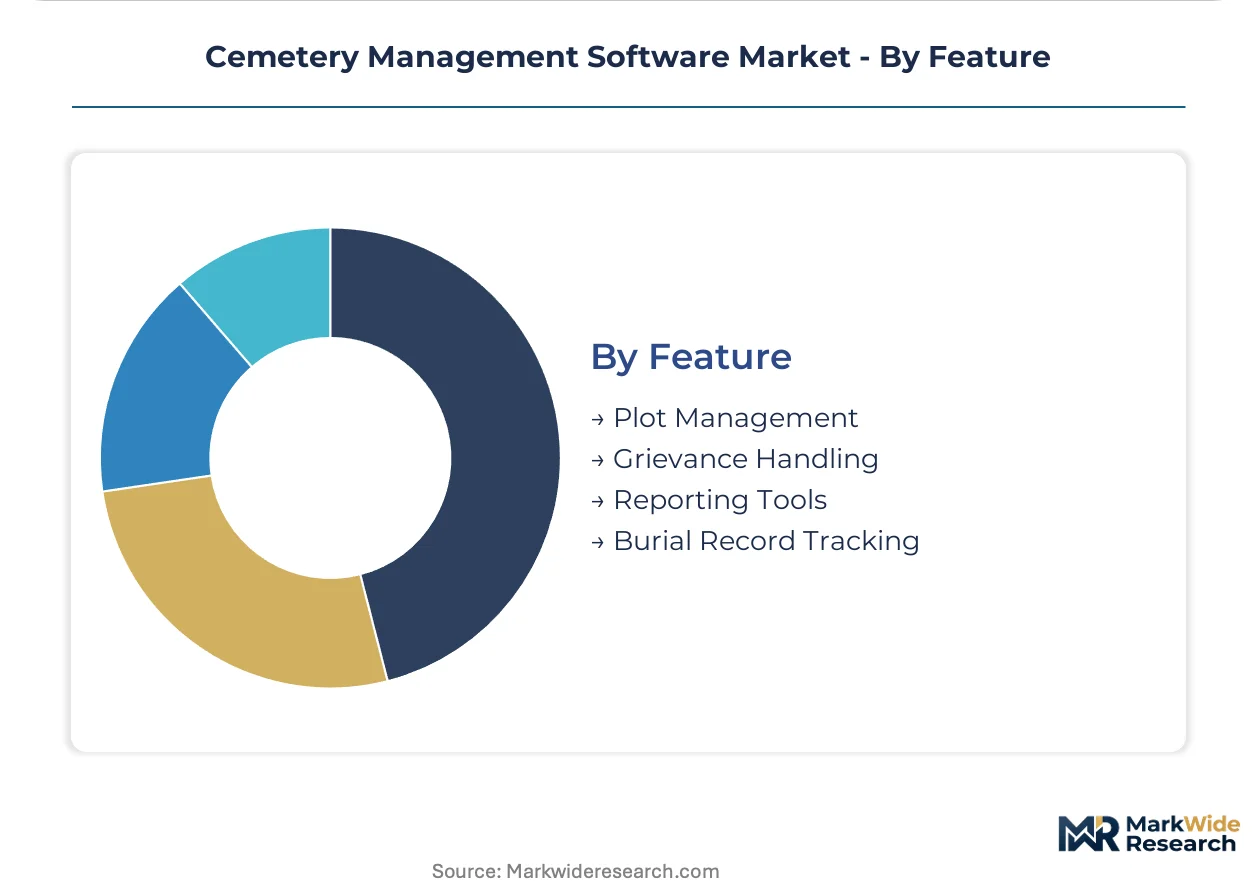
Plot management anchors installed base functionality; burial record tracking is expanding most quickly through AI-enabled transcription tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley venture capital and Boston's SaaS ecosystem anchor cemetery management software development, with municipal digitization grants in the United States driving concentrated demand for cloud-native burial record platforms.
United States
State-level cloud migration mandates from records-keeping authorities in California, Texas, and New York are compressing replacement cycles for aging burial infrastructure. The FTC Funeral Rule governs pre-need sales documentation, embedding compliance tooling into procurement specifications. Municipal cemetery networks in the Northeast Corridor consolidate multi-site deployments through enterprise interoperability requirements.
United Kingdom
Church of England burial ground digitization and local authority cemetery consolidation create dual demand streams for plot inventory platforms. GDPR-informed data handling protocols shape vendor product roadmaps for genealogical record integration. London and Southeast England municipal clusters lead SaaS adoption among historic urban cemeteries with century-old paper registers.
Germany
Baden-Württemberg and Bavaria municipal cemetery operators face perpetual-care trust accounting requirements under state burial regulations. Data sovereignty preferences among government agencies sustain hybrid deployment architectures despite cloud migration pressures. Cologne and Berlin cemetery districts exemplify multi-site digital consolidation into regional management authorities.
Canada
Provincial vital statistics integration requirements in Ontario and Quebec pull cemetery software toward health-record interoperability standards. Health Canada data handling guidelines inform HIPAA-aligned product development for cross-border vendor compatibility. Toronto and Vancouver municipal cemetery networks prioritize GIS-enabled plot inventory for urban burial space optimization.
Australia
New South Wales and Victoria state cemetery regulators enforce immutable financial ledgers for maintenance obligation tracking. TGA-aligned data protocols shape funeral home integration requirements for deceased patient record handling. Sydney and Melbourne metropolitan cemetery trusts consolidate procurement into multi-site digital platforms with mobile field-data capture capabilities.
Cemetery Management Software Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue genealogical platform convergence and mobile-first field interfaces. The vendor base clusters around three strategic archetypes: cloud-native enterprise platforms for municipal networks, specialized mobile tools for family-owned grounds, and integrated historical record systems for public research portals. Competitive positioning hinges on M&A activity consolidating point solutions into full-stack suites, plus strategic partnerships embedding compliance tooling into funeral home software ecosystems.
Within the cloud-native enterprise tier, PlotBox and Chronicle exemplify divergent specialization strategies. PlotBox anchors large-scale public cemetery deployments across North American jurisdictions through multi-tenant SaaS architecture. Chronicle occupies a niche between operational software and public historical record platforms via integrated genealogical mapping tools. Cemify represents the mobile-first archetype, extending smartphone-native interfaces to smaller family-owned burial grounds with constrained IT infrastructure.
| Leading Market Players |
|---|
| Cemify |
| Everspot |
| PlotBox |
| Nexus |
| CemeteryFind |
| Chronicle |
| Cemetery Workstation |
| byondpro |
| CIMS |
| Others |
Supply Flow & Price Mechanics
Cloud-native SaaS architecture migration is simultaneously collapsing upfront deployment costs for municipal cemetery operators and concentrating vendor bargaining power among multi-tenant platform providers with scalable infrastructure. This technology shift compresses capital expenditure barriers for budget-constrained districts while embedding recurring subscription economics that favor established cloud providers over on-premise resellers.
Pricing Analysis
Perpetual-care trust accounting modules and HIPAA-compliant data handling are bundled into enterprise-tier subscriptions, while basic plot management functions are unbundled for entry-level SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity, with municipal networks paying premiums for multi-site interoperability and funeral homes selecting mid-tier options for FTC Funeral Rule compliance tooling. Cost compression in the economy tier is intensifying because mobile-first entrants are undercutting legacy on-premise vendors. Family-owned burial grounds exhibit the highest price sensitivity, while consolidated municipal cemetery networks demonstrate inelastic demand for enterprise-grade compliance features.
Supply Chain Analysis
Specialized GIS development talent scarcity in India, Poland, and Ukraine is constraining vendor capacity for geospatial database layer customization. Cloud infrastructure draws from hyperscaler data centers in the United States, Ireland, and Singapore, while perpetual-care audit trail hardware sources from Taiwanese semiconductor foundries and German industrial sensor manufacturers. Single-source vulnerability in hyperscaler concentration threatens continuity for SaaS-dependent operators. Distribution runs through direct municipal procurement channels and funeral home software integration partnerships rather than traditional value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cemetery management software sits at a technology-transition phase as natural language processing for historical burial record digitization displaces decades of manual transcription labor. Municipal operators with century-old paper registers now demand AI-enabled archival conversion, forcing vendor roadmaps toward automated backfill capabilities.
For Market Incumbents: Acquire mobile field-data capture specialists to extend smartphone-native interfaces into family-owned burial grounds before specialized entrants lock channel relationships. Consolidate genealogical database assets to defend against Chronicle's historical record platform convergence. State-level cloud migration mandates threaten margin compression; vertical integration into compliance documentation modules preserves pricing power against unbundled competitors. For New Entrants and Emerging Players: Direct-to-cemetery digital sales channels bypass entrenched funeral home software integration partnerships that incumbent vendors control. Target underpenetrated municipal cemetery districts in Texas and Florida where digitization grant availability exceeds vendor deployment capacity. White-space concentration in hybrid deployment architecture consulting addresses data sovereignty requirements that pure-cloud vendors cannot satisfy. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by funeral home software consolidators seeking cemetery record interoperability. Long-term viability hinges on perpetual-care trust accounting regulatory permanence across generational maintenance obligations. Watch for FTC Funeral Rule enforcement intensity as inflection signal; heightened pre-need sales documentation requirements accelerate cemetery software embedding into funeral home technology stacks.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Mobile-first field-data capture vendors unlock family-owned burial ground penetration for enterprise platforms. |
| Platform Integration | Genealogical database embedding differentiates operational software from public historical record competitors. |
| Strategic Partnership | Funeral home software ecosystem alliances embed cemetery modules into pre-need sales documentation workflows. |
| Geographic Expansion | Texas and Florida municipal digitization grant concentration offers near-term deployment velocity for cloud-native vendors. |
| Product Launch | AI-enabled archival transcription tools compress decades of manual cemetery record backfill into months. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for cemetery management software market sizing. Primary interviews with municipal cemetery IT directors, funeral home operations managers, state cemetery regulators, and cloud platform engineering leads combined with secondary validation from SEC SaaS vendor disclosures, state digitization grant databases, and municipal procurement records. Bottom-up deployment counts triangulated against top-down subscription revenue estimates from public cloud infrastructure reporting.
Data-stream reconciliation across product type, end user category, deployment architecture, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from adoption curve modeling calibrated to state-level cloud migration mandate deadlines and digitization grant disbursement timelines. Perpetual-care trust accounting regulatory permanence and HIPAA-informed data protocol expansion served as core forecast inputs across the projection horizon.
The model holds under sustained state-level digitization mandate enforcement and stable municipal cemetery network consolidation patterns; deviation in grant funding availability or data sovereignty regulatory reversal would shift deployment velocity and vendor competitive positioning. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global License Management Market
Software & Services
Patent Management Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Global Cinema Software Market
Software & Services
Global Document Management Software Market
Software & Services
UI Design Software Market
Software & Services
Global Continuous Testing Market
Software & Services
Global Brain Training Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Association Management Software Market
Software & Services
Estate Management Software Market
Software & Services
Office Software Market
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Office Productivity Software Market
Software & Services
Home Design Software Market