
 Contract Lifecycle Management (CLM) Solution Market | 2026-2036
Contract Lifecycle Management (CLM) Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Lifecycle Management (CLM) Solution Market Intelligence
API-first architecture is fragmenting the traditional CLM stack into modular, interoperable components rather than monolithic suites. Icertis leverages its AI-native platform to anchor enterprise-wide contract intelligence for Fortune 500 manufacturers. DocuSign competes through its e-signature-to-CLM workflow extension, embedding agreement management directly into customer business processes. Ironclad specializes in high-velocity commercial contracting, dominating technology sector adoption with purpose-built workflow automation.
Contract Lifecycle Management solutions comprise software platforms that orchestrate agreement creation, negotiation, execution, and analysis through automated workflows, document repositories, and compliance monitoring. These systems integrate clause libraries, AI-powered risk extraction, and obligation management to reduce legal cycle times and regulatory exposure. Cloud-based deployment leads the product type landscape due to lower total cost of ownership and faster implementation timelines. Financial institutions represent the fastest-growing end user segment as Basel III capital requirements and stress-testing protocols intensify documentation scrutiny. Automated workflows capture the deepest margin pools within functionality segments by eliminating manual handoffs between legal, procurement, and finance teams.
The EU AI Act and GDPR shape European demand by mandating auditable decision trails in algorithmic contract analysis, while the SEC's disclosure rules in the United States require granular tracking of material agreement terms. HIPAA compliance frameworks further extend CLM requirements for healthcare payers managing provider networks and data-use agreements. Stakeholders must monitor how generative AI clause generation triggers emerging liability frameworks around automated legal advice and contractual intent.
Market Dynamics
Generative AI is compressing contract drafting cycles from weeks to hours, forcing legal departments to restructure workflows around machine-assisted negotiation rather than sequential attorney review.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions across Germany and France must maintain auditable decision trails for algorithmic contract analysis, accelerating procurement of automated compliance tracking systems.
- Basel III documentation intensity:Banks face heightened scrutiny of derivative and lending agreement terms, driving demand for clause extraction and obligation management capabilities.
- API-first architecture adoption:Enterprise buyers are fragmenting monolithic CLM suites into modular components, creating pull for interoperable workflow engines.
Market Restraints
- Cloud infrastructure concentration:Overreliance on hyperscale providers in US West Coast data centers creates geopolitical and availability risk for European financial institutions.
- Legacy system integration friction:Decades-old document management systems in Fortune 500 legal departments resist standard API connectivity, extending implementation timelines.
- Specialized legal AI talent scarcity:Shortage of professionals combining contract law expertise with machine learning operations constrains deployment velocity.
Strategic Opportunities
- Healthcare payer network management:HIPAA-covered entities managing provider data-use agreements represent underpenetrated demand for automated compliance monitoring.
- Convergence of CLM and spend analytics:Procurement teams seek unified platforms linking contract terms to invoice validation, creating white space for integrated vendors.
- India's digital public infrastructure:The country's stack approach to governance creates opening for modular CLM components serving mid-market enterprises.
Industry Challenges
- Generative AI liability ambiguity:Courts have not established precedent for automated clause generation errors, exposing enterprises to contractual intent disputes.
- Cross-functional workflow redesign:Legal, procurement, and finance teams operate with conflicting KPIs, complicating unified platform adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Lifecycle Management (CLM) Solution Market |
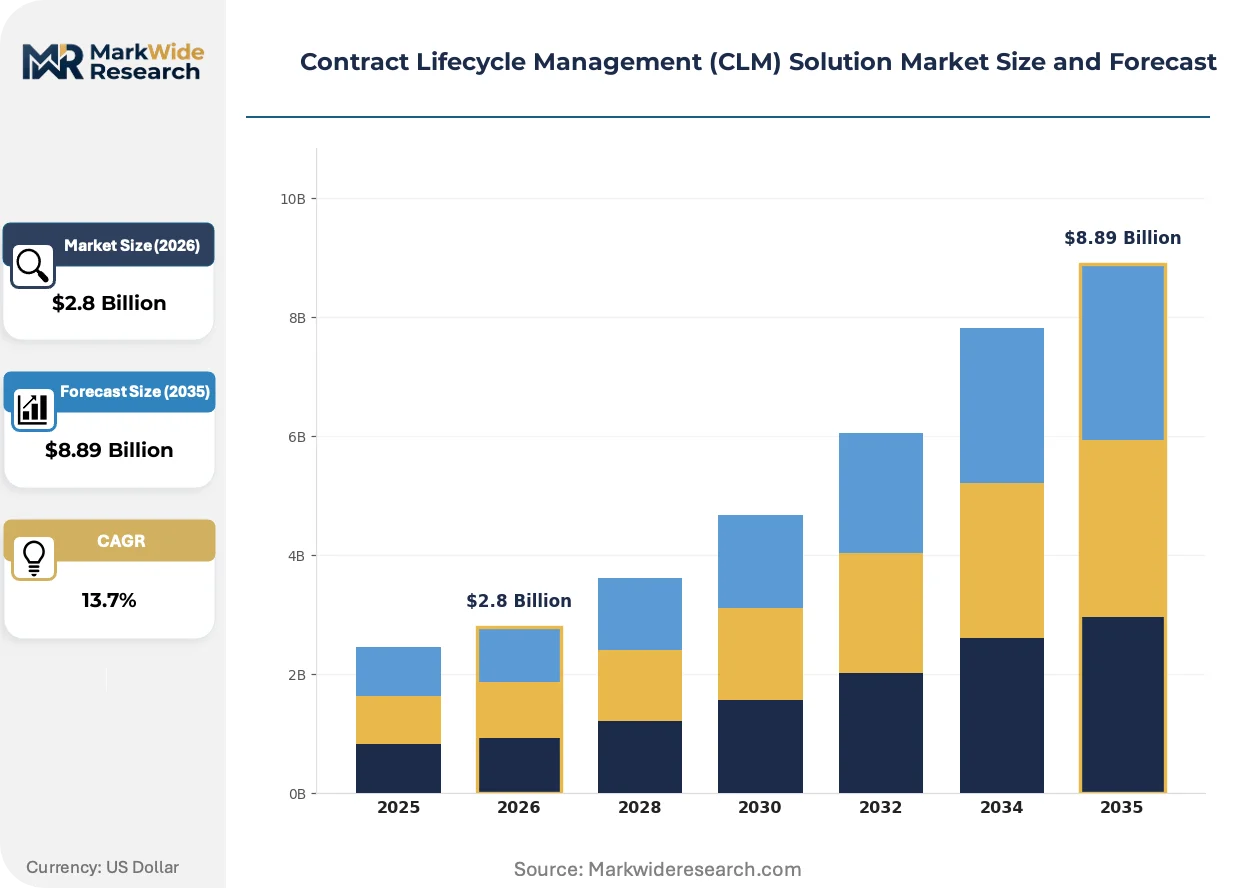
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises, Cloud-Based, Hybrid, SaaS End User: Legal Firms, Corporations, Government Agencies, Financial Institutions Deployment: Private Cloud, Public Cloud, Managed Services, Local Deployment Functionality: Automated Workflows, Document Management, Compliance Tracking, Analytics |
| Companies Covered | Sirion, Agiloft, Conga, DocuSign, Icertis, Ironclad, LinkSquares, Leah, ContractPodAi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Lifecycle Management (CLM) Solution Market Strategic Shifts & Innovations
Natural language processing capabilities are migrating from post-signature analytics to real-time negotiation assistance, altering where attorneys allocate cognitive effort across the contract lifecycle.
Large language models trained on regulatory corpora are digitizing clause precedent research. Corporate legal departments at pharmaceutical and energy firms are deploying these systems to compress risk assessment timelines. The technology is digitizing the traditionally manual work of associate attorneys, reallocating human judgment toward exception handling and stakeholder negotiation.
The SEC's disclosure rules now require granular tracking of material agreement terms, compelling issuers to implement structured data extraction from executed contracts. This regulatory pressure is accelerating adoption of AI-native platforms over legacy repository systems. Financial services firms in New York and London are prioritizing solutions with embedded audit trails for regulatory examination readiness.
Enterprise buyers are consolidating vendor relationships, preferring platforms that extend from e-signature through obligation management rather than point solutions. Technology sector procurement teams are leading this consolidation, using workflow automation as the selection criterion over feature depth. This pattern is most pronounced in Silicon Valley and Bangalore, where high-velocity commercial contracting demands seamless handoffs between legal and revenue operations.
Contract Lifecycle Management (CLM) Solution Market Segmentation
CLM segmentation reveals how deployment architecture and user sophistication split procurement decisions across radically different implementation timelines and compliance burdens. Understanding these divides exposes where vendors can command premium pricing versus where commoditization pressures dominate.
Product Type:
Mature on-premises installations coexist with emerging serverless architectures, creating a bifurcated procurement landscape where legacy comfort and cloud-native speed pull in opposite directions.
- On-Premises:Hardware-resident installations in dedicated data centers deliver air-gapped security for defense contractors and classified government programs. European financial institutions in Frankfurt and Paris favor these deployments under GDPR data-localization mandates, though capital expenditure requirements extend procurement cycles.
- Cloud-Based:Multi-tenant SaaS architectures with elastic compute provisioning enable rapid scaling for mid-market enterprises. Silicon Valley technology firms and Bangalore SaaS companies prioritize these solutions for API-native integration with existing revenue operations stacks.
- Hybrid:Split deployments maintain sensitive contract data on-premises while routing collaborative workflows through cloud gateways. Pharmaceutical manufacturers with FDA-validated quality systems use this architecture to segregate clinical trial agreements from commercial contracting data.
- SaaS:Pure subscription models with zero infrastructure ownership deliver fastest time-to-value for legal departments replacing legacy systems. The model concentrates demand among North American corporations seeking predictable operational expenditure profiles.
Cloud-Based handles the majority of throughput; SaaS is the fastest mover on share.
End User:
Procurement authority varies sharply across user types, with centralized legal operations teams demanding different functionality than distributed business units.
- Legal Firms:AmLaw 100 practices leverage CLM for client-matter profitability tracking and alternative fee arrangement modeling. New York and London headquartered firms drive adoption of AI-powered precedent analysis to compress associate training timelines.
- Corporations:Fortune 500 legal departments prioritize obligation extraction and renewal alerting to prevent revenue leakage. Manufacturing conglomerates with complex supplier networks represent the deepest implementation investment per seat.
- Government Agencies:Federal procurement offices require FedRAMP-authorized platforms with immutable audit trails. The segment demands specialized compliance modules for FAR and DFARS clause management that private-sector vendors rarely prioritize.
- Financial Institutions:Basel III documentation intensity pushes banks toward automated derivative agreement parsing. JPMorgan Chase and Deutsche Bank procurement teams are consolidating vendor relationships around platforms with embedded regulatory examination readiness.
Corporations command the largest absolute spend; Financial Institutions are expanding most quickly as regulatory pressure intensifies.
Deployment:
Control preferences over infrastructure location and operational responsibility create four distinct risk-transfer postures.
- Private Cloud:Single-tenant virtualized environments in dedicated cloud regions satisfy data residency requirements without full capital burden. German automotive manufacturers specify these deployments to maintain engineering contract confidentiality.
- Public Cloud:Shared hyperscale infrastructure delivers lowest unit economics for standardized use cases. The model dominates among technology sector adopters with limited compliance surface area.
- Managed Services:Outsourced operational responsibility including patching, backup, and tier-one support appeals to legal departments lacking dedicated IT resources. Healthcare systems managing HIPAA-covered provider agreements favor this hands-off approach.
- Local Deployment:Air-gapped installations without any external connectivity serve intelligence community and critical infrastructure operators. The segment represents highest implementation complexity and longest sales cycles.
Public Cloud carries the highest transaction volume; Managed Services is climbing the fastest as skills scarcity bites.
Functionality:
Feature depth versus workflow breadth defines competitive positioning, with point solutions and integrated suites serving different organizational maturity levels.
- Automated Workflows:Rules-based routing engines eliminate manual handoffs between legal, procurement, and finance stakeholders. Technology sector revenue operations teams prioritize these capabilities for high-velocity commercial contracting.
- Document Management:Centralized repositories with version control and redline comparison form the foundational layer of any CLM implementation. Legacy system migration projects concentrate demand among Fortune 500 legal departments.
- Compliance Tracking:Real-time obligation monitoring against regulatory deadlines and business terms reduces exposure to material breach. EU AI Act audit trail requirements are accelerating procurement among French and German financial institutions.
- Analytics:Contract metadata extraction and visualization tools enable portfolio-level risk assessment and negotiation pattern analysis. Private equity firms conducting due diligence on target companies represent emerging demand.
Document Management anchors the installed base; Compliance Tracking is gaining share fastest as regulatory frameworks multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 legal departments in the United States drive the highest absolute CLM procurement volumes, while regulatory pressure in Europe and Asia-Pacific accelerates adoption curves. Financial institutions in Germany, France, and Japan face intensifying documentation mandates. Technology sector procurement teams in India and Singapore demand API-native workflow integration.
United States
New York-based banking giants and Silicon Valley technology firms anchor North American demand. SEC disclosure rules require granular tracking of material agreement terms, compelling issuers toward AI-native platforms. JPMorgan Chase and Deutsche Bank procurement teams consolidate vendor relationships around examination-ready solutions.
Germany
Frankfurt's financial center generates concentrated demand for automated compliance tracking. EU AI Act mandates require auditable decision trails for algorithmic contract analysis. German automotive manufacturers specify private cloud deployments to maintain engineering contract confidentiality.
France
Paris-headquartered banks and pharmaceutical manufacturers lead European adoption. GDPR data-localization requirements push institutions toward hybrid deployment architectures. French legal departments prioritize obligation extraction capabilities to prevent revenue leakage across complex supplier networks.
United Kingdom
London-based AmLaw 100 practices and financial services firms drive professional services demand. AI-powered precedent analysis compresses associate training timelines at Magic Circle firms. UK corporations replacing legacy systems favor SaaS models with predictable operational expenditure profiles.
India
Bangalore's SaaS companies and Mumbai financial institutions represent the fastest-growing adoption cluster. The country's digital public infrastructure creates openings for modular CLM components serving mid-market enterprises. Indian technology sector procurement teams lead vendor consolidation toward workflow automation platforms.
Contract Lifecycle Management (CLM) Solution Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that fragments between AI-native platforms and workflow-centric suites. Enterprise buyers consolidate vendor relationships, preferring integrated platforms over point solutions. Three archetypes dominate: AI-native contract intelligence providers, e-signature-to-CLM extenders, and high-velocity commercial contracting specialists. M&A activity concentrates around workflow automation capabilities, while strategic partnerships target API interoperability.
Within the AI-native tier, Icertis anchors enterprise-wide contract intelligence positioning for Fortune 500 manufacturers. DocuSign occupies a channel-controlling position extending e-signature workflows into full CLM orchestration. Ironclad exemplifies the high-velocity specialist archetype, sitting within technology sector adoption patterns with purpose-built automation.
| Leading Market Players |
|---|
| Sirion |
| Agiloft |
| Conga |
| DocuSign |
| Icertis |
| Ironclad |
| LinkSquares |
| Leah |
| ContractPodAi |
| Others |
Cost & Logistics Intelligence
Trans-Atlantic fiber routes linking Frankfurt data centers to US hyperscale regions transmit compliance-sensitive contract data, with bandwidth costs cascading through SaaS subscription tiers and amplifying price spreads between GDPR-hardened private cloud deployments and standard multi-tenant offerings.
Pricing Analysis
Cost-plus contracts indexed to AWS/Azure compute consumption dominate enterprise procurement, with annual escalation clauses tied to named hyperscaler pricing indices. Three-tier pricing structure across premium AI-native platforms, standard workflow suites, and economy document repositories segments buyer willingness-to-pay by integration complexity. Pricing pressure stems from mid-market buyers consolidating around bundled suites rather than best-of-breed point solutions. Financial institutions exhibit lowest price sensitivity due to regulatory examination readiness requirements, while mid-market professional services firms drive hardest bargain on per-seat economics.
Supply Chain Analysis
Upstream NLP model training draws from annotated contract corpora concentrated in the United States, United Kingdom, and Germany, with regulatory text licensing fees constituting a material cost stack component. Compute infrastructure rests on NVIDIA GPU clusters and specialized legal AI training datasets, with talent scarcity for contract law-machine learning hybrid roles constraining vendor scaling velocity. Single-source vulnerability concentrates around hyperscale cloud regions in Northern Virginia and Dublin, with EU AI Act data-localization mandates fragmenting previously unified infrastructure footprints. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for Fortune 500 implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs lock in enterprise buyers; regulatory entrenchment through embedded compliance workflows creates durable incumbent advantages that resist displacement.
For Market Incumbents: Pre-empt modular API fragmentation by acquiring workflow automation specialists before point solutions mature into platform threats. Fortify position through vertical integration into regulatory content libraries, capturing clause precedent data that generative AI rivals cannot replicate without multi-year training investments. Channel control through embedded partnerships with systems integrators deepens replacement friction. For New Entrants and Emerging Players: Establish a beachhead in healthcare payer network management, where HIPAA-covered entities managing provider data-use agreements remain underpenetrated by incumbent CLM suites. Target India's mid-market enterprises through modular components aligned with the country's digital public infrastructure stack. Lead with API-native positioning that interoperates with existing revenue operations tools rather than demanding rip-and-replace adoption. For Investors and Strategic Acquirers: Workflow automation specialists with proven technology sector customer bases present the most compelling acquisition archetype, offering immediate capability gaps for legacy suite vendors. Long-term viability hinges on generative AI liability frameworks crystallizing to clarify automated clause generation risk allocation. Watch SEC examination readiness requirements as the inflection signal for accelerated AI-native platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Content Library Acquisition | Captures clause precedent data that generative AI rivals cannot replicate without multi-year training investments. |
| API-First Architecture Development | Fragments monolithic suites into modular components that interoperate with existing enterprise revenue operations stacks. |
| Healthcare Payer Network Expansion | Addresses HIPAA-covered provider agreement management where incumbent penetration remains shallow. |
| EU AI Act Compliance Certification | Creates audit trail capabilities mandatory for Frankfurt and Paris financial institution procurement. |
| Systems Integrator Channel Deepening | Embeds CLM workflows into multi-year digital transformation engagements that resist competitive displacement. |
Research Approach
A spread of perspectives from legal operations directors, procurement technology leads, compliance officers at financial institutions, and CLM vendor product managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC disclosure filings, EU regulatory guidance documents, and hyperscaler infrastructure expansion announcements. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models, end-user verticals, and functional capability tiers.
Demand-supply balance dynamics anchored the forecast framework, with adoption curves modeled across cloud-based, on-premises, hybrid, and SaaS deployment architectures. Segmentation dimensions included product type, end user category, deployment control preference, and functionality depth, with particular attention to financial institution regulatory intensity. CAGRs derived from penetration rate trajectories within each segment, cross-referenced against IT spending elasticity estimates and compliance mandate implementation timelines.
Sensitivities concentrate around generative AI liability precedent establishment and hyperscale infrastructure availability disruptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and enterprise workflow consolidation preferences. Cross-checking against vendor-reported implementation timelines and customer expansion metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Weather Forecast Software Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Logistics Services Software Market
Software & Services
Mining Simulation Software Market
Software & Services
Global Neural Network Software Market
Software & Services
RFP Software Market
Software & Services
Application Virtualization Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Media Editing App Market
Software & Services
Aviation Software Market
Software & Services
Design Collaboration Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Marketing Automation Software Market