
 Motorcycle Helmet Market | 2026-2036
Motorcycle Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Helmet Market Analysis
Commuter ridership is expanding across metropolitan transit networks in Asia, Latin America, and Southern Europe. HJC leverages high-volume manufacturing scale to supply price-accessible polycarbonate helmets for this demographic. Shoei sustains premium positioning through advanced composite shell R&D and Japanese domestic market loyalty. AGV competes in the performance racing segment with aerodynamic designs developed at its Italian engineering center.
A motorcycle helmet is a protective headgear system engineered from energy-absorbing liners—typically expanded polystyrene foam bonded to impact-resistant shells of polycarbonate, fiberglass, or carbon fiber composites—to mitigate traumatic brain injury during collision or abrasion events. Its primary commercial purpose is regulatory compliance and occupant safety certification for powered two-wheeler operators. Full-face configurations command the largest revenue share due to superior chin-bar protection and integrated visor systems, while carbon fiber materials capture the highest margin pool through weight reduction and motorsport positioning. Bluetooth-enabled feature sets represent the fastest-growing attachment category as riders integrate navigation and communication functions.
DOT certification administered by NHTSA governs minimum impact performance for helmets sold in the United States, while ECE 22.06 enforced across European Union member states mandates stricter rotational-acceleration testing and visor optical standards. India's BIS certification and state-level helmet compulsion statutes under the Motor Vehicles Act create sustained replacement demand among the world's largest two-wheeler fleet. Stakeholders must monitor evolving UN ECE regulation harmonization and emerging Asian national standards to anticipate certification cost shifts and market access barriers.
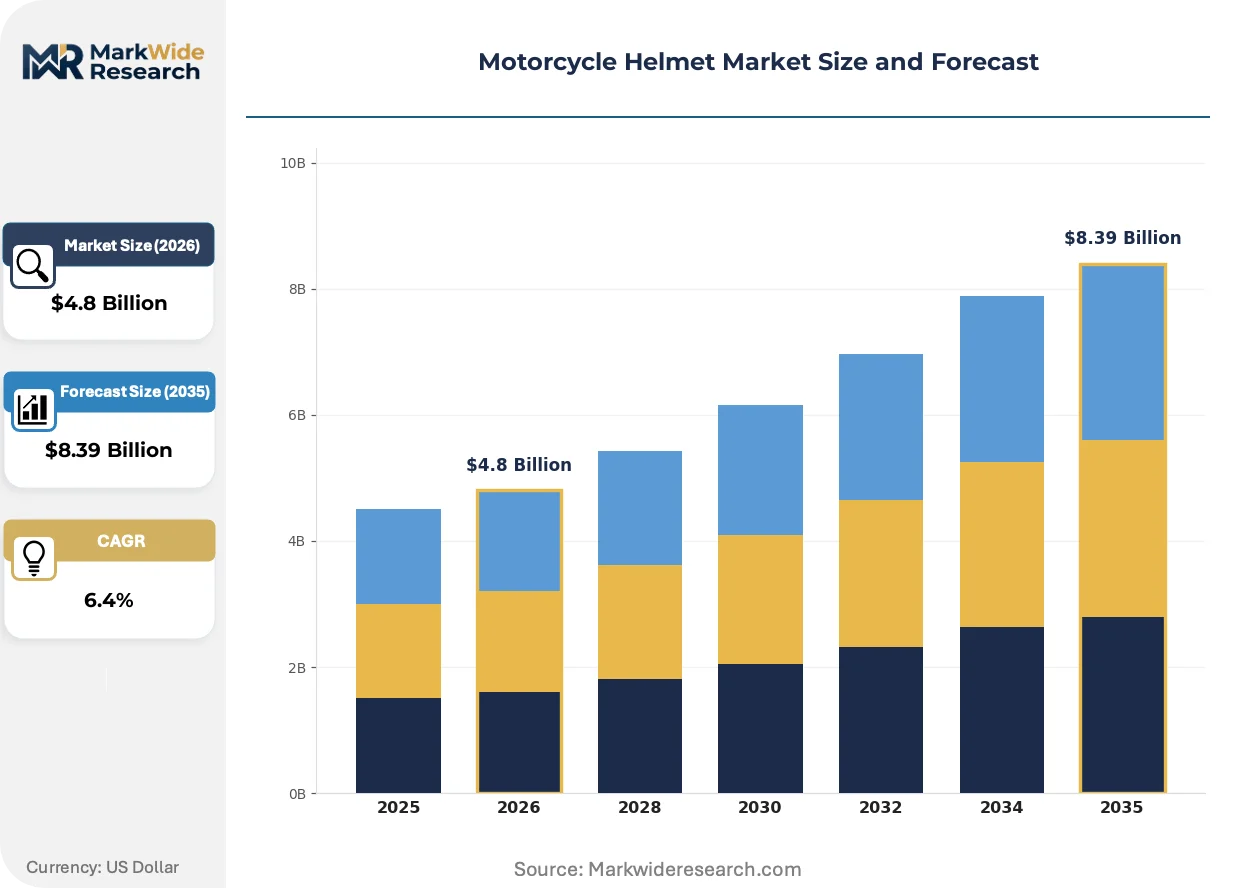
Market Dynamics
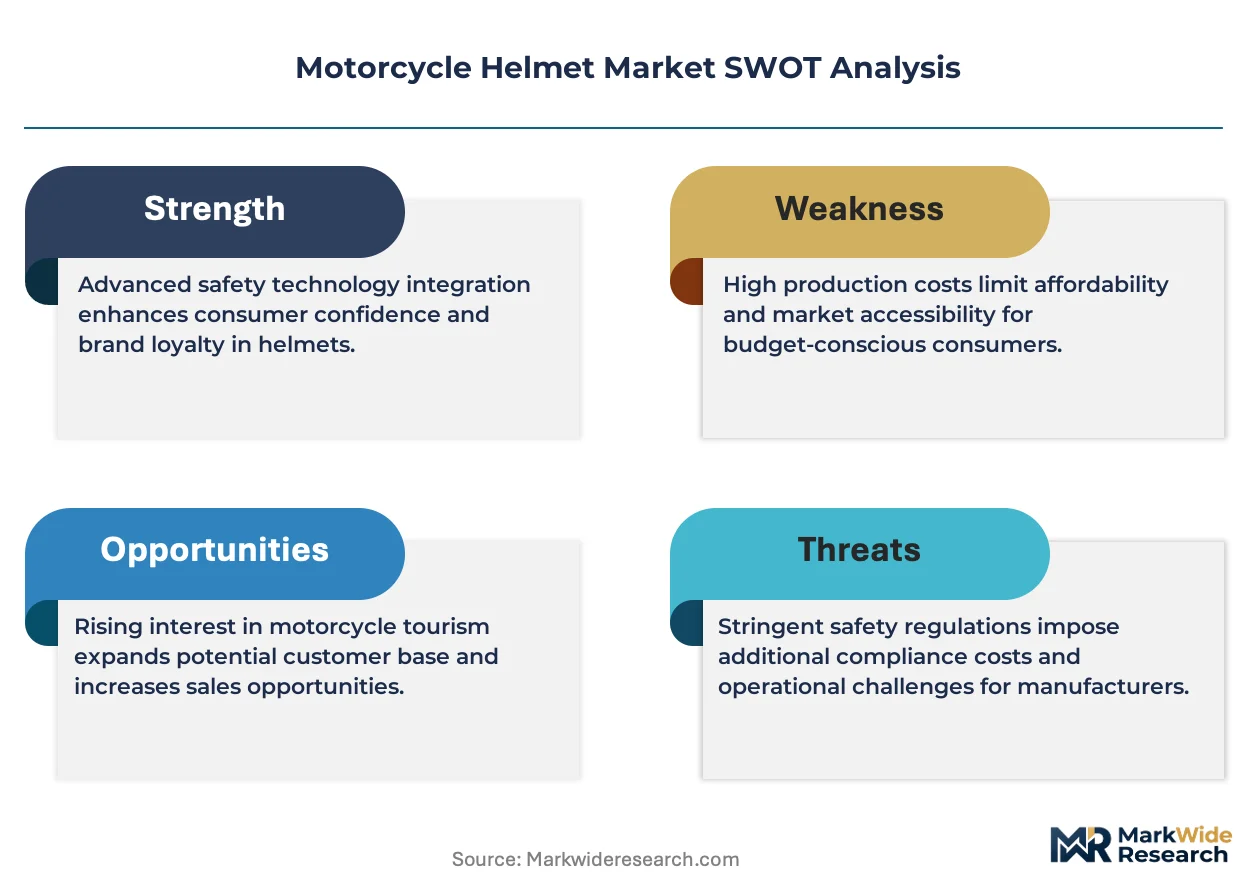
ECE 22.06 rotational-acceleration testing mandates in Europe and India's expanding BIS enforcement are compressing product development cycles while simultaneously fragmenting certification requirements across export destinations.
Growth Catalysts
- India's Motor Vehicles Act enforcement:State-level helmet compulsion statutes sustain replacement demand across the world's largest two-wheeler fleet, creating predictable volume baselines for polycarbonate shell suppliers.
- Bluetooth integration protocols:Wireless communication modules are converging with navigation and intercom functions, expanding attachment rates among touring and commuter segments.
- Carbon fiber weight reduction:Motorsport positioning and premium tier differentiation pull composite shell adoption upward in developed markets.
Market Restraints
- Polycarbonate resin volatility:Petrochemical feedstock fluctuations compress margin stability for high-volume ABS and polycarbonate shell manufacturers.
- Certification divergence:ECE 22.06, DOT FMVSS 218, and India's BIS standards create parallel testing burdens that inflate R&D overhead for exporters.
- Scooter helmet substitution:Open-face and half-helmet configurations undercut full-face unit economics in price-sensitive Southeast Asian corridors.
Strategic Opportunities
- Brazilian two-wheeler expansion:ANVISA medical-device-grade manufacturing capabilities can transfer to helmet liner production, capturing latent demand in São Paulo and Rio de Janeiro metropolitan zones.
- Integrated heads-up display modules:Micro-projection technology is converging with visor optics, creating premium feature differentiation for adventure touring segments.
- E-commerce direct channels:Platform-native brands bypass traditional distributor markups in Indonesia and Vietnam, compressing price points while expanding reach.
Industry Challenges
- Rotational-impact testing expertise:ECE 22.06 oblique-impact protocols require specialized laboratory infrastructure that remains concentrated in Germany and Japan.
- Multi-standard inventory complexity:SKU proliferation across DOT, ECE, and BIS variants strains working capital and forecasting precision for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Helmet Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Full-Face, Modular, Open-Face, Half-Helmet Material: Polycarbonate, Fiberglass, Carbon Fiber, ABS Feature: Bluetooth Connectivity, Ventilation System, Anti-Fog Visor, Sun Shield End User: Professional Riders, Recreational Riders, Commuters, Off-Road Enthusiasts |
| Companies Covered | Schuberth, HJC, Shoei, Nolan, Bell, Arai, Shark, Nexx, AGV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Helmet Market Emerging Trajectories
Helmet systems are transitioning from passive protection to integrated rider-environment interfaces, with sensor embedding, communication protocols, and biometric monitoring reshaping component architecture and value capture.
Smart helmet sensor arrays is converging with crash-detection algorithms and emergency response automation. Adventure touring and long-distance commuter segments in Germany and Australia are adopting these units fastest. The technology is compressing insurance underwriting cycles and creating data-monetization pathways for fleet operators.
ECE 22.06 rotational-acceleration testing protocols now mandate oblique-impact evaluation across European Union member states. Manufacturers must redesign liner geometries and shell attachment systems to comply. Full-face configurations face the steepest redesign burden, with Italian and Spanish engineering centers absorbing disproportionate certification costs.
Subscription-based visor replacement programs are displacing traditional retail accessory purchases. Direct-to-rider channels in the United States and United Kingdom are capturing recurring revenue streams that hardware margins alone cannot sustain. Urban commuter clusters in London and New York exhibit the highest attachment rates to these service models.
Motorcycle Helmet Market Segmentation
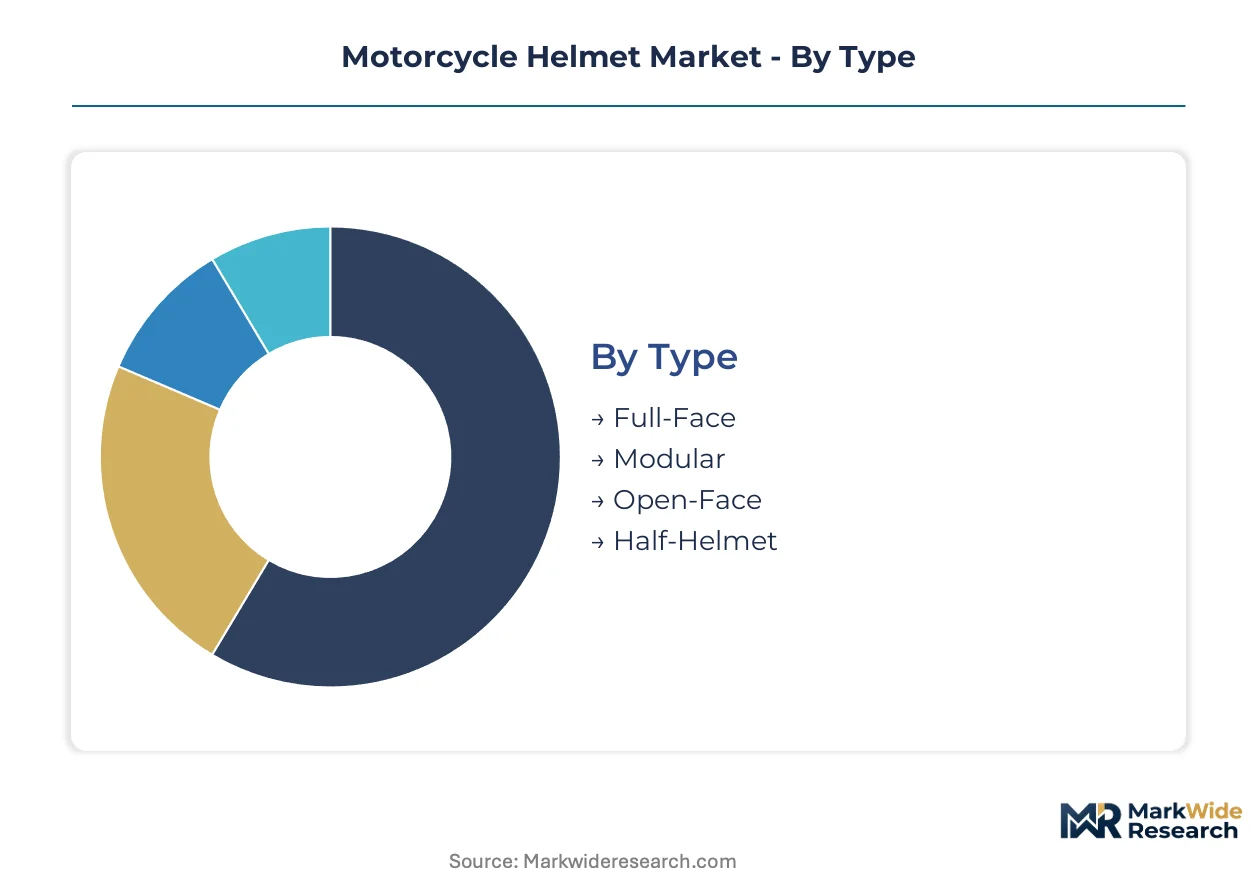
Helmet segmentation maps directly to risk tolerance, regulatory exposure, and price elasticity across rider populations. Manufacturers calibrate shell engineering, certification tiers, and distribution channels against these divisions to optimize margin capture and inventory turns.
Type:
Buyers in this category differentiate by crash protection priority versus thermal comfort and communication access.
- Full-Face:Enclosed shell architecture with integrated chin bar and visor system delivers maximum facial impact protection. Demand concentrates among commuters in India and professional couriers in Brazil where regulatory enforcement is strictest. ECE 22.06 rotational-acceleration testing imposes the steepest redesign burden on this configuration.
- Modular:Hinged chin bar mechanism enables conversion between full-face and open-face modes for touring flexibility. German and Australian adventure riders drive attachment rates where long-distance comfort competes with safety certification. The pivot hardware adds weight and cost complexity that constrains penetration in price-sensitive markets.
- Open-Face:Three-quarter coverage design sacrifices chin protection for ventilation and peripheral visibility. Southeast Asian scooter operators favor this format in urban heat conditions despite inferior crash performance.
- Half-Helmet:Minimal crown coverage meets only basic DOT compliance with lowest unit economics. US cruiser segments sustain residual demand where aesthetic preference overrides safety investment.
Full-Face leads volumes today; Modular is gaining share fastest.
Material:
Cost-to-performance ratios and manufacturing scale determine sourcing strategy across shell suppliers.
- Polycarbonate:Injection-molded thermoplastic shells achieve lowest per-unit production cost at high volume. India's BIS-certified replacement market absorbs the majority of global polycarbonate output where two-wheeler fleet density is highest. Petrochemical feedstock volatility compresses margin stability for manufacturers locked into long-term supply contracts.
- Carbon Fiber:Woven composite layup delivers maximum strength-to-weight ratio for motorsport positioning. Japanese domestic market loyalty and Italian racing heritage brands command premium pricing tiers. The autoclave curing requirement limits production scalability and concentrates supply among specialized fabricators.
- Fiberglass:Glass-reinforced polymer balances impact absorption with moderate weight reduction for mid-market positioning. European touring segments sustain steady demand where ECE certification costs are already absorbed.
- ABS:Acrylonitrile butadiene styrene offers intermediate durability at price points below polycarbonate. Southeast Asian OEM helmet suppliers integrate ABS for factory-fitted motorcycle bundles.
Polycarbonate dominates unit economics; Carbon Fiber claims the steepest margin expansion trajectory.
Feature:
Attachment rates for integrated functions diverge sharply by rider duration and connectivity expectations.
- Bluetooth Connectivity:Wireless communication modules enable intercom, navigation, and smartphone pairing. Touring segments in Germany and Australia adopt fastest where group riding and route complexity demand coordination.
- Ventilation System:Adjustable intake and exhaust ports manage thermal load during high-exertion riding. Southeast Asian commuters prioritize this feature where ambient temperatures exceed 35°C routinely.
- Anti-Fog Visor:Hydrophilic coatings and pin-lock inserts maintain optical clarity across humidity variations. Northern European markets exhibit highest attachment due to precipitation frequency.
- Sun Shield:Integrated drop-down tinted visor eliminates aftermarket sunglasses dependency. US sun-belt states and Middle Eastern markets drive specification rates.
Ventilation System leads specification rates in tropical markets; Bluetooth Connectivity is climbing the fastest in developed economies.
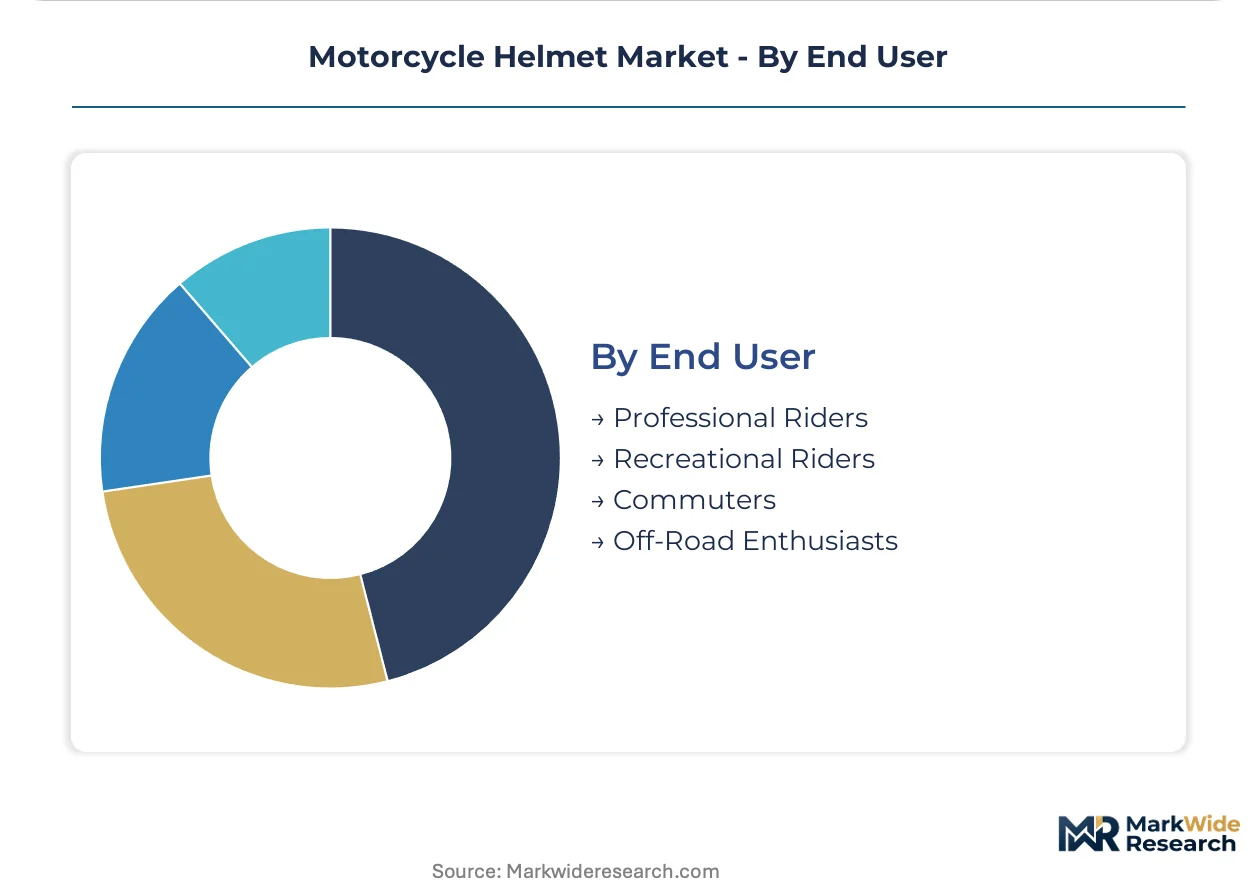
End User:
Risk exposure duration and regulatory scrutiny intensity separate professional obligations from discretionary recreation.
- Commuters:Daily urban transit riders face highest accident frequency and strictest helmet compulsion enforcement. India's state-level Motor Vehicles Act statutes create predictable replacement cycles among the world's largest addressable population.
- Professional Riders:Couriers, delivery fleets, and riding instructors operate under employer-mandated safety protocols. Brazilian last-mile logistics expansion in São Paulo and Rio de Janeiro metropolitan zones is pulling fleet procurement volumes.
- Recreational Riders:Weekend enthusiasts balance aesthetic preference with intermittent protection needs. Southern European and Latin American markets exhibit price elasticity that favors polycarbonate shells.
- Off-Road Enthusiasts:Motocross and enduro participants demand specialized peak visors and enhanced chin-bar ventilation. Australian and US desert racing circuits sustain niche premium positioning.
Commuters anchor global volume; Professional Riders are expanding most quickly through fleet digitization and insurance-linked safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's two-wheeler manufacturing corridors in Pune and Chennai anchor global helmet procurement volumes, with state-level enforcement creating sustained replacement cycles across the world's largest addressable fleet.
India
Commuter ridership across Mumbai, Delhi, and Bengaluru generates predictable demand baselines for polycarbonate shell suppliers. The Motor Vehicles Act compulsion statutes administered by state transport departments sustain replacement velocity. Tamil Nadu's Sriperumbudur industrial belt hosts injection-molding facilities serving both domestic BIS certification requirements and export markets.
United States
DOT FMVSS 218 compliance administered by NHTSA governs minimum impact performance for full-face and half-helmet configurations. California's lane-splitting legalization and Texas cruiser culture sustain divergent product mix preferences. The Southern California logistics corridor concentrates distribution infrastructure for aftermarket accessory channels.
Germany
ECE 22.06 rotational-acceleration testing protocols enforced by KBA impose the steepest redesign burden on full-face configurations. Bavaria's Munich-Stuttgart engineering axis absorbs disproportionate certification costs for composite shell development. The autobahn touring culture drives modular helmet attachment rates where long-distance comfort competes with safety mandates.
Brazil
Last-mile logistics expansion across São Paulo and Rio de Janeiro metropolitan zones pulls fleet procurement volumes for professional rider segments. ANVISA medical-device-grade manufacturing capabilities transfer to helmet liner production for price-accessible polycarbonate units. The ABC Paulista industrial region concentrates molding operations for domestic two-wheeler OEM bundles.
Japan
Domestic market loyalty sustains premium positioning for advanced composite shell R&D developed in the Osaka-Nagoya manufacturing belt. METI industrial standards and JIS certification frameworks govern export quality benchmarks. The Kanto region's precision fabrication heritage concentrates carbon fiber autoclave capacity for motorsport-tier differentiation.
Motorcycle Helmet Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers navigate certification divergence across ECE 22.06, DOT, and BIS standards. The vendor base clusters around three strategic archetypes: high-volume polycarbonate suppliers serving price-sensitive replacement markets, premium composite specialists capturing motorsport positioning, and integrated technology platforms embedding communication modules. Capacity expansion in Indian injection-molding corridors and strategic partnerships for Bluetooth protocol licensing represent the dominant competitive vectors reshaping supply positioning.
Within the premium composite tier, Shoei Co., Ltd. and Arai Helmet Ltd. exemplify Japanese precision manufacturing heritage, while AGV SpA occupies a position reflecting Italian racing engineering lineage. These three anchors demonstrate how geographic origin and certification specialization stratify competitive positioning across ECE 22.06 and DOT compliance vectors.
| Leading Market Players |
|---|
| Schuberth |
| HJC |
| Shoei |
| Nolan |
| Bell |
| Arai |
| Shark |
| Nexx |
| AGV |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists concentrated in Italy and Japan maintain pricing discipline through selective distribution partnerships while absorbing certification cost inflation through captive liner-molding operations. Their ownership structure insulates margin targets from quarterly earnings pressure, enabling long-term supply contracts with polycarbonate resin suppliers that volatile commodity markets would otherwise disrupt.
Pricing Analysis
Distributor markups ranging from 35 to 50 percent separate factory-gate economics from retail price points across European and North American channels. Three-tier pricing structure across premium composite, mid-market fiberglass, and economy polycarbonate levels reflects certification grade and shell material cost differentials. Pricing pressure stems from Indonesian and Vietnamese platform-native brands compressing entry-level price points through direct-to-rider e-commerce channels. Fleet procurement managers in Brazilian last-mile logistics exhibit highest price sensitivity, while German autobahn touring riders demonstrate lowest elasticity for modular configurations with integrated communication modules.
Supply Chain Analysis
Certification qualification gating through ECE 22.06 rotational-acceleration testing concentrates advanced composite shell supply among German and Japanese engineering centers with specialized laboratory infrastructure. Geographic supply concentration centers on India for polycarbonate injection molding, Japan for carbon fiber autoclave curing, and Italy for fiberglass composite layup. Raw material dependencies draw from petrochemical feedstocks for thermoplastic shells, epoxy resin systems for composite matrices, and expanded polystyrene bead stock for energy-absorbing liners. Single-source vulnerability persists in rotational-impact testing equipment where German and Japanese laboratory capacity faces allocation constraints. Distribution runs through OEM bundling agreements in Southeast Asia, independent dealer networks in Europe, and direct-to-consumer platforms in North American urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motorcycle helmet demand functions as a stable compounder anchored by India's state-level helmet compulsion statutes, which generate predictable replacement cycles across the world's largest two-wheeler fleet regardless of discretionary spending fluctuations.
For Market Incumbents: Anchor market position through backward integration into expanded polystyrene liner production in Tamil Nadu's Sriperumbudur belt, capturing cost advantages as Indian BIS enforcement intensifies. Invest in ECE 22.06 certification infrastructure before regulatory harmonization spreads to Asian export markets, as testing capability scarcity will disadvantage late movers. Defend against platform-native entrants by controlling distributor exclusivity in Indonesian and Vietnamese urban corridors where e-commerce penetration is accelerating fastest. For New Entrants and Emerging Players: Launch via direct-to-rider e-commerce channels targeting Indonesian and Vietnamese commuter segments where traditional distributor markups create price-disruption opportunities. Focus white-space capture on Bluetooth-integrated modular configurations for Australian and German adventure touring segments, where attachment rates for communication modules lag penetration potential. Prioritize ANVISA-certified manufacturing partnerships in Brazil's ABC Paulista region to access fleet procurement volumes from São Paulo last-mile logistics expansion. For Investors and Strategic Acquirers: Two-wheeler OEMs with captive helmet bundling operations are the most active acquirer in this space, seeking to secure supply continuity for factory-fit programs. Long-term viability favors targets with multi-standard certification capabilities spanning ECE 22.06, DOT FMVSS 218, and BIS frameworks, as regulatory divergence will persist across the next decade. Monitor Indian state transport department enforcement intensity as the critical inflection signal, as accelerated compulsion statute implementation would compress replacement cycles and expand addressable volume.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | ECE 22.06, DOT, and BIS testing capabilities unlock access to India, Europe, and North American demand pools simultaneously. |
| Backward Integration into Liner Molding | Captive expanded polystyrene production in Tamil Nadu absorbs BIS enforcement cost inflation for polycarbonate shell suppliers. |
| Bluetooth Module Licensing Partnership | Wireless communication protocol integration captures fastest-growing attachment category in German and Australian touring segments. |
| Direct-to-Rider E-Commerce Launch | Platform-native distribution in Indonesia and Vietnam bypasses traditional markups while expanding geographic reach. |
| Fleet Procurement Channel Development | ANVISA-certified supply agreements with Brazilian last-mile logistics operators capture professional rider segment growth. |
Methodological Framework
Multiple input streams — regulatory filing analysis, customs and trade flow databases, and primary fieldwork — were reconciled to construct segment-level demand estimates. Primary interviews with helmet product development directors, state transport department enforcement officers, fleet procurement managers at Brazilian logistics operators, and polycarbonate resin procurement leads were cross-validated against secondary sources including ECE 22.06 certification registries, NHTSA DOT compliance databases, Indian BIS product listings, and two-wheeler OEM annual disclosures. Bottom-up unit shipment modeling and top-down value aggregation were triangulated to resolve estimation variance.
Historical shipment trajectories were cross-referenced against panel input from industry stakeholders to calibrate projection assumptions across the analysis window. Segmentation dimensions modeled include helmet configuration type, shell material grade, integrated feature attachment, end-user risk exposure category, and regional regulatory cluster. CAGRs were derived from curve-fitting approaches applied to certified unit volumes and disclosed average selling prices. Industry-specific forecast inputs incorporated state-level Motor Vehicles Act enforcement schedules, petrochemical feedstock price indices, and Bluetooth module penetration curves from consumer electronics analogs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory harmonization or polycarbonate resin supply disruption scenarios. Model outputs reflect assumptions regarding certification cost pass-through rates and replacement cycle elasticity to enforcement intensity. A model refresh is warranted upon material change in Indian state transport department compulsion statute implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Digital Camlock Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Tube and Dressing Securement Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market