
 Europe Camping Equipment Market | 2026-2036
Europe Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Camping Equipment Market Insights
Portugal is tilting toward textile and assembly capacity for lightweight tent fabrics and synthetic insulation. Hilleberg the Tentmaker anchors premium four-season shelter production in Scandinavia through exacting seam-taping standards. Oase Outdoors ApS dominates the family camping segment across Northern Europe with an extensive retail network. AMG Group Ltd. specializes in technical sleeping systems that leverage advanced down-processing capabilities.
Camping equipment encompasses portable shelters, sleep systems, carrying gear, and field cooking apparatus engineered from ripstop nylon, aluminum alloys, and hydrophobic down or synthetic fills, with waterproof ratings typically exceeding 3000 mm hydrostatic head for primary rainflies. The primary purpose is to enable safe overnight occupancy in non-permanent outdoor settings across variable terrain and weather conditions. Tents command the largest product-type revenue pool due to replacement cycles and seasonal damage exposure. Online Retail is displacing specialty stores as the dominant distribution channel, though high-involvement purchases still flow through brick-and-click hybrid models. Solo Travelers represent the fastest-growing end-user category as self-guided trekking and bikepacking expand across Alpine and Nordic routes.
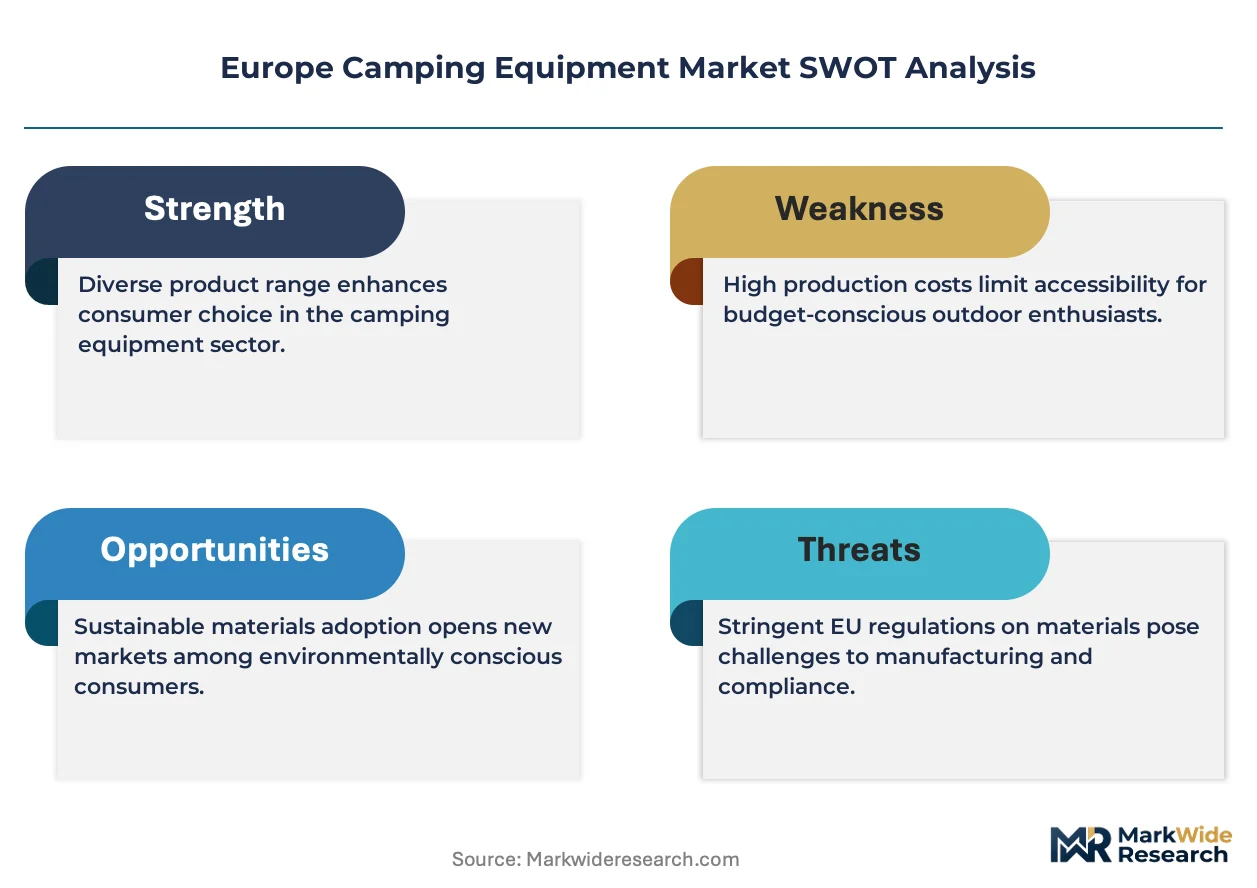
The EU Green Deal and REACH frameworks constrain chemical treatments for water repellency, compelling reformulation of durable water repellent coatings across the supply chain. ECHA scrutiny of per- and polyfluoroalkyl substances is accelerating migration to silicone- and hydrocarbon-based alternatives with comparable performance thresholds. Stakeholders must monitor evolving substance restrictions and certification costs to preserve margin structure and market access across member states.
Market Dynamics
REACH restrictions on per- and polyfluoroalkyl substances are forcing wholesale reformulation of durable water repellent coatings across European tent and sleeping bag production, compressing margins for manufacturers dependent on legacy chemistries.
Growth Catalysts
- EU Green Deal procurement mandates:Public sector camping infrastructure investments now require recycled content thresholds, pulling demand toward certified sustainable gear.
- Family camping participation:Multi-generational outdoor recreation across Germany and Scandinavia sustains replacement cycles for family-sized shelters and sleep systems.
- Alpine route digitalization:Real-time booking platforms for hut-to-hut trekking expand addressable demand for lightweight technical equipment.
Market Restraints
- Fluorinated chemistry substitution costs:Silicone-based water repellent alternatives require retooled application lines and extended curing protocols.
- Down supply concentration:Premium hydrophobic down processing clusters in Eastern European facilities, creating single-source vulnerability.
- Aluminum alloy price volatility:Tent pole and cookware manufacturers face margin pressure from energy-intensive smelting cost swings.
Strategic Opportunities
- Portuguese textile expansion:Underutilized capacity in northern Portugal offers nearshoring alternatives to Asian synthetic fabric suppliers.
- CSRD disclosure requirements:Mandatory supply chain transparency creates first-mover advantage for brands with pre-audited circular material flows.
- Bikepacking route networks:Emerging marked trails across the Alps and Pyrenees unlock ultralight equipment categories for self-supported travel.
Industry Challenges
- Seam-taping technician scarcity:Four-season shelter production requires skilled operators for hot-tape application, with training pipelines failing to match demand.
- REACH pre-registration timelines:New chemical substance approvals extend 18-24 months, delaying product launches for reformulated coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Camping Equipment Market |
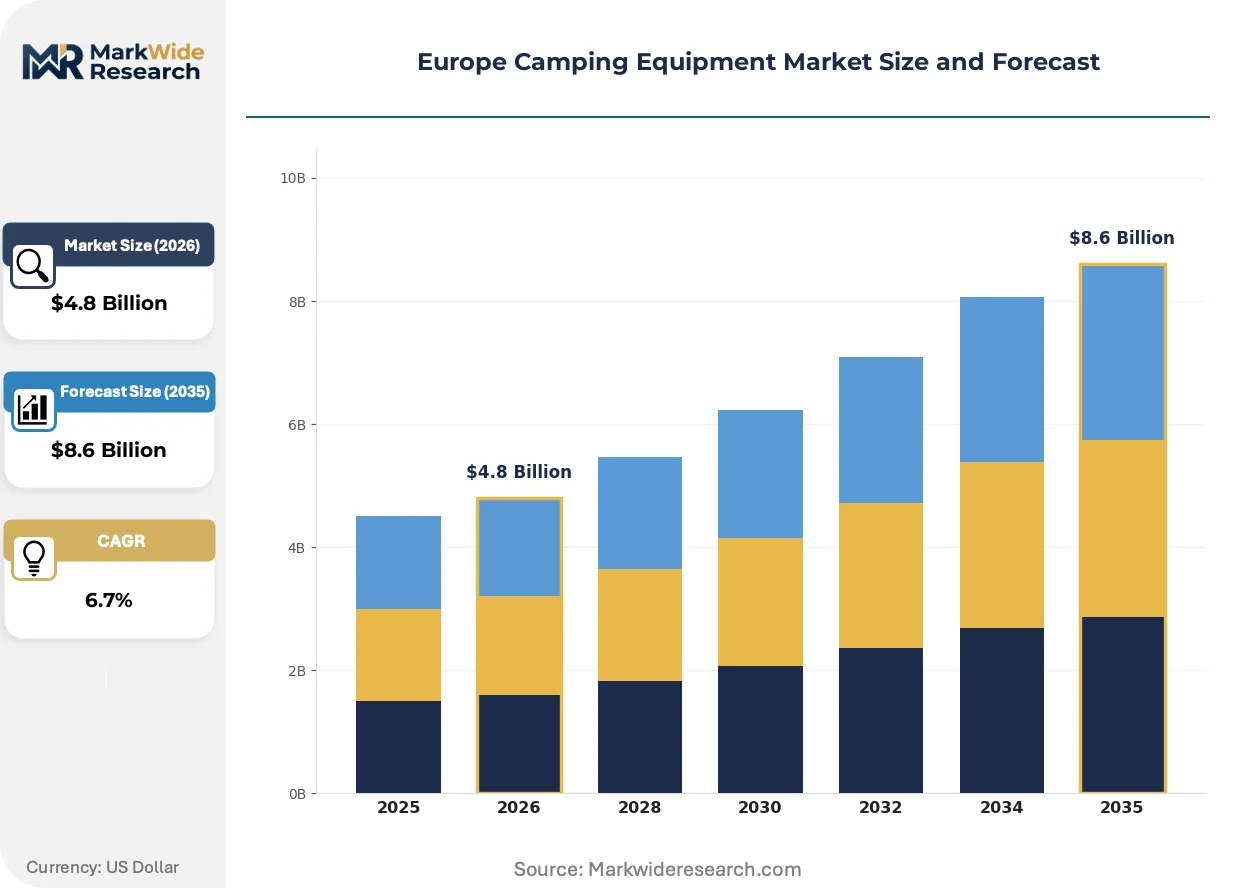
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Tents, Sleeping Bags, Cooking Gear End User: Families, Solo Travelers, Outdoor Enthusiasts, Scouts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Season: Summer, Winter, Spring, Fall |
| Companies Covered | Oase Outdoors ApS, Big Agnes, Dometic Group AB, Exxel Outdoors, Hilleberg the Tentmaker, Johnson Outdoors, AMG Group Ltd., VF Corporation, Newell Brands (The Coleman Company), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Camping Equipment Market Trends and Innovations
European camping equipment is pivoting toward chemical compliance and circular material flows, with manufacturers racing to maintain performance specifications while eliminating restricted substances from supply chains.
Silicone-impregnated nylon fabrics are migrating from niche alpine applications to mainstream three-season shelters. Solo trekkers and bikepackers across Alpine routes adopt these lighter alternatives despite higher unit costs. The shift compresses demand for traditional polyurethane-coated fabrics with shorter product lifecycles.
ECHA scrutiny of per- and polyfluoroalkyl substances under REACH Annex XVII is accelerating substance-by-substance restrictions. Manufacturers must reformulate durable water repellent coatings or surrender market access. Tent rainflies and synthetic insulation face the steepest compliance costs given performance requirements for hydrostatic head ratings.
Specialty outdoor retailers are ceding ground to direct-to-consumer channels and marketplace platforms. Younger buyers in Nordic markets research technical specifications through video content before purchasing. Brand-owned digital storefronts capture margin previously allocated to wholesale distribution, though high-involvement purchases still warrant physical inspection.
Europe Camping Equipment Market Segmentation

Segmentation in the Europe Camping Equipment Market reveals how technical specifications, trip duration, and user expertise split purchasing patterns across distinct equipment categories. Manufacturers calibrate material grades and feature sets to match these divergent use cases rather than pursuing uniform product strategies.
Product Type:
Equipment categories span the full arc from overnight car camping to multi-week alpine traverses, with each product class carrying distinct margin structures and replacement cadences.
- Tents:Fabric shelters engineered from silicone-impregnated nylon or polyurethane-coated polyester with hydrostatic head ratings typically exceeding 3000 mm. Demand concentrates in Germany and Scandinavia where family camping infrastructure expansion drives four- to six-person tunnel tent purchases for seasonal site occupancy.
- Sleeping Bags:Insulated sleep systems utilizing hydrophobic down or synthetic fills with EN 13537 temperature ratings. Solo travelers across Alpine and Nordic routes favor ultralight mummy designs with sub-kilogram packed weights for hut-to-hut trekking mobility.
- Backpacks:Load-bearing carrying systems with internal frame suspension and ripstop nylon construction. Scout groups and educational programs across France and Benelux sustain volume for durable 60-80 liter expedition packs with reinforced base panels.
- Cooking Gear:Portable stove systems and cookware fabricated from hard-anodized aluminum or titanium alloys. Bikepacking route expansion across the Pyrenees drives demand for integrated canister stove and pot combinations with nested storage efficiency.
Established volume favors tents; emerging adoption favors cooking gear.
End User:
User archetypes diverge sharply in equipment sophistication, with technical proficiency and trip autonomy dictating specification requirements and price tolerance.
- Families:Multi-generational camping parties requiring spacious shelters with standing height and partitioned sleeping compartments. German family camping participation sustains replacement cycles for durable, easy-pitch tunnel tents with extended vestibules for gear storage.
- Solo Travelers:Self-guided trekkers and bikepackers prioritizing weight minimization and packability. This category is expanding most quickly across Alpine routes where real-time booking platforms reduce planning friction for independent hut-to-hut journeys.
- Outdoor Enthusiasts:Experienced campers pursuing technical terrain and variable conditions. Scandinavian four-season camping demands expedition-grade equipment with reinforced pole structures and storm-worthy guy-out configurations.
- Scouts:Youth organization members in structured outdoor education programs. French and Belgian scouting federations maintain institutional procurement contracts for standardized, cost-optimized equipment kits with modular interchangeability.
Volume concentration sits with families; specification intensity sits with solo travelers.
Distribution Channel:
Channel selection tracks purchase involvement, with technical complexity and price point determining whether buyers seek physical inspection or digital convenience.
- Online Retail:Marketplace platforms and brand-owned storefronts capturing margin previously allocated to wholesale distribution. Nordic buyers under 35 research technical specifications through video content before purchasing lightweight shelters and sleep systems without physical handling.
- Specialty Stores:Dedicated outdoor retailers with trained staff for fit assessment and equipment matching. High-involvement purchases including four-season tents and technical sleeping bags still warrant brick-and-click hybrid models with in-person inspection.
- Supermarkets:Mass-market retailers stocking entry-level equipment for impulse and seasonal purchases. Summer camping spikes in Southern Europe drive volume for basic two-person dome tents and synthetic sleeping bags at price-competitive positioning.
- Direct Sales:Manufacturer-controlled channels including brand-owned websites and factory outlet locations. Premium Scandinavian tentmakers leverage direct relationships to communicate seam-taping standards and fabric provenance to discerning buyers.
Digital channels gain transaction share; specialty retail retains specification authority.
Season:
Seasonal variation dictates equipment performance requirements and purchasing timing, with climate adaptation driving material selection and design priorities.
- Summer:Three-season equipment optimized for ventilation and insect protection. Mediterranean camping corridors in Spain and Italy drive volume for lightweight mesh-paneled shelters with minimal rainfly coverage.
- Winter:Four-season equipment engineered for snow loading and wind resistance. Alpine regions in Austria and Switzerland demand geodesic dome structures with multiple pole intersections and reinforced guy-out points.
- Spring:Transitional equipment balancing waterproofing with breathability. Variable precipitation patterns across Northern Europe favor shelters with full-coverage rainflies and adjustable ventilation panels.
- Fall:Equipment emphasizing thermal efficiency and weather protection. Shorter daylight hours and cooling temperatures in Benelux and Germany drive demand for insulated sleep systems with comfort ratings approaching freezing.
Summer commands transaction volume; winter commands specification premium.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portugal and Scandinavia concentrate textile and shelter manufacturing capacity, while Germany anchors continental demand through expanded alpine infrastructure.
Germany
Alpine and forest camping infrastructure expansion drives four- to six-person tunnel tent purchases for seasonal site occupancy. EU Green Deal procurement mandates require recycled content thresholds in public sector investments. Bavaria hosts multiple family camping equipment distributors serving Central European retail networks.
Sweden
Four-season shelter demand from Scandinavian outdoor enthusiasts sustains technical manufacturing standards. ECHA REACH restrictions on per- and polyfluoroalkyl substances force reformulation of durable water repellent coatings. Stockholm and Gothenburg anchor premium tent production with exacting seam-taping capabilities.
Portugal
Underutilized textile capacity in northern regions offers nearshoring alternatives for synthetic fabric assembly. CSRD disclosure requirements create first-mover advantage for brands with pre-audited circular material flows. Porto and Braga clusters specialize in lightweight tent fabrics and synthetic insulation production.
France
Scout group procurement across French and Belgian federations sustains volume for standardized equipment kits. REACH Annex XVII substance-by-substance restrictions accelerate migration to silicone-based water repellent alternatives. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur host technical sleeping bag distributors serving Alpine route networks.
Austria
Hut-to-hut trekking digitalization expands addressable demand for lightweight technical equipment. ECHA scrutiny of fluorinated chemistries compresses margins for manufacturers dependent on legacy coating formulations. Tyrol and Salzburg regions concentrate alpine camping infrastructure investment with geodesic dome shelter requirements.
Europe Camping Equipment Market Competitive Landscape
Premium technical specialists and family camping volume players split the market along specification intensity lines. The vendor base organizes into three strategic archetypes: Scandinavian four-season shelter fabricators, Northern European family camping distributors, and technical sleep system specialists. Competitive moves concentrate on Portuguese textile capacity expansion and direct-to-consumer channel capture through brand-owned digital storefronts.
Within the premium technical tier, Hilleberg the Tentmaker and AMG Group Ltd. exemplify exacting manufacturing standards. Oase Outdoors ApS occupies a position in family camping distribution across Northern Europe. These three anchors represent divergent strategic postures: Scandinavian precision manufacturing, British technical specialization, and Danish retail network scale.
| Leading Market Players |
|---|
| Oase Outdoors ApS |
| Big Agnes |
| Dometic Group AB |
| Exxel Outdoors |
| Hilleberg the Tentmaker |
| Johnson Outdoors |
| AMG Group Ltd. |
| VF Corporation |
| Newell Brands (The Coleman Company) |
| Others |
Pricing and Supply Chain Analysis
Porto's northern textile clusters concentrate lightweight synthetic fabric assembly capacity, with underutilized loom infrastructure translating into downstream pricing leverage for tent manufacturers seeking European nearshoring alternatives to Asian suppliers. REACH Annex XVII substance restrictions on per- and polyfluoroalkyl substances compress margin structures across coating reformulation cycles, forcing tiered pricing stratification that separates premium silicone-impregnated shelters from standard polyurethane-coated alternatives.
Pricing Analysis
EU Green Deal procurement mandates dictate the pricing tier structure across public sector camping infrastructure investments, with recycled content certification thresholds creating price differentiation between certified sustainable gear and conventional alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects hydrostatic head performance ratings, seam-taping precision grades, and after-sales service bundling. Cost compression in mid-tier family camping shelters is intensifying because silicone-based water repellent alternatives require extended curing protocols and retooled application lines. Scout group procurement federations exhibit highest price sensitivity due to institutional budget constraints, while solo trekkers across Alpine routes demonstrate lowest sensitivity to unit cost premiums for sub-kilogram packed weights.
Supply Chain Analysis
Export-control scrutiny of fluorinated chemistry precursors under REACH Annex XVII constrains coating formulation flows from legacy European suppliers to reformulation facilities. Geographic supply concentration centers on Portugal for synthetic fabric assembly, Eastern Europe for hydrophobic down processing, and Scandinavia for four-season shelter fabrication with exacting seam-taping standards. Raw material dependencies draw from ripstop nylon yarn, aluminum alloy extrusions for tent pole structures, and hydrophobic down fills. Single-source vulnerability clusters in Eastern European down processing facilities create supply chain risk exposure. Distribution runs through direct-to-consumer brand storefronts capturing margin previously allocated to wholesale networks, though specialty retail retains authority for high-involvement technical purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's camping equipment sector faces high-growth disruption from ECHA's accelerating substance-by-substance restrictions under REACH, which compel wholesale coating reformulation while opening first-mover advantage for pre-audited circular material flows.
For Market Incumbents: Entrench position through backward integration into Portuguese textile capacity and captive control over hydrophobic down processing clusters in Eastern Europe. Invest in seam-taping technician training pipelines to address capability scarcity threatening four-season production expansion. Pre-audit supply chain transparency under CSRD disclosure requirements before mandatory compliance deadlines erode first-mover positioning. For New Entrants and Emerging Players: Southern European camping corridors in Spain and Italy present geographic underpenetration for lightweight mesh-paneled three-season shelters optimized for Mediterranean summer conditions. Target bikepacking route networks across the Pyrenees with ultralight cooking gear combinations featuring nested storage efficiency. Pursue direct-to-consumer video content marketing to capture Nordic buyers under 35 who research technical specifications without physical handling. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate outdoor divisions lacking circular material flow documentation needed for EU Green Deal procurement eligibility. Frame long-term viability around CSRD-mandated supply chain transparency as a structural moat separating compliant from non-compliant equipment suppliers. Monitor ECHA pre-registration timelines for silicone-based water repellent alternatives as inflection indicator for product launch velocity across the vendor base.| Strategic Initiative | Industry Significance |
|---|---|
| Portuguese Textile Capacity Expansion | Nearshoring alternatives to Asian synthetic fabric suppliers reduce lead times and carbon footprint exposure. |
| Silicone-Based Coating Reformulation | REACH-compliant water repellent alternatives preserve market access across ECHA-regulated member states. |
| Direct-to-Consumer Channel Capture | Brand-owned digital storefronts reclaim margin previously allocated to wholesale distribution networks. |
| Seam-Taping Technician Training Programs | Skilled operator pipelines address production bottlenecks in four-season shelter manufacturing. |
| CSRD Supply Chain Pre-Auditing | Pre-mandate transparency documentation creates procurement advantage for EU Green Deal public sector contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade records, ECHA substance restriction databases, and EU Green Deal procurement disclosure filings. Primary interviews engaged product development directors at tent manufacturers, procurement leads at scout federation headquarters, and technical R&D heads at synthetic insulation producers. Secondary validation drew from SEC filings of listed outdoor equipment vendors, REACH Annex XVII regulatory updates, and retail audit data from Nordic marketplace platforms. Bottom-up equipment shipment analysis triangulates against top-down consumer expenditure estimates across the projection horizon.
Forecast inputs include segment-level modeling across product type, end user archetype, distribution channel, and seasonal demand variation. The analytical framework incorporates replacement cycle dynamics for tent rainflies exposed to seasonal damage, EN 13537 temperature rating adoption curves for sleeping systems, and real-time booking platform penetration rates for Alpine hut-to-hut trekking routes. CAGRs derive from equipment category growth differentials and channel shift velocity parameters calibrated against historical analogs.
Practitioners should monitor ECHA substance restriction announcements, aluminum alloy smelting cost volatility, and Portuguese textile capacity utilization rates for early signals of forecast deviation. Material shifts in REACH pre-registration approval timelines or EU Green Deal recycled content threshold revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Camping Cooler Market