
 Global Canoe and Kayak Market | 2026-2036
Global Canoe and Kayak Market Size, Share, and Industry Trends Forecast 2026-2036
Global Canoe and Kayak Market Analysis
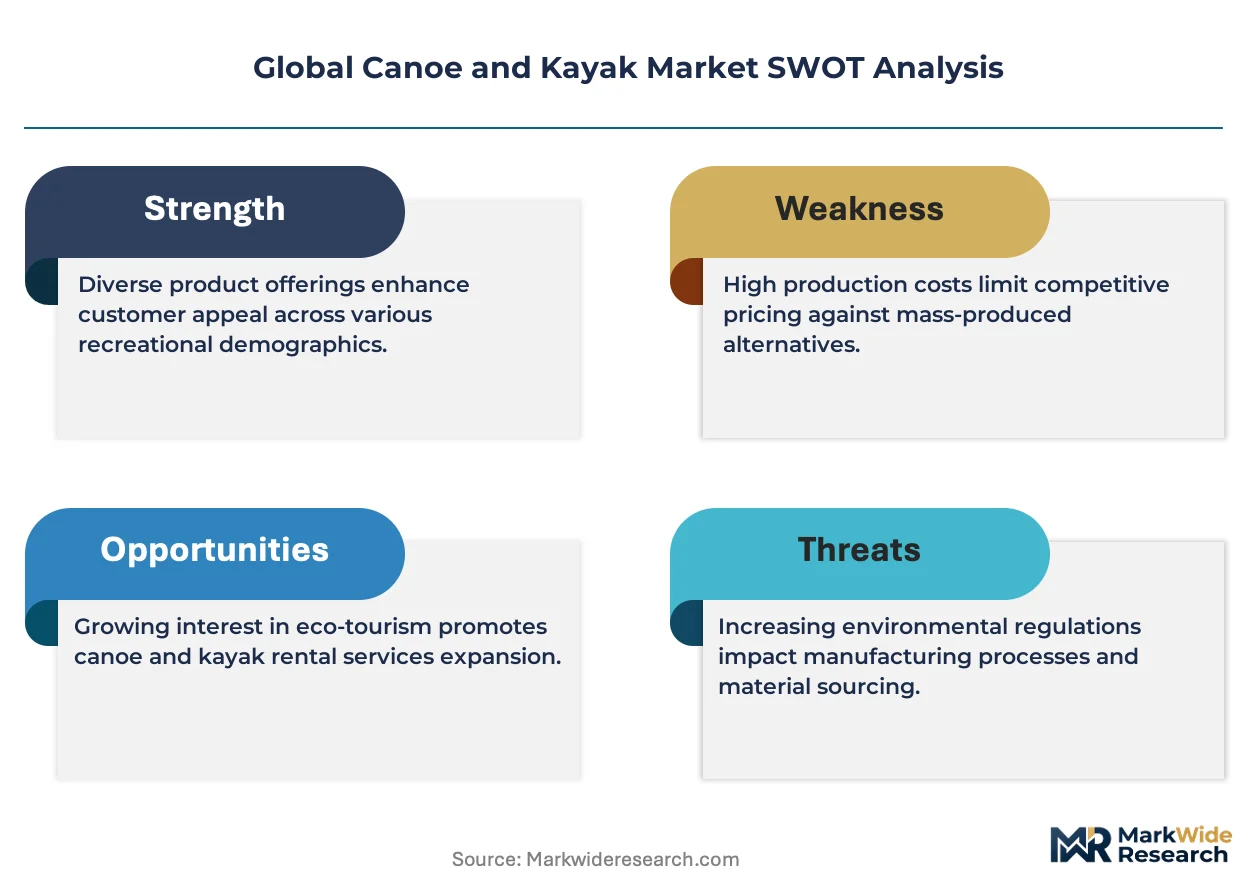
Specialty sporting goods retail is reshaping how paddle craft reach end users, with dedicated water sports chains and experiential showrooms displacing generalist big-box shelf space. Pelican International leverages its Quebec manufacturing base to sustain cost-competitive polyethylene kayak output across North American markets. Old Town Canoes & Kayaks anchors its position through in-house rotomolding capacity and deep ties to outfitter networks in the northeastern United States. Wilderness Systems differentiates via performance-oriented sit-on-top and touring kayak architectures aimed at coastal and river expedition segments.
Canoes and kayaks constitute human-powered watercraft propelled by single or double-bladed paddles, typically constructed from thermoformed plastics, composite laminates, or aluminum alloys with hull lengths spanning 2.5 to 6 meters and beam widths optimized for stability or speed. These vessels serve recreational navigation, competitive sprint and slalom racing, guided tourism, and institutional outdoor education programs across freshwater and protected marine environments. Plastic hull configurations dominate unit volume due to durability and price accessibility, while fiberglass and carbon-composite constructions command premium positioning among professional athletes and expedition tour operators seeking reduced weight and enhanced hydrodynamic efficiency. Recreational users represent the largest addressable population, though tour operators generate disproportionate fleet replacement demand and influence bulk procurement specifications.
EPA regulations govern volatile organic compound emissions from composite manufacturing processes in the United States, while REACH restricts phthalate plasticizers and certain resin additives across European supply chains. ISO 12217 small craft stability and buoyancy standards further condition product design and market access for international trade. Stakeholders must monitor evolving material compliance costs and stability certification requirements as regulatory divergence between major markets intensifies sourcing complexity for multi-region brands.
Market Dynamics
Experiential travel operators are concentrating fleet procurement power, reshaping supplier relationships as polyethylene hull specifications tighten under REACH and EPA manufacturing standards.
Growth Catalysts
- Rotomolding efficiency gains:In-house polyethylene production capabilities at major North American facilities are compressing per-unit manufacturing costs and shortening delivery timelines for recreational craft.
- REACH compliance investments:European manufacturers phasing out phthalate plasticizers ahead of regulatory deadlines are capturing preferential supplier status with institutional buyers.
- Tour operator fleet expansion:Water-based experiential travel programs across Germany, Australia, and the United States are generating sustained bulk replacement cycles for composite and plastic hull vessels.
Market Restraints
- Petroleum-based resin volatility:Polyethylene and composite resin feedstock costs fluctuate with crude oil indices, compressing margin stability for rotomolding-dependent producers.
- Rotomolding capacity concentration:Hull production clusters in Quebec and the northeastern United States create geographic supply risk for brands lacking multi-source manufacturing footprints.
- ISO 12217 certification timelines:Stability and buoyancy testing requirements extend product development cycles by 8-14 months for new hull architectures targeting international markets.
Strategic Opportunities
- Carbon-composite premium tier:Reduced-weight hull technologies are opening expedition and competitive racing segments where price sensitivity remains low.
- Institutional outdoor education:University and municipal recreation programs across Australia represent underpenetrated fleet buyers with multi-year procurement horizons.
- Experiential showroom channels:Dedicated water sports retail formats are displacing generalist distribution, enabling direct consumer education and higher-margin configuration sales.
Industry Challenges
- Rotational molding technician scarcity:Specialized mold operation and polyethylene flow control expertise remains concentrated among legacy manufacturing workforces in Quebec and Maine.
- Multi-jurisdiction compliance synchronization:Diverging EPA volatile organic compound limits and REACH substance restrictions force parallel product line maintenance for transatlantic brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Canoe and Kayak Market |
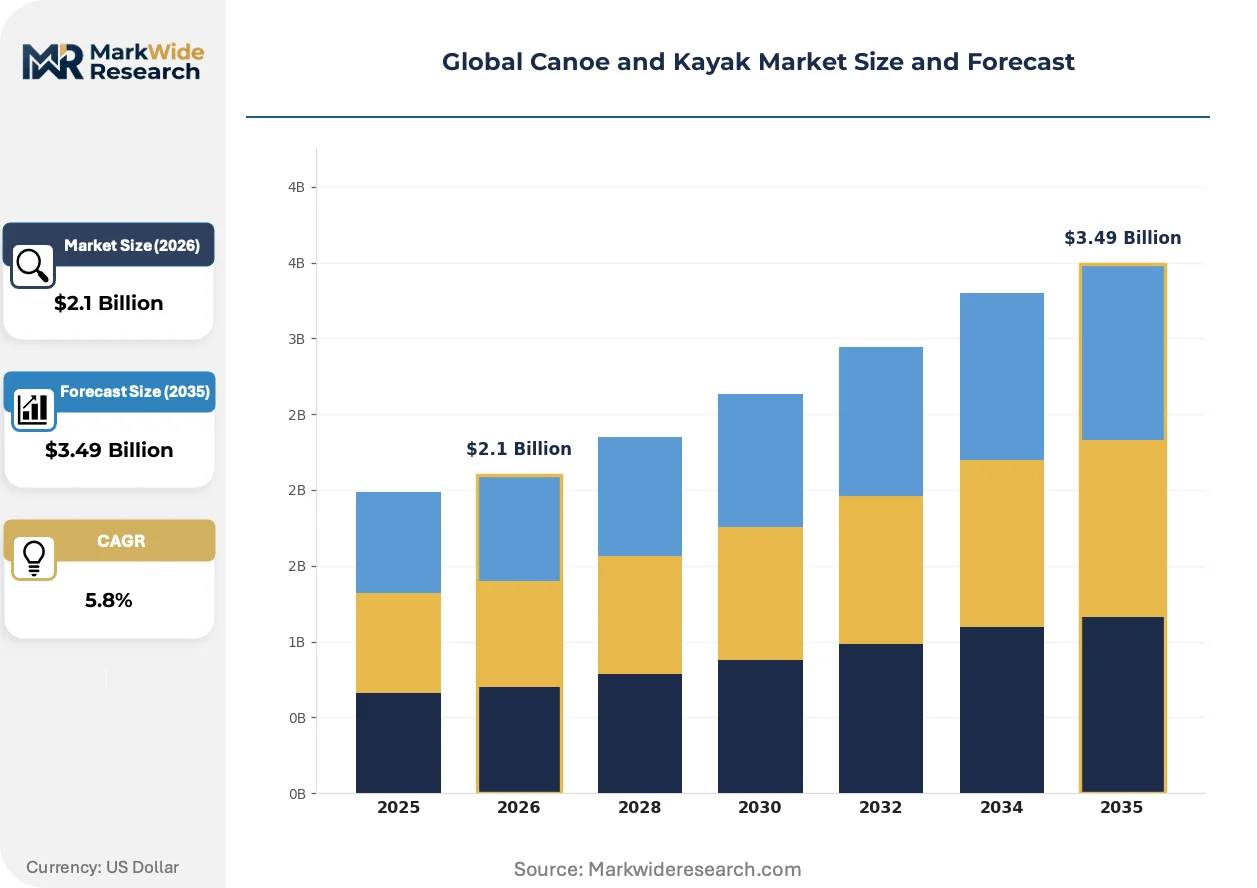
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
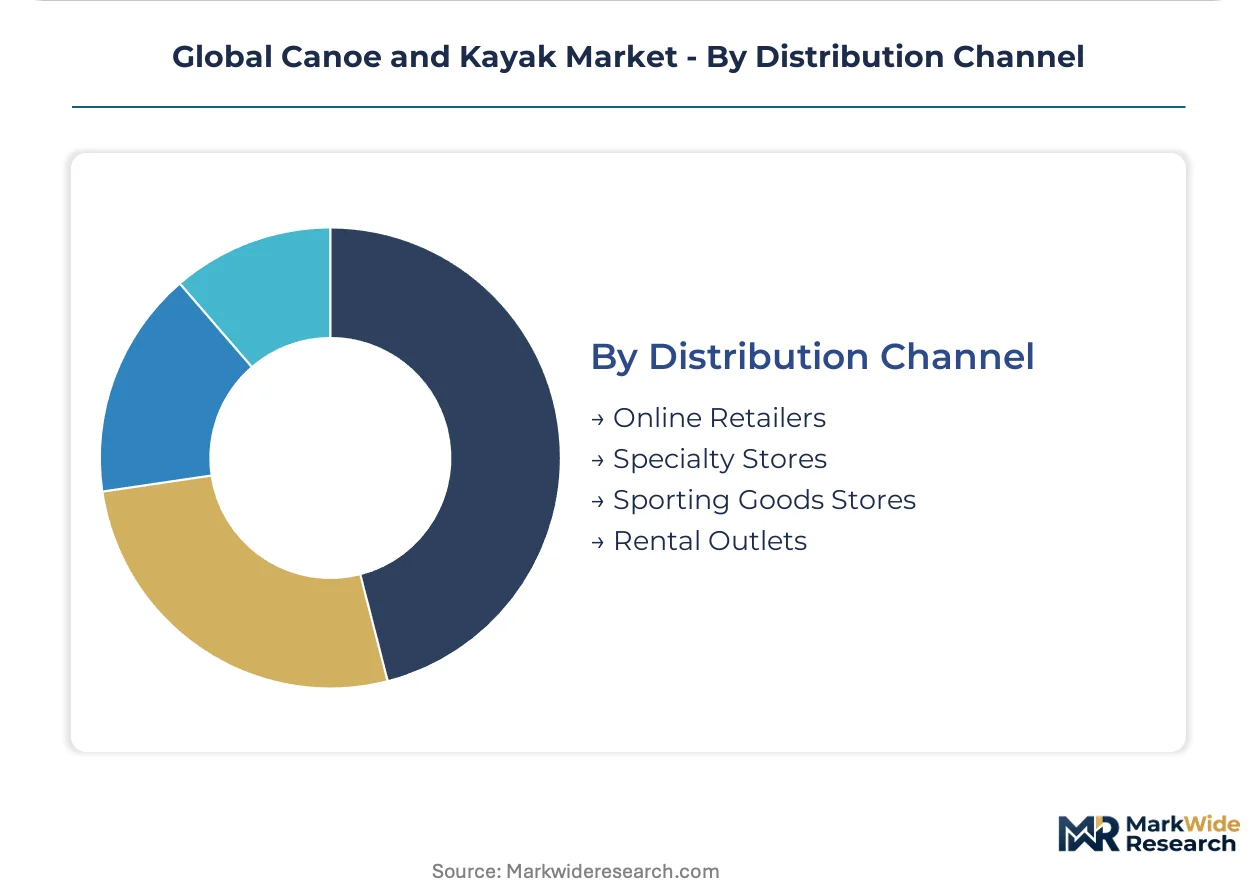
| Segmentation | Product Type: Canoes, Kayaks, Paddle Boards, Rafts Material: Plastic, Fiberglass, Aluminum, Wood End User: Recreational Users, Professional Athletes, Schools, Tour Operators Distribution Channel: Online Retailers, Specialty Stores, Sporting Goods Stores, Rental Outlets |
| Companies Covered | Pelican International, Old Town Canoes & Kayaks, Perception Kayaks, Wilderness Systems, Riot Kayaks, Advanced Elements, BIC Sport, Oru Kayak, Gumotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Canoe and Kayak Market Emerging Trajectories
Material science advances and regulatory stringency are compressing traditional manufacturing methods while experiential retail formats rewrite how paddle craft reach end users.
Thermoformed plastic hull construction is collapsing the durability-weight tradeoff that previously separated recreational polyethylene craft from premium composite alternatives. Coastal expedition operators in Australia and the Pacific Northwest are adopting these hybrid architectures for fleet standardization, eliminating the need to maintain separate maintenance protocols for plastic and composite vessels.
EPA volatile organic compound emission standards for composite lamination processes are forcing manufacturing consolidation among smaller fiberglass and carbon-hull producers. Brands with captive rotomolding capacity or capital to install closed-mold infusion systems are absorbing displaced volume as traditional open-mold operations face facility upgrade costs exceeding operational cash flows.
Specialty water sports chains are displacing big-box retail as the primary consumer touchpoint for recreational kayak purchases. Outfitter-adjacent showrooms in Germany, Colorado, and New South Wales are capturing preference through on-water demonstration programs that generalist channels cannot replicate, compressing the traditional seasonal sales cycle into year-round experiential bookings.
Global Canoe and Kayak Market Segmentation
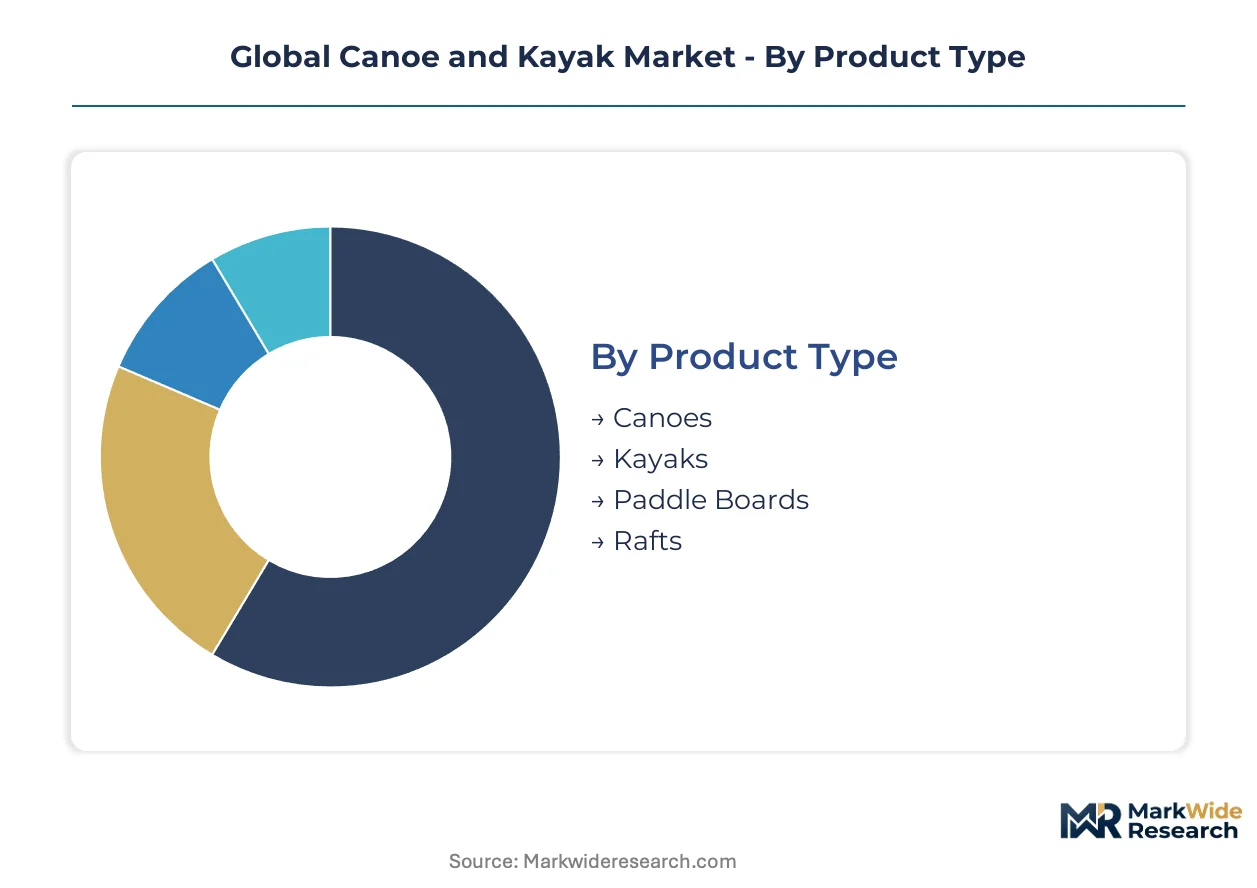
Segmentation in the canoe and kayak market determines service intensity, margin structure, and channel strategy. Hull material drives replacement cycles and warranty exposure. End-user type dictates fleet versus individual purchasing patterns. Distribution channel shapes brand positioning and customer education requirements.
Product Type:
After-sales service intensity varies dramatically across hull architectures, with rental fleets demanding preventive maintenance contracts and individual recreational buyers requiring minimal post-purchase support.
- Canoes:Open-deck vessels with symmetrical hull profiles constructed from polyethylene or aluminum alloys, optimized for tandem paddling and gear capacity. Demand concentrates among outfitters in Maine and Minnesota where multi-day river expedition programs require durable, repairable hulls that withstand rocky put-in damage. These operators prioritize rotomolded polyethylene for field weldability over weight savings.
- Kayaks:Closed or sit-on-top deck configurations with asymmetrical hull lines designed for solo propulsion efficiency. Coastal expedition operators in Australia's New South Wales and British Columbia's Vancouver Island are standardizing on thermoformed plastic hybrids that bridge recreational durability with composite weight reduction, driven by fleet maintenance cost compression.
- Paddle Boards:Planing hull platforms propelled by single-blade standing paddles, typically constructed from EPS foam cores with fiberglass or PVC skin laminates. Recreational users in Florida and California beach communities dominate volume.
- Rafts:Inflatable or rigid multi-chamber vessels for whitewater navigation, built from PVC-coated polyester or hypalon rubber. Commercial river guides in Colorado and West Virginia represent core demand.
By volume, kayaks lead. By growth pace, paddle boards are climbing the fastest.
Material:
Material selection governs manufacturing capital requirements, regulatory compliance burden, and end-user price sensitivity thresholds.
- Plastic:Rotomolded polyethylene or thermoformed ABS constructions dominating recreational unit volume through impact resistance and sub-premium price positioning. REACH phthalate restrictions are forcing European producers toward linear low-density polyethylene formulations that maintain durability without restricted plasticizers.
- Fiberglass:E-glass or S-glass fiber laminates with polyester or vinylester resin matrices, offering weight reduction for touring and competitive applications. EPA volatile organic compound emission limits are consolidating production among facilities with closed-mold infusion capability.
- Aluminum:Marine-grade alloy hulls riveted or welded for institutional durability, concentrated in municipal park fleets and military training programs.
- Wood:Cedar strip or plywood constructions with fiberglass sheathing, serving custom craft builders and traditional paddling enthusiasts in Scandinavia and the Pacific Northwest.
Plastic commands absolute unit volume. Fiberglass maintains steepest expansion trajectory in expedition and racing niches.
End User:
Customer type determines procurement scale, specification authority, and replacement cycle predictability.
- Recreational Users:Individual purchasers seeking casual freshwater or coastal paddling, typically acquiring single units through retail channels with minimal technical specification involvement.
- Professional Athletes:Competitive sprint, slalom, and expedition racers requiring FISA or ICF specification compliance, driving carbon-composite hull development.
- Schools:University and secondary education programs with multi-year fleet procurement horizons, concentrated in Australia's Queensland and Germany's Bavaria where outdoor education curricula mandate water-based components.
- Tour Operators:Experiential travel providers generating bulk replacement demand and influencing hull standardization across Australia, Germany, and the United States. These buyers negotiate multi-vessel contracts with maintenance-inclusive pricing.
Tour operators drive fleet standardization. Schools represent the most underpenetrated procurement channel.
Distribution Channel:
Channel structure determines customer education depth, configuration complexity, and margin capture potential.
- Online Retailers:E-commerce platforms capturing price-sensitive recreational volume with limited pre-purchase hull assessment, concentrated in suburban markets distant from water access.
- Specialty Stores:Dedicated water sports retailers with on-water demonstration programs and technical staff expertise, displacing generalist channels in Germany, Colorado, and New South Wales.
- Sporting Goods Stores:Generalist retailers with seasonal shelf space allocation, losing share to experiential showrooms that compress traditional sales cycles.
- Rental Outlets:Fleet operators selling ex-rental inventory or directing new vessel procurement for affiliate programs, concentrated in tourist-dependent coastal economies.
Specialty stores gain share fastest. Online retailers retain volume leadership in entry-level segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines in Europe and EPA manufacturing standards in North America are redirecting polyethylene hull production toward facilities with captive rotomolding capacity. Tour operator fleet expansion across Germany, Australia, and the United States is concentrating demand for standardized vessel specifications.
United States
Experiential travel operators in Colorado and the Pacific Northwest are driving bulk procurement cycles for thermoformed plastic hybrids. EPA volatile organic compound emission limits for composite lamination are consolidating production among facilities with closed-mold infusion systems. Old Town Canoes & Kayaks anchors rotomolding operations in Maine, supplying outfitter networks across the northeastern corridor.
Germany
Outdoor education curricula in Bavaria mandate water-based components, generating multi-year fleet procurement from universities and municipal programs. ECHA phthalate restrictions under REACH are forcing producers toward linear low-density polyethylene formulations without restricted plasticizers. Specialty water sports retailers in Munich and Hamburg are displacing generalist channels through on-water demonstration programs.
Australia
Tour operators in New South Wales and Queensland are standardizing fleet architectures to eliminate separate maintenance protocols for plastic and composite vessels. The country's national environmental regulator enforces stability certification requirements aligned with ISO 12217 standards for commercial operations. Coastal expedition providers in British Columbia's Vancouver Island influence procurement specifications through bulk replacement demand.
Canada
Pelican International leverages its Quebec manufacturing base to sustain cost-competitive polyethylene output across North American markets. Health Canada and PMRA coordinate material safety standards with EPA thresholds for cross-border supply chains. Montreal-area rotomolding clusters concentrate specialized technician expertise for polyethylene flow control and mold operation.
United Kingdom
Traditional paddling enthusiasts in Scotland and the Lake District sustain demand for cedar strip and plywood constructions with fiberglass sheathing. CE marking requirements under EU-UK trade arrangements condition product design for vessels targeting continental European markets. Outfitter networks in Wales and Cornwall prioritize field-repairable hull specifications for rocky coastal put-in environments.
Global Canoe and Kayak Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturers with captive rotomolding capacity and established outfitter relationships. Three strategic archetypes dominate: vertically integrated polyethylene producers with regional manufacturing footprints, composite specialists serving expedition and racing niches, and inflatable craft innovators targeting portability-driven recreational segments. Competitive moves center on capacity expansion in Quebec and Maine manufacturing clusters, plus strategic partnerships between hull fabricators and experiential travel operators for fleet standardization contracts.
Among North American fabricators, Pelican International, Old Town Canoes & Kayaks, and Wilderness Systems occupy distinct positioning tiers. Pelican International exemplifies the scale-driven polyethylene producer archetype through its Quebec-based manufacturing concentration. Old Town Canoes & Kayaks represents the vertically integrated outfitter-aligned model with deep ties to northeastern United States rental and expedition networks. Wilderness Systems anchors the performance-oriented tier, situating its product architectures within coastal and river expedition segments where hydrodynamic efficiency commands premium positioning.
| Leading Market Players |
|---|
| Pelican International |
| Old Town Canoes & Kayaks |
| Perception Kayaks |
| Wilderness Systems |
| Riot Kayaks |
| Advanced Elements |
| BIC Sport |
| Oru Kayak |
| Gumotex |
| Others |
Supply Flow & Price Mechanics
Petroleum-based resin volatility determines both pricing tier spreads and supply chain shape, compressing margin stability for rotomolding-dependent producers while forcing polyethylene hull manufacturers toward captive feedstock arrangements or long-term offtake contracts with Gulf Coast petrochemical suppliers.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 12217-compliant hulls commanding substantial premiums over uncertified recreational craft. Three-tier pricing structure across premium, standard, and economy levels reflects material grade, with carbon-composite expedition vessels at the apex and rotomolded polyethylene entry craft at the base. Pricing pressure stems from crude oil index fluctuations affecting resin feedstock costs. Recreational users exhibit highest price sensitivity, while tour operators prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Polyethylene resin feedstock draws from Gulf Coast petrochemical complexes in the United States, Alberta oil sands derivatives in Canada, and Rotterdam refining hubs in the Netherlands. Hull fabrication clusters in Quebec, Maine, and Bavaria transform these inputs through rotational molding and thermoforming processes. Single-source vulnerability concentrates in specialized mold operation expertise retained by legacy workforces in Montreal-area and Portland, Maine manufacturing nodes. Distribution runs through specialty water sports retailers with on-water demonstration capabilities, displacing generalist sporting goods channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as experiential travel operators disaggregate procurement authority away from consolidated retail channels, enabling specialist fabricators to capture fleet standardization contracts.
For Market Incumbents: Insulate rotomolding capacity advantages through technician apprenticeship programs in Quebec and Maine, locking in polyethylene flow control expertise that emerging competitors cannot replicate. Secure multi-year fleet maintenance contracts with Australian and German tour operators to create switching costs. Prioritize REACH-compliant linear low-density polyethylene formulations ahead of regulatory deadlines to capture preferential supplier status with European institutional buyers. For New Entrants and Emerging Players: Establish a beachhead in Australian university outdoor education programs, the most underpenetrated procurement channel with multi-year fleet replacement horizons and limited incumbent relationships. Target municipal recreation departments in Bavaria and Queensland where curriculum mandates drive sustained demand. Pursue direct sales models through outfitter-adjacent experiential showrooms rather than competing for big-box shelf space. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated polyethylene producers with captive resin arrangements and established outfitter networks. Long-term viability hinges on regulatory compliance capabilities rather than pure manufacturing scale. Monitor ECHA substance restriction announcements and EPA volatile organic compound threshold revisions as inflection indicators for stranded asset risk in traditional open-mold composite operations.| Strategic Initiative | Industry Significance |
|---|---|
| Rotomolding Capacity Expansion | Captive polyethylene production in Quebec compresses per-unit costs and shortens delivery timelines for North American fleet buyers. |
| REACH Compliance Investment | Phthalate-free formulation development ahead of ECHA deadlines secures preferential supplier status with European institutional procurement. |
| Experiential Showroom Partnership | On-water demonstration programs through specialty retailers in Colorado and New South Wales displace generalist distribution channels. |
| Carbon-Composite R&D Program | Reduced-weight hull technologies open expedition and competitive racing segments where price sensitivity remains minimal. |
| Technician Apprenticeship Pipeline | Mold operation expertise development in Maine and Quebec addresses rotational molding technician scarcity constraining capacity expansion. |
Methodological Framework
A standing panel of rotomolding plant managers, tour operator fleet procurement directors, specialty retailer buyers, and outdoor education program coordinators provided ongoing calibration across the study period. Primary interview insights triangulated against customs and trade data, SEC filings from disclosed industry participants, EPA enforcement records, and ECHA substance restriction announcements. Bottom-up vessel production estimates and top-down experiential travel market sizing converged through iterative reconciliation.
Scenario-bracketing around resin price volatility, regulatory compliance timelines, and tour operator fleet expansion rates bounded the projection range across the analysis window. Segmentation modeling incorporated hull material, end-user type, distribution channel, and geographic regulatory cluster dimensions. CAGRs derived from historical production trajectories and forward-looking procurement survey data, with particular weighting applied to Australian and German fleet replacement cycles.
Stress conditions across crude oil price bands, REACH substance restriction implementation speeds, and rotomolding technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and tour operator demand continuity. Cross-checking against ICF and FISA competitive equipment registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Kids Scooter Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Global Artificial Grass Market
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Artificial Turf Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Skateboard Ramp Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Global Swimming Pool Market