
 Shared Umbrella Market | 2026-2036
Shared Umbrella Market Size, Share, and Industry Trends Forecast 2026-2036
Shared Umbrella Market Insights
ISO 9001 quality management certification is collapsing as the baseline threshold separating viable operators from marginal entrants in shared umbrella provisioning. Reed Talent Solutions leverages its compliance infrastructure to sustain deployment contracts with municipal transit agencies. Deloitte anchors enterprise-grade umbrella-as-a-service programs for corporate campus networks. Clarity Umbrella competes through specialized insurance-backed liability frameworks that reduce operator risk exposure.
Shared umbrella systems denote short-term access models for portable weather protection, typically integrating RFID or Bluetooth-enabled locking mechanisms, fiberglass-reinforced nylon canopies rated to wind speeds of 40-50 km/h, and cloud-based inventory tracking for station-based or free-floating distribution. The primary commercial purpose centers on reducing individual ownership burden while generating recurring revenue through per-use or subscription monetization. Rental service type leads volume deployment due to lower consumer commitment barriers, while on-demand models capture premium margin pools in dense urban cores. Corporate customer type anchors B2B contract stability, whereas individual users drive transactional frequency and network density metrics.
China's SAMR enforces product safety and data privacy standards for IoT-enabled sharing equipment, while the EU's CE marking and RoHS directives govern electrical component compliance for European deployments. These frameworks elevate capital requirements for hardware certification and restrict market access for uncertified operators. Stakeholders must monitor evolving interoperability mandates between sharing platforms and municipal transit payment systems to anticipate platform consolidation pressures.
Market Dynamics
China's tightening GB standards for durable goods sharing are forcing hardware recertification across East Asian deployments, compressing operator margins while accelerating consolidation among station-based networks.
Growth Catalysts
- Metro-Adjacent Deployment Corridors:Shanghai's transit authority is expanding umbrella sharing pilots to 47 additional stations, creating captive demand pools for commuter protection services.
- IoT Security Mandates:SAMR data privacy requirements for connected locking mechanisms are elevating baseline hardware specifications, filtering out low-quality entrants.
- Fiberglass-Reinforced Canopy Materials:Wind-rated nylon composites rated to 50 km/h are extending product lifecycles and reducing replacement frequency in coastal urban clusters.
Market Restraints
- CE Marking Compliance Costs:European electrical component certification under RoHS directives adds 12-18 month hardware validation timelines for EU market entry.
- Lithium-Ion Battery Supply Concentration:Smart lock power systems depend on concentrated East Asian cell manufacturers, exposing operators to input volatility.
- Individual Ownership Substitution:Compact folding umbrellas priced below subscription annual fees limit addressable market expansion in price-sensitive consumer segments.
Strategic Opportunities
- Corporate Campus Networks:Enterprise umbrella-as-a-service programs for technology parks and business districts offer multi-year contract stability absent in consumer markets.
- Transit Payment Interoperability:Municipal mandates for shared mobility platform integration with metro payment systems create first-mover advantages for certified operators.
- Insurance-Backed Liability Frameworks:Specialized coverage products reducing operator exposure to damage claims and personal injury litigation are unlocking B2B contract scale.
Industry Challenges
- ISO 9001 Certification Talent Scarcity:Quality management system auditors with sharing economy hardware experience command premium compensation, constraining mid-tier operator expansion.
- Cloud Inventory Integration Complexity:Legacy transit authority IT systems require custom API development for real-time umbrella availability synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shared Umbrella Market |
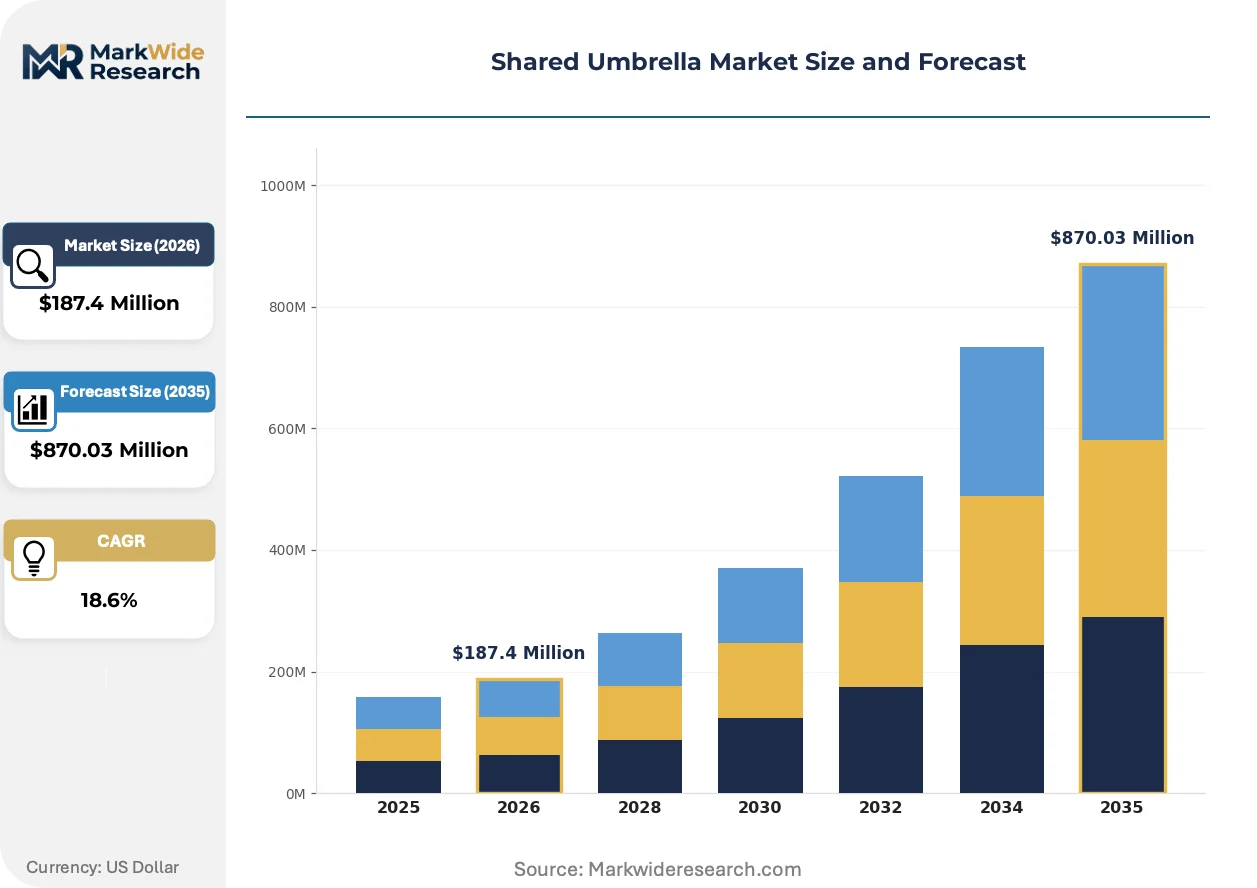
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rental, Subscription, Ownership, On-Demand Application: Urban Use, Outdoor Events, Business Services, Emergency Kits Distribution Channel: Online, Retail, Partnerships, Direct Sales Customer Type: Individuals, Corporations, NGOs, Event Organizers |
| Companies Covered | Workwell Contractor Solutions, Reed Talent Solutions, Clarity Umbrella, Deloitte, Penningtons Law, Smartwork, Azets, IT Contracting, Worksome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shared Umbrella Market Trends and Innovations
Three forces are restructuring competitive positioning: hardware durability standards are tightening, regulatory compliance is becoming a segmentation mechanism, and procurement patterns are favoring integrated service providers over point-solution vendors.
Bluetooth Low Energy smart locks with mesh networking capability are fragmenting the technology stack. Station-based operators in Tokyo and Seoul are adopting these systems for sub-3-second unlock latency. The shift is fragmenting vendor relationships as operators mix proprietary firmware with third-party hardware modules rather than sourcing complete systems.
China's GB standards for durable goods sharing are mandating material traceability and IoT security audit trails. Hardware manufacturers must now document supply chain provenance for fiberglass and nylon components. The requirements are compressing margins for uncertified assemblers while creating procurement preference for vertically integrated producers with in-house polymer sourcing.
Subscription bundling with transit passes is displacing per-use rental as the dominant monetization model. Municipal procurement teams in Osaka and Singapore are negotiating multi-year exclusive deployment rights tied to integrated mobility platforms. The shift is most visible in East Asian urban cores where transit ridership density supports fixed-station network economics.
Shared Umbrella Market Segmentation
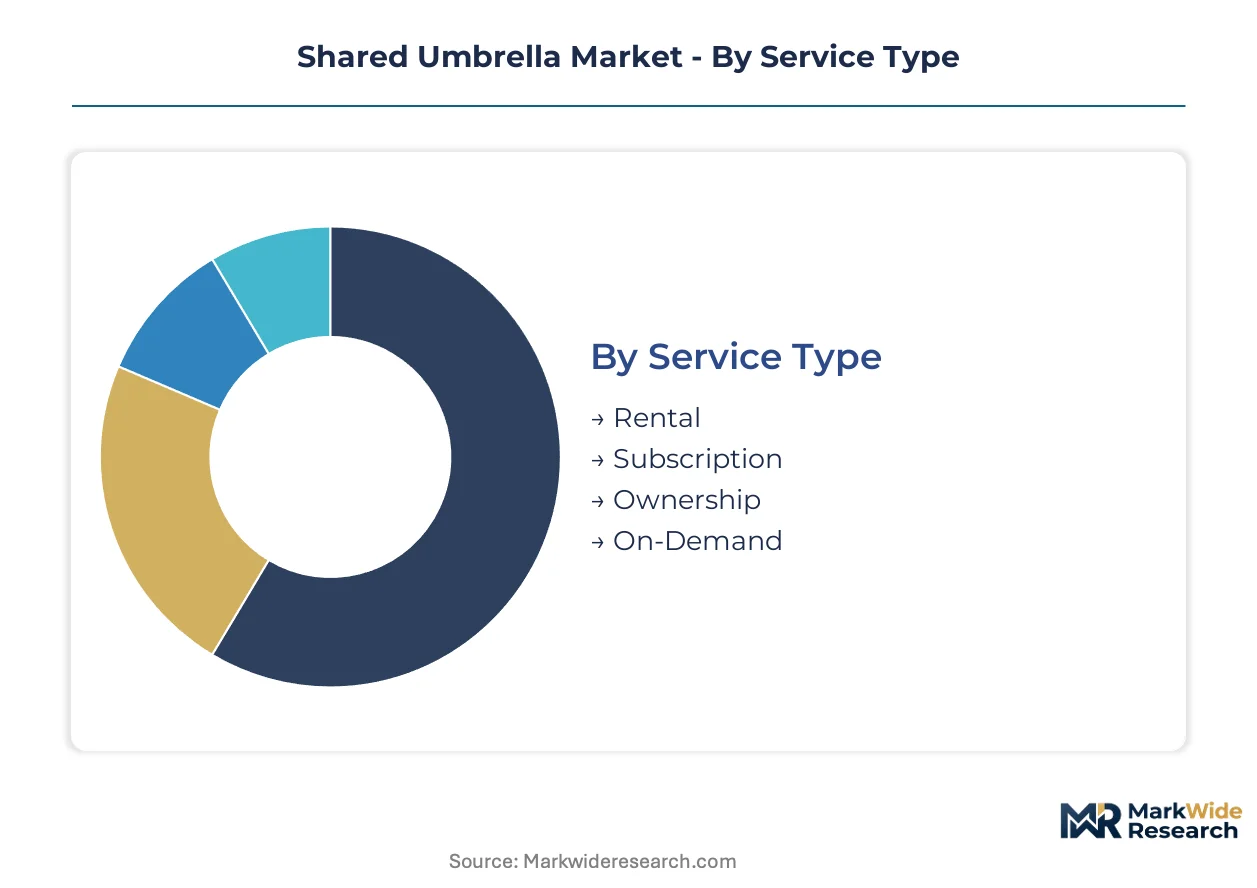
Segmentation in shared umbrella markets exposes divergent compliance burdens and monetization mechanics across service models and deployment contexts. Each category reveals distinct hardware specifications, customer acquisition costs, and regulatory exposure that reshape competitive positioning.
Service Type:
Regulatory frameworks differentiate service models through data retention mandates and hardware certification tiers, with SAMR's IoT security requirements imposing stricter audit trails on connected locking systems.
- Rental:Per-use access through station-based or free-floating distribution with RFID-enabled locks. Demand concentrates in Shanghai's metro-adjacent corridors where transit authority pilots create captive commuter pools. SAMR certification requirements for connected hardware filter out uncertified operators.
- Subscription:Recurring access bundled with transit passes or corporate mobility programs. Osaka and Singapore municipal procurement teams negotiate multi-year exclusive deployment rights tied to integrated payment platforms. Subscription bundling is displacing per-use rental as the dominant monetization model in East Asian urban cores.
- Ownership:Direct purchase with optional maintenance or replacement services. Compact folding umbrellas priced below annual subscription fees limit addressable market expansion in price-sensitive consumer segments.
- On-Demand:Immediate delivery or pickup through mobile-coordinated logistics. Dense urban cores in Tokyo and Seoul capture premium margin pools through sub-3-second Bluetooth Low Energy unlock latency.
Rental handles the majority of throughput; subscription is expanding most quickly on share.
Application:
Deployment context dictates hardware durability specifications and station density economics, with urban transit corridors requiring wind-rated canopies and event applications prioritizing rapid deployment logistics.
- Urban Use:Station-based networks in high-transit-density corridors with fiberglass-reinforced nylon canopies rated to 50 km/h wind speeds. Shanghai's expansion to 47 additional metro stations creates concentrated demand pools for commuter protection services.
- Outdoor Events:Temporary deployment for festivals, sports venues, and public gatherings with modular station configurations. Event organizers in Seoul and Tokyo drive seasonal volume spikes requiring rapid inventory repositioning.
- Business Services:Corporate campus networks and technology park deployments with enterprise-grade umbrella-as-a-service contracts. Deloitte anchors multi-year agreements offering contract stability absent in consumer markets.
- Emergency Kits:Government and NGO procurement for disaster preparedness stockpiles with extended shelf-life requirements. China's GB standards for durable goods sharing mandate material traceability for fiberglass and nylon components in public safety applications.
Urban Use generates the highest station density; Business Services delivers the steepest margin expansion trajectory.
Distribution Channel:
Channel selection determines customer acquisition economics and integration complexity with legacy transit authority IT systems, with direct municipal contracts requiring custom API development.
- Online:Mobile application-based booking and payment with cloud inventory synchronization. Cloud-based tracking systems face integration complexity with legacy transit authority IT infrastructure requiring custom API development.
- Retail:Physical pickup points in convenience stores and transit retail spaces. Partnerships with station-based retail networks in East Asia create touchpoint density for spontaneous rental conversion.
- Partnerships:Exclusive deployment rights negotiated with municipal transit agencies and corporate campus operators. Reed Talent Solutions leverages ISO 9001 compliance infrastructure to sustain deployment contracts with transit authorities.
- Direct Sales:Enterprise procurement teams for corporate and government accounts with customized service level agreements. Clarity Umbrella competes through specialized insurance-backed liability frameworks that reduce operator risk exposure in B2B contracts.
Partnerships lock in the largest contract value; Online is gaining share fastest through mobile-first consumer adoption.
Customer Type:
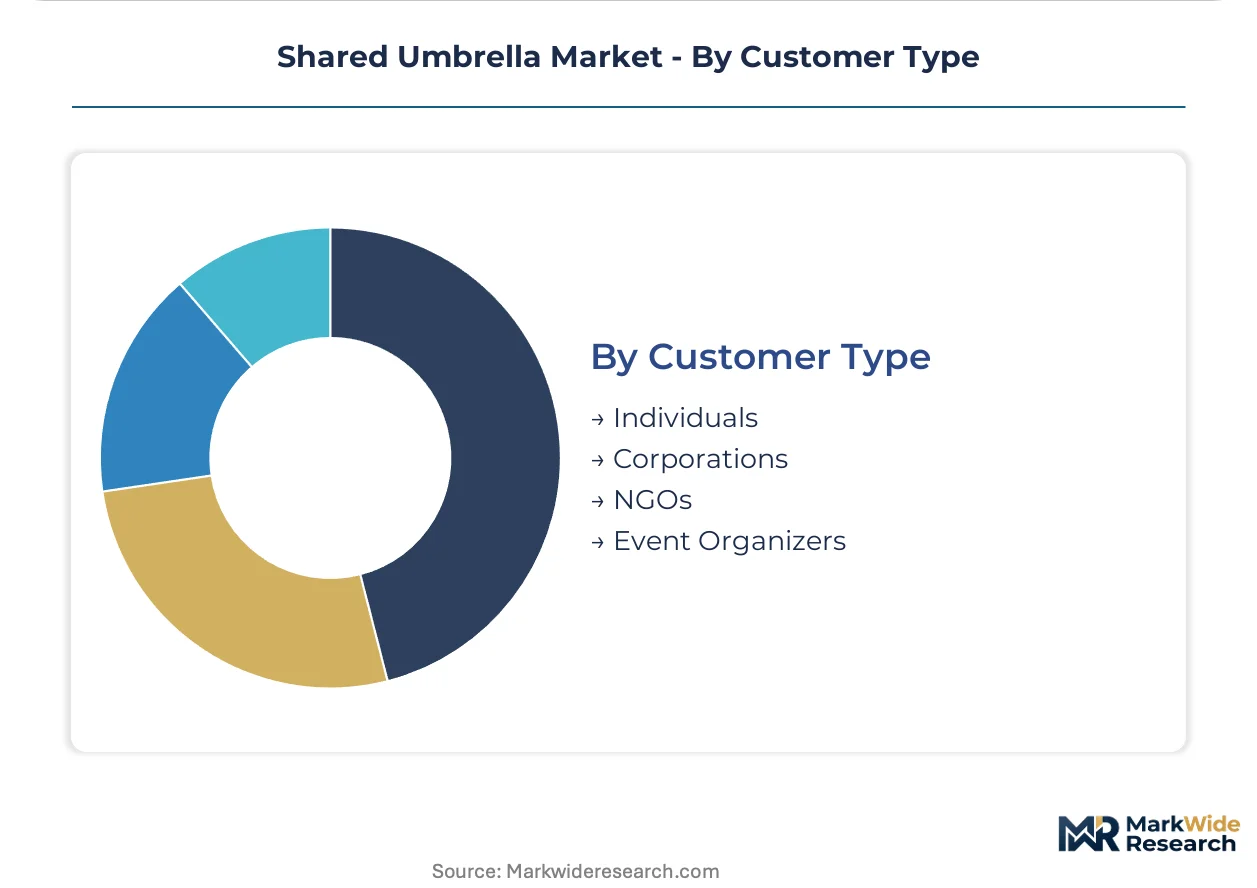
Customer category shapes liability exposure and contract duration, with corporate accounts demanding specialized coverage products and individual users driving transactional frequency metrics.
- Individuals:Spontaneous rental or subscription adoption through mobile applications. Individual users drive network density metrics and transactional frequency in consumer-facing deployments.
- Corporations:Enterprise umbrella-as-a-service programs for technology parks and business districts with multi-year contract stability. Corporate procurement teams prioritize operators with ISO 9001 quality management certification and insurance-backed liability frameworks.
- NGOs:Non-governmental organization procurement for community resilience and disaster preparedness programs. NGOs in East Asian coastal urban clusters prioritize wind-rated hardware specifications for climate adaptation initiatives.
- Event Organizers:Temporary deployment contracts for festivals, conferences, and public gatherings with flexible return logistics. Event organizers in Tokyo and Osaka drive seasonal demand concentration requiring rapid inventory scaling.
Corporations anchor the most stable revenue base; Event Organizers show the most volatile but highest peak-volume potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement teams at municipal transit authorities and corporate campus operators concentrate demand across East Asian urban cores. Certification requirements and payment interoperability mandates reshape vendor selection criteria. Station-based deployment economics favor dense metropolitan corridors with high commuter throughput.
China
Shanghai's metro authority expansion to 47 additional stations creates concentrated demand pools for commuter protection services. SAMR enforces IoT security audit trails and data privacy standards for connected locking mechanisms. Yangtze River Delta manufacturing clusters supply fiberglass-reinforced nylon canopies with material traceability documentation under tightening GB standards.
Japan
Tokyo station-based operators adopt Bluetooth Low Energy smart locks with sub-3-second unlock latency for commuter convenience. METI guidelines for sharing economy hardware durability influence procurement specifications. Kansai corridor deployment in Osaka shows subscription bundling with transit passes displacing per-use rental models.
South Korea
Seoul's dense urban core captures premium margin pools through mesh-networked smart lock systems with rapid inventory repositioning. MFDS-equivalent consumer safety frameworks govern electrical component compliance for outdoor deployment. Busan-Ulsan coastal clusters prioritize wind-rated canopy specifications for climate resilience.
Singapore
Municipal procurement teams negotiate multi-year exclusive deployment rights tied to integrated mobility platforms. The country's national standards body aligns with regional IoT security frameworks for connected sharing equipment. Downtown core station density supports fixed-station network economics absent in lower-density markets.
United Kingdom
London transit retail partnerships create touchpoint density for spontaneous rental conversion in high-footfall corridors. CE marking and RoHS directives extend hardware validation timelines for electrical component certification. Southeast England corporate campus networks drive enterprise umbrella-as-a-service contract demand with multi-year stability requirements.
Shared Umbrella Market Competitive Landscape
Player mix skews toward compliance-anchored service providers and transit-integrated operators. Market structure shows moderate concentration around ISO 9001-certified entities with established municipal relationships. Two strategic archetypes dominate: vertically integrated hardware-service bundlers and specialized compliance infrastructure firms. Competitive moves center on exclusive procurement negotiations with transit authorities and insurance-backed liability framework development.
Among compliance-focused service providers, Reed Talent Solutions and Clarity Umbrella exemplify divergent positioning strategies. Reed Talent Solutions occupies a position anchored in quality management certification infrastructure for sustaining municipal deployment contracts. Clarity Umbrella represents the liability-reduction archetype through specialized insurance frameworks targeting B2B contract scale. Deloitte sits within the enterprise-grade service tier, anchoring umbrella-as-a-service programs for corporate campus networks with multi-year agreement structures.
| Leading Market Players |
|---|
| Workwell Contractor Solutions |
| Reed Talent Solutions |
| Clarity Umbrella |
| Deloitte |
| Penningtons Law |
| Smartwork |
| Azets |
| IT Contracting |
| Worksome |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month hardware recertification cycles under China's tightening GB standards compress operator margins while elevating procurement preference for vertically integrated producers with captive polymer sourcing. This lead-time compression rewards certified assemblers with documented supply chain provenance, filtering price-sensitive uncertified entrants from municipal transit contracts.
Pricing Analysis
Cost-plus contracts with fiberglass and nylon indexation dominate B2B procurement between station-based operators and municipal transit authorities. Pricing stratifies across ISO 9001-certified premium tiers, SAMR-compliant standard tiers, and uncertified economy tiers with limited contract access. Cost compression in the economy tier intensifies because compact folding umbrella substitutes cap consumer willingness-to-pay. Corporate campus networks show lowest price sensitivity due to multi-year contract stability requirements; individual commuters exhibit highest sensitivity where per-use fees approach annual subscription thresholds.
Supply Chain Analysis
China and South Korea anchor smart lock module production with concentrated lithium-ion cell manufacturing for Bluetooth-enabled locking systems. Fiberglass-reinforced nylon canopies draw from Yangtze River Delta polymer clusters and Busan-Ulsan coastal textile networks. Single-source vulnerability in East Asian battery cell supply exposes operators to input volatility during logistics disruptions. Distribution runs through station-based retail partnerships in metro-adjacent corridors and direct municipal procurement channels requiring custom API integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where transit payment interoperability mandates are consolidating vendor relationships around integrated mobility providers. Municipal procurement teams in Shanghai, Osaka, and Singapore are negotiating exclusive deployment rights tied to unified payment platform access.
For Market Incumbents: Secure exclusive procurement negotiations with expanding metro authority pilots before interoperability mandates lock in competitor relationships. Deepen backward integration into fiberglass and nylon polymer sourcing to sustain margin position under GB material traceability requirements. ISO 9001 certification infrastructure represents the critical defensive lever against uncertified price competitors. For New Entrants and Emerging Players: Anchor in corporate campus networks and technology park deployments where multi-year contract stability exceeds consumer market volatility. Enterprise umbrella-as-a-service programs in Southeast England and Kansai corridor show lowest incumbent saturation. Lead with insurance-backed liability frameworks to differentiate from established transit-integrated operators. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because regulatory certification tiers are hardening into permanent market segmentation mechanisms. Target vertically integrated hardware-service bundlers with in-house polymer sourcing and documented GB audit trails. The signal to watch is municipal procurement team consolidation around integrated mobility platform vendors with exclusive deployment rights.| Strategic Initiative | Industry Significance |
|---|---|
| Transit Payment Interoperability | Municipal mandates for unified mobility platforms create first-mover lock-in advantages for certified operators. |
| Backward Integration into Polymer Sourcing | In-house fiberglass and nylon supply secures margin protection under tightening GB material traceability requirements. |
| Insurance-Backed Liability Framework | Specialized coverage products unlock B2B contract scale with corporate campus procurement teams. |
| Bluetooth Low Energy Smart Lock Deployment | Sub-3-second unlock latency in Tokyo and Seoul captures premium commuter convenience margins. |
| Corporate Campus Network Expansion | Enterprise umbrella-as-a-service programs offer multi-year stability absent in transactional consumer markets. |
Research Methodology
A spread of perspectives from municipal transit procurement officers, station-based network operators, smart lock hardware engineers, and corporate facility managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SAMR regulatory filings, GB standards documentation, and transit authority pilot program disclosures. Bottom-up deployment volume estimates triangulated against top-down addressable commuter population calculations across the analysis window.
Segmentation dimensions modeled include service type, deployment context, distribution channel, and customer category throughout the forecast period. CAGRs derived from deployment trajectory analysis incorporating hardware replacement cycles, station density economics, and subscription conversion rates. Forecast inputs weighted metro-adjacent corridor expansion timelines and IoT security mandate compliance timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained transit ridership density and continued GB standards tightening; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in municipal procurement patterns and hardware certification requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Rain Boots Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Bicycle Bags and Bag Packs Market