
 Camping Equipment Market | 2026-2036
Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Equipment Market Intelligence
Technical apparel engineering talent is rotating from military and aerospace sectors into outdoor equipment design, unlocking performance breakthroughs in weatherproofing and weight reduction. Johnson Outdoors leverages this influx through its vertically integrated R&D centers in Wisconsin. Exxel Outdoors anchors its competitive position with manufacturing scale across multiple price tiers. Hilleberg the Tentmaker dominates the expedition-grade segment with proprietary pole architecture and European sourcing.
Camping equipment encompasses portable shelter systems, sleep systems, cooking apparatus, and load-bearing gear engineered from technical textiles and lightweight alloys for temporary outdoor habitation. Nylon ripstop fabrics with silicone elastomer coatings achieve hydrostatic resistance exceeding 3000 mm while maintaining packability below two liters for two-person shelters. Tents command the largest revenue pool among product types due to replacement cycles tied to UV degradation and seam tape failure. Backpacks represent the fastest-growing category as day-hiking participation expands among urban demographics seeking load-carrying ergonomics. The casual camper end-user segment remains the most mature demand pool with price sensitivity driving private-label penetration.
FDA oversight of flame-retardant treatments in tent fabrics and EPA scrutiny of perfluorinated water repellents are tightening chemical compliance burdens for US manufacturers. The EU REACH regulation and F-Gas Regulation constrain insulation technologies in sleeping systems sold across European channels. Stakeholders must monitor pending restrictions on durable water repellent chemistries while positioning supply chains for biomaterial transitions.
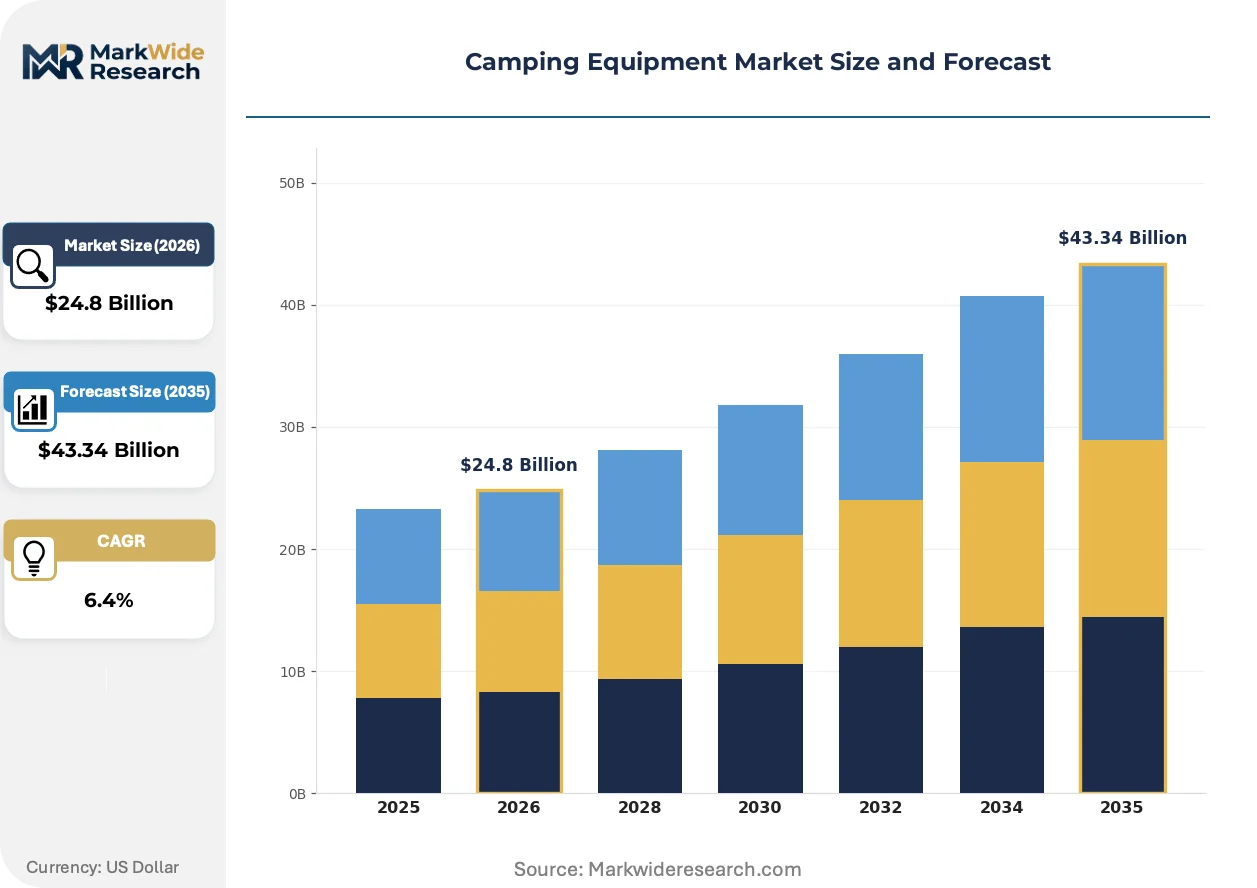
Market Dynamics
The EU Green Deal's product durability mandates are compressing replacement cycles and forcing material transitions across portable shelter and sleep system supply chains.
Growth Catalysts
- Alpine tourism infrastructure:Germany's rental-to-own retail models accelerate equipment turnover among backcountry explorers seeking technical gear without upfront capital commitment.
- REACH chemical compliance:European manufacturers pivoting from perfluorinated water repellents to bio-based alternatives capture premium positioning in expedition-grade segments.
- Silicone elastomer coatings:Nylon ripstop fabrics achieving hydrostatic resistance above 3000 mm enable ultralight shelter designs that expand day-hiking participation among urban demographics.
Market Restraints
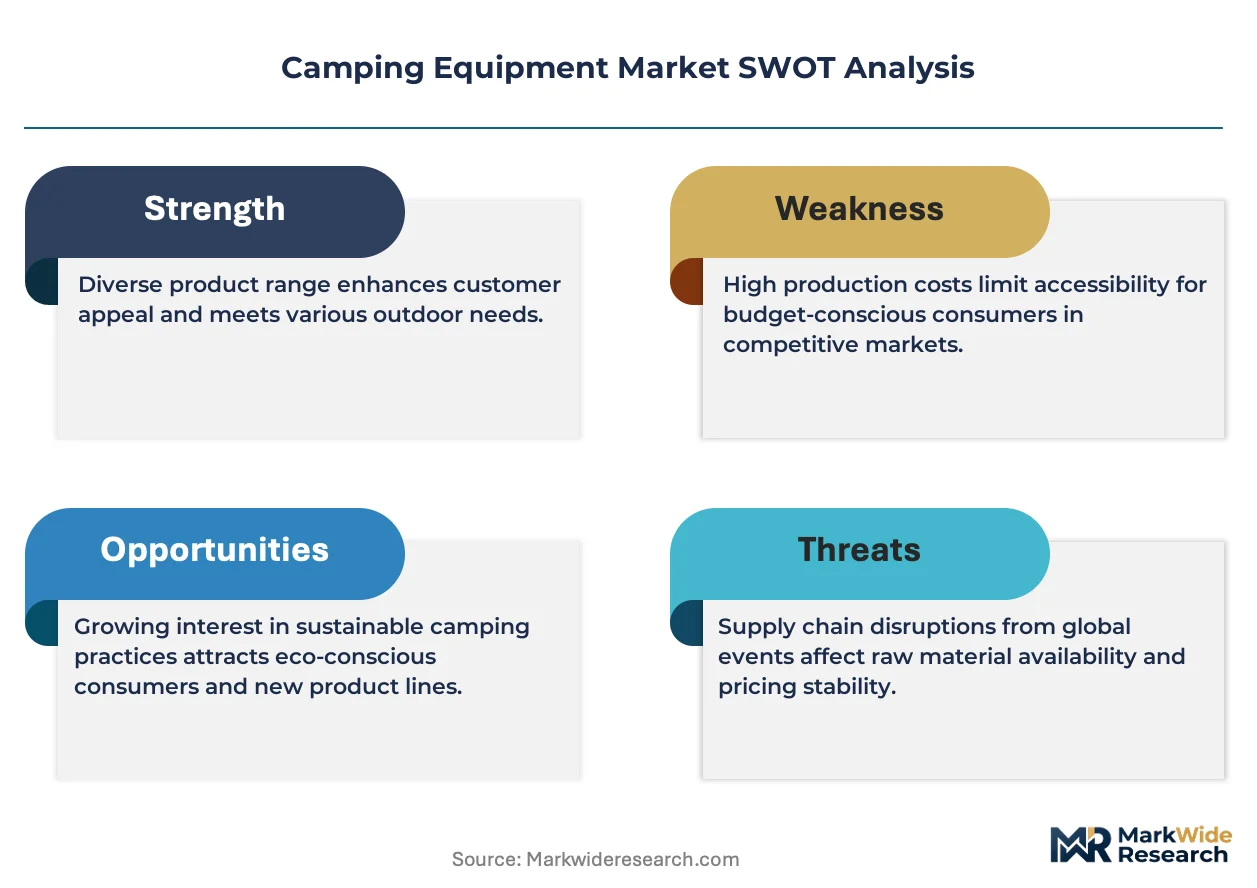
- Petrochemical feedstock volatility:Technical textile production faces margin compression from nylon and polyester price swings tied to crude oil benchmarks.
- East Asian manufacturing concentration:Pole architecture and alloy component sourcing clusters in Zhejiang and Guangdong provinces expose brands to geopolitical shipping disruptions.
- Seam tape thermal limitations:Current adhesive technologies fail below -40°C, constraining expedition-grade tent deployment in high-altitude polar environments.
Strategic Opportunities
- Nordic circular economy pilots:Norway's extended producer responsibility schemes for outdoor equipment create closed-loop material recovery infrastructure.
- Aerospace textile convergence:Carbon fiber weaving techniques from satellite deployable structures transfer to ultralight backpack frame manufacturing.
- Direct-to-consumer refurbishment channels:Digital platforms enabling peer-to-peer resale of sleep systems address price sensitivity in casual camper segments.
Industry Challenges
- Flame-retardant chemist scarcity:FDA-compliant tent fabric treatment expertise concentrates among legacy US textile mills with limited training pipeline capacity.
- Multi-standard certification timelines:Simultaneous EPA, REACH, and F-Gas Regulation testing extends product launch windows by 8-14 months.
- Legacy ERP integration:Biomaterial traceability requirements strain inventory systems designed for petrochemical supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Equipment Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Portable Stoves, Backpacks End User: Families, Solo Adventurers, Backcountry Explorers, Casual Campers Material: Nylon, Polyester, Aluminum, Fiberglass Application: Hiking, Backpacking, Car Camping, Survival |
| Companies Covered | Johnson Outdoors Inc., Newell Brands, Big Agnes, Inc., Oase Outdoors ApS, Nemo Equipment, Inc., Exxel Outdoors, LLC, AMG Group Ltd., Dometic Group AB, Hilleberg the Tentmaker, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Equipment Market Strategic Shifts & Innovations
Bio-based material substitution and regulatory chemistry bans are rewiring competitive advantage away from scale economies toward formulation agility and vertical R&D control.
Silicone-PU hybrid coatings are miniaturizing. These elastomer films deliver hydrostatic resistance comparable to traditional laminates at 40% reduced weight. Backcountry explorers and thru-hikers are adopting silicone-treated shelters at accelerating rates. The technology is miniaturizing pack volumes below one liter for single-person shelters, compressing the performance gap between ultralight and expedition-grade categories.
REACH restrictions on durable water repellents are tightening. ECHA's 2023 proposal to limit PFAS in textiles forces sleeping bag shell manufacturers toward paraffin and bio-wax alternatives. European channels face the steepest compliance burden, with German retailers demanding third-party certification for all DWR chemistries ahead of mandate deadlines.
Rental-to-own subscription models are fragmenting equipment ownership patterns. Urban millennials in Berlin and Munich increasingly access technical gear through monthly plans rather than purchase. Alpine tourism operators capture recurring revenue while manufacturers gain usage data that informs durability engineering priorities.
Camping Equipment Market Segmentation
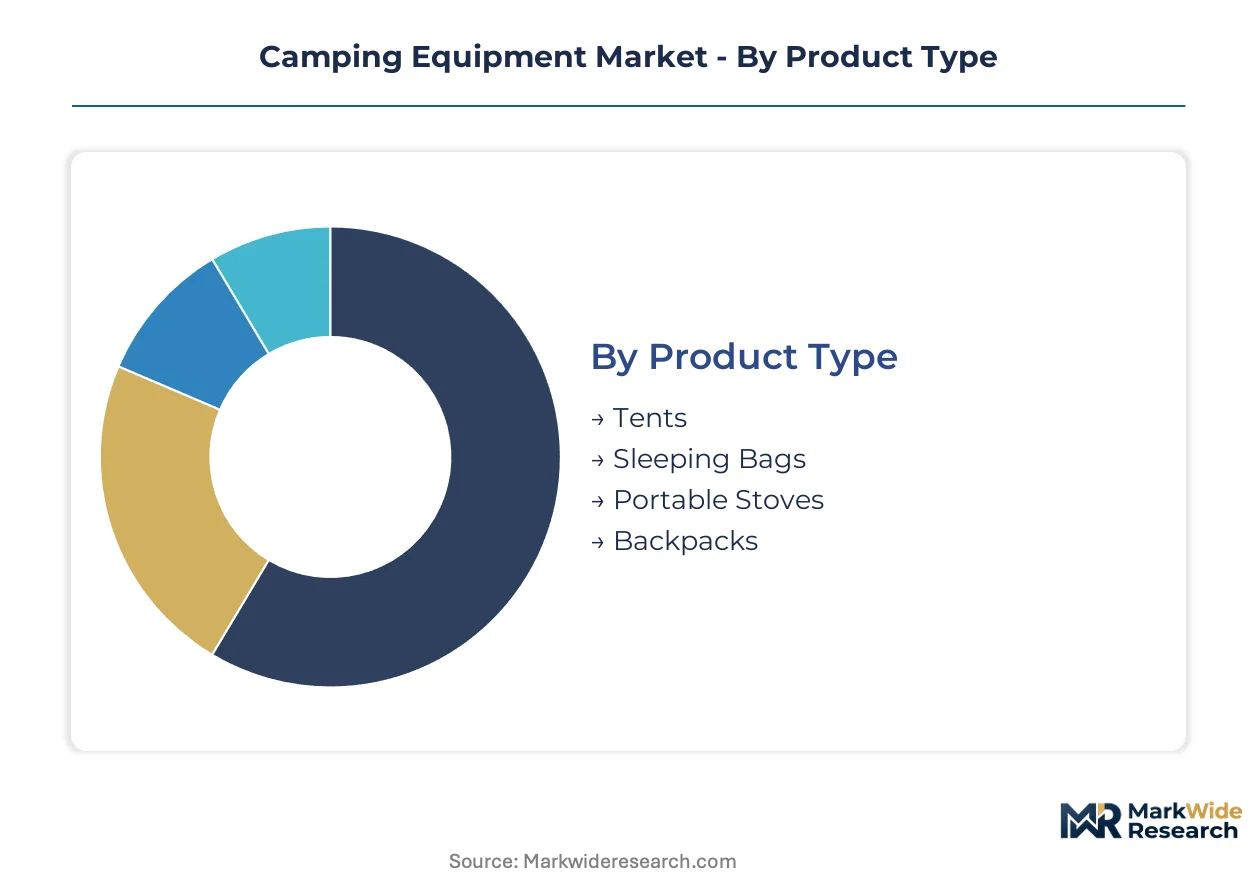
Segmentation in camping equipment reveals how technical specifications, user sophistication, and material chemistry create distinct margin architectures. Equipment manufacturers calibrate R&D investment and distribution channels differently across these boundaries.
Product Type:
Margin pools concentrate in shelter systems where UV degradation and seam failure drive predictable replacement cycles.
- Tents:Portable shelter systems engineered from silicone-coated nylon ripstop with hydrostatic resistance exceeding 3000 mm. Demand concentrates among backcountry explorers in Germany where alpine tourism infrastructure and rental-to-own models accelerate turnover. Replacement cycles tie directly to UV degradation and seam tape failure.
- Backpacks:Load-bearing systems with aerospace-derived frame architectures and ergonomic load distribution. Urban demographics in Berlin and Munich seeking day-hiking participation drive fastest expansion. Ergonomic engineering and weight reduction command premium positioning.
- Sleeping Bags:Insulated sleep systems with down or synthetic fill and DWR-treated shells. REACH and F-Gas Regulation compliance burdens reshape European sourcing strategies.
- Portable Stoves:Combustion and canister-based cooking apparatus for field meal preparation. Compact designs for ultralight backpacking segments attract technical user investment.
The dominant share belongs to Tents, while Backpacks is closing the gap fastest.
End User:
Application intensity and technical knowledge separate casual participants from gear-intensive specialists.
- Backcountry Explorers:Technical users demanding expedition-grade specifications including -40°C operational thresholds and sub-kilogram shelter weights. Germany's rental-to-own retail models reduce capital barriers for this fastest-expanding segment.
- Casual Campers:Price-sensitive participants prioritizing accessibility over performance specifications. Private-label penetration concentrates here as entry-level nylon and fiberglass constructions satisfy intermittent use patterns.
- Families:Multi-person equipment purchasers requiring durability and simplicity over technical optimization. Car-accessible camping applications dominate this pool.
- Solo Adventurers:Individual users balancing weight minimization with self-sufficiency requirements. Ultralight product configurations attract disproportionate engagement.
Backcountry Explorers capture the steepest expansion trajectory, though Casual Campers retain volume concentration.
Material:
Petrochemical feedstock volatility and regulatory chemistry bans are compressing traditional material margins while opening bio-based alternatives.
- Nylon:Polyamide fibers with ripstop weaves and silicone elastomer coatings achieving packability below two liters for two-person shelters. EU Green Deal durability mandates and REACH restrictions on fluorinated chemistries force reformulation investments.
- Polyester:PET-based textiles with lower moisture absorption than nylon alternatives. Cost positioning and recycled content integration attract sustainability-focused channel placement.
- Aluminum:Lightweight alloys for tent pole architecture and cookware construction. Zhejiang and Guangdong manufacturing clusters concentrate supply with geopolitical exposure.
- Fiberglass:Composite pole materials for entry-level shelter segments. Cost advantages trade off against weight penalties and brittleness in cold conditions.
Nylon commands the premium tier, while bio-based alternatives are gaining regulatory tailwinds fastest.
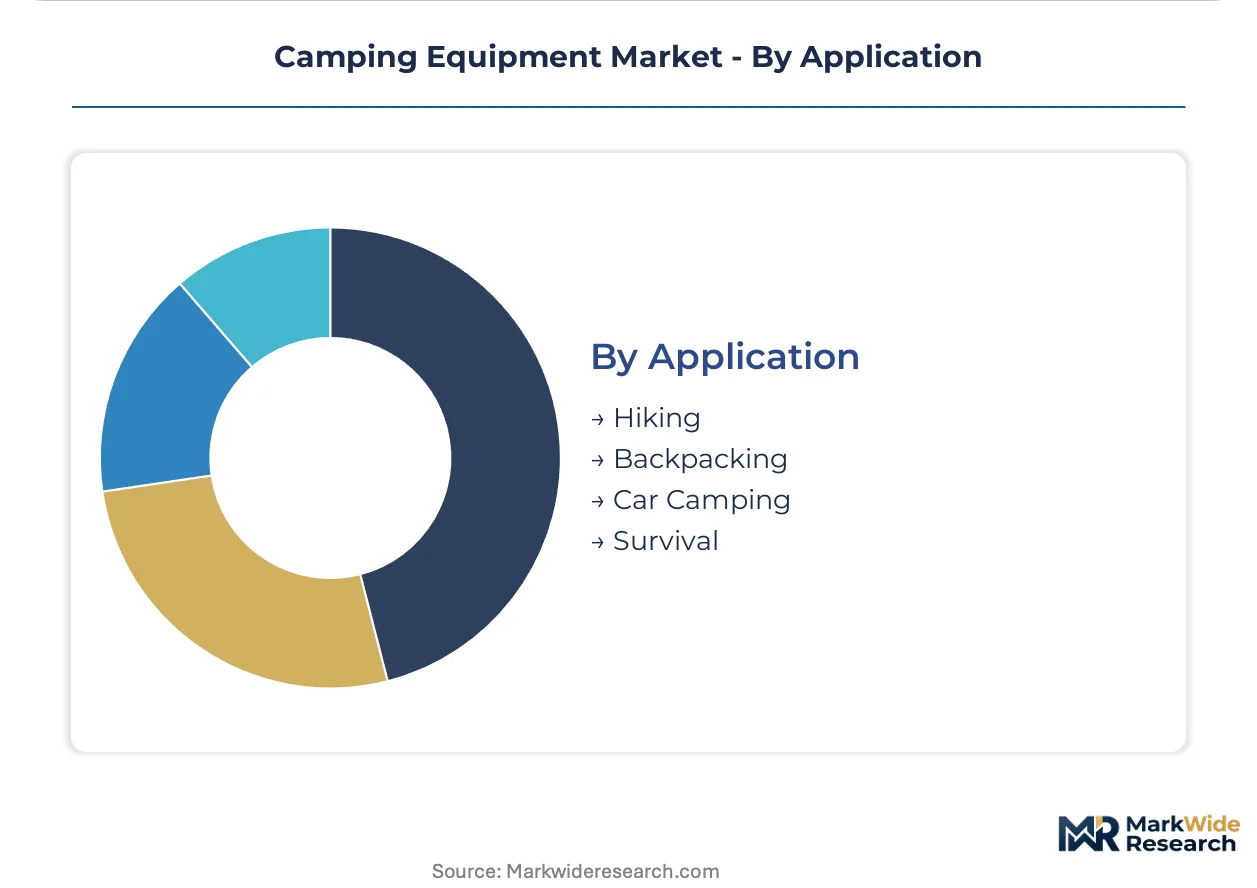
Application:
Mobility requirements and environmental exposure severity determine equipment specification thresholds.
- Backpacking:Multi-day foot-borne travel demanding sub-kilogram shelter systems and ergonomic load distribution. Thru-hiker adoption of silicone-treated shelters miniaturizes pack volumes below one liter for single-person configurations.
- Hiking:Day-trip mobility with reduced overnight requirements. Urban millennial participation in Berlin and Munich expands demand for technical daypacks and minimal shelter options.
- Car Camping:Vehicle-accessible overnight stays with relaxed weight constraints. Family-oriented equipment specifications prioritize interior space and durability over packability.
- Survival:Emergency preparedness and extended self-sufficiency scenarios. Specialized retailers serve this niche with military-aerospace technical heritage products.
Backpacking anchors technical innovation investment, while Hiking shows the most rapid participation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany's alpine corridor while margin compression hits East Asian manufacturing clusters exposed to petrochemical volatility. The EU Green Deal's durability mandates reshape sourcing economics across European channels. Alpine tourism infrastructure investments in Bavaria and Tyrol accelerate equipment turnover through rental-to-own retail models.
Germany
Alpine tourism operators in Bavaria and Baden-Württemberg deploy rental-to-own subscription models that reduce capital barriers for backcountry explorers. The EU Green Deal's product durability mandates force reformulation of silicone-coated shelter systems. Manufacturing clusters around Munich and Stuttgart concentrate technical textile engineering talent rotating from aerospace sectors.
United States
Day-hiking participation expands among urban demographics in Denver and Seattle seeking ergonomic load-bearing systems. FDA oversight of flame-retardant tent fabric treatments tightens compliance burdens for domestic manufacturers. Wisconsin hosts vertically integrated R&D centers drawing military textile engineering expertise into outdoor equipment design.
China
Zhejiang and Guangdong provinces cluster pole architecture and alloy component sourcing for global brands. The country's national standards regulator enforces dual carbon goals that constrain petrochemical feedstock availability for technical textile production. Manufacturing concentration in Ningbo and Dongguan exposes supply chains to geopolitical shipping disruptions.
France
Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur anchor expedition-grade demand from technical mountaineering communities. ANSM and CNIL oversight of chemical safety intersects with ECHA REACH restrictions on perfluorinated water repellents. Lyon-based textile mills pivot toward bio-wax DWR alternatives ahead of mandate deadlines.
Sweden
Nordic circular economy pilots in Stockholm and Gothenburg create closed-loop material recovery infrastructure for outdoor equipment. Extended producer responsibility schemes mandate take-back programs for sleep systems and shelters. Engineering clusters around the Mälaren Valley specialize in ultralight frame architecture for backpacking segments.
Camping Equipment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the camping equipment market. Premium-tier specialists command expedition-grade segments through proprietary pole architecture and European sourcing, while scale-oriented manufacturers anchor mid-market positioning across multiple price tiers. The competitive landscape stratifies into three archetypes: vertically integrated R&D houses, manufacturing-scale diversified portfolios, and niche expedition-grade ateliers. Dominant competitive moves include strategic partnerships with alpine tourism operators and portfolio diversification into rental-to-own service channels.
Among North American outdoor equipment fabricators, Johnson Outdoors Inc. and Exxel Outdoors, LLC occupy positions on opposing vectors of the technology-cost spectrum. Johnson Outdoors exemplifies the vertically integrated R&D archetype through its Wisconsin-based technical centers. Exxel Outdoors represents manufacturing-scale diversification across price tiers. Hilleberg the Tentmaker, Inc. anchors the expedition-grade specialist tier with European sourcing heritage. These three players collectively illustrate how competitive advantage fragments across technical specialization, production scale, and niche premium positioning.
| Leading Market Players |
|---|
| Johnson Outdoors Inc. |
| Newell Brands |
| Big Agnes, Inc. |
| Oase Outdoors ApS |
| Nemo Equipment, Inc. |
| Exxel Outdoors, LLC |
| AMG Group Ltd. |
| Dometic Group AB |
| Hilleberg the Tentmaker, Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for silicone-coated nylon ripstop concentrate pricing power with vertically integrated manufacturers controlling both polymer sourcing and coating application. This lead-time band exposes mid-tier brands to margin compression when petrochemical feedstock volatility intersects with REACH-mandated chemistry transitions.
Pricing Analysis
Configured-to-order expedition-grade shelters command 40-60% premiums over standard SKUs, reflecting customization for hydrostatic resistance thresholds and pole architecture specifications. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in entry-level tiers intensifies because private-label penetration concentrates among casual campers. Backcountry explorers exhibit lowest price sensitivity, prioritizing weight-to-performance ratios over acquisition cost.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo corridors elevates inbound logistics costs for alloy pole components and coated textile rolls destined for European assembly. Manufacturing gravity centers on China, Vietnam, and Germany, with Zhejiang province dominating tent pole architecture and Bavaria hosting technical textile finishing. Raw material dependencies rest on petrochemical-derived nylons, silicone elastomer coatings, and 7000-series aluminum alloys. Single-source vulnerability concentrates in Guangdong province for precision-extruded pole segments. Distribution runs through alpine tourism operators, specialty outdoor retailers, and direct-to-consumer refurbishment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rental-to-own subscription models generate recurring revenue streams expanding faster than hardware turnover, transforming equipment manufacturers into service-anchored platforms with usage-data monetization potential.
For Market Incumbents: Compound defensive positioning through backward integration into silicone-coating application and captive supply of aerospace-derived frame alloys. Threats from bio-based material startups and REACH-accelerated chemistry bans demand accelerated R&D in paraffin-DWR alternatives. Priority levers include certification investment for F-Gas-compliant sleeping systems and channel control through exclusive alpine tourism partnerships. For New Entrants and Emerging Players: Anchor in direct-to-consumer refurbishment channels addressing price sensitivity among urban millennial casual campers in Berlin and Munich. White-space targets include peer-to-peer resale platforms for sleep systems and subscription-based gear access. The most penetrable segment combines day-hiking participation with ergonomic load-bearing demand. Go-to-market execution should leverage digital-native community building around ultralight shelter configurations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming outdoor equipment divisions lacking vertical R&D integration. Long-term viability over the coming decade hinges on biomaterial transition readiness and circular economy infrastructure access. Acquisition archetypes prioritize European-sourced expedition-grade specialists with proprietary pole architecture. Monitor ECHA PFAS restriction implementation timelines as inflection indicator for chemistry-dependent margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Rental-to-Own Platform Launch | Alpine tourism operators in Bavaria capture recurring revenue while reducing capital barriers for technical users. |
| Backward Integration into Coating | In-house silicone-PU hybrid application secures supply continuity against REACH-mandated chemistry transitions. |
| Bio-Based DWR Certification | Third-party paraffin and bio-wax validation opens premium positioning in EU channels ahead of mandate deadlines. |
| Circular Economy Partnership | Nordic extended producer responsibility schemes create closed-loop material recovery infrastructure for sleep systems. |
| Aerospace Textile Licensing | Carbon fiber weaving techniques from satellite deployable structures transfer to ultralight backpack frame manufacturing. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade customs data, alpine tourism operator financial disclosures, and ECHA regulatory filings. Primary interviews engaged product development directors at vertically integrated manufacturers, procurement leads at specialty outdoor retailers, technical textile engineers rotating from aerospace sectors, and sustainability compliance officers navigating REACH transitions. Secondary validation drew from EU Green Deal implementation reports, petrochemical feedstock price benchmarks, and patent filings for silicone-PU hybrid coating technologies. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Segmentation dimensions modeled include product type, end-user sophistication tier, material chemistry family, and application mobility requirement across the analysis window. CAGRs derive from elasticity-adjusted demand projections tied to alpine tourism infrastructure investment and rental-to-own penetration curves. Industry-specific forecast inputs incorporate UV degradation-driven replacement cycle frequencies and seam tape thermal performance thresholds.
Underlying assumptions cover sustained EU Green Deal enforcement trajectory and petrochemical price band stability, with deviation risk concentrated in geopolitical shipping disruptions through East Asian manufacturing clusters and accelerated PFAS restriction timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
US Backpacks Market
Outdoor Gear
Rooftop Tent Market