
 Fairway Mowers Market | 2026-2036
Fairway Mowers Market Size, Share, and Industry Trends Forecast 2026-2036
Fairway Mowers Market Foresight
Modular attachment bundling is recalibrating how golf course superintendents configure fairway mower purchases. Deere & Company leverages its precision agriculture heritage to dominate sensor-integrated cutting decks. The Toro Company anchors its position through deep channel control across North American golf distributors. Kubota Corporation competes with diesel-electric hybrid architectures that extend runtime for large-scale sports turf operations.
Fairway mowers are self-propelled turf maintenance machines engineered to cut grass between 0.375 and 0.75 inches using reel or rotary blades mounted on floating heads that follow ground contours. These machines serve the primary commercial purpose of producing uniform, stripe-patterned playing surfaces on golf courses and athletic fields where ball roll consistency determines playability. Riding configurations command the largest installed base among product types due to operator efficiency on expansive fairway acreage, while electric power sources represent the fastest-expanding segment as battery energy density improves and total cost of ownership calculations shift. Municipalities as an end-user category sit at a mature growth trajectory with predictable replacement cycles, whereas robotic technology holds concentrated margin pools for early movers capable of autonomous navigation software.
EPA Phase IV emissions standards and the EU F-Gas Regulation shape engine and refrigerant specifications for gasoline and diesel units sold in the United States and European member states. California Air Resources Board zero-emission equipment mandates are accelerating electric platform development for equipment fleets operated by public agencies. Stakeholders must monitor battery supply chain localization requirements and charging infrastructure deployment timelines as procurement criteria evolve beyond cutting performance alone.
Market Dynamics
Fleet electrification mandates from California Air Resources Board and German municipal procurement rules are forcing powertrain architecture redesigns across fairway mower portfolios, compressing development timelines while opening margin pools for battery-integrated platform suppliers.
Growth Catalysts
- California zero-emission equipment mandates:Public agency procurement rules now require battery-electric or fuel-cell alternatives for turf maintenance fleets, redirecting capital toward charging infrastructure and platform development.
- Golf course superintendent demand for precision cutting:Tournament-ready turf standards are elevating sensor-integrated floating deck technology from premium option to baseline expectation across United States fairway operations.
- Battery energy density improvements:Lithium-ion cell chemistry advances are extending runtime per charge cycle, erasing the historical productivity penalty that constrained electric platform adoption on large-acreage courses.
Market Restraints
- Lithium supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing original equipment manufacturers to geopolitical friction and forced localization requirements.
- EPA Phase IV compliance costs:Diesel engine after-treatment systems for riding configurations now add substantial hardware expense without commensurate performance gain, narrowing the cost gap with electric alternatives.
- Autonomous navigation software limitations:Robotic fairway mowers still struggle with edge-detection reliability on undulating terrain, constraining deployment to flat practice areas rather than championship fairways.
Strategic Opportunities
- Modular attachment bundling:Superintendents increasingly configure reel cutting decks, rotary heads, and debris collection systems as integrated packages rather than standalone purchases, expanding average transaction value.
- German low-carbon procurement mandates:Municipalities in Bavaria and North Rhine-Westphalia now embed lifecycle carbon calculations into equipment tenders, favoring suppliers with verified battery supply chain transparency.
- Robotic-as-a-service models:Autonomous platform providers are piloting subscription-based deployment where course operators pay per acre maintained rather than capitalizing hardware, reducing adoption risk.
Industry Challenges
- Certified technician scarcity:High-voltage battery system maintenance requires specialized training that legacy small-engine repair networks lack, extending downtime and service costs for early electric adopters.
- Charging infrastructure lead times:Course electrical upgrades for fleet-scale fast-charging often face 12-18 month utility interconnection queues, delaying full electric conversion despite equipment availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fairway Mowers Market |
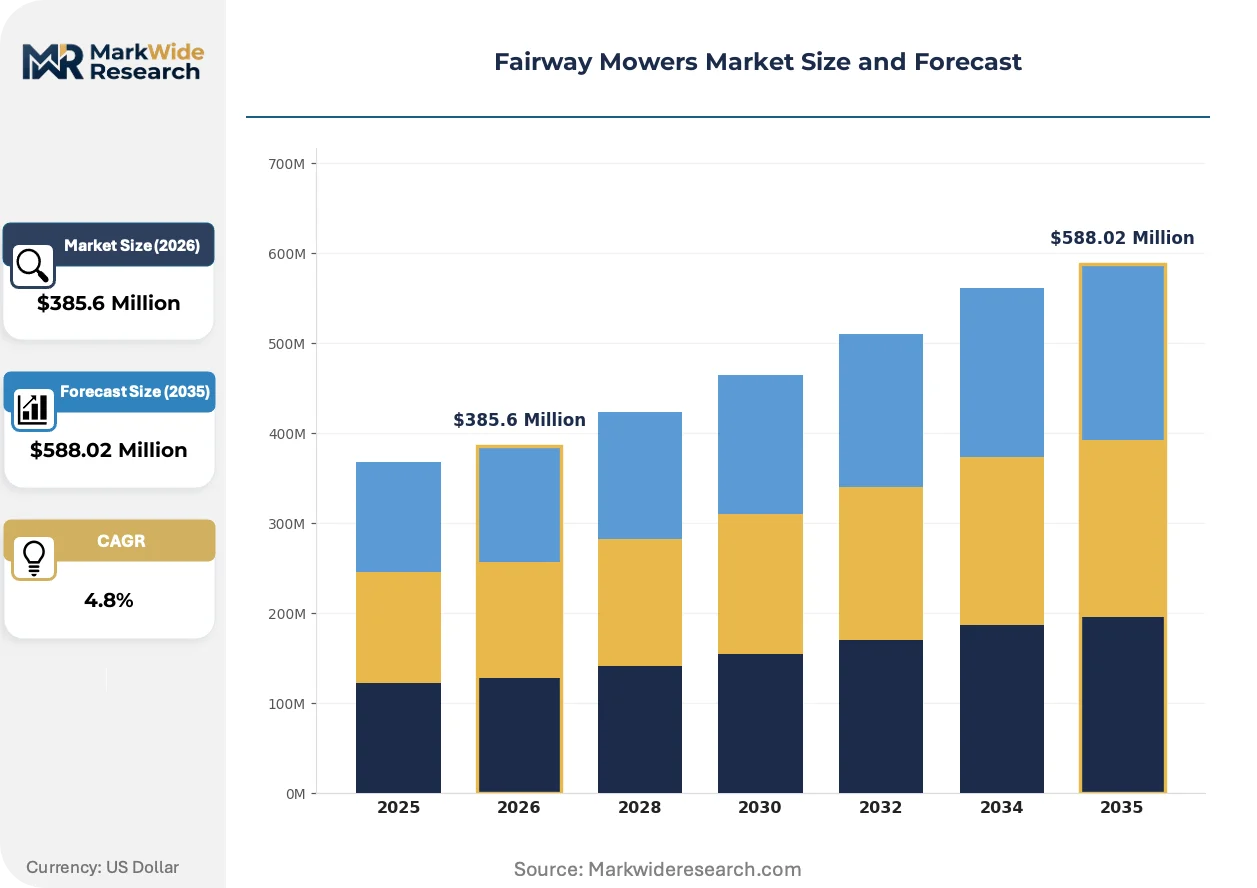
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Behind, Riding, Precision, Tri-Plex End User: Golf Courses, Sports Facilities, Residential Landscapers, Municipalities Power Source: Gasoline, Electric, Diesel, Hybrid Technology: Robotic, Conventional, Sensor-Based, Smart |
| Companies Covered | Deere & Company, The Toro Company, Jacobsen (Textron Specialized Vehicles), Kubota Corporation, Husqvarna Group, Ariens Company, Trimax Mowing Systems, Honda Motor, Kesmac Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fairway Mowers Market Shifts & Advancements
Powertrain architecture, regulatory compliance frameworks, and procurement contracting models are simultaneously transforming how fairway mower value chains capture margin and lock in customer relationships.
Reel cutting technology with integrated torque sensors and real-time blade-speed adjustment is consolidating market preference among premium course operators. United States golf superintendents now specify these systems as standard for tournament conditioning. The technology is compressing differentiation between mid-tier and premium equipment tiers by democratizing precision previously reserved for flagship models.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in diesel-powered riding mowers with cab climate control. Equipment manufacturers must redesign thermal management systems or eliminate enclosed cabs entirely. German and French municipal fleets face the tightest compliance deadlines and are pre-emptively specifying open-station configurations.
Lifecycle cost contracting is displacing upfront equipment purchases among budget-constrained municipal parks departments. California cities now structure five-year agreements bundling hardware, maintenance, and guaranteed uptime thresholds. This shift transfers operational risk to manufacturers while concentrating buyer power among state procurement consortia.
Fairway Mowers Market Segmentation
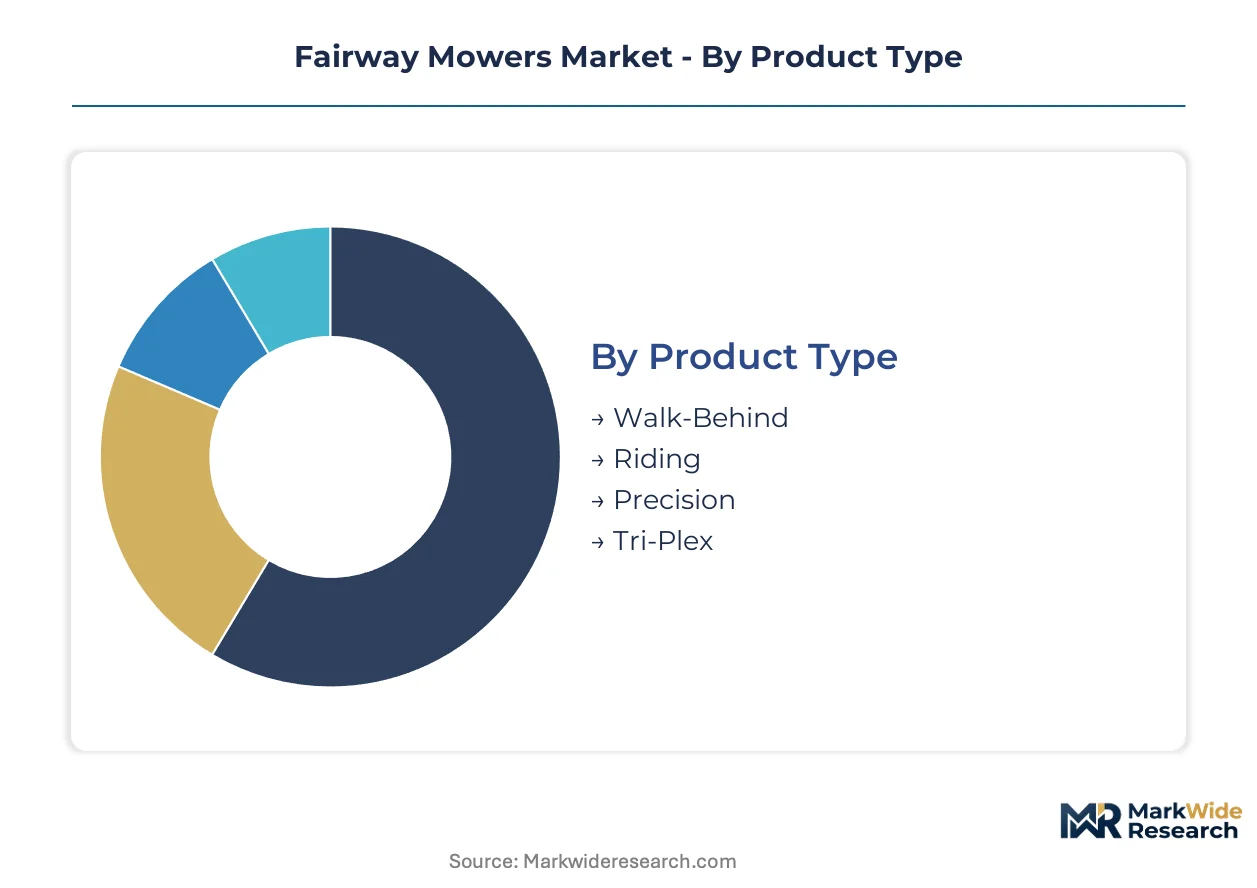
Fairway mower procurement splits sharply between high-volume fleet operators and precision-focused premium buyers. Superintendents configure equipment across four intersecting dimensions where powertrain choices now override traditional product type preferences in capital allocation decisions.
Product Type:
Riding configurations dominate fleet volume while walk-behind units command premium pricing on constrained-access terrain.
- Riding:Self-propelled units with operator stations cover expansive fairway acreage at speeds exceeding eight miles per hour. United States golf courses concentrate replacement demand here as tournament conditioning standards elevate cutting frequency requirements. EPA Phase IV compliance costs are compressing diesel engine margins and accelerating electric platform development.
- Walk-Behind:Manual-steered machines with floating reel heads navigate undulating terrain and hazard-adjacent strips where riding units risk turf damage. Residential landscapers in California and German municipalities favor these for steep-bank access under zero-emission procurement rules. Battery energy density improvements are erasing runtime penalties that previously constrained electric adoption.
- Precision:Sensor-integrated cutting decks with real-time blade-speed adjustment maintain consistent clip quality across variable grass density.
- Tri-Plex:Three-reel configurations mounted on articulated frames deliver striping patterns for tournament playability standards.
Mature deployment sits with Riding configurations across North American golf fleets. Newer deployment is concentrated in Walk-Behind electric conversions for municipal zero-emission mandates.
End User:
Application intensity separates daily-use commercial operators from seasonal maintenance providers.
- Golf Courses:Tournament-ready turf standards demand precision cutting technology with floating heads that follow ground contours between 0.375 and 0.75 inches. United States superintendents specify sensor-integrated decks as baseline equipment, eroding differentiation between mid-tier and premium manufacturers. Fleet replacement cycles compress where playability directly correlates with membership retention.
- Sports Facilities:Multi-field athletic complexes prioritize runtime efficiency and rapid turnaround between events. Diesel-electric hybrid architectures extend operational hours for large-scale turf operations without refueling interruptions. German and French municipal stadium operators face EU F-Gas Regulation deadlines for cab climate systems.
- Residential Landscapers:Seasonal demand patterns favor equipment versatility across property sizes and terrain types.
- Municipalities:Predictable replacement cycles and lifecycle cost contracting dominate procurement with five-year uptime guarantees transferring operational risk to manufacturers.
Volume concentration rests with Golf Courses across premium fairway installations. Margin expansion is climbing fastest in Municipalities through outcome-based service contracting.
Power Source:
Regulatory mandates are reordering powertrain economics faster than technology diffusion alone would predict.
- Electric:Lithium-ion battery platforms with fast-charging capability are gaining share where utility interconnection timelines permit infrastructure deployment. California Air Resources Board zero-emission mandates for public agency fleets redirect capital toward charging infrastructure and platform development. Battery supply chain localization requirements in Germany favor suppliers with verified cathode material transparency.
- Gasoline:Carbureted and fuel-injected small engines retain installed base in residential and light-commercial applications where runtime demands remain modest.
- Diesel:Compression-ignition engines with after-treatment systems face hardware cost inflation from EPA Phase IV compliance without commensurate performance gain.
- Hybrid:Diesel-electric architectures extend runtime for large-acreage operations while maintaining refueling flexibility during transition periods.
Installed base dominance remains with Diesel across legacy golf fleet holdings. Steepest expansion trajectory belongs to Electric as battery energy density improvements eliminate productivity penalties.
Technology:
Automation maturity separates proven navigation systems from experimental deployment.
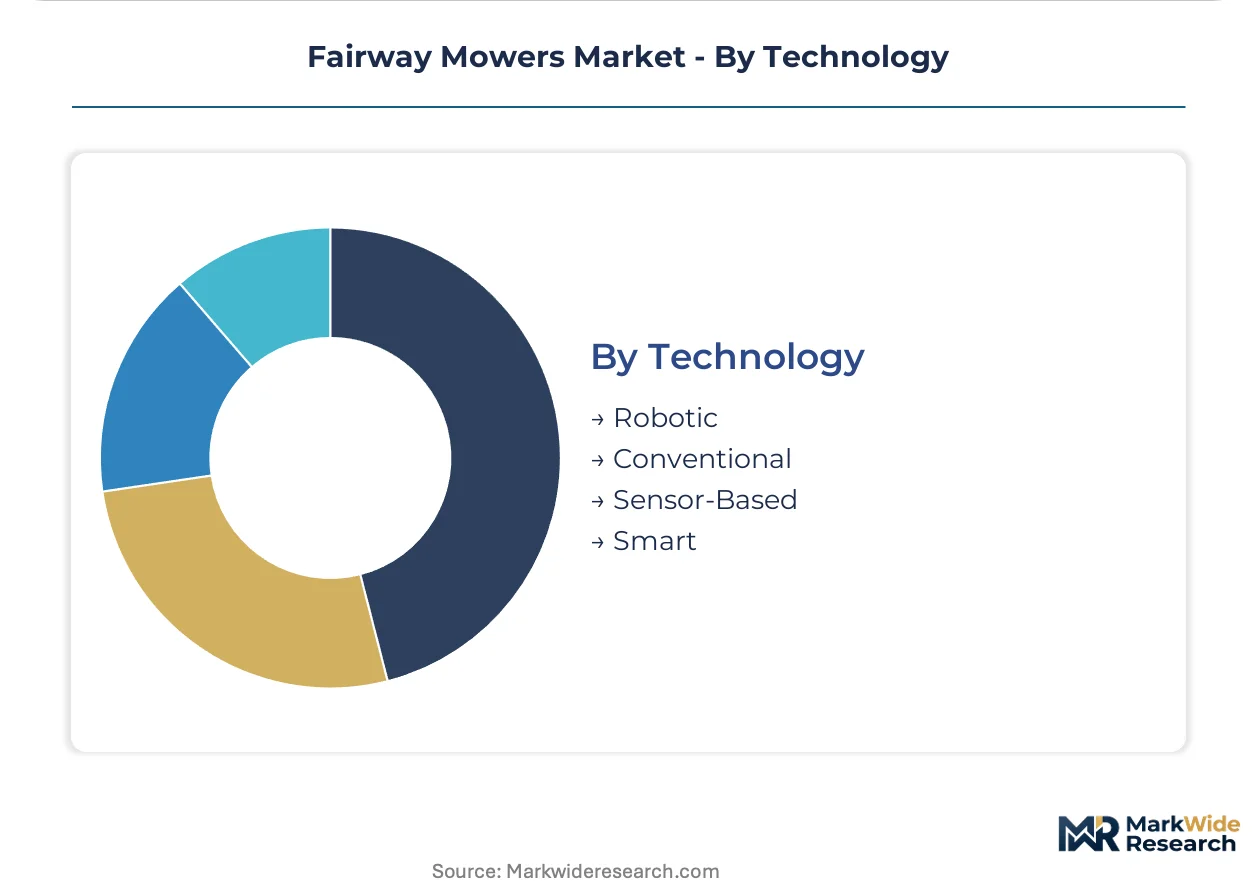
- Conventional:Operator-controlled steering and cutting deck engagement constitute the majority of installed machines across mature golf markets. Maintenance networks and technician training concentrate around these architectures, extending equipment lifecycles through rebuild programs.
- Sensor-Based:Torque sensors and real-time blade-speed adjustment democratize precision cutting technology from flagship to mid-tier equipment tiers. United States superintendents now specify these systems as standard for tournament conditioning.
- Robotic:Autonomous navigation platforms with GPS mapping and obstacle detection remain constrained to flat practice areas by edge-detection reliability limitations on undulating championship fairways.
- Smart:Connected equipment with telematics integration enables predictive maintenance and fleet optimization software.
Operational maturity concentrates in Conventional platforms with established service infrastructure. Technology investment is flowing fastest into Sensor-Based systems as precision becomes baseline rather than premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures precision cutting systems for export while the United States consumes the largest fleet volume. Japan supplies sensor-integrated components. China processes battery cathode materials. Australia imports premium riding configurations for golf tourism infrastructure.
United States
Superintendents at tournament venues demand sensor-integrated floating decks for stripe-patterned fairways. EPA Phase IV emissions standards compress diesel engine margins and redirect R&D budgets toward electric platforms. California cities face CARB zero-emission mandates that accelerate fleet conversion timelines across municipal parks departments.
Germany
Bavarian municipalities embed lifecycle carbon calculations into equipment tenders, favoring transparent battery supply chains. EU F-Gas Regulation phase-downs force refrigerant transitions in cab-equipped riding mowers. Stuttgart industrial clusters prototype diesel-electric hybrid architectures for extended runtime on large-scale sports turf operations.
Japan
Precision component fabricators supply torque sensors and real-time blade-speed adjustment modules to global OEMs. METI efficiency standards shape domestic equipment specifications. Osaka-Nagoya manufacturing corridors concentrate exports of compact electric powertrains for walk-behind configurations.
China
Cathode material processing and lithium-ion cell manufacturing clusters expose downstream OEMs to geopolitical friction. Dual carbon goals accelerate domestic battery supply chain localization requirements. Yangtze River Delta industrial zones supply cells to European and North American mower assemblers under forced partnership structures.
Australia
Gold Coast and Melbourne golf tourism corridors import premium riding configurations for championship course conditioning. National environmental regulations favor low-emission equipment procurement for public parklands. Sydney metropolitan councils pilot lifecycle cost contracting models that transfer operational risk to manufacturers.
Fairway Mowers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology vectors. Market structure shows moderate consolidation around precision agriculture heritage and deep channel control. Three archetypes dominate: diversified industrial conglomerates with agricultural equipment portfolios, turf-specialized manufacturers with dedicated golf distribution networks, and regional fabricators serving municipal procurement markets. Competitive moves concentrate on modular attachment bundling and battery platform partnerships.
Within the diversified conglomerate tier, Deere & Company and Kubota Corporation anchor positions through precision agriculture technology transfer and hybrid powertrain development. The Toro Company exemplifies the turf-specialist archetype with concentrated channel presence across North American golf distributors. These three occupy distinct strategic positions without direct product overlap in premium fairway installations.
| Leading Market Players |
|---|
| Deere & Company |
| The Toro Company |
| Jacobsen (Textron Specialized Vehicles) |
| Kubota Corporation |
| Husqvarna Group |
| Ariens Company |
| Trimax Mowing Systems |
| Honda Motor |
| Kesmac Inc. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators in Italy and Wisconsin anchor component supply for precision reel assemblies, concentrating pricing leverage among established tier-one OEMs while compressing margin capture for second-source challengers. Their multi-generational ownership structures resist private-equity rollup pressure, preserving disciplined capacity expansion that props pricing floors across premium fairway mower tiers.
Pricing Analysis
Margin tightening in mid-tier riding configurations reflects EPA Phase IV after-treatment hardware costs that add expense without performance gain. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated tournament-grade decks from basic floating-head units, with certification tier (CE marking for EU municipal fleets) and volume scale driving spreads. Cost compression accelerates in diesel-powered segments as electric alternatives narrow total-cost-of-ownership gaps. Municipal procurement officers exhibit highest price sensitivity through lifecycle cost contracting, while tournament-course superintendents prioritize cutting precision over unit economics.
Supply Chain Analysis
Lithium-ion cell supply rests on cathode material processing clusters in China, South Korea, and Japan that feed global mower assemblers. Precision cutting deck fabrication draws from hardened steel mills in Germany and Japan, while torque sensor modules source from Osaka-Nagoya manufacturing corridors. Single-source vulnerability concentrates in Chinese battery component processing where forced localization requirements and geopolitical friction threaten input security. Distribution runs through authorized dealer networks with factory-trained technician certification rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery cell capacity constraints in non-Chinese geographies prop pricing power for OEMs with secured supply agreements, creating a supply-constrained market structure that favors early movers in electric platform development.
For Market Incumbents: Lock in multi-year cathode supply agreements with South Korean and Japanese cell producers before localization mandates harden. Secure certified technician training capacity through community college partnerships to service electric fleet conversions, defending against emerging pure-play battery integrators threatening aftermarket revenue streams. For New Entrants and Emerging Players: Golf distributor networks in the southeastern United States represent the most penetrable channel opening, as incumbent exclusivity agreements lapse amid portfolio electrification transitions. Target municipal parks departments in California and Germany with subscription-based robotic-as-a-service models that bypass capital budget constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor sensor-integrated component specialists in Japan and Germany with captive OEM relationships and METI-funded efficiency programs. Watch battery supply chain localization legislation in the EU and US as the inflection signal for margin compression or expansion across electric platform portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from South Korean producers ahead of CARB mandate deadlines. |
| Certified Technician Program | Builds high-voltage maintenance capacity through partnerships with Wisconsin technical colleges. |
| Robotic-as-a-Service Pilot | Transfers autonomous mower adoption risk from municipal capital budgets to per-acre operational expenditure. |
| Sensor Module Acquisition | Captures torque feedback technology from Osaka fabricators for tournament-grade cutting deck integration. |
| Lifecycle Cost Contracting | Aligns manufacturer incentives with California municipal uptime guarantees across five-year service terms. |
Research Methodology
Document review covered EPA Phase IV compliance filings, EU F-Gas Regulation implementation guidance, and CARB zero-emission equipment procurement rules, complemented by interviews with golf course superintendents, municipal fleet managers, and turf equipment distributor principals. Secondary validation drew from SEC 10-K disclosures of diversified industrial conglomerates, customs data on lithium-ion cell trade flows, and German municipal tender databases. Bottom-up equipment shipment estimates triangulated against top-down replacement cycle modeling across the projection horizon.
Cross-referencing historical fleet turnover patterns with panel input from maintenance directors and OEM procurement teams anchored the analytical framework. Segmentation dimensions spanned product type, power source architecture, end-use intensity, and technology tier across the analysis window. CAGRs derived from equipment unit economics and battery cost curve trajectories, with charging infrastructure deployment timelines and utility interconnection queues as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration in additional US states beyond California and breakthrough autonomous navigation reliability that would unlock championship fairway deployment. Forecasts reflect documented assumptions about battery energy density improvement rates and cathode material price stability. A small set of named triggers warrants ongoing watch: EU battery passport implementation timelines, Chinese export restriction announcements, and municipal budget stress indicators affecting parks department capital allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
North America Robotic Lawn Mower Market