
 Nutritional Drink Market | 2026-2036
Nutritional Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Drink Market Insights
Geriatric care facilities is reorganizing demand away from traditional sports nutrition channels toward clinical and wellness-oriented nutritional beverages. Abbott Laboratories anchors the medical nutrition segment through hospital and long-term care partnerships. Danone specializes in pediatric and adult medical nutrition with science-backed formulations. Nestle dominates ready-to-drink meal replacements through extensive retail distribution networks.
Nutritional drinks are formulated beverages delivering macronutrients, micronutrients, and bioactive compounds in liquid form, typically containing 15-30 grams of protein per serving alongside vitamins, minerals, and fiber for targeted health outcomes. Protein Shake products command premium shelf positioning as fitness culture expands into mainstream consumer routines. Ready-to-Drink formats are capturing the fastest volume growth as convenience-seeking buyers shift from powder preparation to grab-and-go consumption. Meal Replacement applications retain the largest revenue pool among working professionals managing caloric intake.
The FDA monitors structure-function claims and Good Manufacturing Practice compliance for nutritional beverages sold in the United States. EFSA evaluates health claim substantiation across European markets, directly influencing permissible marketing language and reformulation requirements. China's NMPA and national food safety standards impose registration obligations on imported nutritional drinks. Stakeholders must track evolving protein fortification thresholds and front-of-pack labeling mandates to maintain formulation competitiveness and market access.
Market Dynamics
Geriatric care procurement is reorganizing supply chains around clinical-grade formulations as aging populations in China, Japan, and Germany shift consumption from retail wellness products to institutional medical nutrition channels.
Growth Catalysts
- EFSA protein claim substantiation:European regulators are tightening evidentiary standards for functional health claims, forcing manufacturers to invest in clinical trials that validate muscle maintenance and recovery benefits, which in turn builds physician trust and hospital formulary inclusion.
- China's urban aging demographics:Municipal healthcare infrastructure in Shanghai, Beijing, and Guangzhou is expanding contracted meal delivery programs for seniors, creating dedicated procurement streams for ready-to-drink medical nutrition that bypass traditional retail entirely.
- Enzymatic hydrolysis technology:Advanced protein processing methods are reducing allergenicity while improving bioavailability, enabling formulation expansion into pediatric and immunocompromised patient segments previously excluded from standard nutritional beverages.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings tied to New Zealand and EU milk production cycles compress gross margins for mid-tier manufacturers lacking long-term supply contracts with cooperative processors.
- FDA structure-function claim scrutiny:Warning letters targeting immune support and cognitive benefit assertions have forced reformulation and label revisions, extending product launch timelines by 8-14 months for US market entrants.
- Plant protein digestibility gaps:Pea and rice protein isolates deliver inferior leucine bioavailability compared to dairy sources, limiting clinical acceptance in sarcopenia management protocols where amino acid threshold dosing is critical.
Strategic Opportunities
- Japan's kaigo care integration:Long-term care insurance expansion is reimbursing prescribed medical nutrition for homebound elderly, opening direct-to-patient subscription channels that circumvent pharmacy retail markups.
- Personalized microbiome formulations:Convergence of rapid gut health diagnostics and precision fermentation is enabling condition-specific probiotic-enriched beverages targeting IBS, post-surgical recovery, and antibiotic-associated diarrhea.
- South Korea's HMR regulatory pathway:MFDS streamlined approval for health functional foods creates faster market access for clinically substantiated protein-fortified drinks compared to pharmaceutical-grade medical nutrition registration.
Industry Challenges
- Clinical trial recruitment bottlenecks:Geriatric endpoint studies require extended observation periods and higher dropout allowances, stretching R&D budgets and delaying competitive claim differentiation against established hospital brands.
- Legacy ERP integration with track-and-trace mandates:China's NMPA serialization requirements for imported nutritional drinks demand supply chain software overhauls that many regional distributors lack technical capacity to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Drink Market |
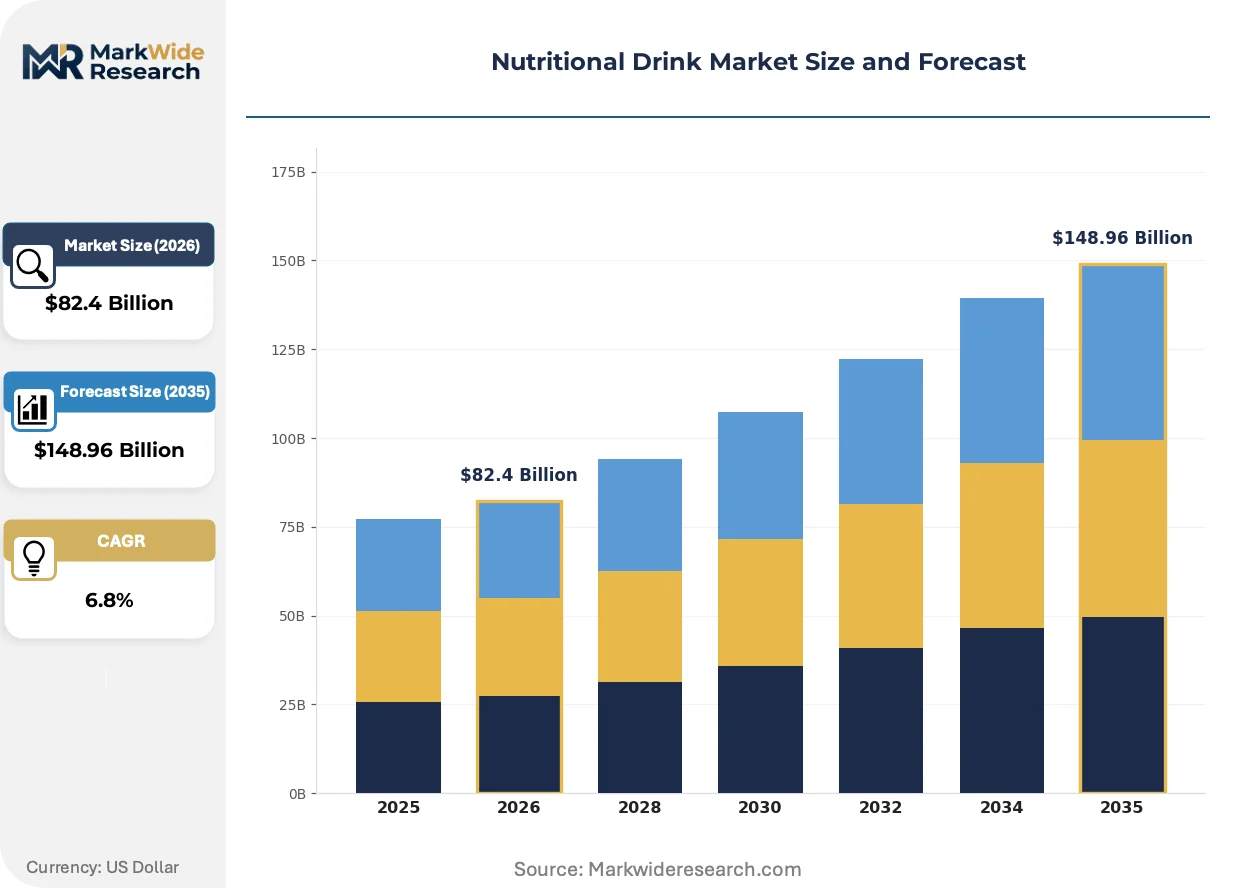
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $148.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacement, Protein Shake, Ready-to-Drink, Nutrient Supplement Target Consumer: Athletes, Health-Conscious Individuals, Elderly, Children Flavor Profile: Chocolate, Vanilla, Strawberry, Berry Blend Packaging Type: Single-Serve Pouches, Tetra Pak, Bottles, Cans |
| Companies Covered | Nestle, PepsiCo, Coca-Cola, Danone, Abbott Laboratories, Mead Johnson Nutrition, Reckitt Benckiser, Hormel Foods, Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Drink Market Trends and Innovations
Precision fermentation and cellular agriculture are disrupting traditional protein sourcing, while regulatory convergence around front-of-pack labeling is compressing formulation flexibility across major markets.
Precision fermentation-derived whey proteins are decomposing the conventional dairy supply chain for premium nutritional beverages. Nestle and Danone are piloting facility-scale production of bioidentical lactoferrin and beta-lactoglobulin without cow agriculture, targeting 2026-2027 commercial scale. This technology is decomposing geographic dependence on New Zealand and EU dairy cooperatives, enabling supply security for manufacturers in protein-deficient regions.
China's NMPA is implementing stricter registration requirements for imported foods for special medical purposes, mandating domestic clinical trials and localized stability data. This policy is fragmenting global product portfolios as multinational manufacturers develop China-specific formulations rather than adapting existing SKUs. Pediatric and geriatric medical nutrition categories face the longest approval queues, prompting joint ventures with domestic license holders.
Hospital procurement departments are consolidating nutritional beverage purchasing through centralized tenders and exclusive distribution agreements. This concentration is displacing fragmented pharmacy retail channels for medical-grade products, particularly in China's tier-one city hospital networks and Germany's Klinikverbund systems. The shift is most visible in oncology and post-surgical recovery segments where formulary inclusion determines volume allocation.
Nutritional Drink Market Segmentation
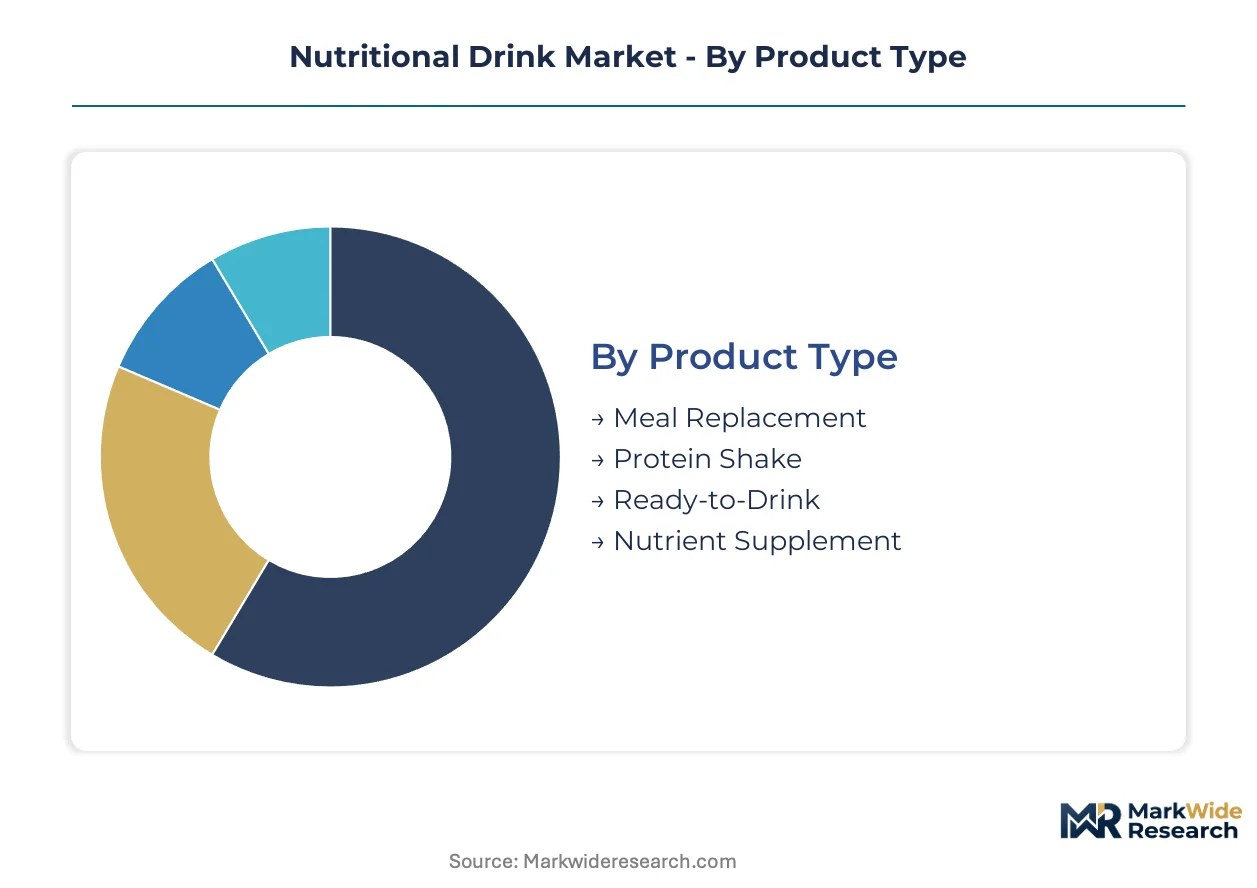
Segmentation in nutritional beverages reveals how formulation specifications, delivery formats, and consumer physiology create distinct competitive arenas. Manufacturers must align R&D investment with the technical thresholds and regulatory pathways governing each category.
Product Type:
Substitution pressure from whole-food alternatives and pharmaceutical interventions varies sharply across liquid nutrition formats, forcing manufacturers to defend functional differentiation.
- Meal Replacement:Complete macronutrient profiles delivering 400-600 calories with balanced protein-carbohydrate-fat ratios for satiety management. Demand concentrates among working professionals in Shanghai and Beijing managing caloric intake through office-based consumption, constrained by China's NMPA registration requirements for foods for special medical purposes.
- Protein Shake:Concentrated protein delivery systems typically containing 20-30 grams per serving with minimal carbohydrate load for muscle protein synthesis. Athletes and fitness enthusiasts in Germany's urban centers drive procurement, though EFSA tightening of muscle maintenance claim substantiation extends clinical trial timelines.
- Ready-to-Drink:Shelf-stable liquid formulations requiring no preparation, spanning nutritional density from light refreshment to medical-grade density. Convenience-seeking elderly consumers in Japan's kaigo care programs accelerate volume through institutional procurement channels.
- Nutrient Supplement:Targeted micronutrient and condition-specific formulations addressing deficiencies rather than complete nutrition. Pediatric applications in India's urban middle-class households expand as fortified beverage awareness spreads.
Meal Replacement retains volume leadership; Ready-to-Drink holds the steepest expansion curve.
Target Consumer:
Cost tier stratification separates premium clinical formulations from mass-market wellness positioning, with reimbursement eligibility determining accessible price points.
- Athletes:High-leucine protein formulations with rapid absorption kinetics for post-exercise recovery windows. Sports nutrition channels in the United States face FDA scrutiny over structure-function claims for performance benefits.
- Health-Conscious Individuals:Clean-label formulations emphasizing organic certification and reduced additive profiles. Urban professionals in South Korea's Seoul metropolitan area drive MFDS-regulated health functional food procurement.
- Elderly:Texture-modified and high-protein density formulations addressing sarcopenia and dysphagia. Japan's long-term care insurance expansion reimburses prescribed medical nutrition for homebound populations.
- Children:Pediatric-appropriate micronutrient fortification with palatability-optimized flavor systems. China's NMPA mandates domestic clinical trials for imported pediatric medical nutrition, fragmenting global product portfolios.
Elderly applications command premium pricing; Health-Conscious Individuals deliver the fastest volume scaling.
Flavor Profile:
Application context dictates flavor acceptance thresholds, with clinical settings prioritizing compliance over preference and retail wellness segments demanding sensory differentiation.
- Chocolate:Dominant flavor profile leveraging cocoa alkaloid masking of protein off-notes and mineral aftertastes. Retail shelf positioning in Germany and the United States secures highest velocity placement.
- Vanilla:Neutral base facilitating protein and micronutrient integration without competing flavor compounds. Hospital formulary inclusion favors vanilla for patient compliance across diverse demographic palates.
- Strawberry:Fruit-derived flavor systems requiring natural color stabilization and acid-base balance for shelf stability. Pediatric segments in India show strong preference affinity.
- Berry Blend:Polyphenol-rich formulations marketed for antioxidant positioning in wellness channels. EFSA health claim substantiation requirements limit explicit benefit communication in European markets.
Chocolate dominates retail velocity; Berry Blend climbs fastest in premium wellness positioning.
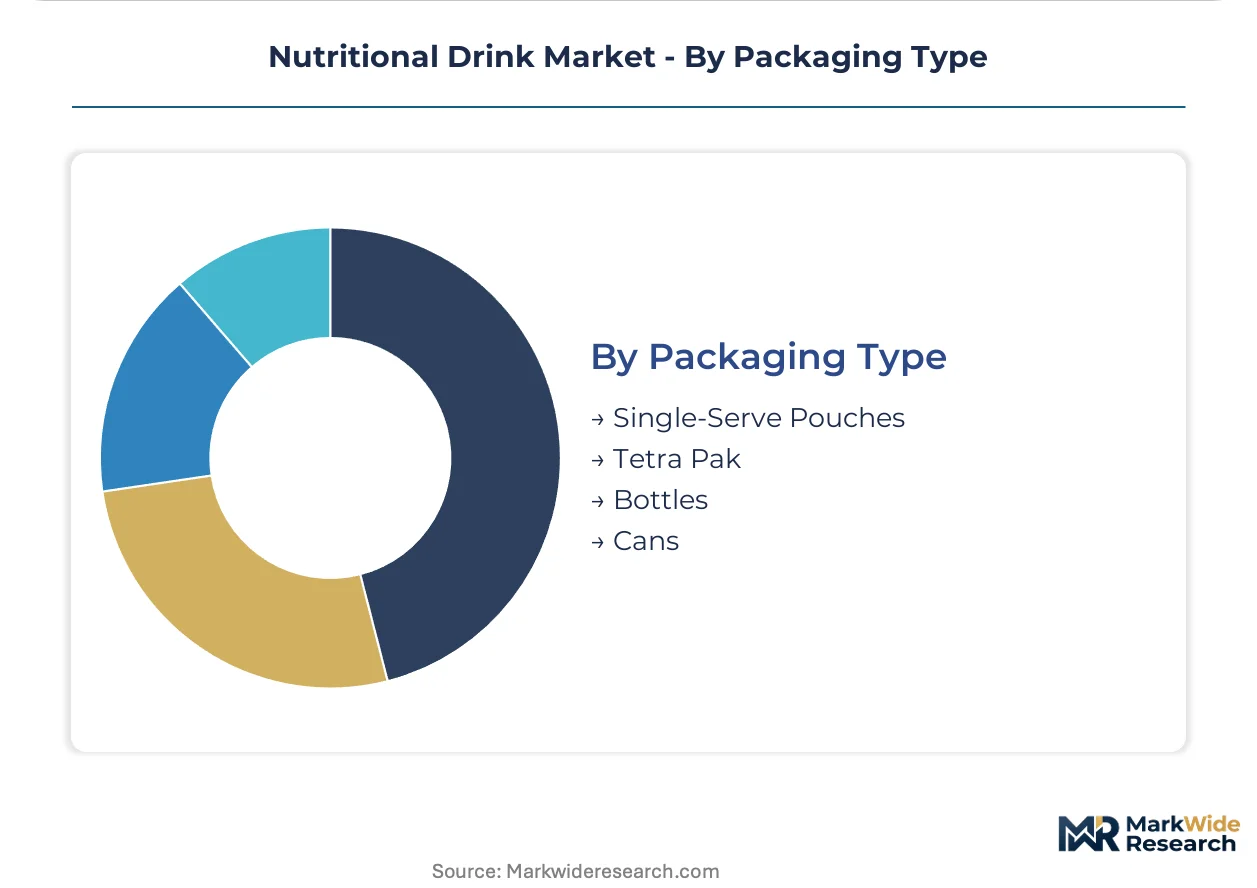
Packaging Type:
Supply concentration in aseptic processing equipment shapes format availability, with capital-intensive Tetra Pak lines limiting manufacturer flexibility.
- Single-Serve Pouches:Flexible film structures with spout fitments enabling portion control and reduced material weight. Emergency nutrition programs and military procurement in the United States specify pouch formats for logistics efficiency.
- Tetra Pak:Aseptic carton systems delivering extended shelf stability without refrigeration for ambient distribution. China's retail infrastructure expansion favors Tetra Pak for rural market penetration.
- Bottles:PET and HDPE rigid containers supporting hot-fill and aseptic processing with resealability. Ready-to-drink protein beverages in Germany's fitness retail channels standardize on bottle formats.
- Cans:Aluminum and steel containers enabling retort sterilization for highest thermal processing requirements. Metal packaging dominates Japan's liquid meal replacement vending machine distribution.
Tetra Pak retains installed base leadership; Single-Serve Pouches gain share fastest in emergency and institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's nutritional beverage distribution hub, while China's high-speed rail network enables same-day temperature-controlled delivery from Yangtze River Delta manufacturing clusters to interior provinces.
United States
FDA structure-function claim enforcement has compressed launch timelines for immune-support beverages. Hospital procurement consolidation through group purchasing organizations concentrates volume allocation among formulary-approved suppliers. Abbott Laboratories anchors medical nutrition supply chains through long-term care facility partnerships across the Midwest and Southeast.
Germany
EFSA protein claim substantiation requirements extend clinical trial obligations for muscle maintenance assertions. Klinikverbund hospital networks centralize nutritional beverage purchasing through exclusive distribution tenders. Bavaria's dairy processing cooperatives supply whey protein concentrates to regional formulation facilities.
China
NMPA registration mandates for foods for special medical purposes fragment global product portfolios into China-specific SKUs. Shanghai's municipal healthcare infrastructure expands contracted meal delivery programs for urban elderly populations. Yangtze River Delta manufacturing clusters produce ready-to-drink formulations for domestic consumption and Southeast Asian export.
Japan
Long-term care insurance expansion reimburses prescribed medical nutrition for homebound elderly through kaigo care programs. METI standards govern functional food labeling for protein-fortified beverages targeting sarcopenia management. Kansai region vending machine networks distribute liquid meal replacements through convenience retail channels.
South Korea
MFDS streamlined approval pathways for health functional foods accelerate market entry for clinically substantiated protein drinks. Seoul metropolitan area working professionals drive ready-to-drink consumption through office-based meal replacement routines. Busan-Ulsan pharmaceutical manufacturing clusters supply active ingredients for condition-specific nutritional formulations.
Nutritional Drink Market Competitive Landscape
Listed leaders compete with private specialists across formulation science and distribution reach, producing a tiered structure where scale-driven multinationals anchor hospital procurement while regional players capture retail wellness channels. Three archetypes dominate: dairy-heritage conglomerates with integrated protein supply chains, pharmaceutical-origin medical nutrition specialists, and beverage-industry entrants leveraging existing retail distribution infrastructure. Competitive moves concentrate on M&A for clinical trial capabilities and exclusive hospital formulary agreements.
Within the pharmaceutical-origin tier, Abbott Laboratories and Danone occupy positions exemplifying science-backed medical nutrition positioning, while Nestle represents the scale-driven multinational archetype leveraging global retail networks for ready-to-drink penetration. These three entities anchor distinct competitive vectors: hospital and long-term care institutional supply, pediatric and adult medical nutrition specialization, and mass-market meal replacement distribution through consumer retail channels.
| Leading Market Players |
|---|
| Nestle |
| PepsiCo |
| Coca-Cola |
| Danone |
| Abbott Laboratories |
| Mead Johnson Nutrition |
| Reckitt Benckiser |
| Hormel Foods |
| Hain Celestial Group |
| Others |
Pricing and Supply Chain Analysis
EFSA protein claim substantiation requirements gate both manufacturer qualification and price differentiation simultaneously, as clinical trial investments for muscle maintenance claims separate premium medical nutrition from commodity wellness beverages while compressing margins for unsubstantiated products.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with premium tiers anchored by hospital formulary inclusion and FDA-recognized medical food status. Price differentiation rests on clinical substantiation depth and reimbursement eligibility rather than ingredient cost alone. Pricing pressure stems from whey protein concentrate volatility tied to New Zealand and EU dairy cycles. Hospital procurement departments show lowest price sensitivity; retail wellness channels exhibit highest elasticity.
Supply Chain Analysis
New Zealand and the European Union anchor whey protein concentrate production, while China's Yangtze River Delta manufacturing clusters dominate ready-to-drink formulation and aseptic processing. Raw material dependencies include dairy protein isolates, plant-based alternatives, and specialized micronutrient premixes. Single-source vulnerability concentrates in enzymatic hydrolysis technology licensors. Distribution runs through hospital group purchasing organizations in the United States and Klinikverbund tender systems in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from whole-food meal delivery services and personalized nutrition platforms, requiring defensive positioning around clinical credibility and institutional procurement lock-in.
For Market Incumbents: Shield formulary positions through exclusive long-term care facility partnerships and backward integration into precision fermentation capacity. Deepen clinical trial pipelines for EFSA-compliant muscle maintenance claims before generic competitors achieve substantiation parity. Prioritize ERP upgrades for China's NMPA serialization mandates to maintain import authorization.
For New Entrants and Emerging Players: Post-surgical recovery subscription services for homebound elderly represent the most penetrable white-space, as Japan's kaigo care reimbursement expansion outpaces incumbent direct-to-patient capabilities. Target South Korea's MFDS streamlined health functional food pathway for faster market access than pharmaceutical-grade registration. Deploy microbiome diagnostic partnerships as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from dairy-heritage conglomerates seeking to divest non-core medical nutrition assets amid portfolio rationalization. Long-term viability hinges on regulatory science capabilities and hospital procurement relationships rather than brand equity alone. Watch for EFSA warning letter patterns as early indicators of claim substantiation failure and subsequent margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EFSA-compliant muscle maintenance studies enable premium pricing and hospital formulary inclusion. |
| Regulatory Approval Pathway | China NMPA registration for foods for special medical purposes unlocks institutional procurement channels. |
| Backward Integration | In-house precision fermentation capacity reduces exposure to New Zealand dairy commodity cycles. |
| Long-term Supply Agreement | Exclusive distribution tenders with Klinikverbund networks secure volume allocation in Germany. |
| Joint Venture | Domestic license holder partnerships in China accelerate pediatric medical nutrition approval timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital procurement managers, long-term care facility nutrition directors, regulatory affairs leads at formulation companies, and dairy cooperative supply planners. Secondary validation drew from FDA warning letter databases, EFSA health claim opinions, China NMPA registration filings, and hospital group purchasing organization contract disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Across the analysis window, forecasts segmented by product type, target consumer physiology, flavor profile, and packaging format. CAGRs derived from regression analysis against aging demographic trajectories, urbanization rates, and institutional healthcare expenditure trends. Industry-specific inputs included protein fortification threshold evolution and front-of-pack labeling mandate implementation schedules.
Forecasts assume regulatory continuity in FDA structure-function claim enforcement and EFSA substantiation standards; material policy shifts would require re-modeling. Specific risks include NMPA registration queue extensions, clinical trial recruitment bottlenecks in geriatric endpoints, and precision fermentation scale-up delays. Recalibration cycles align with material shifts in reimbursement policy and protein sourcing technology commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Coq10 Gummies Market