
 South America Pea Protein Market | 2026-2036
South America Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
South America Pea Protein Market Analytics
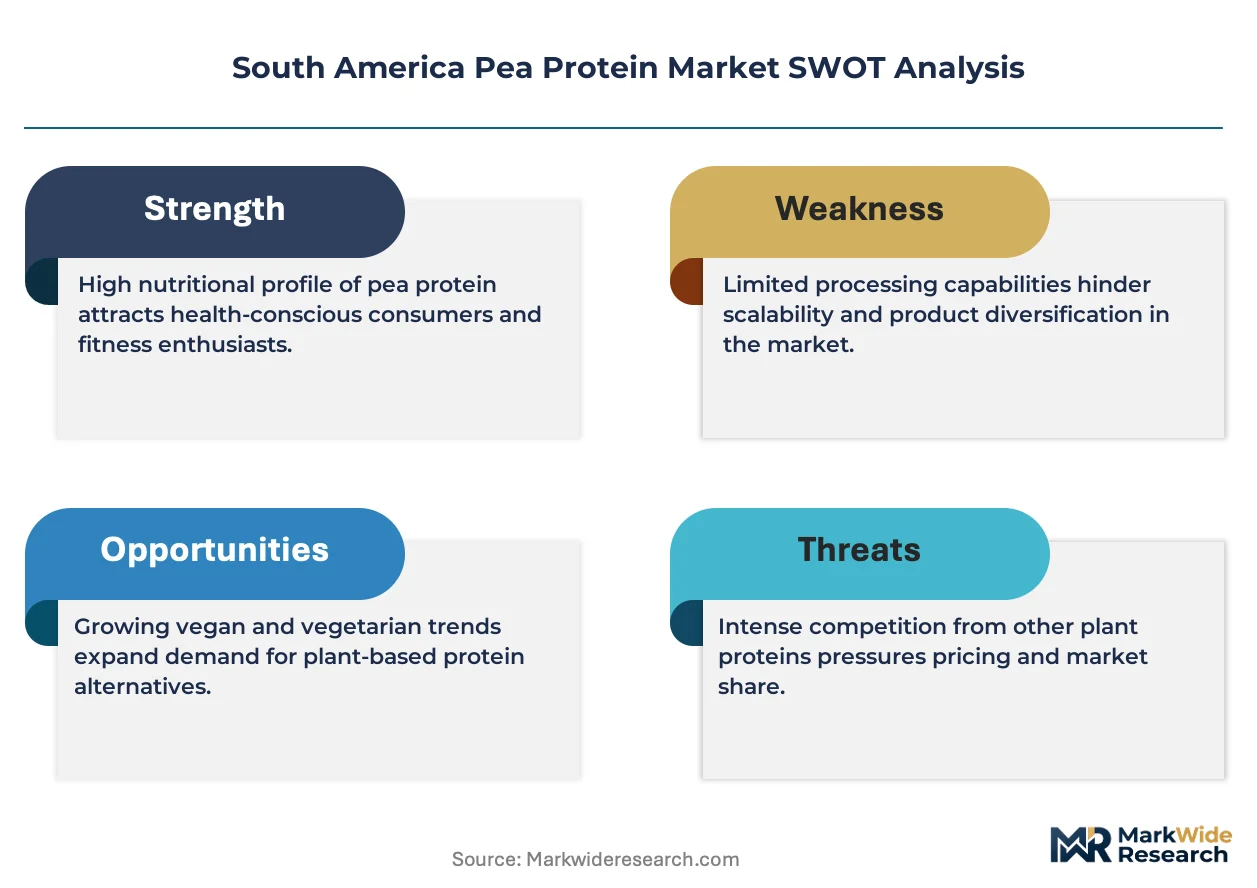
Argentine pea protein extraction capacity is rebalancing toward higher-purity output. Cargill, Incorporated leverages its continental grain handling infrastructure to secure raw yellow pea supply. Roquette Frères anchors European process technology within Brazilian toll-manufacturing partnerships. Puris Foods competes on non-GMO identity preservation from farm through isolation.
Pea protein denotes the isolated or concentrated protein fraction extracted from Pisum sativum seeds via dry milling, air classification, and alkaline solubilization followed by isoelectric precipitation, yielding products with protein content ranging from 80% to 90% on a dry basis for use in food formulation, sports nutrition, and meat analog systems. Isolate commands premium positioning in dairy alternatives and clear beverage systems where solubility and neutral flavor prove decisive. Concentrate retains cost advantage in bakery and extruded meat alternatives where slightly higher starch content remains functionally acceptable. Textured grades occupy emerging capacity as Brazilian and Chilean brands expand whole-muscle analog portfolios.
ANVISA governs novel food ingredient approvals and protein content labeling claims across Brazil, while Argentina's national food code authority enforces compositional standards that directly affect isolate versus concentrate marketability. The Mercosur technical regulation harmonization process creates cross-border formulation complexity that favors multi-country registration capabilities. Stakeholders must track pending protein content threshold definitions and monitor how Brazilian PLI-style bioeconomy incentives redirect domestic crushing investment toward food-grade rather than feed-grade pea fractionation.
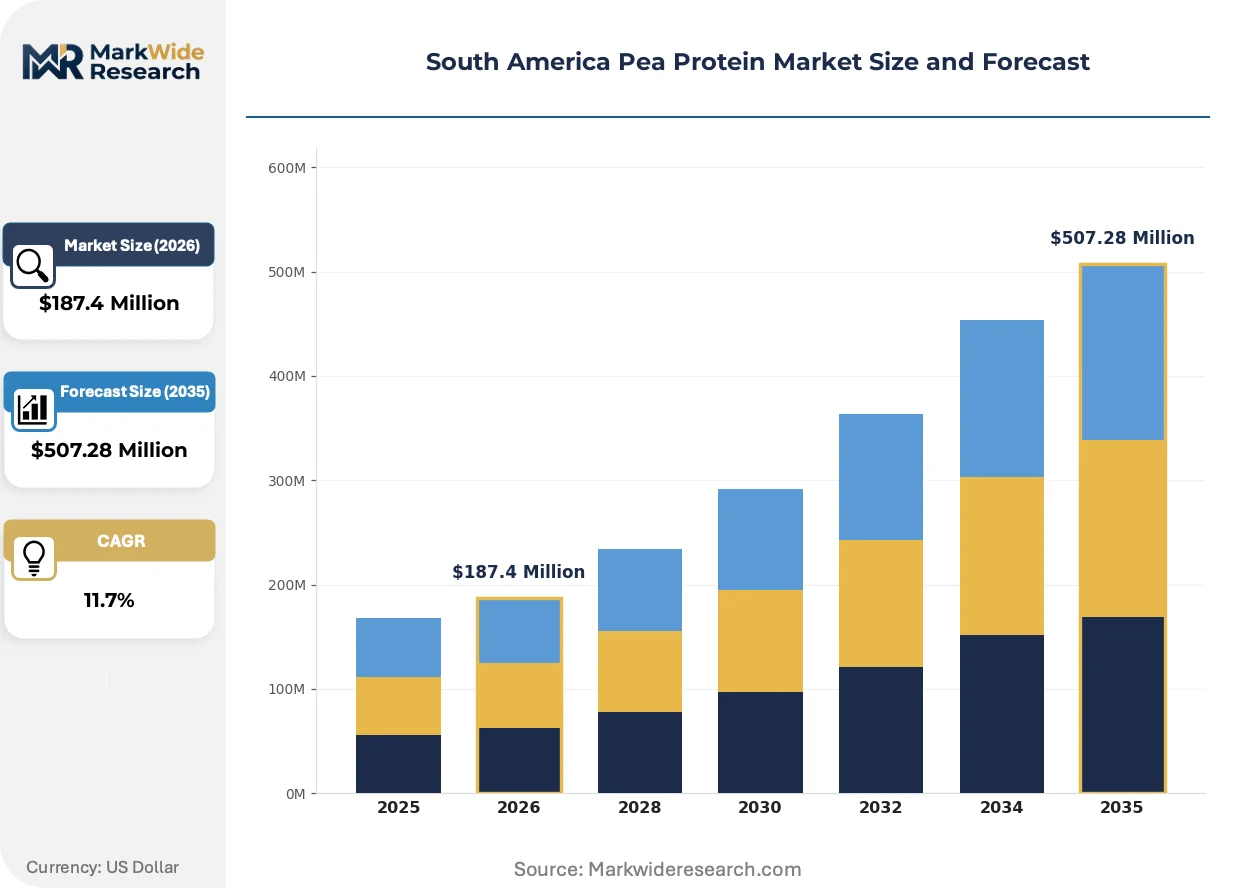
Market Dynamics
ANVISA's pending protein content threshold definitions are forcing Brazilian formulators to recalibrate isolate versus concentrate ratios ahead of enforcement, while Argentine crushing investment tilts toward food-grade fractionation capacity.
Growth Catalysts
- ANVISA Novel Food Pathways:Brazil's evolving ingredient classification framework accelerates isolate registration for beverage applications, pulling investment toward higher-purity extraction infrastructure.
- Plant-Based Meat Analog Demand:Brazilian food processors expand extruded whole-muscle portfolios, absorbing textured pea protein volumes at contract-scale procurement commitments.
- Mercosur Harmonization:Cross-border technical regulation alignment reduces duplicate formulation testing, enabling multi-country SKU deployment from single production bases.
Market Restraints
- Yellow Pea Input Volatility:Argentine drought cycles compress domestic raw material availability, forcing Brazilian processors to absorb import freight premiums from North American suppliers.
- Isolate Production Concentration:Higher-purity extraction capacity clusters in southern Brazil and Buenos Aires province, creating geographic single-point vulnerability for beverage-grade supply.
- Functional Limitation in Clear Systems:Residual lipoxygenase activity in standard isolates generates off-flavor development in extended-shelf-life beverages, restricting addressable market scope.
Strategic Opportunities
- Colombian Beverage White Space:Underdeveloped local extraction infrastructure forces Colombian dairy alternative brands to import isolate at premium landed cost, creating toll-manufacturing entry potential.
- Chilean Whole-Muscle Analog Expansion:Santiago-based food tech ventures pilot textured protein extrusion for seafood analog applications, diverting capacity from traditional meat replacement formats.
- Brazilian PLI-Style Bioeconomy Incentives:Pending domestic crushing subsidies redirect capital expenditure toward food-grade pea fractionation rather than legacy feed-grade output.
Industry Challenges
- Protein Quantification Skill Gap:Argentine and Brazilian laboratories lack standardized Dumas combustion capacity for rapid isolate verification, extending batch release timelines.
- Dual Registration Burden:Mercosur harmonization remains incomplete for protein content claims, forcing parallel compliance documentation for Brazilian and Argentine market entry.
- Extrusion Equipment Lead Times:Textured protein capacity expansion confronts twelve-month delivery schedules for twin-screw systems, constraining Brazilian brand launch cadence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Pea Protein Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Textured End User: Food & Beverage, Nutraceuticals, Bakery, Meat Alternatives Application: Protein Supplements, Dairy Alternatives, Snacks, Culinary Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Archer-Daniels-Midland Company, Cosucra, Cargill, Incorporated, The Scoular Company, Puris Foods, Ingredion Incorporated, Roquette Frères, Sotexpro, Glanbia plc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Pea Protein Market Evolving Landscape
Enzymatic debittering protocols and precision fermentation hybrids are compressing the flavor-function tradeoff that has historically constrained isolate adoption in neutral-taste applications.
Membrane filtration cascades are rewriting the economics of 90% protein isolate production. Brazilian toll-manufacturing partners deploy European-designed ceramic microfiltration systems to reduce alkaline solubilization steps. This equipment compression is enabling mid-scale processors to challenge legacy extraction specialists on isolate purity metrics.
Argentina's national food code authority is tightening compositional standards for protein content claims on isolate-labeled products. The enforcement trajectory forces reformulation of existing beverage SKUs to hit revised minimum thresholds. Brazilian exporters targeting Argentine retail channels are front-loading analytical verification investments to preempt border detention risk.
Buyer concentration among São Paulo-based dairy alternative brands is consolidating procurement decisions into technical sourcing teams with direct extrusion expertise. These teams are displacing traditional ingredient distributors from specification-setting roles. The shift is most visible in contract structures that embed annual volume commitments with price collars tied to yellow pea futures.
South America Pea Protein Market Segmentation
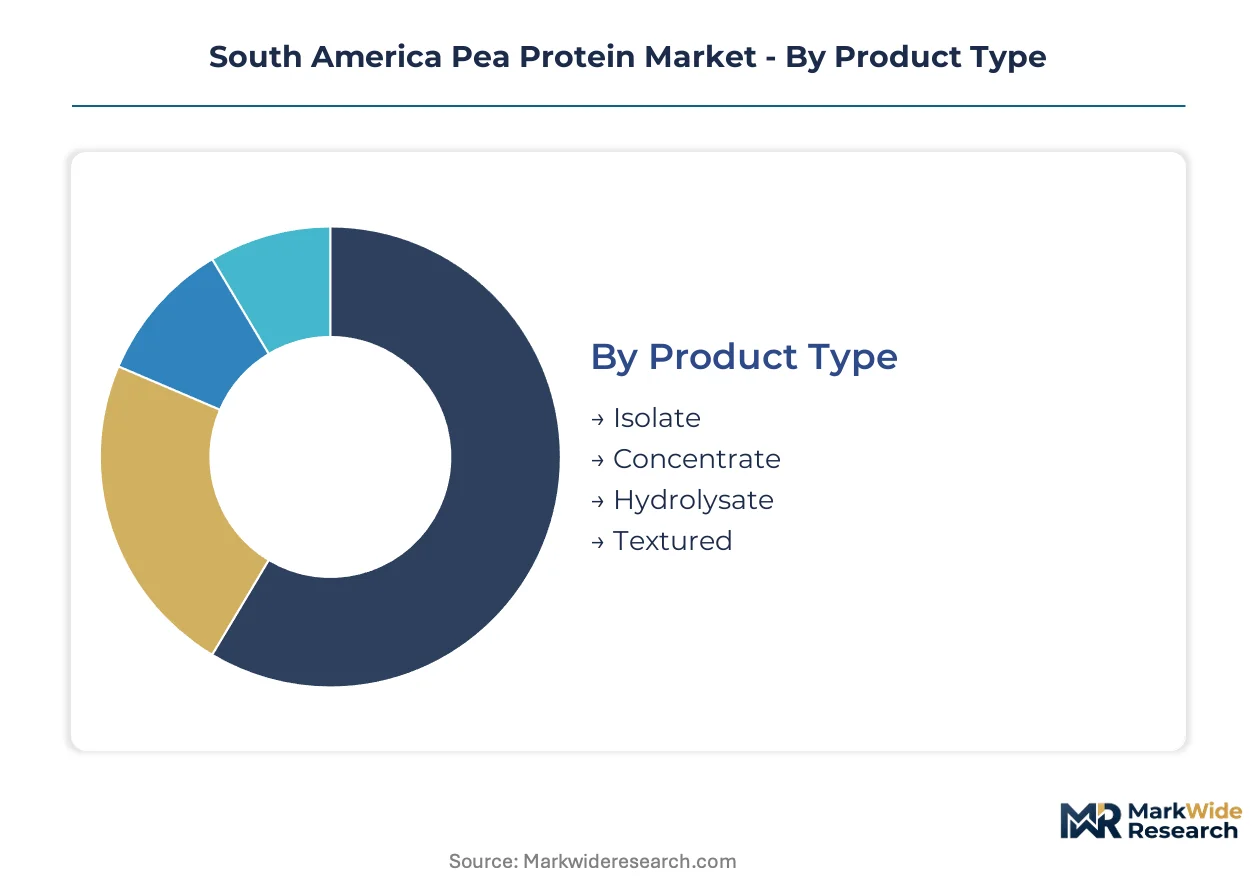
Pea protein segmentation in South America reflects divergent purity requirements across Brazilian beverage formulators and Argentine meat-alternative extruders. Technical specifications vary sharply by end-use, with ANVISA registration pathways favoring isolate grades while bakery applications absorb concentrate cost efficiencies.
Product Type:
Customization-to-standardization tension runs deepest here, with isolate commanding bespoke extraction protocols versus textured grades scaling through commoditized extrusion infrastructure.
- Isolate:Comprising 80-90% protein on a dry basis through alkaline solubilization and isoelectric precipitation. São Paulo dairy-alternative brands concentrate procurement here for neutral flavor and solubility in clear beverage systems, though residual lipoxygenase activity constrains extended-shelf-life applications.
- Concentrate:Retaining 50-80% protein with higher starch and fiber fractions. Brazilian bakery processors and extruded snack manufacturers leverage its cost advantage where slight off-notes remain masked by thermal processing, absorbing volumes from southern Brazilian toll-manufacturers.
- Hydrolysate:Enzymatically pre-digested for rapid amino acid absorption in sports nutrition applications across Argentine gym-channel distribution.
- Textured:Thermoplastic extrusion yields fibrous structures for whole-muscle meat analogs, with Chilean food-tech ventures piloting seafood-specific geometries.
Leading the category by volume: Concentrate. Growing fastest: Textured.
End User:
Margin stratification separates pharmaceutical-grade nutraceutical buyers from commodity bakery accounts, with meat alternatives capturing the steepest capacity expansion.
- Food & Beverage:Dominant value concentration spanning protein-fortified juices, plant-based milks, and ready-to-drink nutritionals. Brazilian ANVISA novel food approvals accelerate isolate uptake here.
- Nutraceuticals:Sports nutrition and clinical nutrition segments demand hydrolysate and isolate grades with batch-level amino acid profiling, commanding premium positioning in Colombian urban centers.
- Bakery:Concentrate grades penetrate panadería supply chains through Argentine distributors, with emulsification properties replacing egg functionality in vegan formulations.
- Meat Alternatives:Textured protein absorption is climbing the fastest as Brazilian brands expand extruded whole-muscle portfolios beyond ground-format legacy products.
Dominant by revenue: Food & Beverage. Expanding most quickly: Meat Alternatives.
Application:
Volume concentration favors established formats while emerging categories reshape procurement specifications.
- Protein Supplements:Powder and ready-to-mix formats concentrate demand in Brazilian fitness channels, with isolate and hydrolysate grades specified for post-workout positioning.
- Dairy Alternatives:Oat-pea and pea-dominant milks drive isolate procurement from São Paulo technical sourcing teams embedding annual volume commitments with price collars tied to yellow pea futures.
- Snacks:Extruded puffs and protein bars absorb concentrate grades through Argentine and Brazilian co-manufacturing relationships.
- Culinary:Emerging pea protein isolates in sauce thickening and emulsification applications, particularly in Colombian and Chilean foodservice trials.
Category leader by tonnage: Protein Supplements. Gaining share fastest: Dairy Alternatives.
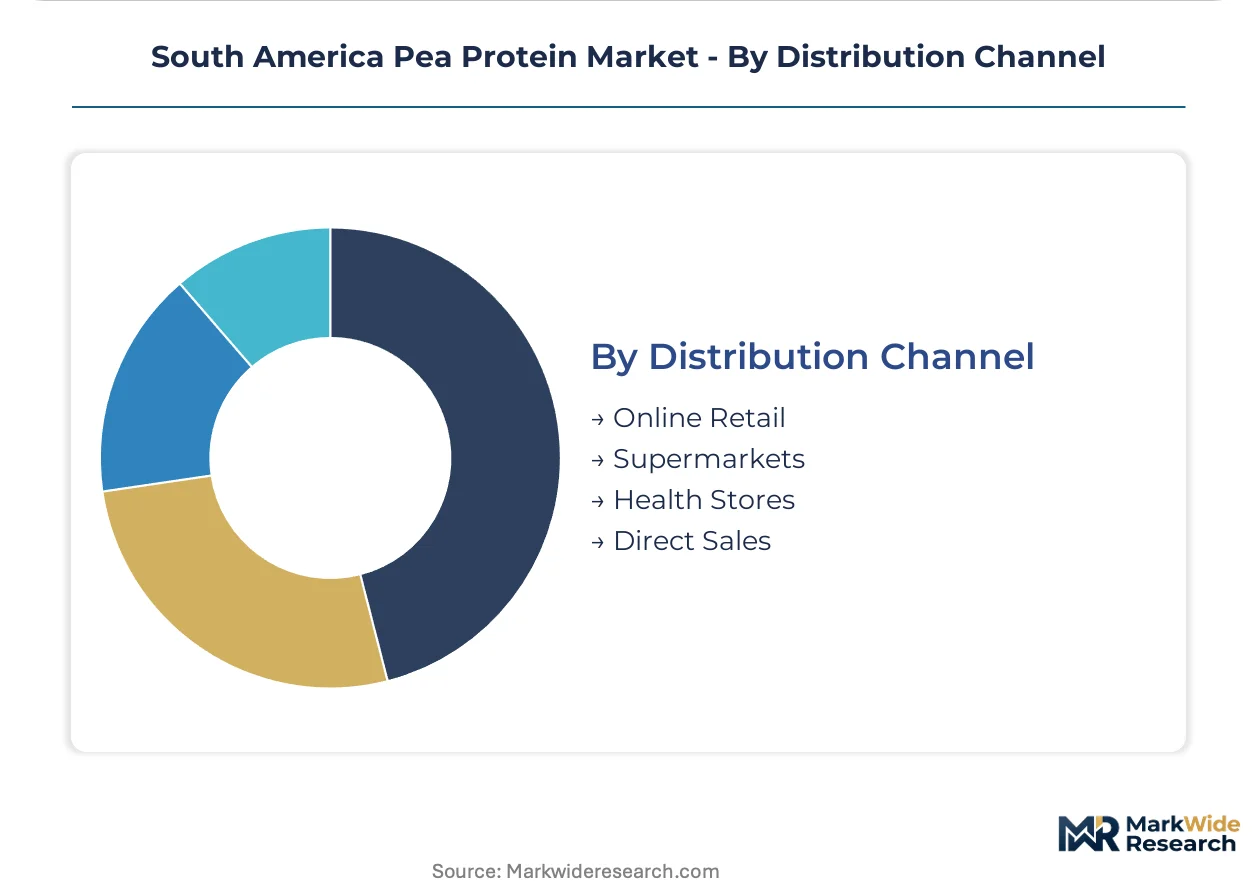
Distribution Channel:
Customer-type stratification separates institutional procurement from fragmented retail access, with digital channels compressing traditional distributor margins.
- Online Retail:Direct-to-consumer protein powders and specialty ingredients bypass São Paulo distributor markups, though logistics complexity limits bulk isolate shipments.
- Supermarkets:Mass-market pea-protein-fortified products concentrate shelf space in Brazilian and Argentine retail chains, with private-label expansion driving concentrate-grade specification.
- Health Stores:Premium isolate and organic-certified concentrates target affluent urban consumers in Buenos Aires and Santiago specialty retail.
- Direct Sales:Industrial buyers in Brazilian meat-alternative manufacturing secure textured protein through toll-manufacturing contracts with embedded technical service agreements.
Volume concentration: Supermarkets. Channel climbing fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine yellow pea cultivation in the Pampas grain belt anchors raw material flows into Brazilian processing corridors. Southern Cone extraction capacity clusters around Buenos Aires province and Rio Grande do Sul, with cross-border Mercosur trade shaping procurement economics.
Brazil
São Paulo dairy-alternative brands drive isolate procurement for oat-pea milk formulations. ANVISA's pending novel food ingredient classifications are forcing reformulation timelines ahead of enforcement. Southern Brazilian toll-manufacturing partnerships with European process technology providers are expanding higher-purity extraction infrastructure.
Argentina
Buenos Aires province crushing investment is tilting toward food-grade fractionation capacity away from legacy feed-grade output. The national food code authority is tightening compositional standards for protein content claims on isolate-labeled products. Rosario grain handling clusters are securing raw yellow pea supply through continental infrastructure networks.
Chile
Santiago-based food tech ventures are piloting textured protein extrusion for seafood analog applications. Local whole-muscle analog portfolios are expanding beyond ground-format legacy products. Valparaíso corridor logistics are supporting import-dependent isolate procurement for beverage formulation trials.
Colombia
Bogotá dairy alternative brands are absorbing imported isolate at premium landed cost due to underdeveloped local extraction infrastructure. National health authority registration pathways for novel protein ingredients remain less defined than Brazilian ANVISA frameworks. Medellín distribution channels are concentrating sports nutrition demand for hydrolysate grades.
South America Pea Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue toll-manufacturing partnerships and non-GMO identity preservation. The supplier base stratifies between multinational grain handlers with continental infrastructure and specialized extraction technology licensors. Three archetypes dominate: integrated agricultural processors, European process technology partners, and identity-preserved specialty suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves reshaping supply availability.
Among North American agricultural conglomerates, Cargill, Incorporated and Archer-Daniels-Midland Company represent integrated processing archetypes with grain handling infrastructure spanning the Southern Cone. European specialists exemplify technology-licensing positioning, with Roquette Frères anchoring process design partnerships in Brazilian toll-manufacturing arrangements. Puris Foods occupies a distinct tier focused on non-GMO supply chain verification from farm through isolation.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Cosucra |
| Cargill, Incorporated |
| The Scoular Company |
| Puris Foods |
| Ingredion Incorporated |
| Roquette Frères |
| Sotexpro |
| Glanbia plc |
| Others |
Value Network & Pricing Analysis
Yellow pea futures volatility transmits directly through Brazilian toll-manufacturing contracts, with São Paulo dairy-alternative brands embedding annual volume commitments and price collars to hedge Argentine drought-driven supply shocks. This raw material cost pathway splits downstream into isolate premiums for beverage-grade purity versus concentrate efficiencies for bakery and extruded meat analog applications.
Pricing Analysis
Service bundling separates technical support tiers, with São Paulo-based procurement teams demanding embedded extrusion expertise and batch-level amino acid profiling as standard inclusions. Three-tier pricing structure across premium isolate, standard concentrate, and economy feed-grade output reflects protein content thresholds and ANVISA registration status. Pricing pressure stems from Brazilian PLI-style bioeconomy incentives redirecting domestic crushing investment toward food-grade fractionation, expanding higher-purity capacity. Bakery processors exhibit highest price sensitivity, accepting slightly elevated starch content in concentrate grades, while nutraceutical buyers absorb isolate premiums for batch-level verification.
Supply Chain Analysis
Freight cost differentials between Argentine Pampas rail corridors and North American import routes determine Brazilian processor sourcing economics during drought cycles. Supply concentrates in Argentina, southern Brazil, and European process technology licensors, with raw yellow pea flows anchored in Rosario grain handling clusters. Critical dependencies include ceramic microfiltration systems, alkaline solubilization chemicals, and twin-screw extrusion equipment. Tariff exposure within incomplete Mercosur harmonization creates cross-border documentation friction. Distribution runs through São Paulo technical sourcing teams displacing traditional ingredient distributors, with direct toll-manufacturing contracts capturing textured protein volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade fractionation capacity scarcity across the Southern Cone props isolate pricing premiums, with twelve-month extrusion equipment lead times constraining Brazilian brand launch cadence and sustaining supplier bargaining power.
For Market Incumbents: Acquire distressed toll-manufacturing assets in southern Brazil to preempt European process technology partners from anchoring exclusive arrangements. Lock in multi-year yellow pea offtake agreements with Rosario grain handlers before Argentine drought cycles compress domestic availability. Certification investment in ANVISA novel food registration capabilities defends against emerging identity-preserved specialty suppliers threatening premium positioning. For New Entrants and Emerging Players: Begin with Colombian beverage white space, where underdeveloped local extraction infrastructure forces Bogotá dairy-alternative brands to import isolate at premium landed cost. Target toll-manufacturing entry with European-designed ceramic microfiltration systems, offering 90% protein purity without legacy alkaline solubilization steps. Lead with technical service agreements embedding extrusion expertise, mirroring São Paulo procurement team specifications. For Investors and Strategic Acquirers: ANVISA's pending protein content threshold enforcement is the leading indicator that Argentine border detention risk will consolidate compliant isolate suppliers into preferred vendor status. Long-term viability centers on backward integration into Pampas yellow pea cultivation or captive toll-manufacturing partnerships with Brazilian processors. Monitor Brazilian PLI-style bioeconomy incentive disbursement timelines as the signal for domestic crushing capital expenditure redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yellow Pea Cultivation | Cargill's continental grain handling infrastructure secures raw material flows against Argentine drought volatility. |
| Ceramic Microfiltration Capacity Expansion | European-designed systems enable mid-scale Brazilian processors to challenge legacy extraction specialists on isolate purity. |
| ANVISA Novel Food Registration Investment | Preemptive compliance documentation prevents Argentine border detention risk for Brazilian exporters. |
| Textured Protein Extrusion Partnership | Santiago food-tech ventures pilot seafood-specific geometries, diverting capacity from traditional meat replacement formats. |
| Non-GMO Identity Preservation Certification | Puris Foods competes on farm-through-isolation verification, commanding premium positioning in health store channels. |
Research Methodology
Document review covered ANVISA regulatory filings, Argentine national food code amendments, Mercosur technical regulation harmonization drafts, and yellow pea futures market data, complemented by interviews with extraction technology licensors, São Paulo dairy-alternative brand procurement leads, Brazilian toll-manufacturing plant managers, Argentine grain handling operators, and Colombian health authority registration specialists. Secondary validation drew from customs trade records, SEC filings of North American agricultural conglomerates, and equipment supplier order backlogs. Bottom-up volume modeling and top-down market sizing triangulated against processor capacity announcements.
Segmentation outputs reflect protein purity tiers, end-use applications spanning beverage formulation to meat analog extrusion, and distribution channel evolution across direct sales and retail concentration. CAGRs derived from historical isolate and concentrate price trajectories, capacity utilization assumptions, and ANVISA registration pathway acceleration scenarios. Forecast inputs incorporated drought cycle frequency in the Pampas, twin-screw extrusion equipment delivery schedules, and PLI-style incentive disbursement probabilities.
Underlying measurement precision varies by segment; isolate-grade procurement volumes carry tighter precision than emerging textured protein applications due to concentrated buyer visibility. Forecasts reflect documented assumptions on regulatory enforcement timing and raw material availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
India Pea Protein Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Plant-Based Margarine Market