
 Smart Grid Software Market | 2026-2036
Smart Grid Software Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grid Software Market Insights
Cloud-native architectures are repositioning utility software economics by displacing legacy on-premises systems with subscription-based delivery models. Siemens AG leverages deep domain expertise in grid automation to anchor European utility relationships. IBM Corporation competes through AI-powered analytics layers that integrate weather, load, and asset data for predictive operations. Cisco Systems, Inc. specializes in secure communications infrastructure that extends from substation routers to enterprise control centers.
Smart grid software encompasses the digital systems, algorithms, and platforms that monitor, control, and optimize electricity generation, transmission, and distribution networks in real time. These systems typically process telemetry at millisecond intervals, apply machine learning to forecast load patterns, and execute automated switching commands to maintain voltage stability and power quality. The analytics segment leads current revenue contribution as utilities prioritize visibility across geographically dispersed assets, while cloud deployment exhibits the fastest structural expansion due to lower capital barriers and faster upgrade cycles for mid-sized municipal utilities. Network management solutions occupy concentrated margin pools where specialized vendors command premium pricing for mission-critical fault-location and restoration capabilities.
The U.S. Federal Energy Regulatory Commission shapes wholesale market participation rules that dictate software compliance requirements for grid operators, while the EU F-Gas Regulation and GDPR constrain data center cooling choices and cross-border data flows for cloud-hosted platforms. India's CEA mandates communication protocol standards that determine vendor eligibility for national smart grid pilots. Stakeholders must weigh sovereign data requirements against cloud scalability when selecting deployment architectures for multi-country operations.
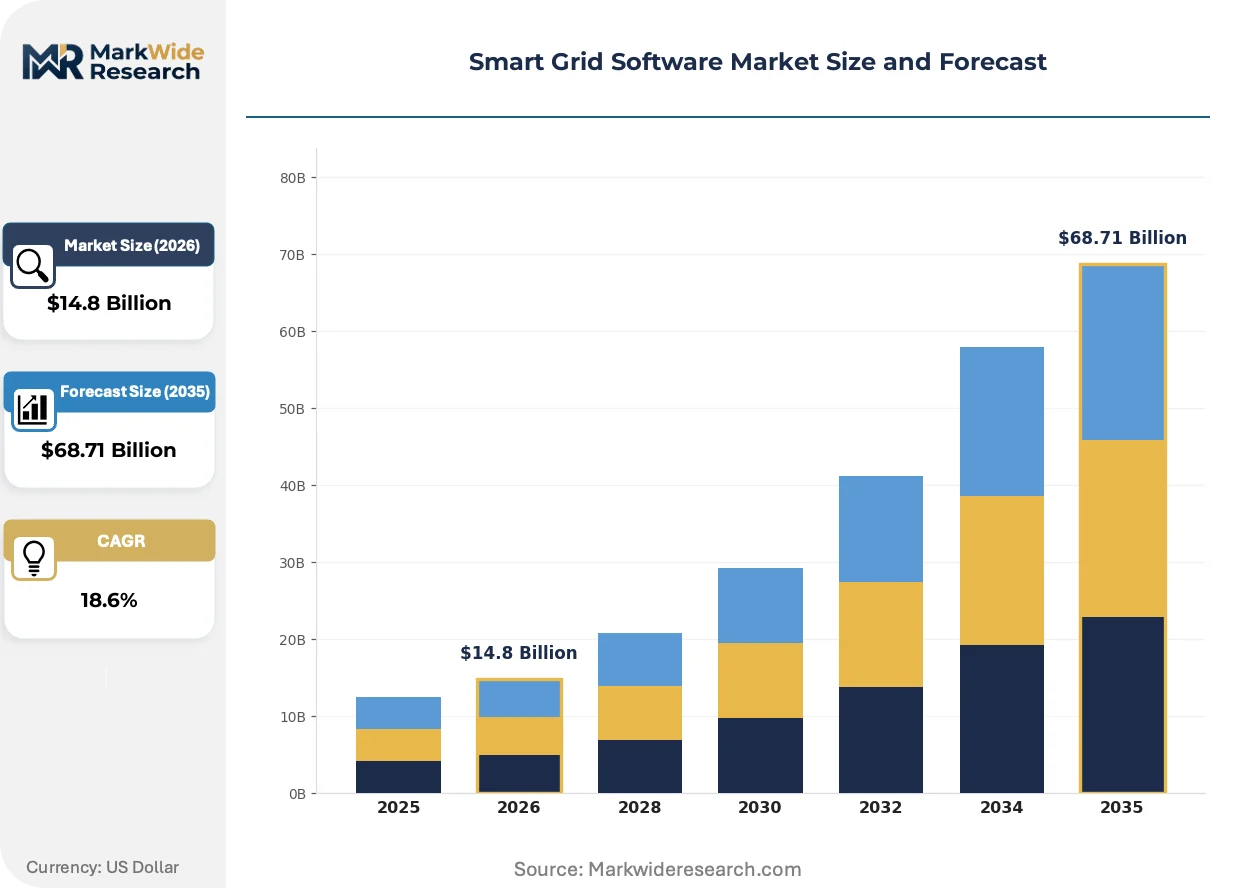
Market Dynamics
Cloud-native architectures are compressing deployment cycles and forcing legacy vendors to abandon perpetual-license models in favor of recurring-revenue structures.
Growth Catalysts
- Inflation Reduction Act:The U.S. legislation channels billions toward grid modernization and clean energy infrastructure, accelerating utility procurement of advanced software platforms.
- Energiewende mandates:Germany's policy framework mandates digital grid upgrades to absorb variable renewable generation, creating sustained demand for analytics and control systems.
- Distributed energy resource proliferation:Behind-the-meter solar and battery storage growth is forcing utilities to deploy real-time visibility tools for network stability.
Market Restraints
- Cross-border data friction:GDPR constraints on cloud-hosted platforms complicate multi-country operations for European utilities with assets spanning jurisdictions.
- Protocol standardization gaps:India's CEA-mandated communication standards limit vendor eligibility for national smart grid pilots, constraining supplier pool diversity.
- Legacy system entrenchment:Decades-old SCADA infrastructure at municipal utilities creates technical debt that slows cloud migration timelines.
Strategic Opportunities
- Mid-sized municipal utilities:This underpenetrated segment exhibits lower capital barriers for SaaS deployment compared to investor-owned utilities with entrenched vendors.
- AI-weather convergence:Machine learning integration with meteorological data streams enables predictive load forecasting that reduces curtailment costs.
- Subscription model expansion:Channel innovation toward usage-based pricing aligns vendor incentives with utility operational outcomes rather than upfront capital expenditure.
Industry Challenges
- Cybersecurity certification complexity:NERC CIP compliance timelines extend sales cycles for control-center software vendors serving North American utilities.
- OT-IT integration friction:Convergence of operational technology and information technology domains demands scarce hybrid skill sets in power systems and cloud architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grid Software Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Analytics, Automation, Demand Response, Network Management End User: Utilities, Energy Providers, Government, Industrial Clients Deployment: On-Premises, Cloud, Hybrid, Software as a Service Application: Energy Management, Grid Optimization, Monitoring, Fault Detection |
| Companies Covered | Siemens AG, IBM Corporation, Cisco Systems, Inc., Schneider Electric SE, ABB Ltd., General Electric Company, Itron, Inc., Honeywell International Inc., Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grid Software Market Trends and Innovations
Real-time telemetry processing and automated switching capabilities are redefining competitive requirements for grid software vendors.
Digital twin technology is modularizing utility asset management by creating virtual replicas of physical infrastructure. Mid-sized municipal utilities are adopting these platforms fastest due to lower legacy integration burdens. The technology is modularizing maintenance scheduling from calendar-based to condition-based interventions.
The EU F-Gas Regulation constrains data center cooling choices for cloud-hosted platforms, forcing vendors to redesign thermal architectures. This industrial consequence raises operational costs for European deployments. Grid analytics providers are responding by establishing sovereign cloud instances within member-state borders.
Utility buying committees are unbundling software procurement from hardware supply agreements that historically favored integrated vendors. This pattern disrupts traditional channel structures where automation hardware vendors controlled software decisions. The shift is most visible in Germany, where municipal utilities now issue separate RFPs for analytics platforms and substation equipment.
Smart Grid Software Market Segmentation
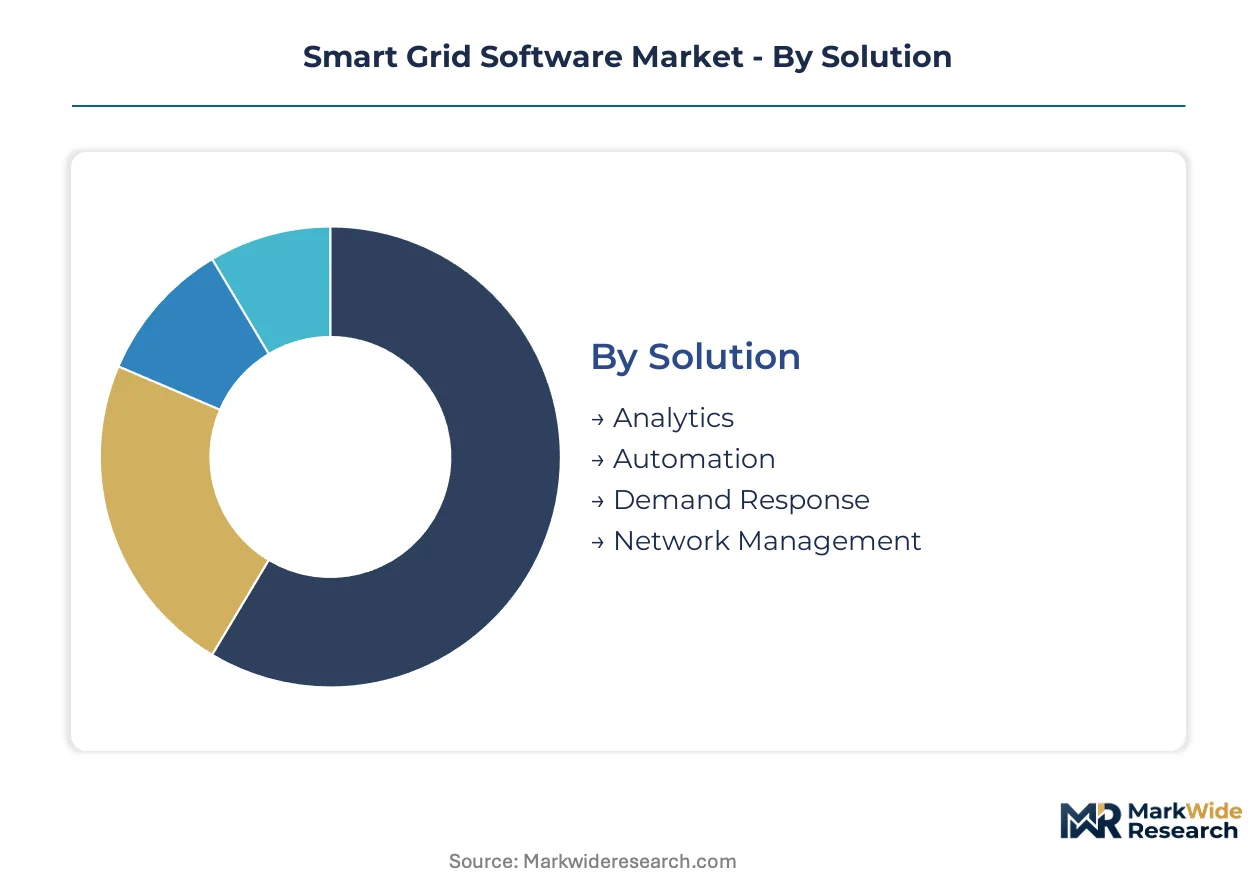
Segmentation in smart grid software determines which procurement pathways utilities pursue and which regulatory compliance burdens vendors must shoulder. The four-dimensional structure—spanning solution type, end user, deployment mode, and application—creates distinct margin pools and certification requirements across each axis.
Solution:
NERC CIP certification applies most stringently to Network Management and Automation segments, while Analytics and Demand Response face lighter operational-technology security mandates.
- Network Management:Fault-location algorithms and outage management systems process real-time SCADA telemetry to isolate disturbances and restore service. Demand concentrates at North American investor-owned utilities where FERC Order 2222 compliance requirements drive procurement of advanced distribution management systems.
- Analytics:Machine learning platforms integrate weather, load, and asset data to forecast renewable generation and optimize dispatch. German municipal utilities under Energiewende mandates represent the fastest-expanding customer base for predictive grid analytics.
- Automation:Automated switching and voltage regulation software executes millisecond control commands.
- Demand Response:Load curtailment platforms aggregate behind-the-meter flexibility.
Leading the category by volume: Analytics. Growing fastest: Network Management.
End User:
Cost tier stratification separates enterprise-grade procurement at large utilities from constrained budgets at municipal and government buyers.
- Utilities:Investor-owned and cooperative utilities deploy comprehensive software stacks spanning control centers to field operations. U.S. utilities leveraging IRA funding channels are replacing legacy SCADA with cloud-native platforms at accelerated procurement cycles.
- Industrial Clients:Heavy manufacturing and data center operators purchase behind-the-meter energy management software to optimize self-generation and grid services revenue. German automotive clusters and Texas petrochemical corridors exhibit concentrated demand for industrial microgrid control systems.
- Energy Providers:Independent power producers and retail energy suppliers.
- Government:Federal, state, and municipal agencies procuring for public infrastructure.
Dominant procurement volume sits with Utilities. Industrial Clients are climbing the fastest as commercial and industrial distributed energy adoption accelerates.
Deployment:
Application maturity varies sharply across deployment architectures, with SaaS offerings still proving cybersecurity credentials for critical infrastructure operators.
- Cloud:Scalable infrastructure enables mid-sized utilities to access enterprise-grade analytics without capital-intensive data center investments. Indian municipal utilities participating in CEA-mandated smart grid pilots favor cloud deployment to circumvent legacy integration burdens.
- Software as a Service:Subscription delivery compresses upgrade cycles and aligns vendor incentives with operational outcomes. German utilities navigating GDPR data residency requirements are driving demand for sovereign cloud SaaS instances hosted within national borders.
- On-Premises:Air-gapped systems serving critical infrastructure security requirements.
- Hybrid:Segregated architectures separating operational technology workloads from informational analytics.
Cloud deployment claims the largest installed base. SaaS models are expanding most quickly as municipal procurement committees gain comfort with subscription economics.
Application:
Functional priority determines software stack composition, with real-time operations commanding premium pricing against planning and optimization layers.
- Grid Optimization:Power flow algorithms and volt-VAR optimization tools minimize losses and defer capital upgrades. U.S. utilities in renewable-rich regions deploy these systems to manage bi-directional power flows from distributed solar and storage.
- Fault Detection:Traveling-wave and impedance-based algorithms pinpoint cable and equipment failures to accelerate crew dispatch. German distribution system operators under reliability mandates represent concentrated demand for advanced fault-location platforms.
- Energy Management:Enterprise-level monitoring and control of generation, storage, and load assets.
- Monitoring:Telemetry visualization and alarm management for control center operators.
Grid Optimization leads application spending. Fault Detection is gaining share fastest as extreme weather events harden utility reliability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment tax credits under the U.S. Inflation Reduction Act are channeling capital toward grid modernization clusters, concentrating software procurement in jurisdictions with the strongest policy tailwinds.
United States
IRA funding accelerates utility replacement of legacy SCADA with cloud-native platforms. FERC Order 2222 compliance mandates drive procurement of advanced distribution management systems at investor-owned utilities. Texas and California renewable-rich corridors exhibit concentrated demand for bi-directional power flow management software.
Germany
Energiewende reliability mandates force distribution system operators to deploy predictive analytics for variable renewable absorption. The EU F-Gas Regulation constrains data center cooling choices for cloud-hosted platforms. Municipal utilities in Bavaria and North Rhine-Westphalia now unbundle software procurement from hardware supply agreements.
India
CEA-mandated communication protocol standards determine vendor eligibility for national smart grid pilots. Mid-sized municipal utilities favor cloud deployment to circumvent legacy integration burdens. Maharashtra and Gujarat distribution companies lead procurement volumes under state-level smart grid initiatives.
China
Dual carbon goals accelerate deployment of AI-integrated grid optimization platforms at provincial grid operators. MIIT standards govern industrial data security requirements for control system software. Yangtze River Delta utilities concentrate investment in digital twin technology for transmission asset management.
Japan
METI grid flexibility incentives drive demand response platform deployment to manage post-Fukushima generation mix challenges. JIS standards constrain foreign vendor participation in critical infrastructure procurement. Kansai region utilities lead adoption of automated switching systems for earthquake resilience.
Smart Grid Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated automation vendors historically controlling software decisions through hardware bundling. The vendor base spans three tiers: diversified industrial conglomerates with deep utility relationships, pure-play software specialists competing on analytics capabilities, and communications infrastructure providers securing the network layer. Consolidation pressure intensifies as cloud-native delivery models compress margins and force legacy perpetual-license vendors toward recurring-revenue restructuring. Dominant competitive moves include strategic partnerships between software specialists and cloud hyperscalers, plus geographic expansion through sovereign cloud instances to satisfy data residency mandates.
Within the diversified industrial tier, Siemens AG and ABB Ltd. anchor European utility relationships through combined hardware-software offerings. IBM Corporation and Oracle Corporation occupy positions as enterprise software incumbents leveraging AI and database infrastructure for grid analytics penetration. Cisco Systems, Inc. exemplifies the communications-specialist archetype, securing substation-to-control-center connectivity layers that underpin software platform performance.
| Leading Market Players |
|---|
| Siemens AG |
| IBM Corporation |
| Cisco Systems, Inc. |
| Schneider Electric SE |
| ABB Ltd. |
| General Electric Company |
| Itron, Inc. |
| Honeywell International Inc. |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up software specialists have consolidated mid-tier analytics vendors across Germany and the United States, compressing supplier diversity while imposing subscription-pricing discipline that favors recurring revenue over perpetual licenses. This ownership concentration tightens pricing power at the platform layer while fragmenting negotiation leverage for municipal utilities locked into multi-year SaaS contracts.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply for utilities requiring sub-quarter deployment of fault-location modules, while spot inventory of standardized API connectors trades at modest discounts. The dominant pricing structure spans three-tier subscription levels across premium analytics, standard network management, and economy monitoring tiers, with differentiation driven by NERC CIP certification grade and geographic data residency compliance. Cost compression in the economy tier is intensifying because Indian municipal utilities are aggregating procurement through state-level smart grid consortiums. Investor-owned utilities in Texas and California exhibit the lowest price sensitivity due to IRA-funded modernization budgets, while German municipal operators under Energiewende mandates face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Dallas, and Singapore anchor hub-and-spoke fulfillment patterns for cloud infrastructure hardware and edge computing nodes deployed at substations. Software development concentrates in Germany, the United States, and India, with Indian centers handling substantial analytics engineering for cost-sensitive deployments. The supply chain draws from Taiwanese semiconductor foundries for edge processors, German industrial automation components, and U.S.-origin cybersecurity modules. Single-source vulnerability in Taiwanese chip fabrication creates exposure for substation router deployments. Distribution runs through systems integrators and direct enterprise sales teams, with hyperscaler marketplaces gaining share for mid-sized utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart grid software market sits in a technology-transition phase where cloud-native architectures are systematically displacing legacy SCADA systems that utilities have operated for decades. This replacement cycle creates asymmetric opportunities across vendor tiers and utility segments.
For Market Incumbents: Lock in long-term platform contracts with investor-owned utilities before IRA funding windows narrow, while acquiring specialized AI-weather forecasting boutiques to defend against pure-play analytics entrants. The threat of cloud-native challengers offering usage-based pricing demands preemptive certification investment in sovereign cloud instances for European data residency compliance. Vertical integration into edge hardware production secures margin pools that software-only competitors cannot access.
For New Entrants and Emerging Players: The Inflation Reduction Act in the United States opens a window for SaaS-native vendors to penetrate mid-sized municipal utilities that legacy incumbents have underserved. White-space targets include predictive maintenance modules for aging transformer fleets and demand response platforms for Texas industrial microgrids. The most penetrable segment comprises Indian municipal utilities participating in CEA-mandated smart grid pilots, where cloud deployment circumvents legacy integration burdens. A channel partnership with regional systems integrators accelerates credibility building without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play analytics specialists with established NERC CIP certification in North America, where regulatory compliance creates durable moats. Long-term viability hinges on recurring revenue share exceeding seventy percent and demonstrated success in sovereign cloud deployments. The signal to watch is utility RFP unbundling patterns in Germany, where separate procurement of software and hardware indicates sustained vendor displacement opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Deployment | EU GDPR and F-Gas Regulation compliance secures German municipal utility contracts against U.S. hyperscaler competition. |
| AI-Weather Platform Integration | METI incentives in Japan and IRA funding in the United States accelerate predictive load forecasting adoption. |
| NERC CIP Certification Investment | Compliance timelines extend sales cycles but create exclusionary barriers for uncertified competitors in North America. |
| Mid-Sized Utility Channel Partnership | Systems integrator alliances bypass direct sales costs for municipal procurement committees with constrained technical staff. |
| Digital Twin Technology Licensing | Yangtze River Delta utilities in China concentrate investment in transmission asset virtualization for maintenance optimization. |
Research Methodology
Document review covered FERC orders, EU regulatory filings, and CEA smart grid pilot documentation, complemented by interviews with utility planning officers, grid operations directors, software procurement leads, and hyperscaler platform engineers. Secondary validation drew from EIA grid modernization data, IEA renewable integration reports, and utility capital expenditure disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing derived from vendor revenue disclosures and public procurement databases.
Output projections span the analysis window across solution type, deployment architecture, utility ownership structure, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves incorporating policy funding trajectories, renewable penetration rates, and legacy system replacement cycles. Forecast inputs included FERC Order 2222 compliance timelines, Energiewende mandate implementation schedules, and Indian smart grid pilot expansion patterns.
Caveats apply where NERC CIP rule revisions, EU data sovereignty enforcement shifts, or hyperscaler market entry strategies could materially shift the outlook. Forecasts reflect documented assumptions about policy continuity and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Solar Digitalization Platform Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Carbon and Energy Software Market