
 Solar Analyzer Market | 2026-2036
Solar Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Analyzer Market Analytics
Aftermarket service revenue is fragmenting across calibration, recertification, and remote diagnostics as photovoltaic fleet ages expand. Seaward leverages its coastal UK manufacturing base to sustain European channel dominance in electrical safety testers. Megger anchors its position through deep utility relationships and high-voltage insulation testing heritage. EmaZys ApS competes via specialized impedance spectroscopy modules for string-level fault isolation.
A solar analyzer measures photovoltaic system electrical parameters including current-voltage curves, insulation resistance, and spectral irradiance to verify performance and identify degradation. Handheld units dominate residential and commercial rooftop segments where technician mobility matters, while stationary architectures capture utility-scale monitoring contracts with continuous data logging requirements. Thermal imaging integration represents the fastest-growing technology segment as operators prioritize predictive maintenance over reactive fault response.
IEC 62446, the US National Electrical Code Article 690, and Germany's VDE-AR-E 2100-712 collectively mandate periodic verification of PV system safety and performance, directly stimulating replacement demand for certified test equipment. China's GB/T 9535 and evolving grid interconnection standards from the National Energy Administration further tighten product compliance requirements for equipment sold domestically. Stakeholders must track evolving certification reciprocity between IEC frameworks and national deviations to anticipate market access barriers and service revenue migration toward firmware-upgradable analyzer platforms.
Market Dynamics
The solar analyzer market is being fundamentally restructured by the transition from reactive maintenance to predictive analytics, as utility-scale operators demand continuous performance telemetry rather than periodic manual testing.
Growth Catalysts
- String-level monitoring mandates:Germany's VDE-AR-E 2100-712 and IEC 62446 require granular fault detection, compelling operators to deploy distributed impedance spectroscopy across large photovoltaic fleets.
- Utility-scale capacity expansion:China's National Energy Administration interconnection standards enforce rigorous commissioning protocols, creating sustained equipment refresh cycles for grid-connected solar farms.
- Thermal imaging convergence:The integration of infrared cameras with electrical parameter analyzers enables single-technician diagnostic workflows, reducing labor costs for commercial rooftop maintenance.
Market Restraints
- Sensor calibration dependency:Precision irradiance sensors require annual recertification against NIST-traceable standards, creating recurring cost burdens for distributed operators.
- High-voltage insulation tester concentration:Production of megohm-range test equipment concentrates among legacy European electrical safety specialists, limiting supply chain flexibility.
- Silicon photodiode spectral limitations:Conventional reference cells exhibit wavelength-dependent degradation under UV exposure, constraining measurement accuracy for bifacial module characterization.
Strategic Opportunities
- India's distributed solar mandate:The country's PLI scheme for solar manufacturing is creating demand for localized test equipment calibration infrastructure.
- Firmware-upgradable platforms:Cloud-connected analyzers with over-the-air protocol updates capture recurring revenue streams as grid codes evolve.
- Drone-mounted thermal inspection:Aerial thermography integration opens utility-scale predictive maintenance contracts beyond handheld device limitations.
Industry Challenges
- Certification timeline compression:IEC 62446-1:2016 edition updates require test equipment recertification within 18-month windows, straining manufacturer validation resources.
- Legacy data system integration:Stationary monitoring architectures must interface with decades-old SCADA protocols, complicating deployment in retrofitted solar farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Analyzer Market |
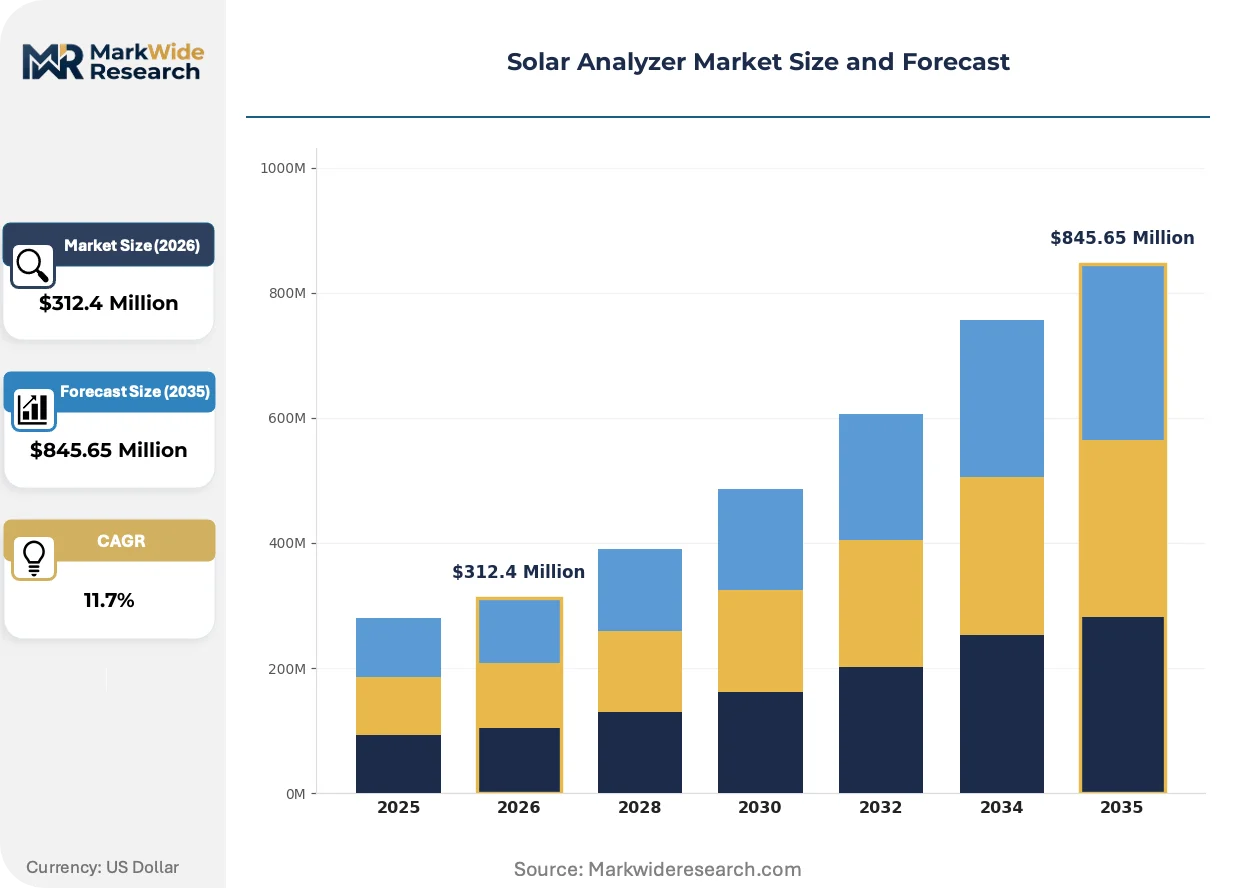
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Stationary, Portable, Fixed Technology: Thermal, Photovoltaic, Electrical, Optical End User: Utilities, Residential, Commercial, Industrial Application: Performance Monitoring, Fault Detection, System Diagnosis, Energy Auditing |
| Companies Covered | Meco Instruments Pvt. Ltd., Solmetric, Inc., Seaward, Solar Light Company, Inc., EmaZys ApS, HT Italia, Megger, Amprobe, Aplab Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Analyzer Market Evolving Landscape
Diagnostic technology in photovoltaic systems is pivoting toward autonomous, continuously-connected architectures that eliminate scheduled manual intervention. This shift is compressing the traditional divide between portable field equipment and permanent monitoring infrastructure.
Spectral response measurement is migrating from laboratory-grade monochromator systems to compact LED-array simulators. Commercial EPC contractors now specify these units for rapid binning of high-volume module shipments. The technology is migrating from quality-control laboratories to containerized field stations at utility-scale project sites.
The US Inflation Reduction Act's domestic content bonus credits are reshaping equipment sourcing patterns. Manufacturers must now certify that test instruments used in qualifying projects meet Buy America assembly thresholds. Domestic inverter producers are responding by vertically integrating analyzer procurement into their commissioning service offerings.
Service unbundling is fragmenting traditional equipment sales. Operators now procure calibration subscriptions separately from hardware, with remote diagnostics delivered through cellular-connected firmware. This pattern is most pronounced in Germany, where aging rooftop fleets generate recurring revenue for predictive maintenance platforms.
Solar Analyzer Market Segmentation
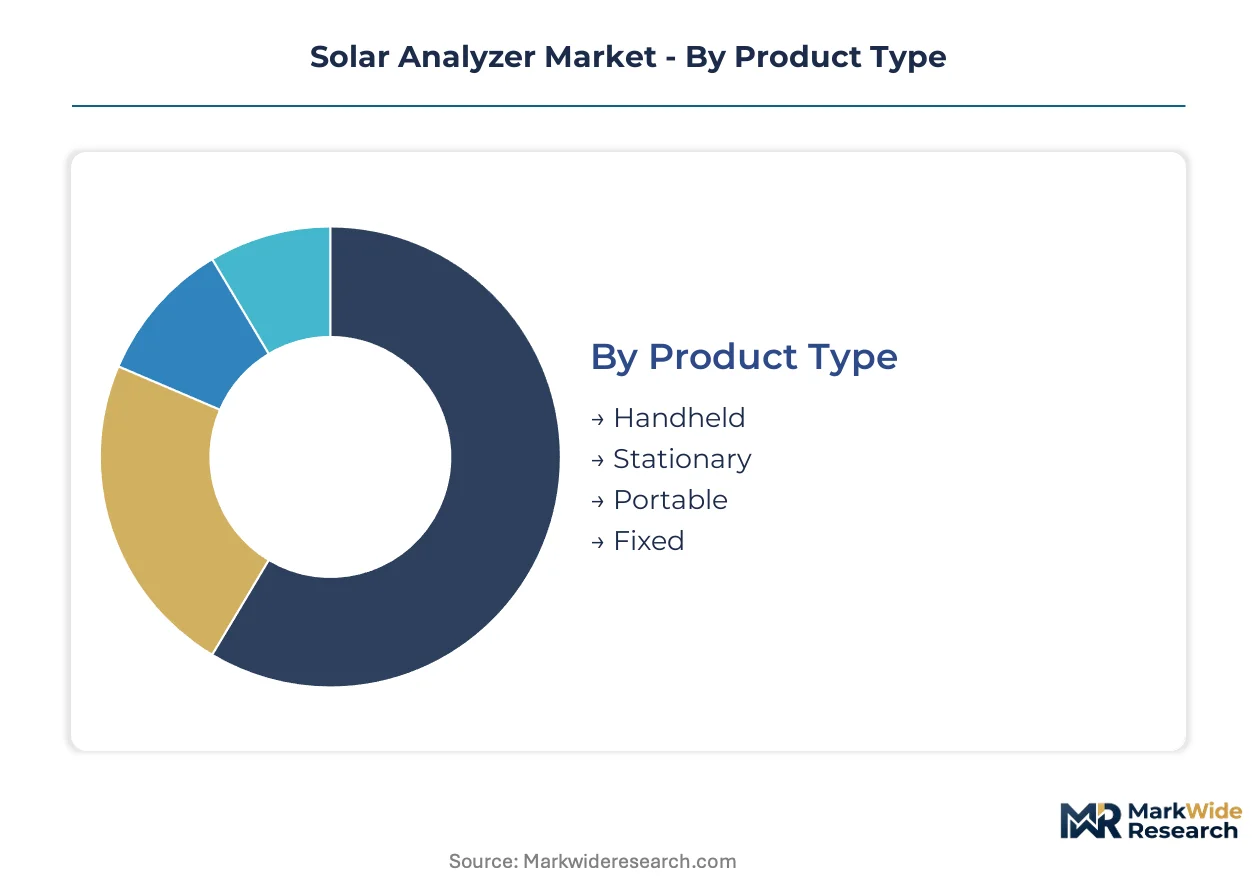
Segmentation in the solar analyzer market reflects divergent equipment requirements across deployment scales and regulatory environments. Product architecture, sensing technology, and end-use application each create distinct procurement patterns that manufacturers must address through specialized feature sets.
Product Type:
Mature form factors dominate utility procurement cycles, while emerging configurations capture distributed solar growth.
- Handheld:Battery-powered units with integrated irradiance sensors and Bluetooth data export enable single-technician rooftop commissioning workflows. Residential and commercial EPC contractors in Germany and the United States concentrate procurement here, driven by VDE-AR-E 2100-712 and NEC Article 690 compliance mandates for periodic verification.
- Stationary:Rack-mounted architectures with continuous Ethernet logging and API connectivity serve utility-scale fleet operators transitioning to predictive maintenance models. China's National Energy Administration interconnection standards enforce rigorous data retention protocols that favor these installations.
- Portable:Transit cases with modular sensor arrays bridge field and laboratory environments for module shipment inspection.
- Fixed:Weather-hardened enclosures with direct SCADA integration target retrofitted solar farms requiring legacy protocol compatibility.
Stationary architectures handle the majority of throughput; handheld units are gaining share fastest among distributed fleet operators.
Technology:
Cost tier differentiation separates premium sensing modalities from standardized electrical measurement cores.
- Thermal:Infrared focal plane arrays with radiometric calibration enable hot-spot detection before power degradation manifests. Drone-mounted deployments for utility-scale predictive maintenance contracts in the United States are accelerating procurement, supported by IRA domestic content bonus credit eligibility requirements.
- Photovoltaic:Silicon photodiode reference cells with spectral mismatch correction provide irradiance normalization for I-V curve tracing. IEC 62446 certification requirements sustain replacement demand across European rooftop fleets.
- Electrical:Four-wire resistance measurement and high-voltage insulation testing form the baseline specification for safety verification.
- Optical:LED-array spectral simulators enable rapid binning of bifacial modules without laboratory monochromator infrastructure.
Electrical measurement cores handle the majority of throughput; thermal imaging is climbing the fastest on share expansion.
End User:
Customer type determines service bundling preferences and calibration frequency obligations.
- Utilities:Centralized procurement departments favor firmware-upgradable platforms with cellular connectivity for over-the-air protocol updates as grid codes evolve. China's state-owned power generators anchor volume concentration through standardized commissioning protocols.
- Residential:Homeowner-driven purchases concentrate in rooftop-saturated markets where aging systems require fault isolation services. Germany's service unbundling trend fragments traditional equipment sales into separate calibration subscriptions.
- Commercial:Facility managers prioritize single-technician diagnostic workflows that reduce labor costs for multi-site portfolio maintenance.
- Industrial:Cogeneration facility operators integrate solar analyzers with existing electrical maintenance programs for captive power assets.
Utilities handle the majority of throughput; commercial segment procurement is expanding most quickly on distributed solar mandate acceleration.
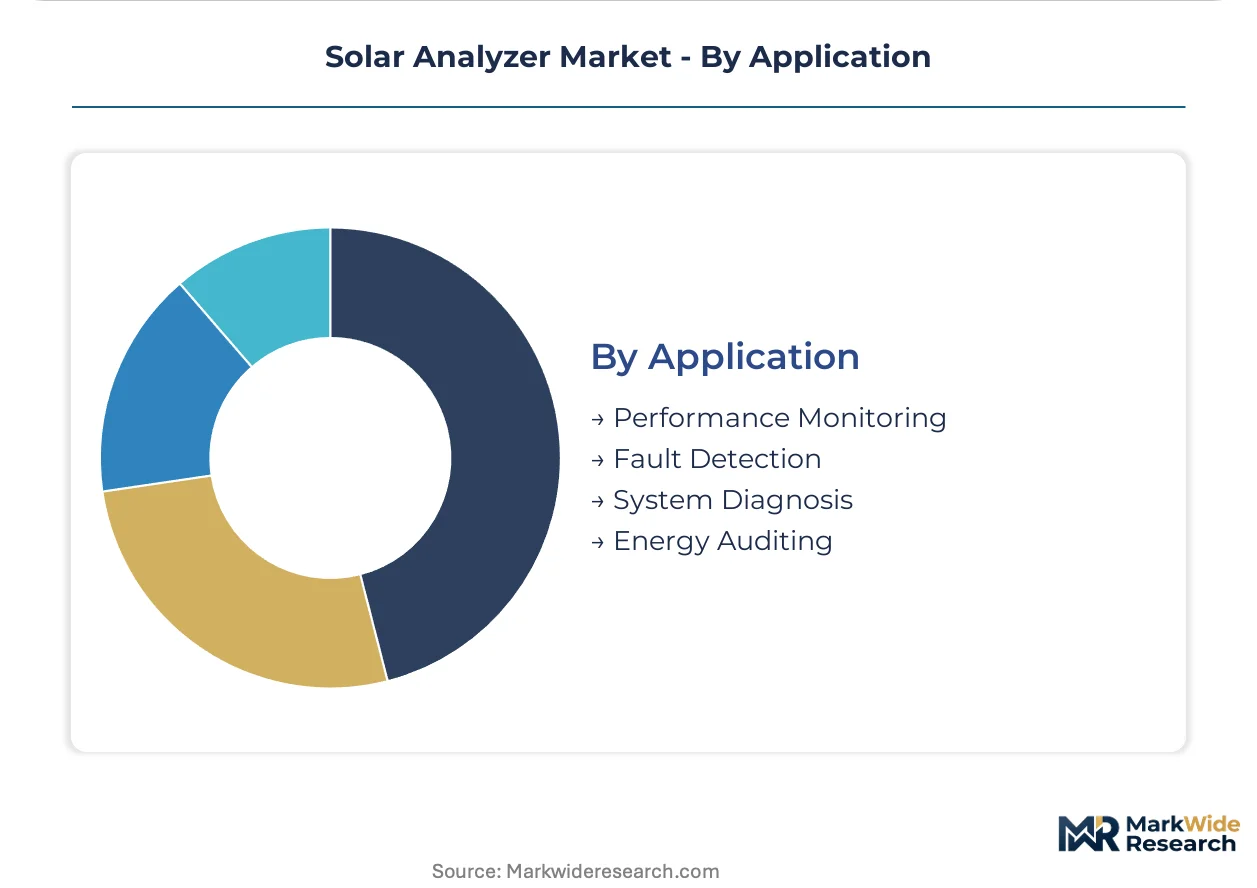
Application:
Volume concentration sits with compliance-driven verification, while margin expansion follows predictive service models.
- Performance Monitoring:Continuous telemetry architectures with cloud dashboards and automated alerting replace periodic manual testing for utility-scale operators. China's grid interconnection standards enforce sustained equipment refresh cycles through rigorous commissioning protocols.
- Fault Detection:String-level impedance spectroscopy identifies degradation before power output collapses, mandated by Germany's VDE-AR-E 2100-712 for granular fleet visibility.
- System Diagnosis:Root-cause analysis workflows combine electrical, thermal, and optical measurements for warranty claim documentation.
- Energy Auditing:Pre-installation site assessment and production forecasting support financing due diligence for commercial rooftop projects.
Performance monitoring handles the majority of throughput; fault detection is the fastest mover on share as predictive maintenance displaces reactive response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys stationary analyzers for continuous utility-scale telemetry, while Germany fragments procurement across handheld units for aging rooftop fleets and the United States accelerates drone-thermal integration for predictive maintenance contracts.
China
State-owned power generators anchor volume concentration through standardized commissioning protocols. The National Energy Administration enforces rigorous grid interconnection standards that mandate sustained equipment refresh cycles. Yangtze River Delta manufacturing clusters supply modular analyzer platforms for domestic solar farm deployment.
Germany
Aging rooftop photovoltaic fleets generate recurring calibration subscription demand among residential operators. VDE-AR-E 2100-712 mandates string-level impedance spectroscopy for granular fault detection across distributed installations. Bavarian technical service providers unbundle hardware sales from predictive maintenance software contracts.
United States
Utility-scale operators prioritize thermal imaging convergence for single-technician diagnostic workflows. The Inflation Reduction Act's domestic content bonus credits reshape equipment sourcing toward Buy America-compliant assembly. California solar EPC contractors specify LED-array spectral simulators for rapid module binning at project sites.
India
The Production Linked Incentive scheme for solar manufacturing creates demand for localized test equipment calibration infrastructure. The Central Electricity Authority mandates periodic system verification for grid-connected installations. Gujarat and Rajasthan solar parks drive procurement of portable analyzers for module shipment inspection.
Japan
Commercial facility managers integrate solar analyzers with existing electrical maintenance programs for captive power assets. METI's evolving grid codes require firmware-upgradable platforms with over-the-air protocol update capability. Kansai region industrial cogeneration sites deploy stationary architectures with direct SCADA integration.
Solar Analyzer Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Electrical safety specialists with high-voltage insulation testing heritage dominate megohm-range equipment production. Three archetypes populate the field: coastal European manufacturers leveraging channel density, utility-relationship incumbents with commissioning service integration, and impedance spectroscopy specialists targeting string-level diagnostics. Competitive moves center on firmware-upgradable platform development and predictive maintenance service unbundling.
Within the heritage electrical safety tier, Seaward occupies a position exemplifying European channel dominance through coastal UK manufacturing. Megger represents the utility-relationship archetype, anchoring scale advantage through deep infrastructure operator partnerships. EmaZys ApS sits within the specialized diagnostics segment, exemplifying impedance spectroscopy capability for distributed fault isolation.
| Leading Market Players |
|---|
| Meco Instruments Pvt. Ltd. |
| Solmetric, Inc. |
| Seaward |
| Solar Light Company, Inc. |
| EmaZys ApS |
| HT Italia |
| Megger |
| Amprobe |
| Aplab Limited |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta manufacturing clusters anchor global analyzer platform production, translating concentrated component sourcing into tiered pricing power across handheld and stationary architectures. Contract structures segment procurement between long-term utility offtake agreements and spot-market transactions for distributed rooftop operators.
Pricing Analysis
Long-term offtake contracts dominate utility-scale stationary analyzer procurement, while spot and project-based pricing governs commercial EPC contractor purchases. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62446-certified units with NIST-traceable calibration from uncertified economy imports. Pricing pressure stems from India's PLI-driven localization mandates compressing import-dependent margins. Commercial facility managers exhibit highest price sensitivity; state-owned utilities show lowest.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta electronics assemblers and Bavarian precision sensor foundries. Silicon photodiode reference cells and infrared focal plane arrays draw from Taiwan and Japan; high-voltage insulation test components rest on German specialty production. Single-source vulnerability concentrates in NIST-traceable irradiance sensor calibration. Distribution runs through authorized electrical safety distributors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar analyzer penetration sits at early-cycle expansion as utility-scale capacity buildouts accelerate predictive maintenance adoption. String-level monitoring mandates across Germany, China, and the United States create sustained equipment refresh demand.
For Market Incumbents: Build firmware-upgradable platform moats to capture recurring revenue as grid codes evolve. Deepen calibration service infrastructure in India and the United States to defend against emerging local assemblers. Anchor utility relationships through commissioning service bundling that locks out standalone hardware competitors.
For New Entrants and Emerging Players: Pursue drone-mounted thermal inspection white space in utility-scale predictive maintenance contracts. Target India's distributed solar calibration infrastructure gap with localized service partnerships. Penetrate Germany's aging rooftop fleet segment through unbundled software subscriptions rather than hardware sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors impedance spectroscopy specialists with string-level diagnostic IP. Long-term viability hinges on protocol adaptability across evolving IEC and national grid standards. Watch for inflection in cellular-connected firmware upgrade attach rates as predictive maintenance displaces reactive service models.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Upgradeable Platform Development | Captures recurring revenue from China's National Energy Administration protocol updates. |
| Drone-Mounted Thermal Integration | Opens utility-scale contracts beyond handheld device physical limitations in the United States. |
| Localized Calibration Infrastructure | Meets India's PLI scheme domestic content thresholds for solar manufacturing test equipment. |
| Impedance Spectroscopy Module Specialization | Addresses Germany's VDE-AR-E 2100-712 string-level fault detection mandates. |
| SCADA Protocol Backward Compatibility | Enables stationary architecture deployment in retrofitted solar farms with legacy infrastructure. |
Research Methodology
Operator-level perspectives from utility planning officers, EPC contractors, solar farm maintenance directors, and calibration service technicians anchored the qualitative base. Primary interviews combined with secondary validation from IEC certification databases, National Energy Administration grid interconnection filings, and FERC utility procurement records. Bottom-up equipment shipment analysis triangulated against top-down solar capacity installation data across the analysis window.
Scenario-bracketing framed volume and value outputs across product architecture, sensing technology, end-use application, and regional regulatory cluster dimensions. CAGRs derived from equipment refresh cycle modeling tied to commissioning protocol mandates. Forecast inputs incorporated bifacial module adoption curves and thermal imaging convergence rates.
Sensitivities concentrate around IEC 62446-1 revision timelines and India PLI localization enforcement intensity. Forecasts reflect documented assumptions on utility-scale capacity expansion trajectories and rooftop fleet aging patterns. Quarterly review of cellular-connected analyzer attach rates and drone-thermal contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Digitalization Platform Market
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Power System Analysis Software Market