
 Saas-Based Expense Management Market | 2026-2036
Saas-Based Expense Management Market Size, Share, and Industry Trends Forecast 2026-2036
Saas-Based Expense Management Market Analytics
Asset-light subscription financing is narrowing the competitive field for new entrants in SaaS-based expense management. SAP Concur leverages its embedded ERP partnerships to sustain renewal rates across multinational accounts. Expensify competes through mobile-first architecture that dominates the self-serve segment. Oracle Corporation anchors its position through captive database integration that extends workflow stickiness.
SaaS-based expense management denotes cloud-hosted software that automates receipt capture, policy enforcement, reimbursement routing, and general-ledger reconciliation through multi-tenant architecture with API connectivity to corporate card networks and accounting systems. Its primary commercial purpose is to replace manual spreadsheet-based processes with real-time spend visibility and automated compliance checks. Expense tracking solutions lead by volume as the entry point for first-time buyers, while ERP integration commands premium pricing due to implementation complexity and data security requirements. Public cloud deployment dominates new subscriptions, though hybrid configurations are gaining traction among financial services buyers with segmented data sovereignty needs.
The EU AI Act, GDPR, and CSRD collectively shape product roadmaps by mandating algorithmic transparency in automated expense auditing and granular carbon reporting for business travel. The US SEC climate disclosure rules and HIPAA provisions for healthcare employee reimbursements create parallel compliance obligations that vendors must address through configurable policy engines. Stakeholders should monitor how regulatory fragmentation between jurisdictions affects single-platform standardization strategies.
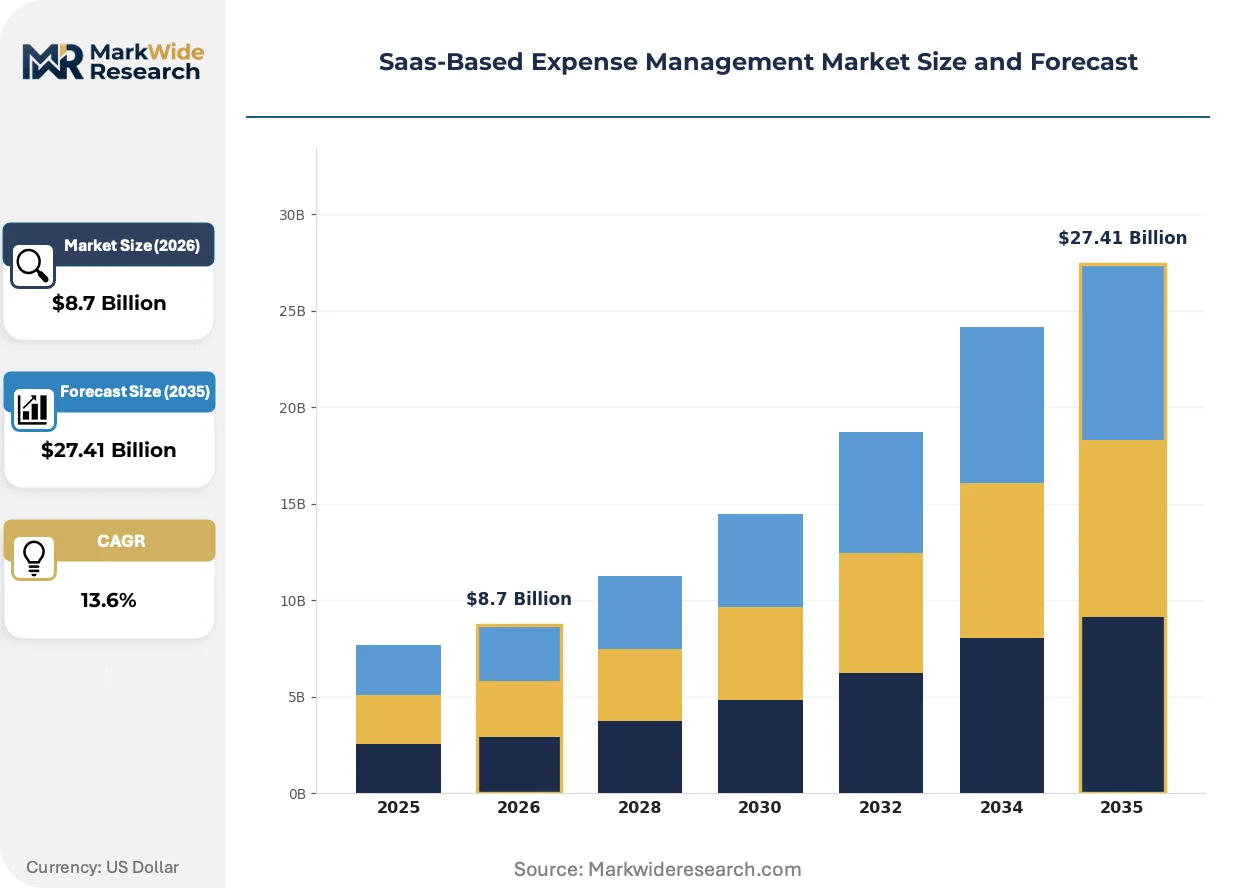
Market Dynamics
Mid-market enterprises are accelerating cloud migration, compressing procurement cycles from twelve-month ERP implementations to thirty-day self-serve deployments. This shift is collapsing the traditional enterprise sales motion and forcing vendors to rearchitect onboarding workflows.
Growth Catalysts
- EU AI Act compliance mandates:Automated expense auditing systems must now embed algorithmic transparency and human-in-the-loop review protocols, creating replacement demand for legacy rule-based engines across financial services and healthcare verticals.
- Real-time payment infrastructure:Instant reimbursement rails through corporate card networks are eliminating float-based business models and converting holdout enterprises that previously cited cash-flow friction as adoption barrier.
- Germany's Mittelstand digitization:Family-owned engineering and manufacturing clusters are replacing paper-based expense processes with mobile-first platforms to satisfy supply-chain ESG documentation requirements from automotive OEM customers.
Market Restraints
- Input cost concentration:Cloud compute and API gateway pricing from hyperscalers in Ireland and Frankfurt regions creates margin pressure independent of vendor pricing power.
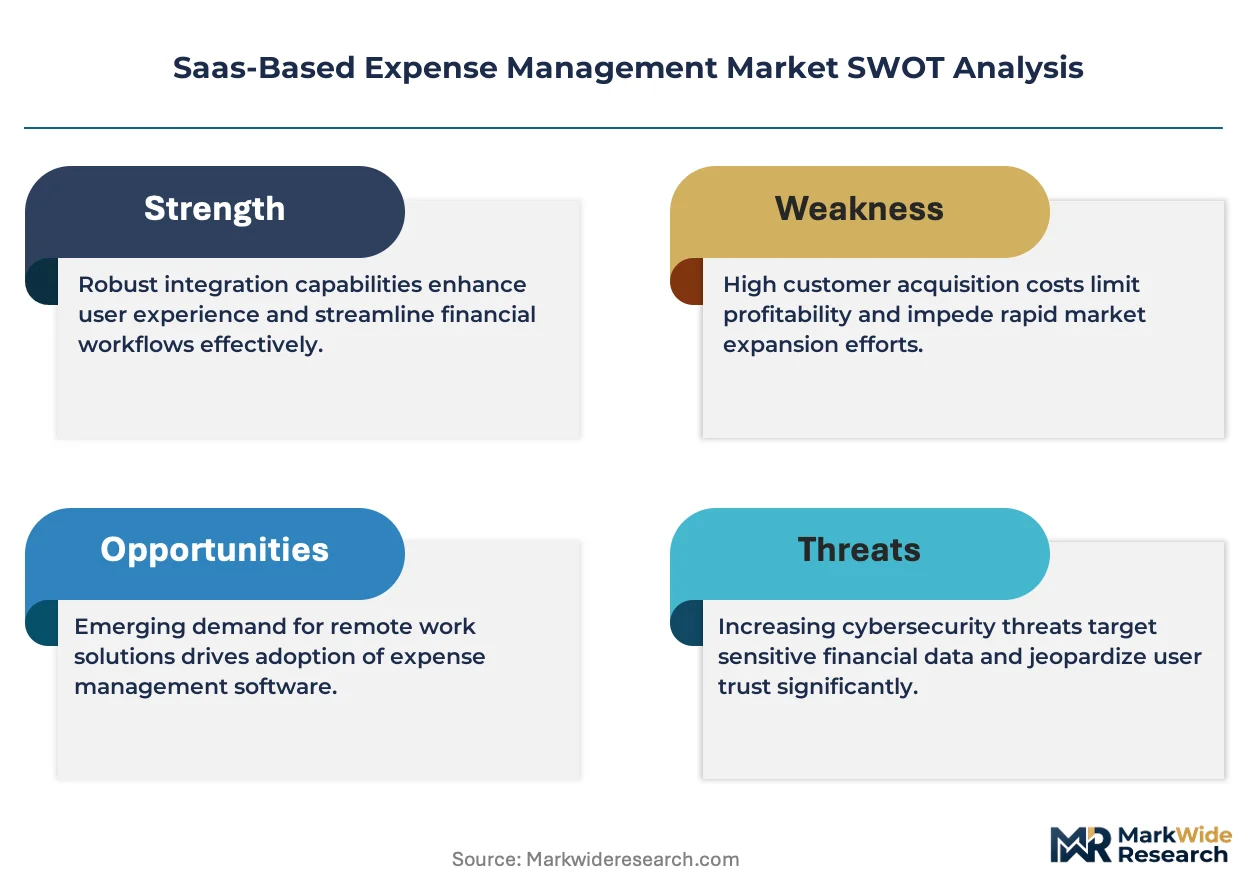
- Substitution by embedded ERP modules:SAP and Oracle are bundling expense workflows at marginal cost into existing enterprise licenses, compressing standalone vendor addressable market in accounts above five thousand employees.
- GDPR data-localization friction:Multi-tenant architectures face architectural constraints when serving financial services buyers with segmented data sovereignty requirements, forcing costly hybrid deployments.
Strategic Opportunities
- Carbon reporting automation:CSRD-mandated Scope 3 emissions disclosure for business travel creates attach-rate expansion for vendors that integrate flight and hotel carbon calculators directly into reimbursement workflows.
- Healthcare reimbursement specialization:HIPAA-compliant platforms for clinician expense capture remain underpenetrated in the United States, with most hospitals still processing physician travel through manual accounts-payable queues.
- Convergence of spend management and corporate cards:API-native platforms that embed issuance and policy enforcement in a single interface are displacing the traditional separation between software and banking relationships.
Industry Challenges
- Legacy ERP integration complexity:Custom general-ledger mapping for decades-old on-premise accounting systems consumes forty percent of implementation professional services hours and drives customer churn at renewal.
- AI audit model certification delays:Vendor algorithms for automated receipt classification and fraud detection lack standardized validation frameworks, forcing repeated documentation cycles with national regulators in France and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saas-Based Expense Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Expense Tracking, Invoice Management, Budgeting Tools, Reporting Software End User: SMEs, Large Enterprises, Non-Profit Organizations, Government Agencies Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Integration Level: API Integration, Third-Party Integrations, Custom Solutions, ERP Integration |
| Companies Covered | SAP Concur, Oracle Corporation, IBM Corporation, Expensify, Coupa Software, Zoho Corporation, Emburse, Apptricity Corporation, Infor Global Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saas-Based Expense Management Market Evolving Landscape
Expense management platforms are converging with adjacent financial infrastructure, eroding the historical boundary between software and payment services. This integration is compressing vendor margins while expanding total addressable transaction volume.
Optical character recognition combined with large language models is collapsing the manual data-entry bottleneck that previously consumed eighty percent of expense report preparation time. Mid-market finance teams are adopting these tools within thirty-day implementation windows, bypassing traditional IT procurement gates. The structural consequence is a shift from seat-based subscription pricing toward transaction-volume monetization models.
The EU AI Act's algorithmic transparency requirements are forcing vendors to document training data provenance and decision-logic interpretability for automated expense auditing. Industrial consequence includes mandatory human review queues for flagged transactions exceeding defined thresholds. Financial services buyers in Germany and the Netherlands are demanding pre-certified compliance documentation before contract execution.
Self-serve procurement through product-led growth channels is displacing the traditional enterprise sales-led motion in companies below five hundred employees. Finance operations leaders are discovering and adopting platforms through peer referrals rather than RFP processes, compressing vendor customer-acquisition costs but elevating churn risk. This pattern is most visible in technology and professional services verticals across the United Kingdom and Ireland.
Saas-Based Expense Management Market Segmentation
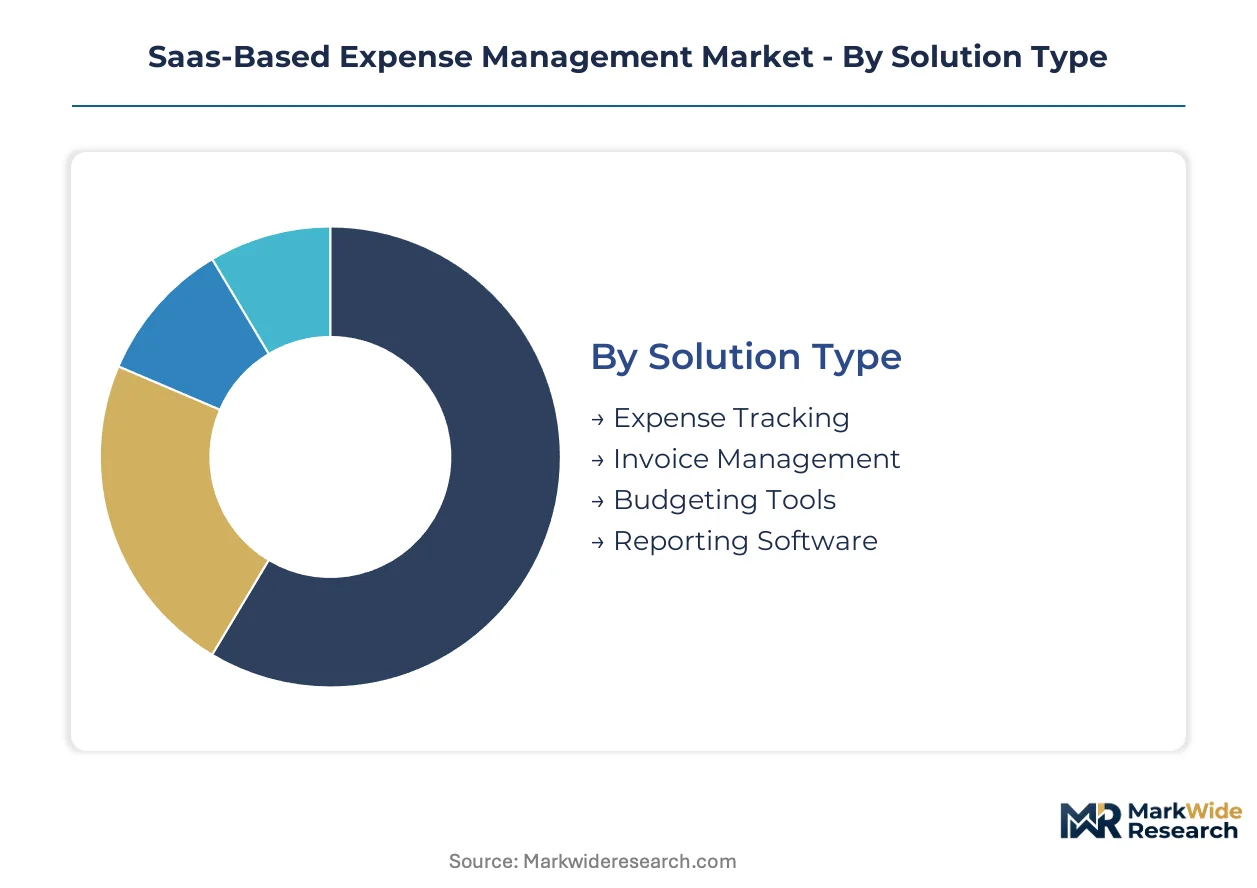
Segmentation in SaaS-based expense management reveals how procurement patterns diverge across technical maturity, compliance requirements, and integration complexity. Vendors must architect distinct service models for each slice, as implementation support demands vary dramatically from self-serve mobile deployments to multi-system ERP consolidations.
Solution Type:
After-sales service intensity peaks with solutions requiring continuous policy calibration and regulatory re-certification, particularly where automated auditing triggers ongoing algorithmic validation cycles.
- Expense Tracking:Mobile-first platforms with optical character recognition and receipt capture dominate first-time buyer adoption. Demand concentrates among UK and German mid-market technology firms replacing spreadsheet workflows, driven by EU AI Act compliance deadlines for automated audit trails.
- Invoice Management:Accounts-payable automation with three-way matching and vendor onboarding portals commands premium implementation services. French manufacturing clusters and Dutch logistics operators prioritize these tools to satisfy CSRD-mandated supply chain documentation requirements.
- Budgeting Tools:Real-time spend controls with departmental allocation alerts.
- Reporting Software:Carbon footprint calculators and ESG disclosure dashboards.
By volume, Expense Tracking leads. By growth pace, Reporting Software is expanding most quickly.
End User:
Cost tier segmentation separates high-touch enterprise deployments from low-friction self-serve segments, with professional services margins compressing at the lower end.
- SMEs:Cloud-native platforms with thirty-day implementation windows and peer-referral discovery channels. Irish professional services firms and UK technology startups drive adoption, motivated by HMRC Making Tax Digital compliance and cash-flow visibility needs.
- Large Enterprises:Multi-entity deployments with custom general-ledger mapping and segmented data sovereignty. German automotive suppliers and French banking groups require these configurations to satisfy GDPR localization mandates and BaFin regulatory scrutiny.
- Non-Profit Organizations:Grant-compliant expense routing with donor-restricted fund tracking.
- Government Agencies:Public procurement integration with audit-trail preservation.
SMEs generate the highest transaction velocity. Large Enterprises deliver the steepest revenue per seat.
Deployment Model:
Volume concentration favors public cloud architectures, though margin structures improve where hybrid configurations address data sovereignty constraints.
- Public Cloud:Multi-tenant SaaS with API connectivity to corporate card networks and accounting systems. Netherlands fintech clusters and Scandinavian professional services firms favor this model for rapid scaling without infrastructure overhead.
- Hybrid Cloud:Segmented architectures with sensitive data on private nodes and compute on public infrastructure. German financial services buyers in Frankfurt and Munich mandate these deployments to reconcile BaFin supervision with cloud agility.
- Private Cloud:Single-tenant dedicated instances for defense and intelligence sectors.
- On-Premises:Legacy installations in heavily regulated healthcare and public sectors.
Public Cloud dominates new subscriptions. Hybrid Cloud is climbing the fastest among regulated verticals.
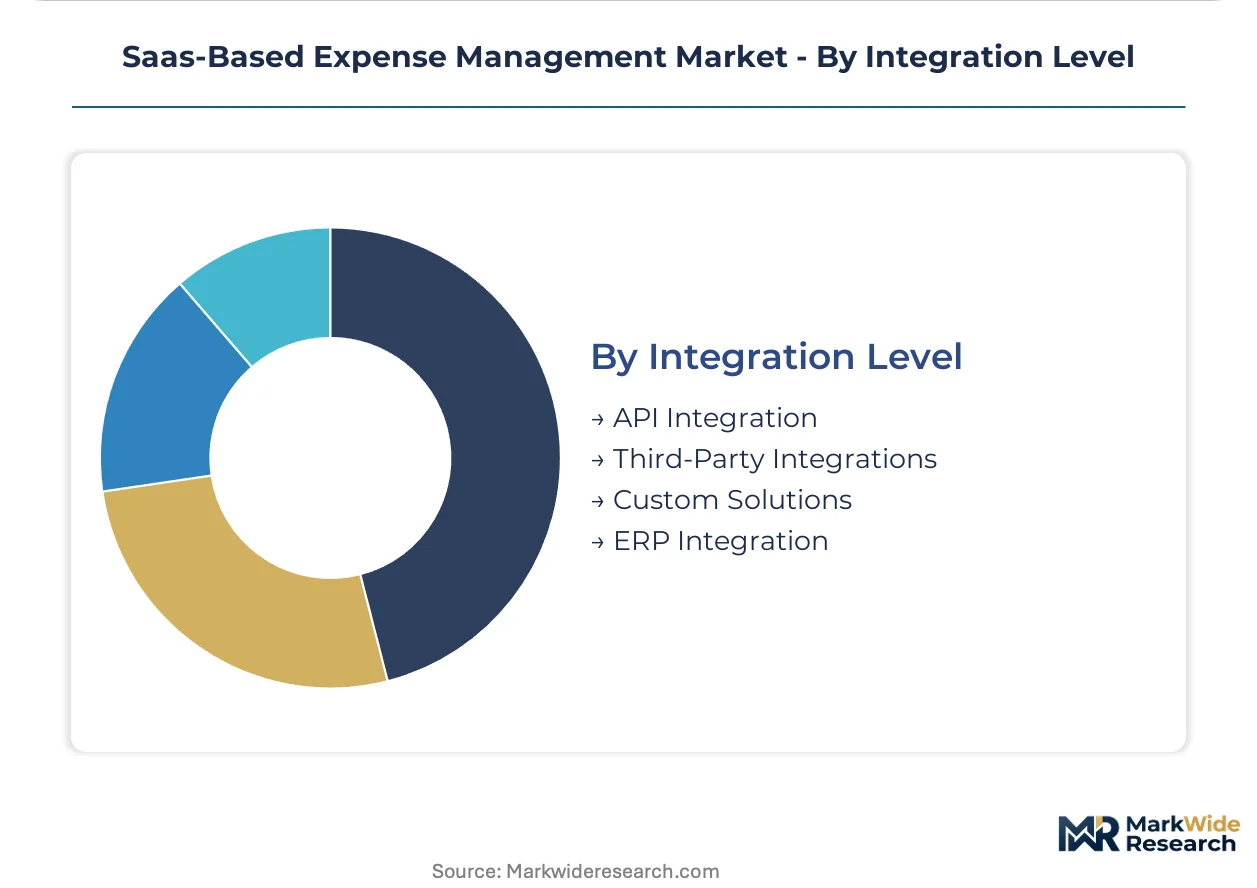
Integration Level:
Customer type segmentation distinguishes plug-and-play buyers from those requiring deep system consolidation, with implementation timelines stretching from days to quarters.
- ERP Integration:Native connectors to SAP, Oracle, and Microsoft Dynamics with custom chart-of-accounts mapping. Multinational manufacturers with decades-old on-premise systems in Germany and Italy require these deployments, though forty percent of professional services hours consume legacy reconciliation work.
- API Integration:RESTful and GraphQL endpoints for bespoke workflow automation. UK technology scale-ups and French insurtech operators prefer this flexibility to embed expense management into proprietary operational platforms.
- Third-Party Integrations:Pre-built connectors to travel booking platforms and corporate card issuers.
- Custom Solutions:Fully engineered deployments for unique regulatory or operational environments.
API Integration captures the highest volume of new deployments. ERP Integration commands the longest contract tenures and renewal rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's algorithmic transparency mandates and GDPR data-localization requirements are reshaping procurement patterns across major economies. Germany's Mittelstand digitization programs and the United Kingdom's HMRC Making Tax Digital compliance deadlines accelerate cloud migration timelines. France's CSRD implementation and Italy's push for supply-chain ESG documentation create parallel demand drivers.
Germany
BaFin supervision requirements and automotive OEM supply-chain audits drive hybrid cloud deployments among Frankfurt financial services firms. The EU AI Act mandates human-in-the-loop review protocols for automated expense auditing systems. Bavarian manufacturing clusters and Baden-Württemberg engineering firms are replacing paper-based processes with mobile-first platforms to satisfy customer ESG documentation requirements.
United Kingdom
HMRC Making Tax Digital deadlines compress implementation windows for mid-market technology firms and professional services operators. GDPR compliance requirements shape data-residency specifications for London-based fintech scale-ups. The Southeast England technology corridor and Manchester financial services hub demonstrate concentrated adoption of API-native expense platforms through peer-referral discovery channels.
France
CSRD-mandated Scope 3 emissions disclosure requirements attach carbon calculators to business travel reimbursement workflows. ANSM and CNIL oversight extends to healthcare employee expense processing in pharmaceutical clusters. Île-de-France insurtech operators and Auvergne-Rhône-Alpes manufacturing groups prioritize invoice management tools with three-way matching capabilities.
United States
SEC climate disclosure rules and HIPAA provisions for healthcare reimbursements create dual compliance obligations for vendors. Real-time payment infrastructure through corporate card networks eliminates float-based adoption barriers. Silicon Valley technology scale-ups and Boston healthcare clusters demonstrate fastest uptake of self-serve procurement channels bypassing traditional RFP processes.
India
RBI guidelines on digital payment infrastructure and SEBI disclosure requirements shape enterprise software procurement in financial services. PLI scheme incentives for technology manufacturing extend to back-office digitization among supplier networks. Karnataka technology corridors and Maharashtra financial services hubs drive API-first platform adoption among domestic scale-ups.
Saas-Based Expense Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that fragments between embedded ERP incumbents and standalone cloud-native platforms. Consolidation pressure intensifies as SAP and Oracle bundle expense workflows at marginal cost into existing enterprise licenses. Three archetypes dominate: ERP-anchored suites, mobile-first self-serve platforms, and API-native spend-management convergers. Competitive moves concentrate on strategic partnerships with corporate card networks and portfolio diversification into carbon reporting automation.
Among ERP-anchored suites, SAP Concur and Oracle Corporation exemplify the channel-control archetype through captive database integration and embedded workflow stickiness. Expensify occupies a position within the mobile-first product-specialist tier, representing the self-serve discovery model that compresses customer-acquisition costs. These three companies illustrate the structural tension between incumbent platform breadth and challenger deployment velocity.
| Leading Market Players |
|---|
| SAP Concur |
| Oracle Corporation |
| IBM Corporation |
| Expensify |
| Coupa Software |
| Zoho Corporation |
| Emburse |
| Apptricity Corporation |
| Infor Global Solutions |
| Others |
Value Network & Pricing Analysis
Hyperscaler cloud infrastructure in Ireland and Frankfurt regions anchors upstream cost structures, concentrating margin pools with AWS, Microsoft Azure, and Google Cloud while compressing downstream vendor profitability across subscription tiers.
Pricing Analysis
Certification level for GDPR, EU AI Act, and HIPAA compliance creates the primary spread between premium and standard tiers. Seat-based subscription models dominate enterprise deployments, while transaction-volume monetization gains traction in mid-market self-serve segments. Pricing pressure stems from hyperscaler API gateway and compute pricing that vendors cannot pass through to buyers. SMEs exhibit highest price sensitivity, driving thirty-day implementation windows and peer-referral discovery, whereas large enterprises prioritize compliance bundling over unit cost.
Supply Chain Analysis
Upstream feedstock for SaaS-based expense management draws from cloud infrastructure provisioning concentrated in Ireland, Germany, and the Netherlands, with secondary dependencies on corporate card network APIs and optical character recognition engines. Critical inputs include multi-tenant architecture frameworks, large language model inference capacity, and regulatory compliance certification services. Single-source vulnerability runs through hyperscaler concentration in Dublin and Frankfurt regions. Distribution runs through direct self-serve channels for mid-market buyers and partner-led enterprise sales for multinational accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity expands as regulatory divergence between EU AI Act, GDPR, and US HIPAA compliance creates specialized vendor niches that generalist platforms cannot address without architectural rewrites.
For Market Incumbents: Pre-empt embedded ERP substitution by SAP and Oracle through deeper API-native spend management convergence and captive corporate card issuance partnerships. Lock in multinational manufacturing accounts with hybrid cloud deployments satisfying BaFin and GDPR data-localization mandates. Prioritize carbon reporting automation attach rates to capture CSRD-driven replacement cycles. For New Entrants and Emerging Players: Build out HIPAA-compliant healthcare reimbursement specialization targeting US hospital systems still processing clinician expenses through manual accounts-payable queues. Capture Germany's Mittelstand engineering clusters with mobile-first platforms satisfying automotive OEM ESG documentation requirements. Lead with product-led growth channels and thirty-day implementation guarantees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across API-native platforms requiring corporate card infrastructure integration and real-time payment rail connectivity. Long-term viability favors vendors with embedded financial services licensing rather than pure software plays. Target acquisition profiles center on mid-market specialists with pre-certified EU AI Act compliance documentation. Monitor algorithmic audit model certification delays with French and German regulators as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Reporting Automation | CSRD-mandated Scope 3 disclosure attaches flight and hotel calculators to reimbursement workflows. |
| API-Native Spend Convergence | Embedded corporate card issuance collapses historical separation between software and banking relationships. |
| Hybrid Cloud Certification | BaFin-supervised financial services buyers in Frankfurt mandate segmented data sovereignty architectures. |
| Healthcare Reimbursement Specialization | HIPAA-compliant clinician expense capture remains underpenetrated across US hospital accounts-payable functions. |
| Real-Time Payment Infrastructure | Instant reimbursement rails through corporate card networks eliminate float-based adoption barriers. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with CFOs, IT procurement officers, expense platform engineers, and corporate treasury leads. Primary fieldwork combined with secondary validation across vendor pricing disclosures, Gartner procurement surveys, and BaFin supervisory reports. Bottom-up deployment volume estimates were triangulated against top-down enterprise software spending benchmarks.
Assumptions held fixed include sustained EU AI Act implementation timelines, hyperscaler pricing trajectories, and corporate card network API availability across the analysis window. Segmentation dimensions modeled encompass deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from deployment velocity curves and seat expansion patterns. Forecast inputs incorporated GDPR enforcement intensity and CSRD carbon disclosure adoption rates.
Stress conditions across hyperscaler pricing volatility, regulatory certification delays, and embedded ERP bundling aggressiveness were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against Gartner enterprise application spending surveys and IDC SaaS deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global CMDB Software Market
Software & Services
Deck Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Software Construction Components Market
Software & Services
Webcasting Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Application Server Market
Software & Services
Global Handyman Software Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Invoice Processing Software Market
Software & Services
Global Membership Management Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Entity Management Software Market
Software & Services
Time and Attendance Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Family Office Software Solutions Market