
 Global Managed Application Services Market | 2026-2036
Global Managed Application Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Managed Application Services Market Foresight
EU CSRD disclosure mandates and the EU AI Act are consolidating accountability requirements across enterprise software estates, pushing large organizations toward outsourced governance partners. IBM Corporation leverages its hybrid cloud consulting depth to anchor complex mainframe-to-cloud transitions for regulated clients. Accenture sustains competitive positioning through industry-specific operating models that embed compliance workflows directly into application management. HCL Technologies Limited dominates engineering-centric application modernization, particularly for manufacturing and energy clients navigating dual carbon reporting obligations.
Managed Application Services encompass the ongoing operational oversight, performance tuning, security patching, and functional evolution of business-critical software applications, typically delivered through remote service centers with defined SLA thresholds such as sub-15-minute incident response for Tier-1 systems. These services eliminate the capital burden of in-house application teams while ensuring continuous availability of ERP, CRM, and custom-built platforms. Cloud Migration and Hybrid Cloud deployment models command premium pricing due to architectural complexity and scarcity of certified multi-platform engineers. Application Monitoring represents a mature, high-volume segment where automation is compressing margins and shifting value toward predictive analytics integration. Incident Management within the BFSI vertical generates outsized margin pools because financial regulators in multiple countries mandate auditable response protocols and dedicated personnel.
FDA 21 CFR Part 11, EU GDPR, and Japan's METI data governance guidelines each impose distinct compliance architectures on application environments, creating specialized demand for jurisdiction-certified managed service providers. The SEC's cybersecurity disclosure rules and analogous frameworks from India's SEBI now require documented application vulnerability management, directly expanding the scope of managed engagements. Stakeholders must evaluate whether their provider portfolios span the regulatory multiplicity of their operating geographies or concentrate risk in single-jurisdiction partners.
Market Dynamics
Financial services enterprises are outsourcing application governance to navigate the EU AI Act's algorithmic accountability mandates and the SEC's cybersecurity disclosure rules, compressing procurement cycles for compliant managed service partnerships.
Growth Catalysts
- EU AI Act enforcement:Enterprises subject to high-risk AI system classifications must maintain auditable application logs and human oversight protocols, expanding managed service scopes for compliance documentation.
- Hybrid cloud complexity:Mainframe-to-cloud transitions require certified multi-platform engineers for ERP continuity, pulling demand toward providers with mainframe modernization capabilities.
- Carbon reporting convergence:Manufacturing and energy clients face dual CSRD and ISO 14064 obligations, driving outsourcing of emissions-tracking application layers.
Market Restraints
- Certified engineer scarcity:AWS, Azure, and Google Cloud platform certifications command salary premiums exceeding 40% above baseline IT wages, inflating service delivery costs.
- Single-jurisdiction provider concentration:Mid-tier managed service providers in India and the Philippines lack EU GDPR and Japan METI data residency certifications, limiting cross-border contract eligibility.
- Automation margin compression:Application Monitoring tools from Datadog and Dynatrace embed predictive analytics, displacing tier-1 human incident response and eroding traditional pricing power.
Strategic Opportunities
- German industrial Mittelstand:Small and mid-sized manufacturers lack in-house SAP S/4HANA expertise for CSRD carbon disclosure integration, creating white space for specialized managed partners.
- AI observability convergence:MLOps platforms and traditional APM tools are merging, enabling providers to bundle model performance monitoring with legacy application support.
- India's SEBI cybersecurity mandates:Documented vulnerability management requirements for listed companies expand managed engagement scopes beyond traditional SLA boundaries.
Industry Challenges
- Multi-cloud orchestration expertise:Kubernetes and Terraform proficiency gaps persist among mid-level engineers, delaying client migration timelines and penalty exposure.
- Regulatory certification latency:FDA 21 CFR Part 11 validation for pharmaceutical application environments requires 6-12 month documentation cycles, constraining revenue recognition speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Managed Application Services Market |
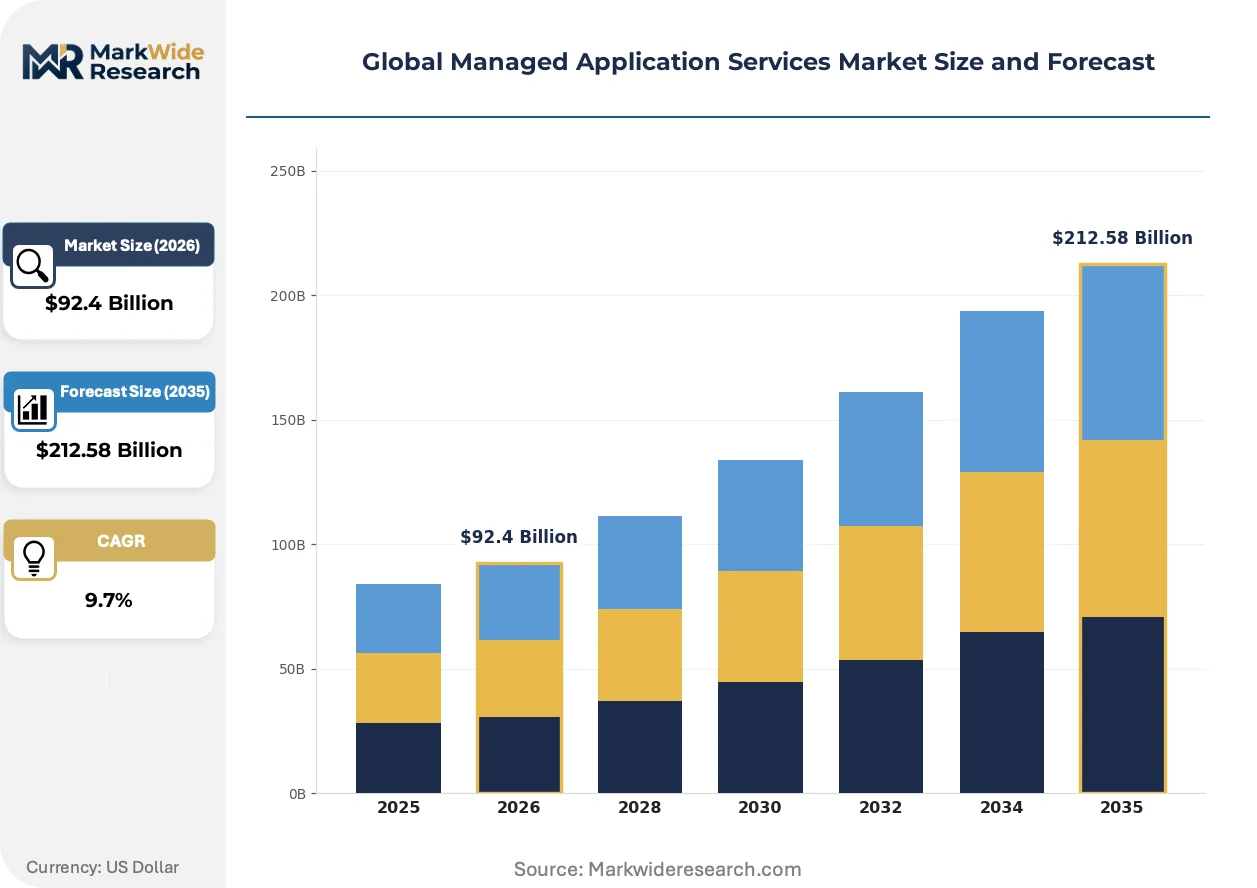
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $212.58 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Application Monitoring, Software Deployment, Cloud Migration, Incident Management, User Support Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises, Multi-Cloud Industry Vertical: BFSI, Telecommunications, Energy & Utilities, Manufacturing, Government Client Type: Enterprises, Small & Medium Businesses, Startups, Non-Profit Organizations |
| Companies Covered | IBM Corporation, Accenture, HCL Technologies Limited, DXC Technology Company, Fujitsu, Wipro Limited, Capgemini SE, Cognizant Technology Solutions Corporation, Rackspace US, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Managed Application Services Market Shifts & Advancements
Generative AI capabilities are embedding into managed service delivery models, shifting value from reactive ticket resolution toward autonomous code remediation and predictive capacity planning.
Observability platforms are integrating OpenTelemetry standards for unified telemetry collection across cloud-native and legacy monolithic applications. Financial services firms in the United States and Germany are adopting these tools at the fastest clip, consolidating previously siloed monitoring stacks. This convergence is integrating security operations and application performance management into single-pane workflows, compressing vendor consolidation timelines.
The EU CSRD disclosure mandates now require granular sustainability data from application estates, forcing enterprises to retrofit carbon measurement APIs into existing ERP and CRM platforms. Industrial manufacturers face the steepest compliance burden, as Scope 3 emissions tracking demands supplier-facing application modifications. German automotive suppliers and French chemical processors are accelerating managed service procurement to meet 2025 filing deadlines.
Consumption-based pricing models are displacing fixed-fee managed service contracts in the BFSI vertical. Large banks in India and the United States now demand outcome-linked payment structures tied to incident reduction targets and availability thresholds. This shift pressures providers to absorb operational risk while investing in automation tooling, favoring scaled players with capital reserves over boutique specialists.
Global Managed Application Services Market Segmentation
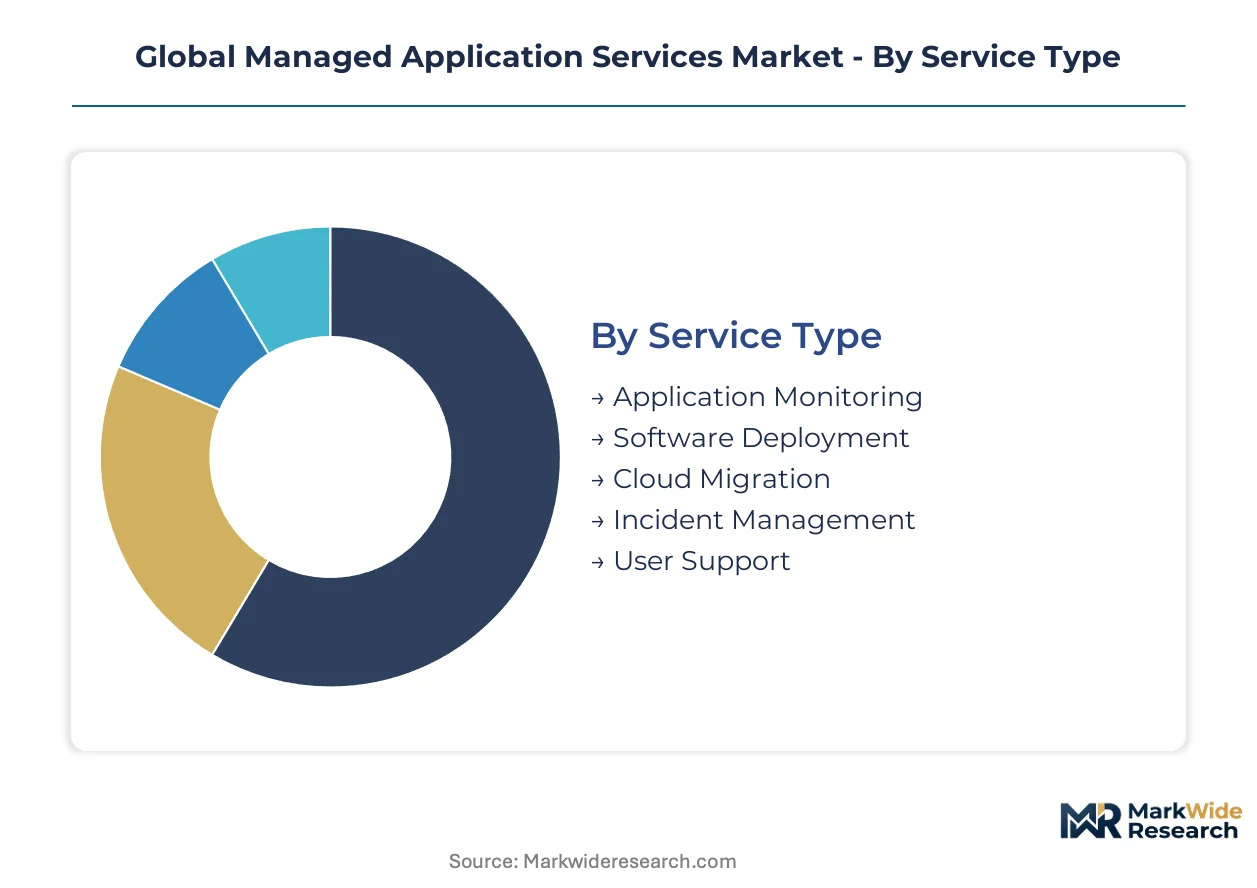
Segmentation in managed application services reveals how procurement priorities diverge across technical complexity, regulatory exposure, and organizational scale. Providers configure delivery models and pricing architectures around these fault lines to capture margin pools that in-house teams cannot economically defend.
Service Type:
Application lifecycle stages drive replacement-cycle timing, with modernization waves clustering around cloud platform end-of-support milestones and compliance deadline pressures.
- Application Monitoring:Continuous telemetry collection across distributed architectures using OpenTelemetry and proprietary APM agents. German automotive suppliers and US financial services firms deploy these capabilities to meet sub-15-minute incident response SLAs mandated by regulators.
- Cloud Migration:Mainframe-to-cloud transition services requiring certified multi-platform engineers for ERP continuity. Manufacturing clients in India and energy utilities in Germany pull demand toward providers with mainframe modernization depth as they confront dual carbon reporting obligations.
- Incident Management:Auditable response protocols with dedicated personnel for Tier-1 system recovery.
- Software Deployment:Release automation and configuration management across hybrid estates.
- User Support:Tiered helpdesk operations with knowledge base maintenance and training delivery.
Application Monitoring sits at the top of the volume ranking, with Cloud Migration climbing the fastest.
Deployment Model:
Cost tier differentiation separates commodity public cloud management from premium multi-cloud orchestration requiring scarce Kubernetes and Terraform expertise.
- Hybrid Cloud:Integrated on-premises and cloud infrastructure with unified governance layers. US healthcare systems and Japanese financial institutions prioritize this model to satisfy data residency requirements while accessing elastic compute for analytics workloads.
- Multi-Cloud:Orchestration across AWS, Azure, and Google Cloud with workload portability. Large enterprises in India and Germany adopt this architecture to avoid vendor lock-in and negotiate favorable pricing through competitive tension.
- Private Cloud:Dedicated infrastructure with single-tenant isolation for regulated workloads.
- Public Cloud:Shared infrastructure with standardized management tooling and consumption-based pricing.
- On-Premises:Legacy data center retention with modernized operational procedures.
Hybrid Cloud commands the highest pricing tier, while Multi-Cloud is gaining share fastest among Fortune 500 accounts.
Industry Vertical:
Margin concentration follows regulatory intensity, with sectors facing algorithmic accountability mandates and cybersecurity disclosure rules outsourcing governance functions most aggressively.
- BFSI:Comprehensive application oversight spanning core banking, trading platforms, and customer-facing digital channels. US banks and Indian listed companies under SEBI cybersecurity mandates expand managed engagement scopes beyond traditional SLA boundaries to include documented vulnerability management.
- Manufacturing:SAP S/4HANA and emissions-tracking application layers for CSRD compliance. German industrial Mittelstand and French chemical processors accelerate procurement to meet carbon disclosure deadlines.
- Energy & Utilities:SCADA and grid management application support with ISO 14064 integration.
- Government:Citizen service platforms with strict procurement and security clearance requirements.
- Telecommunications:BSS/OSS modernization and 5G service orchestration layers.
BFSI generates the deepest margin pools, with Manufacturing showing the steepest expansion trajectory as carbon reporting deadlines approach.
Client Type:
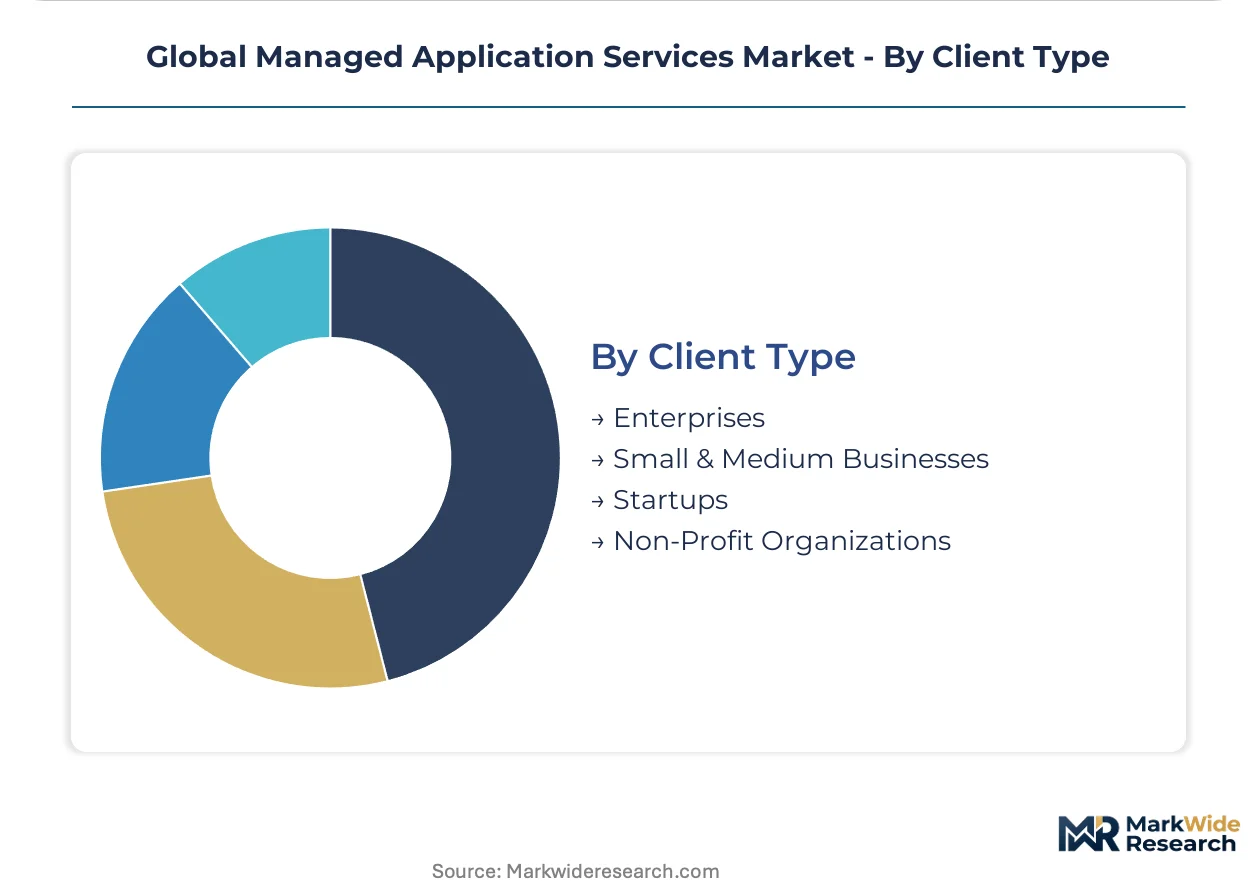
Organizational maturity determines service packaging, with enterprises demanding outcome-linked contracts and smaller entities seeking standardized subscription tiers.
- Enterprises:Complex multi-year engagements with dedicated delivery teams and custom SLA frameworks. Large banks in India and the United States now demand consumption-based pricing tied to incident reduction targets and availability thresholds.
- Small & Medium Businesses:Standardized packages with limited customization and shared service center delivery. German mid-sized manufacturers lacking in-house SAP expertise create white space for specialized partners offering CSRD-ready managed services.
- Startups:Elastic scaling arrangements with minimal committed volumes and rapid onboarding.
- Non-Profit Organizations:Discounted or grant-funded service tiers with simplified governance requirements.
Enterprises anchor current revenue concentration, with Small & Medium Businesses expanding most quickly as compliance complexity outpaces internal capability building.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Managed application services originated in the United States during the 1990s enterprise outsourcing wave, then expanded through India's service center buildout and Germany's industrial automation clusters. Today procurement concentrates in regulatory-intensive jurisdictions where compliance complexity outpaces internal IT capabilities.
United States
Financial services firms in New York and Chicago drive demand for SEC-compliant vulnerability management and cybersecurity disclosure documentation. The SEC's cybersecurity rules now mandate documented application security protocols, expanding managed engagement scopes for listed enterprises. Healthcare systems in Boston and San Francisco prioritize hybrid cloud deployments to satisfy HIPAA data residency requirements while accessing elastic analytics infrastructure.
Germany
Industrial Mittelstand manufacturers around Stuttgart and Munich lack in-house SAP S/4HANA expertise for CSRD carbon disclosure integration. The EU CSRD mandates granular sustainability reporting from application estates, forcing ERP retrofits for Scope 3 emissions tracking. Automotive suppliers in Baden-Württemberg accelerate procurement of specialized managed partners to meet 2025 filing deadlines.
India
SEBI cybersecurity mandates for listed companies expand managed service scopes beyond traditional SLAs into documented vulnerability management. Banks in Mumbai and Bangalore now demand consumption-based pricing tied to incident reduction targets. IT service centers in Hyderabad and Pune face engineer scarcity as AWS, Azure, and Google Cloud certifications command salary premiums exceeding baseline IT wages.
Japan
Financial institutions in Tokyo and Osaka adopt hybrid cloud architectures to satisfy METI data governance guidelines while modernizing core banking platforms. METI's data residency requirements create specialized demand for jurisdiction-certified providers with local operational presence. Manufacturing conglomerates in Nagoya outsource emissions-tracking application layers to navigate dual carbon reporting obligations.
United Kingdom
London-based financial services firms navigate EU AI Act algorithmic accountability mandates through outsourced governance partnerships. The UK Information Commissioner's Office enforces GDPR-aligned data processing standards, compelling enterprises to seek compliant managed service relationships. Fintech clusters in Manchester and Edinburgh concentrate demand for cloud migration services supporting mainframe-to-cloud transitions.
Global Managed Application Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and multi-platform engineering scarcity. The vendor base stratifies into three tiers: global systems integrators with regulatory certification breadth, regional specialists with industry-vertical depth, and automation-native challengers compressing incident response pricing. Consolidation pressure favors scaled providers with capital reserves to absorb outcome-linked contract risk, while mid-tier players face margin compression from embedded observability tooling.
Within the global systems integrator tier, IBM Corporation and Accenture occupy positions anchored by hybrid cloud consulting depth and industry-specific operating models respectively. HCL Technologies Limited exemplifies the engineering-centric modernization archetype, particularly for manufacturing and energy clients navigating compliance complexity. These three anchors represent divergent strategic postures: platform-agnostic infrastructure consulting, compliance-embedded vertical specialization, and technical modernization execution.
| Leading Market Players |
|---|
| IBM Corporation |
| Accenture |
| HCL Technologies Limited |
| DXC Technology Company |
| Fujitsu |
| Wipro Limited |
| Capgemini SE |
| Cognizant Technology Solutions Corporation |
| Rackspace US, Inc. |
| Others |
Supply & Pricing Matrix
Certified multi-platform engineers concentrated in India and the United States command salary premiums exceeding baseline IT wages by substantial margins, creating labor-cost differentials that stratify pricing tiers between premium hybrid-cloud engagements and commoditized monitoring services.
Pricing Analysis
Outcome-linked payment structures tied to incident reduction targets and availability thresholds now dominate BFSI procurement in India and the United States, displacing fixed-fee contracts. Price differentiation hinges on certification depth—EU GDPR, Japan METI data residency, and FDA 21 CFR Part 11 compliance tiers—and automation tooling maturity. Cost compression in Application Monitoring is intensifying because Datadog and Dynatrace embed predictive analytics that displace human incident response. Small and medium businesses exhibit highest price sensitivity, while regulated enterprises in financial services absorb premium pricing for auditable governance layers.
Supply Chain Analysis
Cloud-certified engineering talent draws from India, the United States, and Germany as the primary supply nodes for multi-platform expertise. Raw material dependencies include AWS, Azure, and Google Cloud platform certifications, Kubernetes and Terraform proficiency, and OpenTelemetry-standard observability tooling. Single-source vulnerability concentrates risk in Indian service centers lacking EU GDPR and Japan METI certifications, constraining cross-border contract eligibility. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed application services function as a stable compounder anchored by regulatory compliance mandates that perpetually outpace internal enterprise IT capabilities.
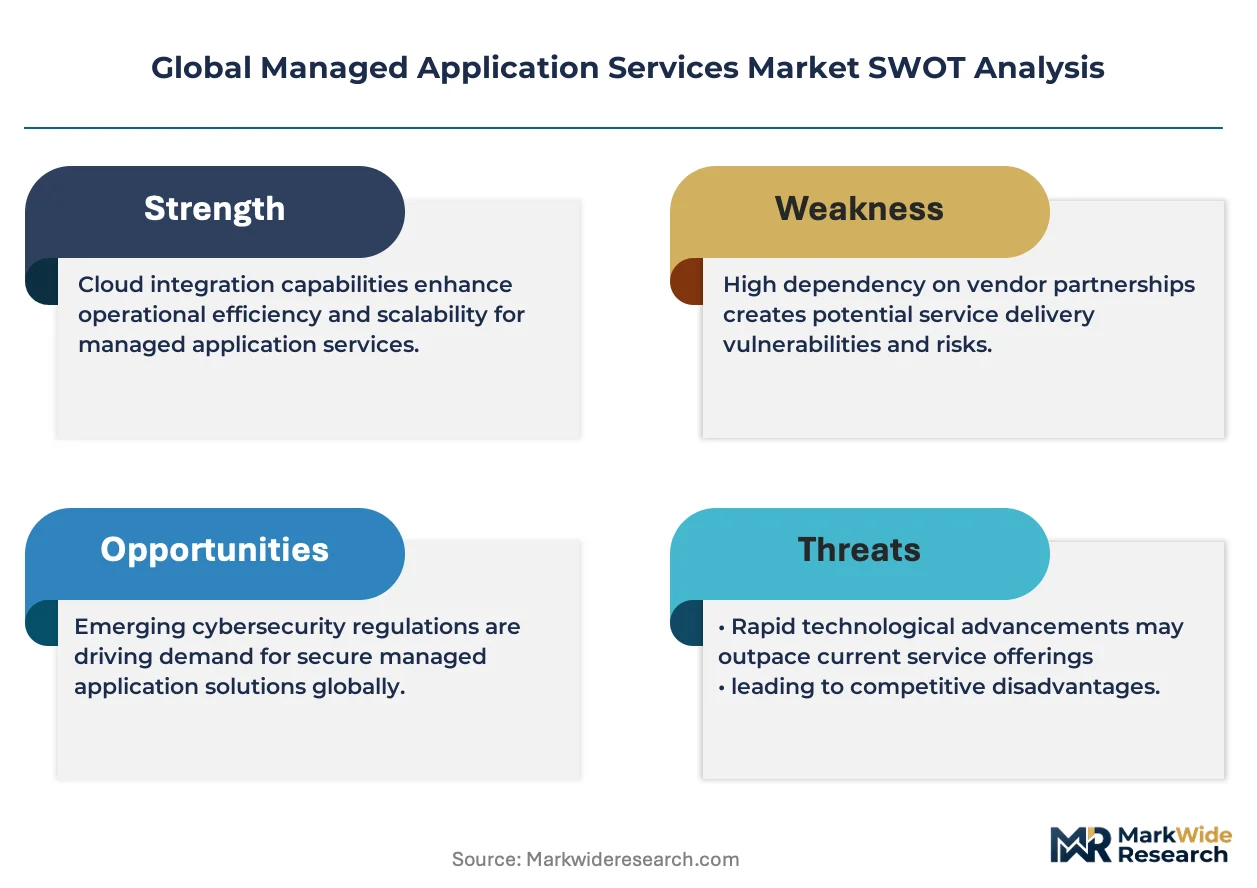
For Market Incumbents: To counter automation-native challengers compressing incident response pricing, incumbents must deepen vertical integration into MLOps platform development and expand EU AI Act certification coverage across delivery centers. Channel control through hyperscaler marketplace exclusivity represents a second defensive lever.
For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for specialized compliance-embedded partnerships serving automotive suppliers and chemical processors facing CSRD carbon disclosure deadlines. India's SEBI cybersecurity mandates for listed companies present a second penetrable entry point. A consumption-based pricing model with outcome-linked SLAs offers the most viable go-to-market angle.
For Investors and Strategic Acquirers: Global systems integrators are the most active acquirer in this space, consolidating regional specialists with jurisdiction-specific certification depth. The five-to-ten-year viability window favors providers with capital reserves to absorb outcome-linked contract risk. Acquisition targets should display engineering-centric modernization capabilities for manufacturing and energy verticals. Watch for inflection when carbon reporting deadlines trigger accelerated procurement waves among German industrial Mittelstand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Observability Platform Integration | Merges MLOps monitoring with legacy APM for unified telemetry across hybrid estates. |
| EU AI Act Certification Investment | Enables auditable algorithmic accountability services for high-risk system classifications. |
| German Mittelstand Partnership Program | Captures CSRD-driven SAP S/4HANA modernization demand among mid-sized manufacturers. |
| Consumption-Based Pricing Transition | Aligns provider incentives with client incident reduction and availability outcomes. |
| Multi-Cloud Orchestration Capability Buildout | Addresses Kubernetes and Terraform proficiency gaps delaying client migration timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, and service provider certification registries. Bottom-up and top-down triangulation reconciled segment-level inputs with aggregate market sizing.
Segment-weighting across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern structured the analytical framework. CAGRs derived from regression analysis of historical procurement velocity and regulatory deadline clustering. Cloud migration wave timing and compliance certification latency served as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when regulatory enforcement timelines shift, certified engineer supply constraints intensify, or automation tooling displaces additional service tiers. Forecasts reflect documented assumptions about procurement cycle compression and SLA premium sustainability. A small set of named triggers—EU AI Act penalty enforcement, SEBI mandate expansion, and mainframe end-of-support milestones—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
3D Animation Software Market
Software & Services
Global Apparel Management Software Market
Software & Services
Automated Testing Software Market
Software & Services
Webcasting Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Global OEE Software Market
Software & Services
Global Animation Software Market
Software & Services
Email Applications Market
Software & Services
Lawn Care Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Global Business Card Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Global Portal Software Market
Software & Services
Parks and Playground Inspection Software Market