
 Europe Amino Acid in Dietary Supplements Market | 2026-2036
Europe Amino Acid in Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Amino Acid in Dietary Supplements Market Foresight
Buyer concentration among sports nutrition consumers is recalibrating as amateur fitness enthusiasts and aging wellness seekers fragment the traditional athlete-dominated customer base. Ajinomoto Co., Inc. leverages its fermentation technology leadership to supply pharmaceutical-grade amino acids across European nutraceutical channels. NOW Foods anchors its position through vertical integration from raw material sourcing to finished supplement manufacturing. Evonik Industries AG specializes in precision amino acid derivatives for medical nutrition applications, extending its industrial biotech expertise into consumer health.
Amino acids in dietary supplements comprise crystalline or microencapsulated essential and conditionally essential amino acids, typically manufactured through microbial fermentation or enzymatic extraction, formulated to support protein synthesis, nitrogen balance, and metabolic function in human nutrition. L-Glutamine and L-Leucine dominate product type revenue pools due to their established roles in muscle protein synthesis and gut barrier integrity, while sports nutrition and muscle recovery applications capture the deepest margin pools as consumers prioritize performance-linked dosing protocols. Powder and capsule forms lead volume distribution, though liquid formats are gaining traction in convenience-oriented channels across Southern Europe.
EFSA health claims assessments, EU Novel Food Catalogue listings, and national pharmacy regulator frameworks in Germany and France shape product authorization timelines and label substantiation requirements for amino acid supplements. REACH compliance for synthetic amino acid precursors and emerging EU packaging sustainability directives add compliance layers to ingredient sourcing and finished goods distribution. Stakeholders must monitor regulatory divergence between member states on amino acid dosage thresholds and monitor channel-specific enforcement intensity as online retail growth outpaces traditional health store oversight capacity.
Market Dynamics
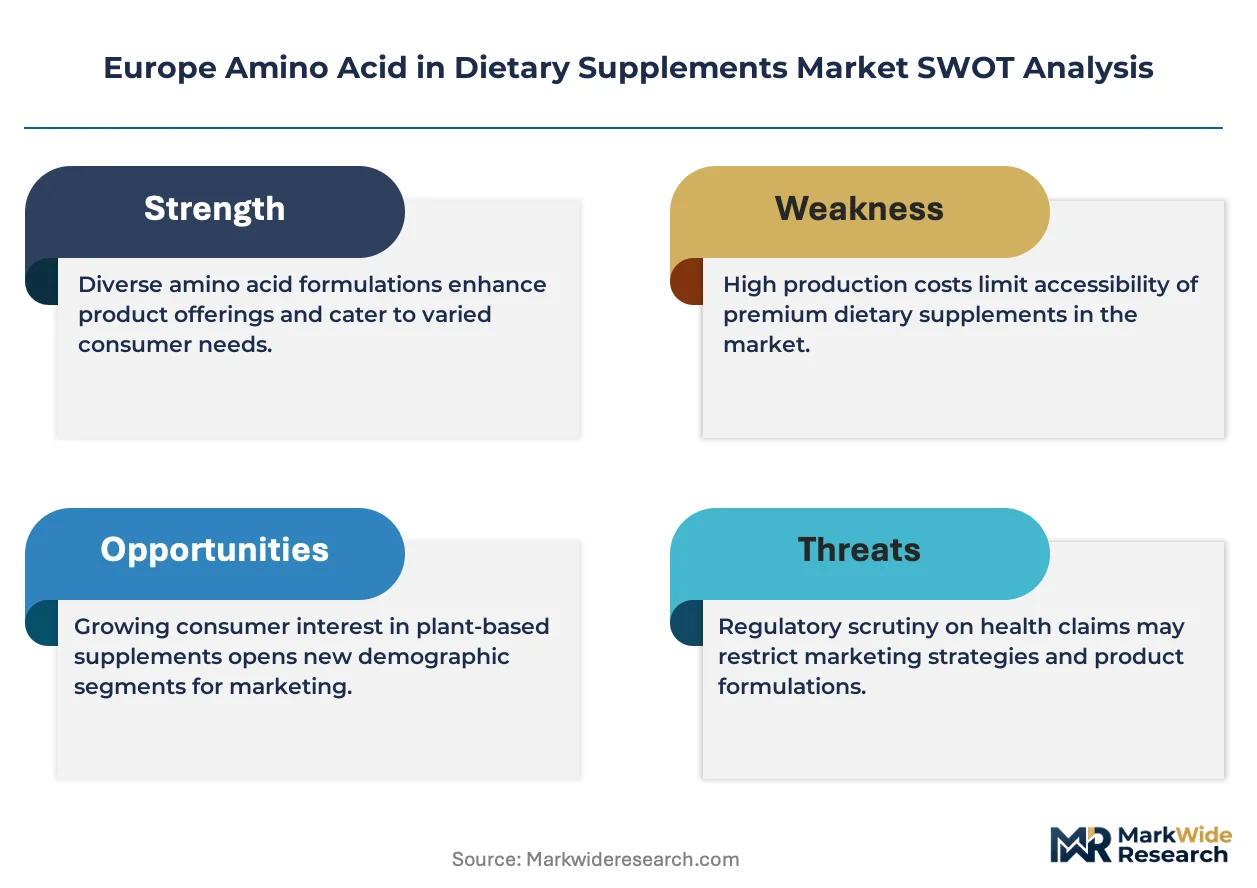
EFSA novel food evaluations and evolving EU health claims regulations are tightening substantiation requirements, forcing reformulation cycles and label revisions across European amino acid supplement portfolios. This regulatory compression is reshaping competitive positioning between established pharmaceutical-grade suppliers and emerging functional food entrants.
Growth Catalysts
- REACH compliance for synthetic precursors:The EU's chemical registration framework is accelerating substitution toward fermentation-derived amino acids, favoring suppliers with established biotech infrastructure.
- Aging wellness demographics:France and Germany's expanding senior populations are adopting conditionally essential amino acids for sarcopenia prevention, fragmenting the traditional sports nutrition buyer base.
- Microencapsulation technology:Advanced coating processes are improving amino acid stability in liquid formats, opening convenience-oriented distribution channels across Southern Europe.
Market Restraints
- Fermentation feedstock volatility:Corn and sugar beet price swings in Eastern European agricultural supply zones compress margin predictability for bulk amino acid manufacturers.
- EFSA health claim authorization delays:The 18-24 month evaluation timeline for novel amino acid efficacy statements freezes product launch pipelines and ties up R&D capital.
- Plant protein concentrate substitution:Pea and rice protein isolates with complete amino acid profiles are displacing standalone amino acid SKUs in mass-market sports nutrition.
Strategic Opportunities
- Medical nutrition channel expansion:Hospital and clinical prescribing protocols for immuno-nutrition are creating demand for pharmaceutical-grade L-Glutamine in Germany and the Netherlands.
- EU Green Deal packaging mandates:Biodegradable sachet and blister requirements are favoring suppliers with in-house sustainable format development capabilities.
- Direct-to-consumer subscription models:Personalized amino acid dosing based on microbiome testing is gaining traction among UK fitness enthusiasts through specialized e-commerce platforms.
Industry Challenges
- Novel food dossier compilation expertise:The technical skill gap in toxicology and bioavailability study design is bottlenecking SME market entry across member states.
- Multi-country label harmonization:Divergent national pharmacy regulator interpretations of amino acid dosage thresholds in Germany, France, and Italy complicate pan-European SKU strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Amino Acid in Dietary Supplements Market |
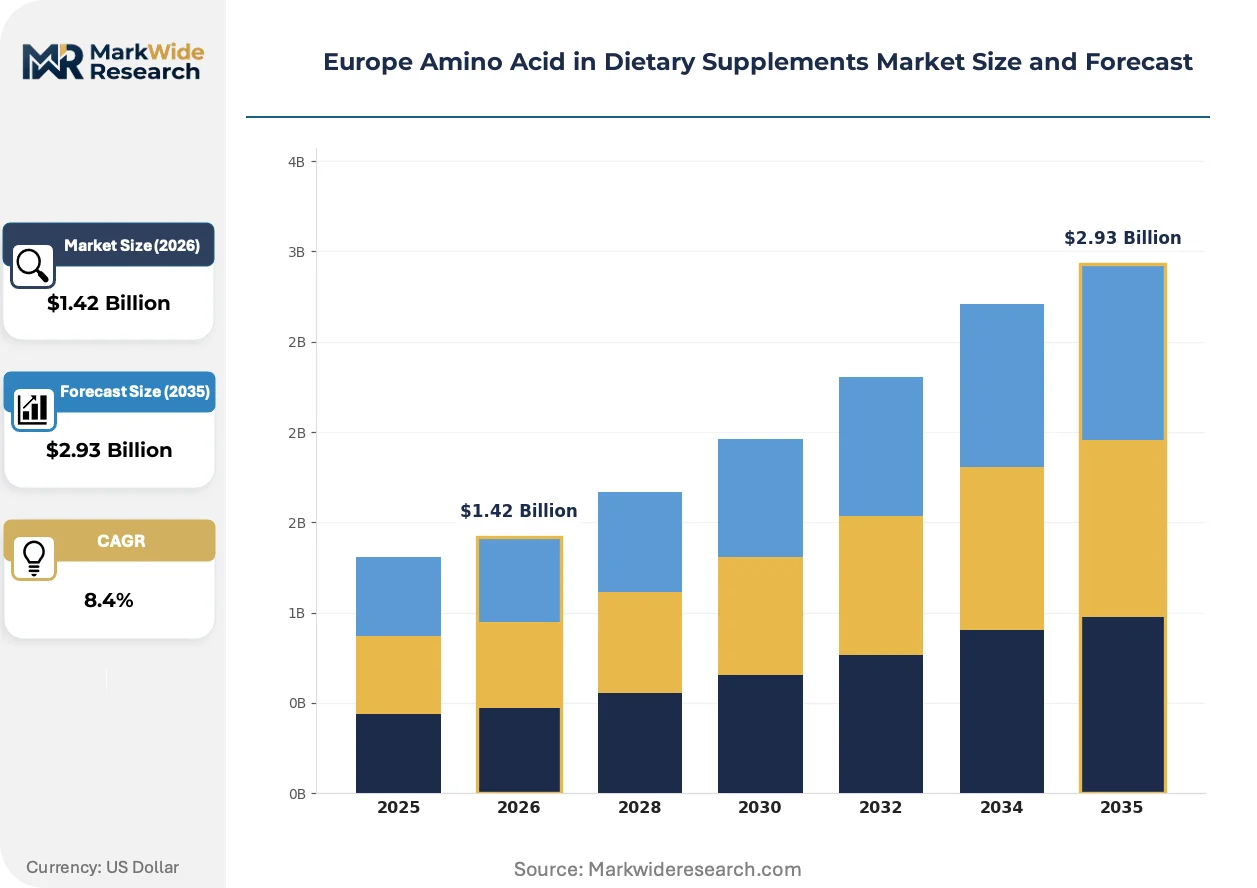
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Glutamine, L-Leucine, L-Arginine, L-Phenylalanine Application: Sports Nutrition, Weight Management, Muscle Recovery, Immune Support Form: Powder, Capsule, Liquid, Bar Distribution Channel: Online Retail, Health Stores, Supermarkets, Pharmacies |
| Companies Covered | MusclePharm, NOW Foods, Solgar Inc., Optimum Nutrition, Evonik Industries AG, Ajinomoto Co., Inc., Universal Nutrition, Jarrow Formulas, Inc, Glanbia Nutritionals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Amino Acid in Dietary Supplements Market Shifts & Advancements
Continuous manufacturing and real-time quality monitoring are compressing batch cycle times from weeks to days, while regulatory digitization and shifting channel economics are redrawing how amino acid supplements reach European consumers.
Fermentation process analytical technology (PAT) is automating in-line metabolite monitoring and pH adjustment, eliminating manual sampling protocols. German and Dutch contract manufacturers are deploying these systems to secure pharmaceutical-grade certification. This automation is compressing the cost gap between industrial and food-grade amino acid production, enabling mid-tier suppliers to enter clinical nutrition channels previously reserved for established pharmaceutical players.
EFSA's updated guidance on Article 13.1 health claims for amino acids is requiring randomized controlled trial data for muscle function statements, raising the evidentiary bar above traditional literature reviews. This policy shift is favoring suppliers with dedicated clinical research budgets and partnerships with European university medical centers. Sports nutrition brands targeting amateur fitness enthusiasts face the steepest compliance burden, as their legacy marketing claims lack the required intervention study backing.
Subscription-based replenishment models are displacing traditional health store replenishment for core amino acid SKUs, with UK and German consumers locking into 90-day cycles for L-Leucine and BCAAs. Specialized e-commerce platforms are capturing this shift through personalized dosing algorithms and loyalty pricing. This channel rotation is most visible among urban millennials in London, Berlin, and Amsterdam, where convenience and cost predictability outweigh immediate retail availability.
Europe Amino Acid in Dietary Supplements Market Segmentation
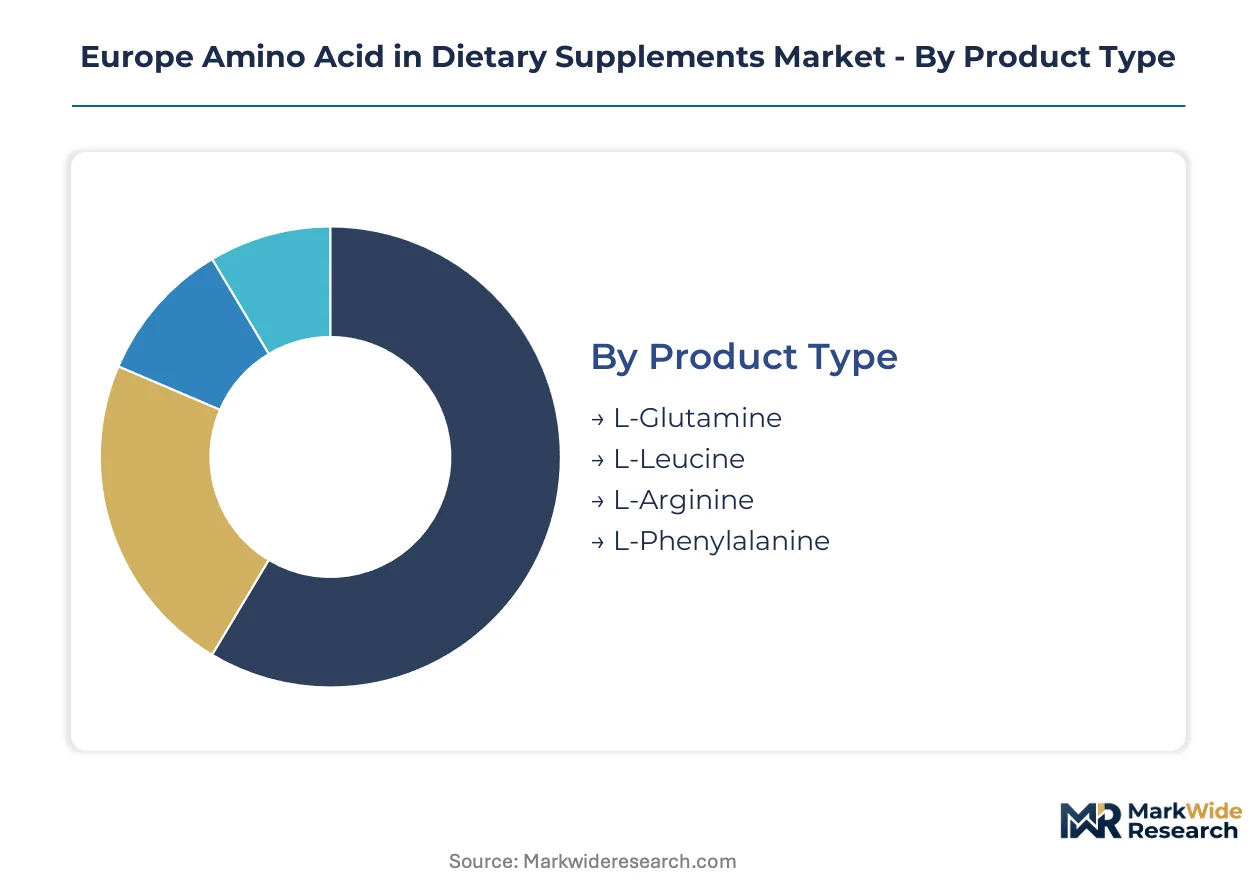
Amino acid supplement segmentation in Europe reflects divergent technical requirements across standalone crystalline formulations and embedded multi-ingredient systems. Product positioning strategies must reconcile EFSA substantiation thresholds with channel-specific consumer expectations for purity, convenience, and dosing precision.
Product Type:
Standalone crystalline amino acids command premium shelf positioning in German pharmacy channels, while embedded formulations in protein matrices dominate mass-market sports nutrition SKUs across the United Kingdom and France.
- L-Glutamine:Pharmaceutical-grade crystalline powder supports nitrogen transport and gut barrier integrity in clinical nutrition protocols. Demand concentrates in German hospital prescribing systems where immuno-nutrition guidelines specify perioperative dosing regimens.
- L-Leucine:Branched-chain amino acid with the strongest mTOR pathway activation profile for muscle protein synthesis. French sports nutrition brands embed microencapsulated L-Leucine in post-workout recovery formulations targeting amateur endurance athletes.
- L-Arginine:Nitric oxide precursor used in cardiovascular wellness segments and pre-workout vasodilation stacks.
- L-Phenylalanine:Aromatic amino acid restricted to specialized cognitive and mood support applications under tighter dosage scrutiny.
Volume placements concentrate in L-Glutamine; the faster expansion belongs to L-Leucine.
Application:
Cost tier stratification separates clinical-grade dosing protocols from convenience-oriented consumer positioning, with reimbursement eligibility in German medical nutrition creating the steepest price premiums.
- Sports Nutrition:Pre-workout, intra-workout, and recovery formulations targeting protein synthesis optimization. UK fitness enthusiasts drive powder format demand through specialized e-commerce subscription platforms with personalized dosing algorithms.
- Muscle Recovery:Post-exertion formulations emphasizing reduced delayed-onset muscle soreness and accelerated tissue repair. Dutch contract manufacturers supply pharmaceutical-grade BCAAs to Nordic rehabilitation clinic networks under strict quality certification.
- Weight Management:Satiety-signaling and thermogenic amino acid combinations in meal replacement systems.
- Immune Support:Glutamine and arginine blends targeting lymphocyte proliferation in wellness positioning.
Revenue concentration sits with Sports Nutrition; Medical Nutrition channel expansion is climbing the fastest.
Form:
Manufacturing complexity and stability requirements create three distinct cost tiers, with liquid formats demanding the most advanced microencapsulation infrastructure to prevent degradation.
- Powder:Unflavored and flavored crystalline amino acids offering dose flexibility and cost efficiency at scale. German bulk ingredient distributors supply tonnage quantities to Scandinavian private-label sports nutrition brands.
- Capsule:Pre-measured dosing for travel and workplace consumption with reduced taste masking requirements. Italian pharmacy chains stock pharmaceutical-grade capsule lines under national regulator pharmacy-only classification.
- Liquid:Ready-to-drink shots and concentrates requiring stability-enhancing formulation technology.
- Bar:Embedded amino acids in protein-fortified snack formats competing with whole-food alternatives.
Unit economics favor Powder; Liquid formats are gaining share fastest in Southern European convenience channels.
Distribution Channel:
Customer type fragmentation between clinical prescriber networks, self-directed fitness enthusiasts, and aging wellness seekers dictates channel-specific compliance burdens and margin structures.
- Online Retail:Direct-to-consumer platforms with subscription replenishment and algorithm-driven personalization. UK specialized fitness e-commerce operators capture repeat purchase loyalty through 90-day amino acid cycles with microbiome-linked dosing recommendations.
- Pharmacies:Clinical-grade formulations with pharmacy-only status under German and French national regulator frameworks. Hospital discharge protocols in the Netherlands drive L-Glutamine prescribing through hospital-affiliated pharmacy networks.
- Health Stores:Staff-assisted selection for intermediate-knowledge consumers seeking format guidance.
- Supermarkets:Mass-market BCAA and protein combination products in grab-and-go positioning.
Transaction velocity concentrates in Online Retail; the steepest expansion trajectory belongs to Pharmacies as medical nutrition protocols broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for amino acid dietary supplements concentrates in Germany's mature sports nutrition sector, with France and the United Kingdom fragmenting the buyer base through aging wellness demographics and amateur fitness participation. EFSA regulatory frameworks and national pharmacy classifications create divergent compliance burdens across member states.
Germany
Clinical-grade L-Glutamine formulations command premium positioning in pharmacy and specialized retail channels, driven by hospital immuno-nutrition prescribing protocols. The national pharmaceutical regulator maintains strict pharmacy-only classification for high-dose amino acid products. North Rhine-Westphalia hosts contract manufacturing clusters supplying pharmaceutical-grade BCAAs to Nordic rehabilitation networks.
United Kingdom
Urban millennials in London drive subscription-based replenishment models for L-Leucine and BCAAs through specialized e-commerce platforms with personalized dosing algorithms. The Food Standards Agency oversees novel food evaluations alongside EFSA alignment procedures. Greater Manchester and Birmingham clusters concentrate direct-to-consumer fulfillment infrastructure for microbiome-linked amino acid services.
France
Expanding senior populations adopt conditionally essential amino acids for sarcopenia prevention, fragmenting traditional sports nutrition demand. ANSM enforces national pharmacy regulator frameworks with tighter dosage scrutiny than neighboring jurisdictions. The Lyon-Grenoble corridor hosts microencapsulation technology development for liquid format stability enhancement.
Netherlands
Hospital discharge protocols drive L-Glutamine prescribing through hospital-affiliated pharmacy networks, creating medical nutrition channel expansion. The national food safety authority coordinates with EFSA on novel food dossier evaluations. Rotterdam-Amsterdam logistics hubs facilitate fermentation-derived amino acid distribution across Benelux clinical nutrition channels.
Italy
Pharmacy chains stock pharmaceutical-grade capsule lines under national regulator pharmacy-only classification, restricting mass-market access. The Ministry of Health interprets amino acid dosage thresholds more conservatively than German or French counterparts. Lombardy-based contract manufacturers supply Southern European convenience channels with stability-enhanced liquid formats.
Europe Amino Acid in Dietary Supplements Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional food integration and personalized nutrition platforms. Market structure reflects moderate consolidation around fermentation technology leaders and pharmaceutical-grade specialists, with fragmentation in private-label sports nutrition. Three archetypes dominate: biotechnology-anchored suppliers with captive fermentation infrastructure, vertically integrated nutraceutical manufacturers, and specialized medical nutrition formulators. Capacity expansion in microbial fermentation and strategic partnerships for novel food dossier compilation represent the dominant competitive moves.
Within the biotechnology-anchored tier, Ajinomoto Co., Inc. and Evonik Industries AG exemplify suppliers with established European nutraceutical channel presence. NOW Foods occupies a position among vertically integrated manufacturers controlling raw material sourcing through finished supplement production. These three companies represent divergent strategic postures: fermentation technology licensing, precision derivatives for clinical applications, and mass-market format diversification.
| Leading Market Players |
|---|
| MusclePharm |
| NOW Foods |
| Solgar Inc. |
| Optimum Nutrition |
| Evonik Industries AG |
| Ajinomoto Co., Inc. |
| Universal Nutrition |
| Jarrow Formulas, Inc |
| Glanbia Nutritionals |
| Others |
Supply & Pricing Matrix
Fermentation feedstock costs for corn and sugar beet originating from Eastern European agricultural zones cascade through three distinct pricing tiers before reaching pharmacy shelves, specialized retail channels, and direct-to-consumer platforms across Germany, France, and the United Kingdom.
Pricing Analysis
Volume placements concentrate in bulk powder formats where contract-based long-term offtake agreements dominate, while pharmaceutical-grade crystalline formulations in German pharmacy channels capture the deepest margin pools through pharmacy-only classification. Price differentiation hinges on EFSA health claim authorization status and clinical-grade certification tier, with unauthorized novel food candidates facing pricing softness as reformulation cycles tie up R&D capital. Amateur fitness enthusiasts through UK e-commerce subscription platforms exhibit the highest price sensitivity, whereas Dutch hospital prescribing protocols for immuno-nutrition show minimal elasticity due to reimbursement eligibility.
Supply Chain Analysis
Dual-sourcing requirements from German and Dutch contract manufacturers are becoming standard for Nordic rehabilitation clinic networks and hospital-affiliated pharmacy chains, mitigating single-source vulnerability from any one fermentation facility. Raw material procurement draws from Ukrainian corn belts, French sugar beet cooperatives, and German biotech-grade glucose suppliers. Supply chain risk centers on REACH compliance delays for synthetic amino acid precursors, which can freeze ingredient qualification timelines. Distribution runs through Rotterdam-Amsterdam logistics hubs for Benelux clinical nutrition channels, with specialized cold-chain infrastructure for stability-enhanced liquid formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food dossier compilation costs and 18-24 month evaluation timelines erect a formidable cost-of-compliance barrier that entrenches established fermentation technology leaders while filtering out capital-constrained challengers.
For Market Incumbents: Deploy captive fermentation infrastructure expansion to secure pharmaceutical-grade certification tiers that emerging functional food entrants cannot replicate. Deepen backward integration into Eastern European corn and sugar beet supply zones to buffer feedstock volatility. Channel control through hospital-affiliated pharmacy networks in the Netherlands and Germany defends margin pools against plant protein concentrate substitution threats. For New Entrants and Emerging Players: Enter via microbiome-linked personalized dosing platforms targeting UK urban millennials, the most penetrable self-directed fitness segment with lowest incumbent loyalty. White-space opportunities concentrate in Southern European liquid format convenience channels where microencapsulation technology gaps persist. A direct-to-consumer subscription go-to-market angle with algorithm-driven replenishment bypasses traditional health store distribution bottlenecks. For Investors and Strategic Acquirers: EFSA health claim authorization for novel amino acid efficacy statements is the leading indicator that a target possesses durable competitive moats and clinical research budgets sufficient for long-term viability. Acquisition focus should center on contract manufacturers with in-house PAT-enabled continuous manufacturing and existing pharmaceutical-grade certifications. Deviation in EFSA evaluation timelines or REACH enforcement intensity would shift the sector outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Novel Food Dossier Investment | EFSA authorization unlocks pharmacy-only classification in Germany and France. |
| Fermentation Capacity Expansion | Captive biotech infrastructure secures REACH-compliant amino acid precursor supply. |
| Microencapsulation Technology Licensing | Liquid format stability opens Southern European convenience channel penetration. |
| Hospital System Partnership | Immuno-nutrition prescribing protocols in the Netherlands drive recurring L-Glutamine demand. |
| Direct-to-Consumer Platform Launch | Subscription replenishment captures UK fitness enthusiast loyalty through 90-day cycles. |
Research Methodology
EFSA guidance documents, EU Novel Food Catalogue listings, and REACH registration databases formed the secondary backbone, supplemented by customs records tracking fermentation-derived amino acid flows through Rotterdam-Amsterdam logistics hubs. Primary interviews with regulatory affairs leads at German contract manufacturers, pharmacy procurement managers in French hospital networks, and sports nutrition brand managers in the United Kingdom validated segment assumptions. Bottom-up volume modeling across product type, application, form, and distribution channel dimensions was cross-checked against top-down market sizing from trade flow analysis.
Historical trendline analysis of sports nutrition participation rates, aging demographic amino acid adoption curves, and EFSA evaluation timeline patterns informed the projection framework across the analysis window. Segmentation modeling incorporated product grade tier, end-use application, format stability requirements, and channel-specific compliance burden as core dimensions. CAGRs were derived from elasticity-adjusted demand curves for L-Glutamine clinical nutrition protocols and L-Leucine sports nutrition penetration, with fermentation capacity expansion schedules and feedstock price volatility as key forecast inputs.
Revisions become necessary when EFSA health claim authorization delays extend beyond standard evaluation windows, REACH enforcement intensifies for synthetic precursors, or plant protein concentrate substitution accelerates in mass-market sports nutrition. Deviation in Eastern European agricultural supply stability or German pharmacy regulator dosage threshold interpretations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Choline Market
Nutritional Supplements
Curcumin Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Dietary Supplement Cultures Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
North America Digestive Health Supplements Market