
 Business Productivity Software Market | 2026-2036
Business Productivity Software Market Size, Share, and Industry Trends Forecast 2026-2036
Business Productivity Software Market Analysis
India is narrowing its gap in business productivity software development through Bangalore's expanding SaaS engineering clusters and government-backed digital infrastructure investments. Microsoft anchors its position through deep enterprise integration across Office Suite and cloud deployment ecosystems. Salesforce differentiates through AI-embedded customer relationship management workflows that extend into revenue operations. Atlassian specializes in developer-centric project management tools that dominate technical team adoption.
Business productivity software encompasses applications that automate, coordinate, and optimize commercial workflows through task scheduling, real-time collaboration protocols, and resource allocation algorithms. These systems operate on cloud-native architectures with API-first designs that enable cross-platform data exchange and role-based access controls for distributed organizations. Office Suite and Project Management categories occupy the largest revenue pools due to universal enterprise dependency on document creation and milestone tracking functions. Cloud-Based deployment is displacing On-Premises installations as latency-sensitive mobile access becomes standard for hybrid work arrangements. Subscription pricing now dominates procurement decisions, though Enterprise Licensing persists in regulated sectors requiring dedicated infrastructure.
FDA oversight of software-as-a-medical-device intersects with productivity platforms handling clinical trial documentation, while EU GDPR and the EU AI Act impose data governance and algorithmic transparency requirements on vendors serving European enterprises. SEC disclosure rules for publicly traded firms further mandate audit trails within financial reporting workflows embedded in productivity suites. Stakeholders must weigh compliance architecture investments against speed-to-market advantages as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Cloud-native architectures are hybridizing with on-premises infrastructure as financial services firms in Texas and California technology corridors demand sovereign data controls alongside elastic compute capacity. This architectural tension is reshaping vendor roadmaps and compliance investments across the sector.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy algorithmic transparency tools within productivity suites, forcing upgrades to embedded audit and explainability modules.
- Financial services automation:Workflow automation suites are penetrating securities trading floors and insurance underwriting operations, replacing manual spreadsheet coordination.
- Bangalore SaaS engineering clusters:India's government-backed digital infrastructure investments are accelerating development velocity for project management and collaboration platforms.
Market Restraints
- GDPR-EU AI Act regulatory friction:Overlapping data governance and algorithmic accountability requirements impose redundant compliance costs on vendors serving European buyers.
- Hyperscaler concentration risk:Cloud infrastructure dependencies concentrate in three US-based providers, creating single-point-of-failure exposure for latency-sensitive mobile deployments.
- Legacy system entrenchment:On-premises document management systems in regulated healthcare and government sectors resist cloud migration due to HIPAA and FedRAMP certification timelines.
Strategic Opportunities
- Clinical trial documentation automation:FDA software-as-a-medical-device oversight creates white space for productivity platforms embedding audit trails in pharmaceutical research workflows.
- AI-embedded revenue operations:Convergence of natural language processing and predictive analytics is opening new pricing tiers for customer relationship management extensions.
- SEC disclosure rule alignment:Audit trail mandates for publicly traded firms are driving replacement cycles in financial reporting modules.
Industry Challenges
- API security architecture talent scarcity:Shortage of engineers skilled in zero-trust identity protocols and role-based access control implementation delays enterprise deployments.
- Cross-border data residency complexity:Fragmented sovereignty requirements between EU, US, and emerging markets force redundant infrastructure provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Productivity Software Market |
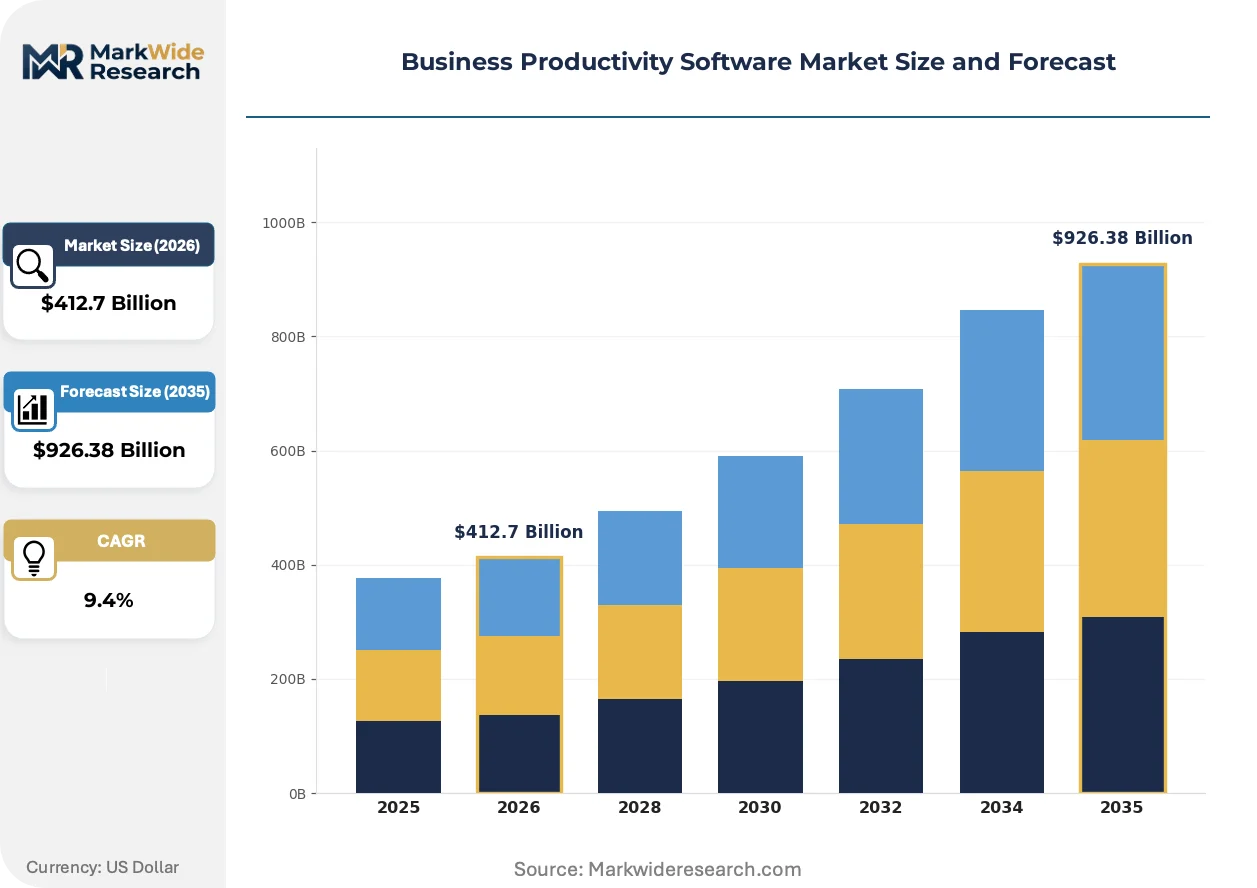
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $926.38 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Office Suite, Project Management, Communication Tools, Document Collaboration Deployment: Cloud-Based, On-Premises, Hybrid, Mobile End User: Small Enterprises, Large Corporations, Freelancers, Non-Profit Organizations Pricing Model: Subscription, One-Time Purchase, Freemium, Enterprise Licensing |
| Companies Covered | Salesforce, monday.com, Microsoft, Notion, Smartsheet, Google, Asana, HubSpot, Atlassian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Productivity Software Market Emerging Trajectories
Generative AI capabilities are embedding into core productivity workflows faster than vendor pricing models can adapt, compressing traditional software release cycles and forcing architectural bets on inference cost structures.
Retrieval-augmented generation is hybridizing with conventional document editing interfaces, enabling real-time synthesis of institutional knowledge bases within word processors and spreadsheets. Enterprise legal departments and consulting practices are adopting these tools at twelve-to-eighteen-month refresh cycles. This capability compression is collapsing the boundary between content creation and enterprise search, forcing incumbents to rearchitect data layer investments.
The EU AI Act's risk classification framework is mandating conformity assessments for productivity software handling automated decision support in hiring and performance management contexts. Vendors must now maintain technical documentation and human oversight protocols for high-risk system deployments. Financial services and human capital management segments are responding by segmenting product lines between EU-compliant and non-EU feature sets.
Subscription fatigue among mid-market buyers is fragmenting procurement authority away from centralized IT toward departmental leaders with discretionary software budgets. Finance and operations teams are unbundling all-in-one suites, selecting point solutions for specific workflow pain points. This pattern concentrates in US technology corridors where SaaS procurement literacy runs deepest and shadow IT governance remains permissive.
Business Productivity Software Market Segmentation
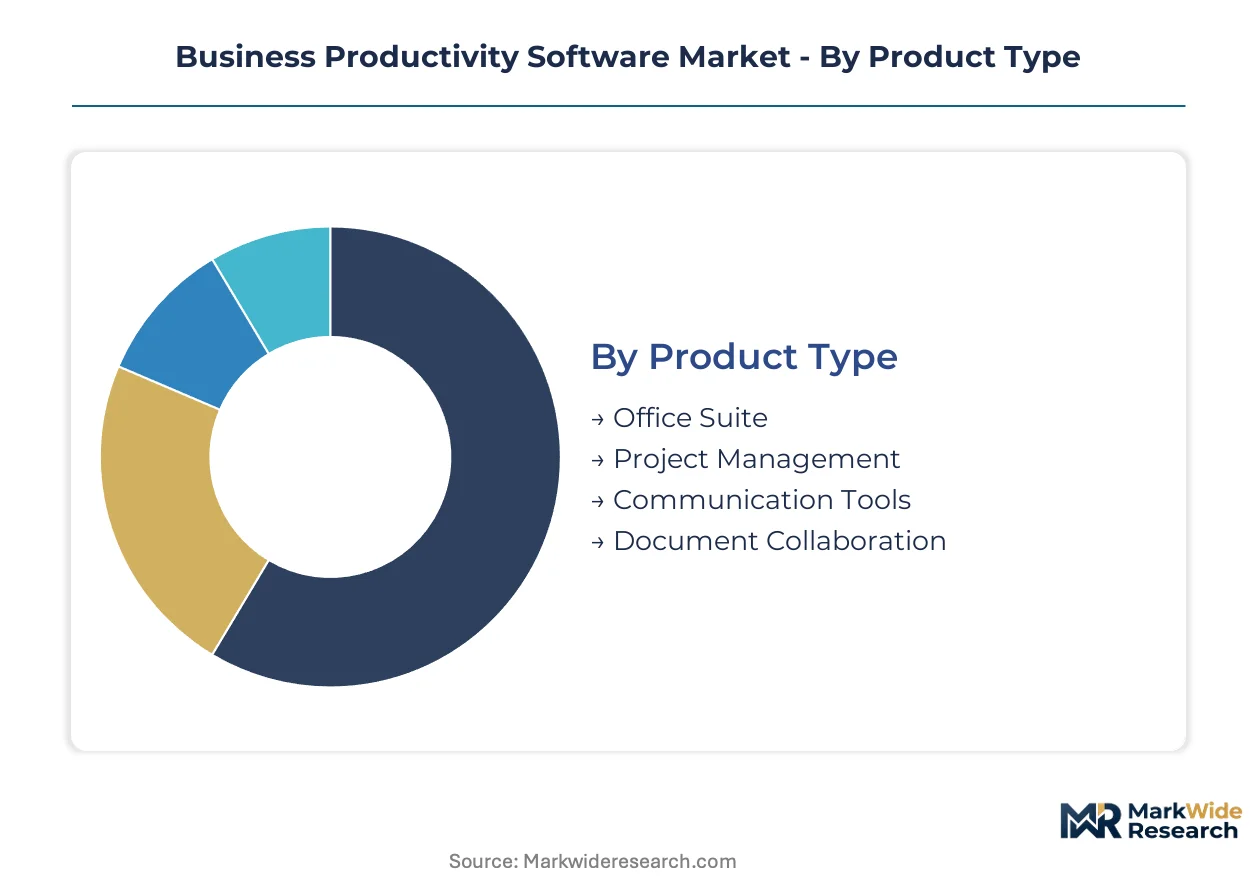
Segmentation in business productivity software reveals how procurement authority fragments across deployment constraints, pricing fatigue, and end-user technical literacy. Vendors must architect separate go-to-market motions for each slice.
Product Type:
After-sales service intensity varies dramatically across product categories, with enterprise suites demanding dedicated customer success teams while point solutions rely on self-service knowledge bases.
- Office Suite:Comprehensive document creation, spreadsheet, and presentation tools forming the backbone of knowledge worker workflows. Demand concentrates in financial services firms across Texas and California technology corridors, driven by SEC disclosure rule mandates for audit-trail-enabled reporting modules. This category commands the highest support touchpoints per seat due to universal enterprise dependency.
- Project Management:Milestone tracking, resource allocation, and Gantt visualization systems for cross-functional coordination. Technical teams in Bangalore SaaS engineering clusters drive adoption velocity, fueled by government-backed digital infrastructure investments accelerating development tool procurement. Atlassian's dominance here forces competitors into vertical specialization.
- Communication Tools:Real-time messaging, video conferencing, and asynchronous channel platforms. Slack and Microsoft Teams embed deeply into enterprise workflows.
- Document Collaboration:Concurrent editing, version control, and comment-threading systems for distributed teams. Notion and Confluence compete for knowledge base centralization.
Office Suite holds the largest share; momentum sits with Project Management.
Deployment:
Cost tier stratification separates hyperscaler-dependent cloud deployments from capital-intensive on-premises installations requiring dedicated infrastructure teams.
- Cloud-Based:Elastic compute provisioning through API-first architectures with cross-platform data exchange capabilities. Financial services automation in Texas and California technology corridors accelerates displacement of legacy installations, though EU GDPR and EU AI Act compliance mandates force redundant sovereignty investments. Latency-sensitive mobile access has become standard for hybrid work arrangements.
- Hybrid:Orchestrated workloads spanning sovereign on-premises nodes and burst-capable cloud capacity. Regulated healthcare and government sectors resisting full cloud migration due to HIPAA and FedRAMP certification timelines gravitate here, balancing data residency requirements against elastic demand spikes.
- On-Premises:Dedicated hardware installations with air-gapped security for classified or critical infrastructure environments. Defense contractors and national laboratories maintain this preference.
- Mobile:Native iOS and Android applications optimized for field service, executive travel, and frontline worker scenarios. Construction and logistics verticals prioritize offline-first architectures.
Cloud-Based commands current procurement volume; Hybrid deployment is climbing the fastest as sovereignty requirements harden.
End User:
Customer type determines sales cycle complexity, with large corporations demanding procurement committee consensus while freelancers convert through product-led growth funnels.
- Large Corporations:Multi-divisional deployments with role-based access controls and custom integration requirements. EU AI Act compliance mandates for algorithmic transparency tools in automated decision support systems drive upgrade cycles in human capital management segments, forcing segmentation between EU-compliant and non-EU feature sets.
- Small Enterprises:Departmental procurement with discretionary software budgets and rapid implementation timelines. Subscription fatigue concentrates unbundling behavior here, with finance and operations teams selecting point solutions for specific workflow pain points.
- Freelancers:Individual productivity subscriptions with minimal configuration overhead. Notion, Trello, and Google Workspace dominate through freemium conversion.
- Non-Profit Organizations:Grant-funded technology investments with donor reporting requirements and volunteer coordination needs. Discounted pricing tiers and donation programs structure vendor engagement.
Large Corporations generate the deepest revenue per account; Small Enterprises are gaining share fastest through departmental procurement fragmentation.
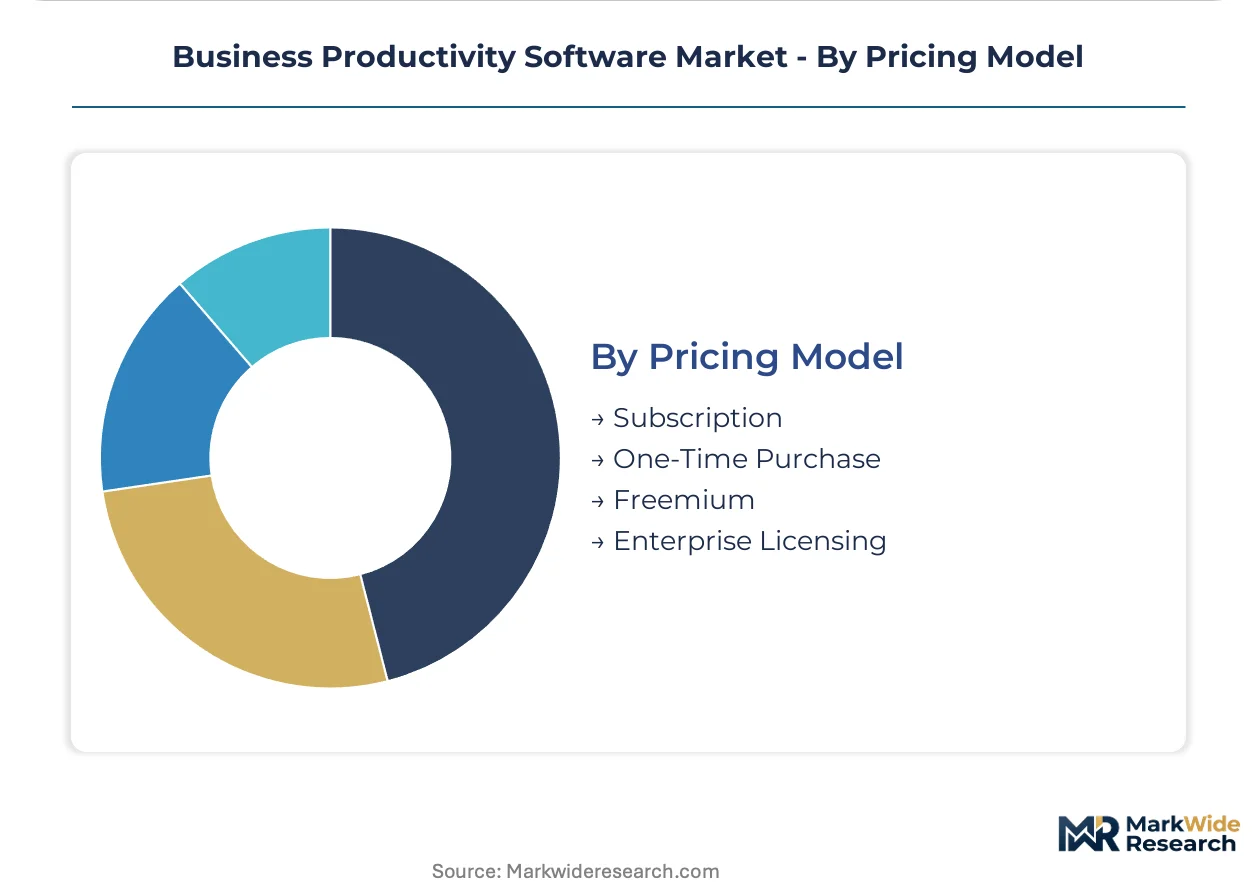
Pricing Model:
Margin structure diverges between recurring subscription streams and lumpy enterprise licensing deals with professional services attachments.
- Subscription:Monthly or annual recurring revenue with tiered feature access and usage-based overage charges. This model now dominates procurement decisions across mid-market buyers in US technology corridors, though EU AI Act and GDPR regulatory friction imposes redundant compliance costs that compress net retention rates.
- Enterprise Licensing:Perpetual or term-limited agreements with dedicated infrastructure and custom development clauses. Regulated sectors requiring FedRAMP and HIPAA certifications persist here despite cloud migration pressure.
- Freemium:Zero-cost entry tiers with conversion gates at team size or feature depth thresholds. Product-led growth motions optimize for viral coefficient over immediate monetization.
- One-Time Purchase:Perpetual license with maintenance and support renewals. Legacy on-premises document management systems in government sectors resist displacement here.
Subscription holds the largest share; Enterprise Licensing maintains steepest expansion trajectory in regulated verticals resisting cloud migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure mandates and EU AI Act compliance obligations anchor demand concentration in the United States, where enterprise procurement in Texas and California technology corridors drives workflow automation adoption. Regulatory fragmentation across jurisdictions forces vendors into redundant infrastructure investments.
United States
Financial services firms in Austin and Dallas-Fort Worth accelerate workflow automation suite procurement to satisfy SEC audit trail requirements for publicly traded entities. HIPAA and FedRAMP certification timelines slow cloud migration in healthcare and government sectors. California's Bay Area and Los Angeles technology corridors concentrate SaaS engineering talent and enterprise buyer density.
Germany
Industrial Mittelstand enterprises demand project management platforms with GDPR-compliant data residency controls. The EU AI Act's risk classification framework forces conformity assessments for automated decision support in hiring contexts. Berlin and Munich host the densest clusters of enterprise software procurement committees.
India
Bangalore's SaaS engineering clusters accelerate development velocity for collaboration platforms through government-backed digital infrastructure investments. RBI and SEBI data localization norms impose sovereignty requirements on financial services deployments. Hyderabad and Pune expand as secondary hubs for technical team adoption.
United Kingdom
London's financial services sector drives demand for audit-trail-enabled reporting modules aligned with FCA disclosure expectations. GDPR compliance architecture investments compress vendor margins across European sales. The Cambridge-Oxford corridor concentrates AI-embedded productivity tool development.
Japan
Tokyo-headquartered conglomerates maintain hybrid deployment preferences balancing sovereign data controls with elastic compute needs. METI industrial digitization programs subsidize SME adoption of cloud-native productivity suites. Osaka and Nagoya manufacturing clusters resist full cloud migration due to legacy system entrenchment.
Business Productivity Software Market Vendor Landscape
Platform conglomerates and vertical specialists split the market into distinct competitive spheres. The vendor base organizes around three strategic archetypes: hyperscaler-anchored suites with deep enterprise integration, best-of-breed point solutions targeting departmental procurement, and developer-centric collaboration tools. M&A activity concentrates on AI capability tuck-ins and API-first architecture acquisitions. Geographic expansion into Bangalore and Tel Aviv engineering clusters represents the dominant competitive move.
Within the hyperscaler-anchored tier, Microsoft and Google exemplify platform breadth through office suite and cloud deployment ecosystems. Salesforce occupies a position representing AI-embedded customer relationship management convergence with revenue operations. Atlassian anchors the developer-centric specialization vector, with Jira and Confluence dominating technical team project management adoption. These three entities collectively illustrate how competitive positioning fragments across integration depth, vertical focus, and end-user technical literacy.
| Leading Market Players |
|---|
| Salesforce |
| monday.com |
| Microsoft |
| Notion |
| Smartsheet |
| Asana |
| HubSpot |
| Atlassian |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific fiber routes connecting Seattle and Mumbai shape cost dynamics for cloud infrastructure provisioning, concentrating pricing power among hyperscalers while forcing downstream vendors into tiered service differentiation across enterprise and mid-market tiers.
Pricing Analysis
Price spreads between US enterprise deployments and Indian mid-market subscriptions reflect divergent compliance architecture costs and after-sales service intensity. Subscription models dominate procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by integration depth and audit-trail certification. Cost compression in the mid-market tier is intensifying because departmental buyers unbundle suites into point solutions. Freelancers and small enterprises exhibit highest price sensitivity, while financial services firms in regulated corridors show lowest elasticity due to SEC-mandated audit requirements.
Supply Chain Analysis
US export controls on advanced GPU clusters and inference accelerators restrict flows to Bangalore and Tel Aviv engineering hubs, fragmenting AI capability development across jurisdictions. Software supply chains draw from the United States, India, and Ireland for cloud infrastructure, API middleware, and compliance tooling. Dependencies span hyperscaler compute credits, open-source framework maintenance, and zero-trust identity protocols. Single-source vulnerability concentrates in three US-based cloud providers. Distribution runs through direct enterprise sales teams, self-service product-led growth funnels, and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of engineers skilled in zero-trust identity protocols and role-based access control implementation creates a bottleneck that advantages vendors with captive training pipelines and certification partnerships.
For Market Incumbents: Build switching-cost moats through deep ERP and CRM integration that embeds workflow automation into financial reporting and customer operations. Defend against unbundling by segmenting product lines between EU-compliant and non-EU feature sets to satisfy GDPR-EU AI Act overlap without margin erosion. Prioritize FedRAMP and HIPAA certification investments to capture healthcare and government sectors resisting cloud migration. For New Entrants and Emerging Players: Pursue clinical trial documentation automation as FDA software-as-a-medical-device oversight creates white space for audit-trail-enabled productivity platforms. Target pharmaceutical research workflows and contract research organizations as the most penetrable segment. Lead with API-first architectures that embed into existing electronic data capture systems rather than displacing them. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with AI-embedded revenue operations capabilities over horizontal suite providers facing subscription fatigue. Five-to-ten-year viability hinges on inference cost structures and sovereignty-compliant deployment options. Acquisition targets should demonstrate Bangalore or Tel Aviv engineering presence and EU AI Act technical documentation readiness. Watch hyperscaler capex allocation shifts as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP and CRM embedding captures financial services automation budgets in Texas and California corridors. |
| Acquisition of Specialist Firm | AI capability tuck-ins accelerate EU AI Act compliance module development for automated decision support. |
| Geographic Expansion | Bangalore engineering clusters reduce development costs while satisfying RBI data localization for financial services. |
| Product Launch | Hybrid deployment options address HIPAA and FedRAMP certification timelines slowing healthcare cloud migration. |
| Strategic Partnership | Systems integrator alliances extend reach into government sectors with complex procurement committee requirements. |
Methodological Framework
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory frameworks preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Primary fieldwork captured deployment decision criteria across cloud-native, hybrid, and on-premises configurations. Secondary validation drew from FDA software-as-a-medical-device guidance documents, GDPR enforcement actions, and Bangalore SaaS cluster development reports. Bottom-up segment sizing triangulated against top-down market construction.
Assumptions held regulatory fragmentation intensity and hyperscaler concentration constant across the modeling period, with EU AI Act compliance timelines and SEC disclosure rule enforcement as fixed parameters. Segmentation dimensions spanned deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from elasticity-adjusted replacement cycle analysis and vendor-reported seat expansion rates. Forecast inputs incorporated API security architecture talent availability and cross-border data residency requirement proliferation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized private equity consolidators or sovereign wealth funds pursuing vertical specialization would shift outcomes. Material shifts in EU AI Act enforcement stringency or US export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Multivariate Testing Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Orchestration Tools Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Global Software Quality Assurance Market
Software & Services
Global Customer Service Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Apache Spark Market
Software & Services
LTFS Copy Software Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Vertical Software Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Global Ad Server Software Market
Software & Services
3D Animation Software Market
Software & Services
Driver Updater Software Market
Software & Services
Global Cloud Testing Market