
 Vertical Software Market | 2026-2036
Vertical Software Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Software Market Outlook
Subscription-based project finance and asset-light SaaS leasing is rewriting competitive entry barriers for mid-market vendors. Palantir Technologies leverages deep government and defense relationships to sustain premium pricing in intelligence-adjacent verticals. Veeva Systems anchors its position through pharmaceutical CRM specialization and compliance-layer integration. Procore Technologies dominates construction management by controlling field-to-office data pipelines across project lifecycles.
Vertical software denotes applications engineered for singular industry domains rather than horizontal general-purpose platforms, typically embedding sector-specific data models, regulatory logic, and workflow templates within modular architectures. These systems automate compliance reporting, supply chain coordination, and customer management functions that generic ERP cannot address without costly customization. Healthcare and manufacturing verticals lead current revenue contribution, with cloud deployment models representing the fastest-growing structural segment as enterprises retire legacy on-premises estates. SMB-targeted solutions concentrate margin pools through standardized configurations that reduce implementation overhead.
FDA 21 CFR Part 11 and HIPAA shape healthcare software validation requirements and data handling standards, while EU AI Act and GDPR impose algorithmic transparency and cross-border transfer constraints on European deployments. The SEC's cybersecurity disclosure rules now mandate incident reporting timelines that affect financial services vertical software procurement criteria. Stakeholders must monitor how divergent regulatory timetables between Washington and Brussels fragment product roadmaps and certification costs.
Market Dynamics
Cloud-native architectures are displacing legacy on-premises estates as healthcare systems and pharmaceutical networks prioritize elastic scalability over capital-intensive infrastructure ownership. This infrastructure transition concentrates procurement power among hyperscaler-backed vendors while fragmenting the long-tail of point-solution providers.
Growth Catalysts
- HIPAA compliance automation:Healthcare systems face escalating audit frequency and penalty structures, driving procurement of embedded compliance-layer platforms that automate 21 CFR Part 11 validation workflows and audit trail generation without manual configuration.
- India:The country's digital health infrastructure programs under the National Health Stack mandate interoperable electronic health records, creating standardized procurement specifications that favor modular vertical software over customized enterprise deployments.
- Edge-to-cloud data pipelines:Manufacturing verticals deploy IoT-enabled field data capture that streams directly into SaaS analytics layers, compressing project feedback loops and enabling predictive maintenance without intermediary data lakes.
Market Restraints
- Certification cost concentration:FDA 21 CFR Part 11 and EU MDR validation requirements impose six-figure compliance burdens that disproportionately constrain mid-market vendors lacking dedicated regulatory affairs functions.
- Hyperscaler dependency:Cloud deployment concentration within AWS, Azure, and Google Cloud infrastructure creates single-point-of-failure exposure and egress cost volatility that erodes SaaS margin structures.
- Legacy ERP entrenchment:SAP and Oracle horizontal platforms retain institutional procurement relationships through sunk-cost amortization, forcing vertical specialists to fund expensive migration incentives.
Strategic Opportunities
- Germany:Operational technology clusters in Baden-Württemberg and Bavaria lack unified workflow platforms connecting shop-floor systems to pharmaceutical supply chain coordination, creating white-space for MES-integrated vertical suites.
- AI Act algorithmic transparency:EU-mandated explainability requirements for clinical decision support systems favor vendors with pre-built audit interfaces, creating competitive moats against black-box competitors.
- Subscription finance convergence:Asset-light SaaS leasing models that bundle implementation, training, and compliance validation into per-seat pricing reduce customer procurement friction and accelerate sales cycles.
Industry Challenges
- Interoperability engineering scarcity:Healthcare verticals face acute shortages of HL7 FHIR implementation specialists capable of bridging legacy EHR systems with modern API-first platforms.
- Multi-jurisdiction certification lag:Simultaneous FDA, EMA, and Health Canada software validation timelines stretch 18-24 months, delaying product launches and consuming R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Software Market |
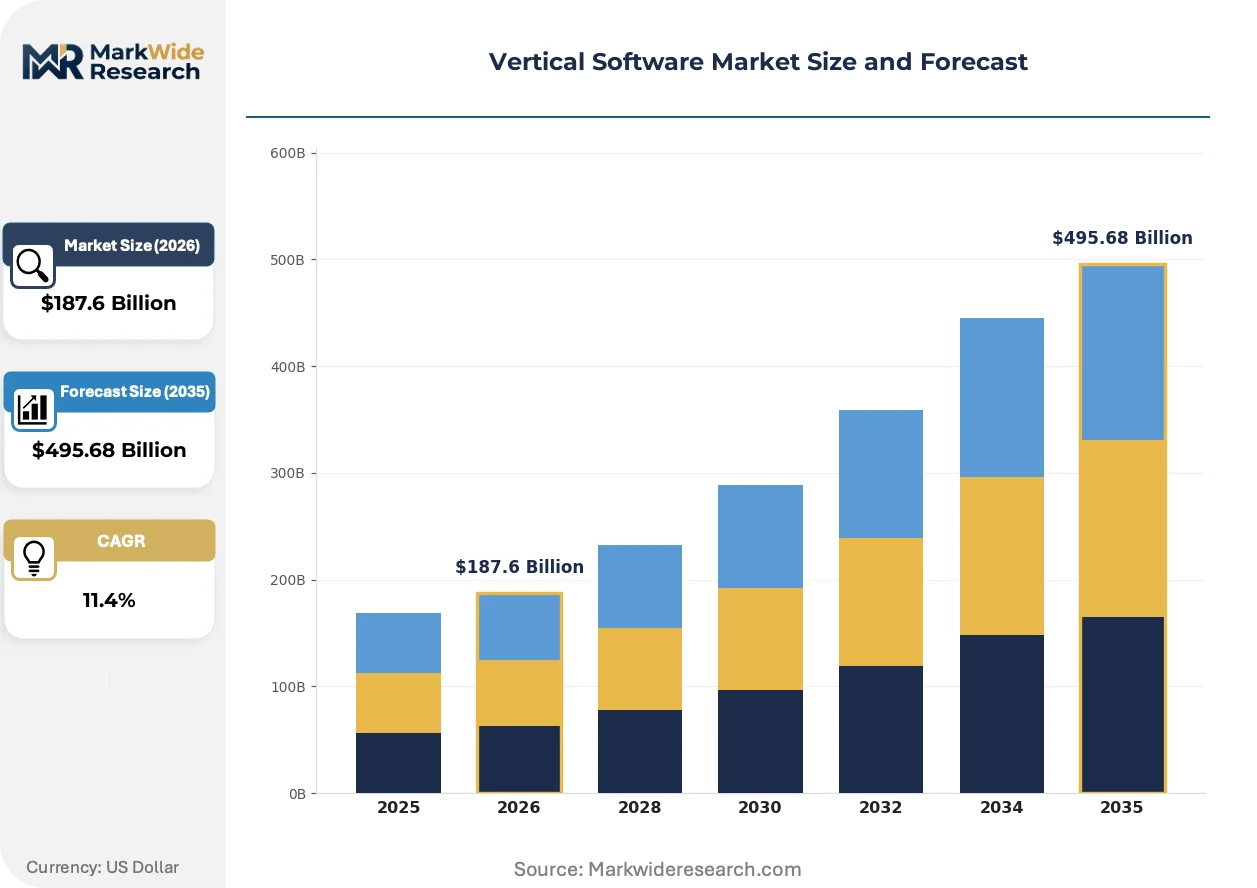
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Industry Vertical: Healthcare, Retail, Education, Manufacturing Deployment Model: On-Premises, Cloud, Hybrid, Managed Services Target Audience: SMBs, Enterprises, Startups, Non-Profits Solution Type: CRM, ERP, Project Management, Compliance |
| Companies Covered | Palantir Technologies, Sabre, Veeva Systems, Q2 Holdings, ACI Worldwide, Procore Technologies, Doximity, NCR Voyix, Toast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Software Market Strategic Shifts
Generative AI is compressing software configuration cycles while regulatory frameworks fragment across Atlantic jurisdictions. Vendors that embed compliance logic natively rather than bolting it post-hoc capture disproportionate enterprise procurement.
Low-code workflow builders are digitizing clinical pathway customization that previously required six-month implementation projects. Hospital IT departments in Texas and California deploy these tools to modify order sets and alert protocols without vendor dependency. The technology is digitizing domain expertise that historically resided in consulting engagements, collapsing implementation margins for traditional systems integrators.
EU AI Act risk classification mandates now categorize clinical decision support systems as high-risk applications requiring conformity assessment and post-market monitoring. Pharmaceutical software vendors must maintain algorithmic change logs and performance drift documentation that horizontal platforms lack. European hospital procurement committees increasingly require CE-marked AI components, filtering non-compliant vendors from shortlists regardless of functional parity.
Outcome-based contracting is replacing perpetual license models in North American hospital networks. Procurement committees in Massachusetts and North Carolina now tie vendor payments to measurable workflow efficiency gains and readmission reduction metrics. This shift concentrates vendor selection among platforms with embedded analytics capable of isolating software attribution from confounding operational variables.
Vertical Software Market Segmentation
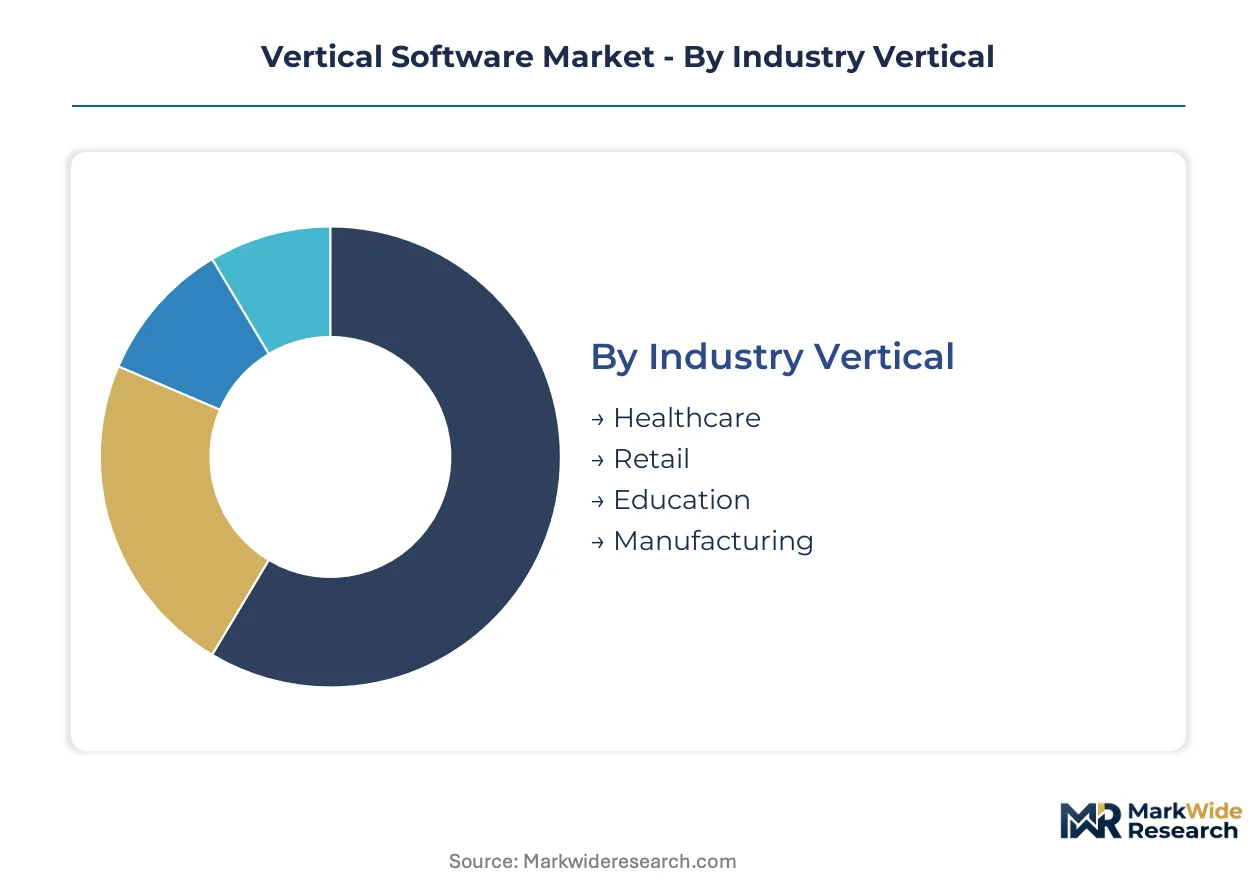
Vertical software procurement patterns diverge sharply across industry domains and infrastructure maturity. Deployment architecture choices and target customer profiles determine pricing elasticity, implementation complexity, and regulatory compliance burden for vendors competing in this space.
Industry Vertical:
Healthcare systems demand embedded audit trails and clinical workflow automation, while retail networks prioritize real-time inventory synchronization across distributed storefronts.
- Healthcare:Platforms integrate HIPAA-compliant data handling with FDA 21 CFR Part 11 validation workflows for electronic records and clinical decision support. Hospital procurement committees in Texas and Massachusetts favor modular architectures that bridge legacy EHR systems through HL7 FHIR interfaces without rip-and-replace disruption.
- Manufacturing:MES-integrated suites connect shop-floor IoT sensors to cloud analytics layers, enabling predictive maintenance and quality traceability. German operational technology clusters in Baden-Württemberg lack unified workflow platforms linking production systems to pharmaceutical supply chain coordination, creating white-space for specialized vendors.
- Retail:Omnichannel inventory management and customer data platforms dominate procurement specifications, with cloud-native architectures displacing legacy POS-integrated systems.
- Education:Student information systems and learning management platforms concentrate demand, with interoperability requirements for federal reporting standards shaping vendor selection.
The dominant share belongs to Healthcare, while Manufacturing is closing the gap fastest through IoT-enabled field data capture adoption.
Deployment Model:
Cost tier stratification separates capital-intensive infrastructure ownership from elastic subscription models that transfer operational risk to vendors.
- Cloud:SaaS architectures with multi-tenant elasticity capture disproportionate investment across North American hospital networks and European pharmaceutical supply chains. AWS, Azure, and Google Cloud infrastructure concentration creates single-point-of-failure exposure and egress cost volatility that compresses margin structures for independent software vendors.
- Hybrid:Workloads split between on-premises legacy systems and cloud analytics layers accommodate regulated data residency requirements while enabling elastic compute for non-sensitive operations. Financial services verticals in Switzerland and Singapore deploy this model to satisfy national data localization mandates without sacrificing scalability.
- On-Premises:Perpetual license models persist in defense and intelligence-adjacent verticals where air-gapped environments are mandatory.
- Managed Services:Vendor-operated private cloud deployments address mid-market customers lacking dedicated IT operations functions.
Cloud deployments command the largest revenue pool, with Hybrid architectures gaining share fastest as regulated industries navigate data sovereignty constraints.
Target Audience:
Customer type determines implementation methodology, with standardized configurations reducing overhead for smaller accounts and customized deployments capturing enterprise margin.
- Enterprises:Multi-divisional deployments require extensive integration engineering with existing ERP estates and legacy compliance systems. Procurement committees mandate proof-of-concept phases and outcome-based contracting tied to measurable efficiency metrics.
- SMBs:Standardized vertical templates with reduced configuration options accelerate time-to-value and lower total cost of ownership. India's digital health infrastructure programs under the National Health Stack create standardized procurement specifications that favor modular solutions over customized enterprise deployments for regional hospital networks.
- Startups:API-first platforms with pay-as-you-scale pricing accommodate unpredictable growth trajectories and limited capital reserves.
- Non-Profits:Grant-funded procurement cycles and donor reporting requirements shape feature prioritization and pricing negotiations.
Enterprises contribute the dominant revenue share, while SMB-targeted solutions are expanding most quickly through subscription finance convergence.
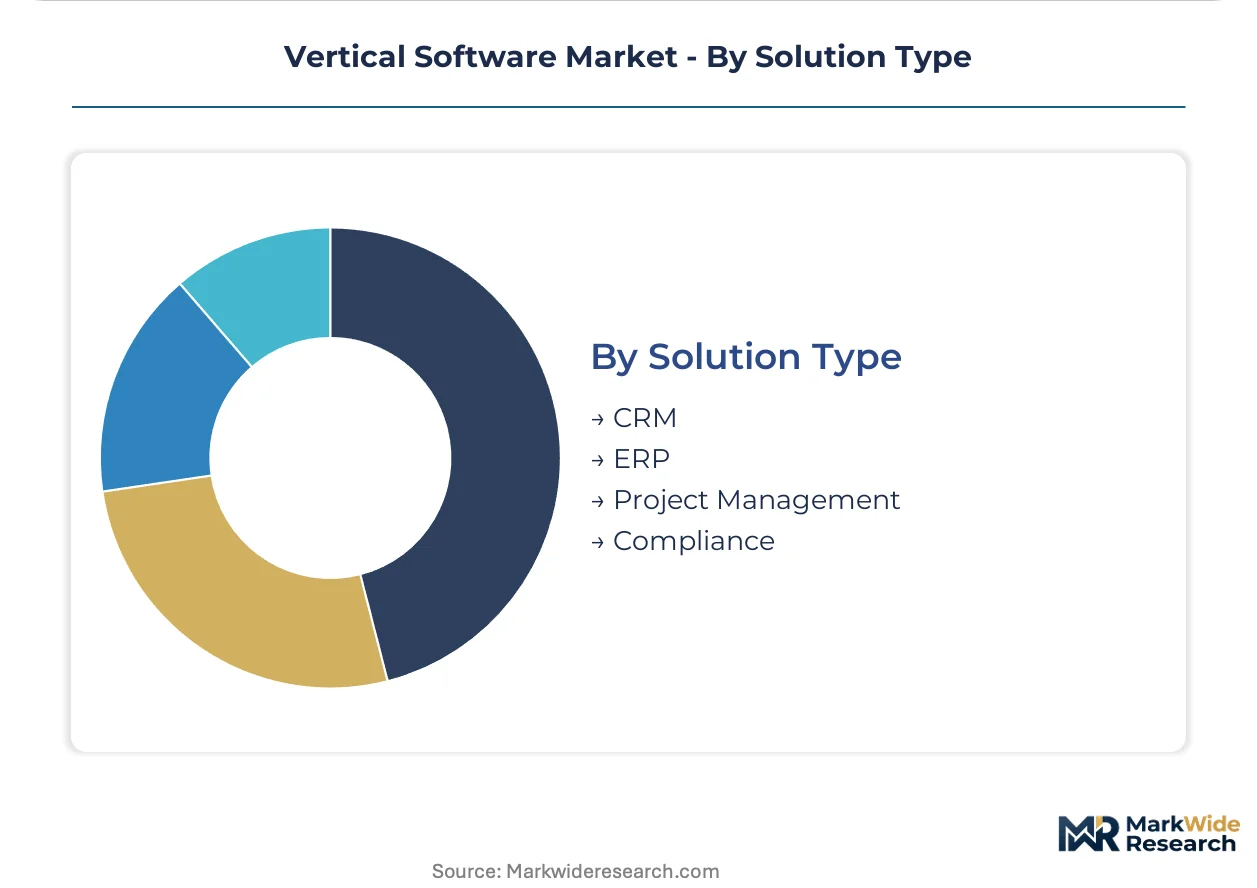
Solution Type:
Functional specialization depth determines competitive moat durability, with compliance-layer integration proving stickier than transactional workflow automation.
- Compliance:Embedded regulatory logic automates audit trail generation, validation documentation, and cross-jurisdiction certification maintenance. EU AI Act algorithmic transparency mandates for clinical decision support systems favor vendors with pre-built explainability interfaces.
- CRM:Industry-specific customer data models and engagement workflows replace generic sales force automation in pharmaceutical and financial services verticals.
- ERP:Vertical extensions to horizontal platforms address sector-specific inventory, procurement, and financial reporting requirements without full system replacement.
- Project Management:Field-to-office data pipelines capture construction and professional services coordination, with outcome-based contracting replacing perpetual licenses in North American markets.
Compliance solutions hold the dominant position, while Project Management platforms are gaining share fastest through outcome-based contracting adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and pharmaceutical supply chain operators concentrate demand in five national markets where regulatory mandates and infrastructure investment cycles intersect.
United States
Texas and Massachusetts hospital networks drive procurement of HIPAA-compliant clinical workflow platforms. FDA 21 CFR Part 11 validation requirements shape vendor selection criteria for electronic records systems. The Dallas-Fort Worth metro anchors demand for modular EHR integration tools that bridge legacy systems without disruption.
Germany
Baden-Württemberg and Bavaria operational technology clusters seek unified MES-integrated suites connecting shop-floor systems to pharmaceutical supply chains. EU AI Act algorithmic transparency mandates filter non-compliant clinical decision support vendors from procurement shortlists. Stuttgart's manufacturing base generates concentrated demand for predictive maintenance platforms with embedded compliance layers.
India
National Health Stack digital infrastructure programs mandate interoperable electronic health records for regional hospital networks. CDSCO software validation timelines extend product launch cycles for foreign vendors. Karnataka's Bengaluru tech corridor hosts domestic platform developers targeting standardized modular deployments over customized enterprise systems.
United Kingdom
NHS procurement frameworks favor cloud-native architectures with embedded GDPR compliance for patient data handling. MHRA software as medical device regulations impose post-market surveillance obligations on clinical decision support vendors. London's hospital trusts concentrate demand for outcome-based contracting models tied to measurable efficiency metrics.
Japan
PMDA software validation requirements and HL7 FHIR interoperability standards shape hospital IT procurement specifications. METI digital health infrastructure subsidies accelerate retirement of legacy on-premises estates. Tokyo-Osaka hospital networks drive adoption of SaaS analytics layers for clinical pathway optimization.
Vertical Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where hyperscaler-backed platforms capture enterprise procurement while point-solution vendors fragment across niche workflows. The vendor base stratifies into three archetypes: compliance-embedded suite providers, field-data pipeline controllers, and modular API-first platforms. M&A activity concentrates among horizontal ERP incumbents acquiring vertical specialists, while independent vendors pursue strategic partnerships with cloud infrastructure providers to defray certification costs.
Within the defense and intelligence-adjacent tier, Palantir Technologies occupies a position representing premium-priced government relationship models. Veeva Systems exemplifies pharmaceutical CRM specialization with compliance-layer integration. Procore Technologies anchors the construction management segment through field-to-office data pipeline control. These three companies represent distinct competitive archetypes: government-contracting leverage, vertical workflow depth, and project lifecycle coordination.
| Leading Market Players |
|---|
| Palantir Technologies |
| Sabre |
| Veeva Systems |
| Q2 Holdings |
| ACI Worldwide |
| Procore Technologies |
| Doximity |
| NCR Voyix |
| Toast |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in cloud infrastructure across North American and European data center clusters compresses SaaS vendor margins while intensifying price competition for enterprise contracts. This utilization dynamic forces vertical software providers to bundle compliance validation and implementation services into subscription tiers rather than extracting premium pricing for discrete modules.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 21 CFR Part 11 and EU MDR validation documentation adding substantial cost to healthcare deployments. Subscription-based SaaS models dominate enterprise procurement, though outcome-based contracting is displacing flat-rate subscriptions in hospital networks. Price differentiation hinges on embedded compliance automation and after-sales support depth. Margins are tightening due to hyperscaler egress cost volatility, with mid-market vendors facing acute pressure while government-contracting specialists maintain pricing power through relationship entrenchment.
Supply Chain Analysis
Upstream cloud infrastructure feeds from concentrated hyperscaler capacity in the United States, Ireland, and Singapore, with compute and storage resources forming the primary input layer. Software development labor pools in India, Poland, and Vietnam provide engineering capacity for implementation and customization services. Single-source vulnerability around AWS, Azure, and Google Cloud creates systemic exposure for independent vendors. Distribution runs through direct enterprise sales teams and channel partners serving mid-market accounts, with managed service providers increasingly intermediating deployment complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical software markets reward defensive moats rooted in regulatory entrenchment and customer switching costs rather than pure technology differentiation. Network effects from embedded workflow data compound these advantages over multi-year contract cycles.
For Market Incumbents: Harden compliance-layer integration to deepen switching costs, particularly embedding EU AI Act audit interfaces and FDA validation documentation natively rather than through bolt-on modules. Expand certification investment to cover simultaneous FDA, EMA, and Health Canada timelines, neutralizing mid-market competitors lacking dedicated regulatory affairs functions. Counter emerging API-first challengers by controlling field-to-office data pipelines across complete project lifecycles. For New Entrants and Emerging Players: German operational technology clusters in Baden-Württemberg and Bavaria represent the most penetrable entry point, lacking unified MES-integrated suites connecting shop-floor systems to pharmaceutical supply chains. India's standardized National Health Stack procurement specifications favor modular solutions over customized enterprise deployments for regional hospital networks. Pursue asset-light SaaS leasing models that bundle implementation and compliance validation into per-seat pricing to reduce procurement friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compliance-embedded suite providers with pre-built regulatory interfaces, as these vendors capture multi-year contracts with automatic renewal provisions. Long-term viability favors platforms with algorithmic transparency capabilities addressing EU AI Act mandates. Monitor CDSCO and PMDA software validation timeline convergence as an inflection indicator for foreign vendor market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-Layer Integration | Embedded FDA and EU AI Act logic creates switching costs that extend contract renewal rates. |
| Strategic Partnership | Hyperscaler alliances defray six-figure certification burdens for mid-market vertical specialists. |
| Geographic Expansion | German operational technology clusters lack unified MES-integrated workflow platforms. |
| Platform Integration | HL7 FHIR interfaces bridge legacy EHR systems without rip-and-replace disruption. |
| Acquisition of Specialist Firm | Horizontal ERP incumbents acquire vertical specialists to defend against modular challengers. |
Study Parameters
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with hospital procurement committee members, pharmaceutical IT directors, cloud platform engineers, and regulatory affairs specialists informed demand-side dynamics. Secondary sources include FDA 510(k) submissions, EMA qualification opinions, hyperscaler capex disclosures, and hospital GPO contract databases. Bottom-up deployment estimates and top-down market sizing triangulate to constrain forecast variance.
Calibration against historical adoption curves and regulatory implementation timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to validated baseline estimates, with cloud migration velocity and compliance automation penetration serving as primary demand-side inputs.
Stress conditions across hyperscaler pricing volatility, multi-jurisdiction certification delays, and legacy ERP entrenchment were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timetable convergence and infrastructure investment cycles. Cross-checking against hospital procurement database trends and pharmaceutical IT budget surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Stock Media Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Remote Sensing Software Market
Software & Services
Europe Business Software Market
Software & Services
Global Cloud Accounting Technology Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Content Services Platforms Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Animation Design Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
G Suite Technology Services Market