
 Global Customer Service Software Market | 2026-2036
Global Customer Service Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Service Software Market Foresight
Mid-market enterprises is rotating toward integrated cloud-native suites, displacing fragmented point solutions that dominated early digital transformation cycles. Salesforce Inc. leverages its CRM-native architecture to embed service workflows inside revenue operations. Zendesk Inc. competes through modular pricing that lowers barriers for sub-1,000-agent deployments. NICE Systems Ltd. dominates workforce optimization add-ons that deepen agent productivity metrics.
Global Customer Service Software encompasses applications that manage, route, and analyze customer interactions across synchronous and asynchronous channels, typically integrating natural language processing engines with ticket orchestration protocols to resolve inquiries at sub-minute latency targets. Cloud-Based deployment leads in new license growth while On-Premises retains stickiness in banking and insurance due to data residency mandates; Help Desk and Contact Center solutions capture the largest margin pools as they anchor broader platform contracts. Knowledge Management represents the fastest-expanding solution type as generative AI reduces article creation overhead.
The EU AI Act, GDPR, and ISO 27001 collectively mandate algorithmic transparency and cross-border data governance that elevates compliance costs for non-European vendors. The FCC in the United States enforces TCPA and robocall rules that constrain outbound engagement automation. Stakeholders must monitor how divergent AI liability frameworks between Brussels and Washington reshape R&D allocation and localization requirements.
Market Dynamics
Generative AI engines are compressing resolution timelines from minutes to seconds, forcing vendors to rebuild core architectures around large language model inference rather than traditional rule-based routing systems.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements in Brussels are accelerating procurement cycles for certified vendors as enterprises face 2025 enforcement deadlines.
- Contact center modernization in India:Domestic IT services firms are replacing legacy Avaya and Cisco installations with cloud-native stacks to support multinational client contracts.
- Real-time voice synthesis:Neural TTS engines now achieve sub-200-millisecond latency, enabling conversational AI to handle tier-one support without human escalation.
Market Restraints
- GPU compute cost volatility:NVIDIA H100 cluster pricing fluctuations are squeezing margins for AI-native vendors dependent on cloud inference.
- Data residency fragmentation:Divergent sovereignty laws across Germany, France, and Singapore are forcing redundant infrastructure builds.
- Human-in-the-loop mandates:Draft FDA guidance for healthcare customer service bots requires clinical reviewer involvement, limiting full automation.
Strategic Opportunities
- Small and medium enterprise penetration in Brazil:Under-500-agent deployments remain 70% on-premises, creating whitespace for SaaS migration.
- Convergence of CRM and service data lakes:Unified customer 360 architectures are collapsing separate procurement budgets into single platform decisions.
- Japan's METI digital transformation subsidies:2024-2026 funding pools explicitly cover contact center AI modernization for domestic manufacturers.
Industry Challenges
- Prompt engineering talent scarcity:Vendors compete for practitioners capable of tuning retrieval-augmented generation pipelines for domain-specific accuracy.
- ISO 42001 AI management system certification timelines:Sixteen-month audit cycles are delaying go-to-market for European deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Service Software Market |
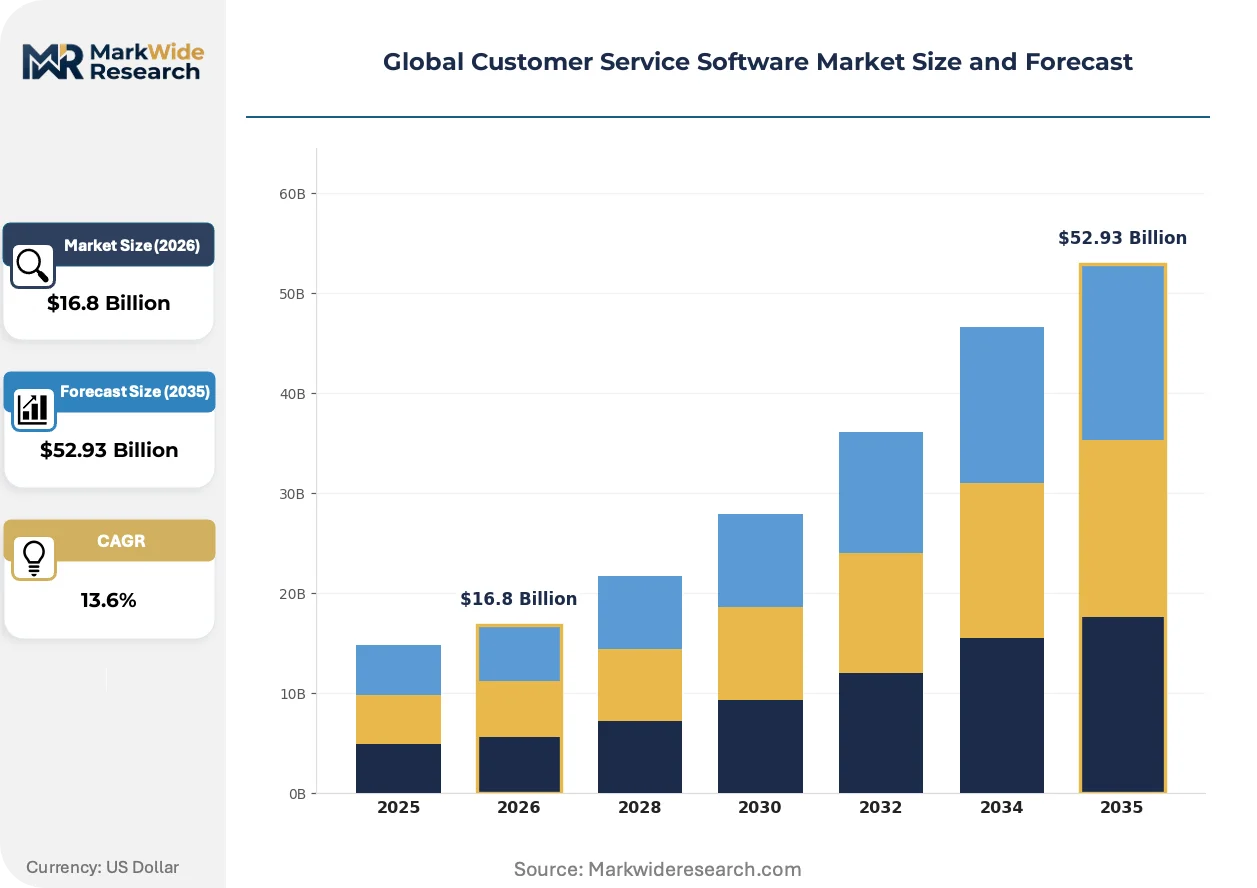
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $52.93 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Help Desk, Live Chat, Contact Center, Knowledge Management, Feedback Management Use Case: Technical Support, Query Resolution, Complaint Management, Customer Engagement, Service Automation Customer Industry: Telecommunications, E-Commerce, Banking, Travel & Hospitality, Insurance |
| Companies Covered | Microsoft Corporation, Freshworks Inc., Oracle Corporation, Genesys Telecommunications Laboratories Inc., ServiceNow Inc., SAP SE, Zendesk Inc., NICE Systems Ltd., Salesforce Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Service Software Market Shifts & Advancements
Agentic AI systems that autonomously execute multi-step resolution workflows are redefining competitive differentiation beyond static chatbot capabilities. Three forces are actively restructuring vendor priorities.
Retrieval-augmented generation stacks are displacing knowledge base search as the primary content delivery mechanism in enterprise deployments. Mid-market buyers in the United States and Germany are prioritizing RAG-native vendors in 2024 procurement cycles. This shift is compressing incumbent advantage in legacy content management and forcing point-solution vendors toward platform partnerships.
Brussels finalized its AI Act risk classification framework in early 2024, establishing binding obligations for high-risk customer service automation including bias auditing and human oversight protocols. Non-European vendors face localization costs exceeding seven figures to achieve conformity. Banking and insurance sectors in France and Italy are delaying full AI rollout until Q3 2025 to await clarified enforcement guidance from national regulators.
Subscription-to-consumption billing migration is fragmenting traditional seat-based pricing. Enterprise buyers in telecommunications and utilities are unbundling software licenses from agent headcount, instead metering by resolved interaction volume. This pattern is most advanced in the United Kingdom and Netherlands, where procurement teams have secured finance-department backing for variable cost structures tied to operational efficiency metrics.
Global Customer Service Software Market Segmentation
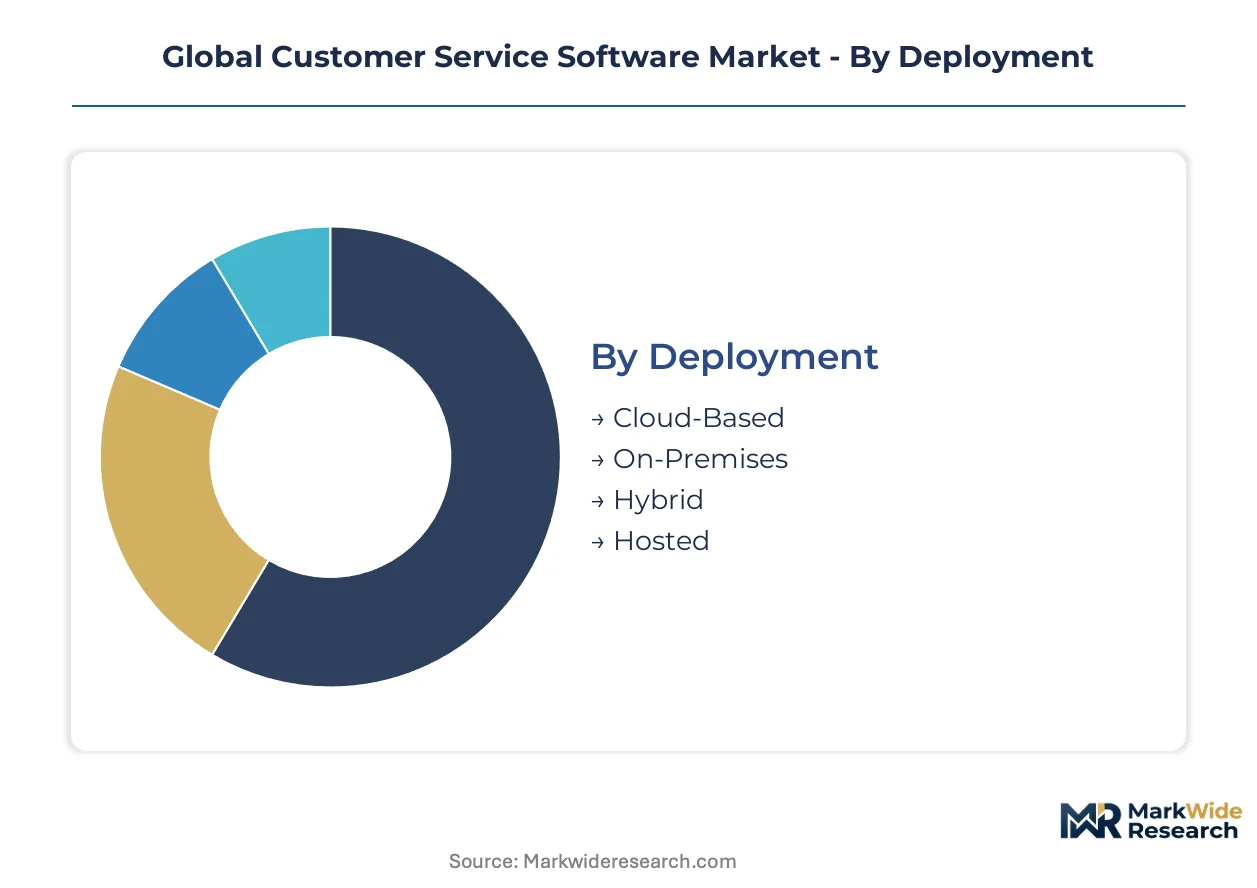
Customer service software segmentation reveals how procurement decisions split between infrastructure control and operational flexibility. Vendors architect product lines around deployment constraints, solution depth, use case complexity, and vertical compliance requirements.
Deployment:
Margin pools concentrate in cloud-native architectures where recurring revenue and lower support costs compound lifetime value.
- Cloud-Based:Multi-tenant SaaS platforms deliver elastic scaling and automatic feature updates. Banking and insurance sectors in Germany and France are migrating from on-premises stacks to meet GDPR and EU AI Act audit requirements.
- On-Premises:Single-tenant installations behind corporate firewalls satisfy data residency mandates. Indian IT services firms retain these deployments for multinational client contracts requiring jurisdictional data control.
- Hybrid:Split architectures route sensitive workloads on-premises while pushing routine interactions to cloud inference. This model dominates telecommunications carriers managing regulated subscriber data.
- Hosted:Managed private cloud deployments combine dedicated infrastructure with vendor-operated maintenance. Mid-market enterprises in the United States select this path to defer capital expenditure while preserving customization.
The dominant share belongs to Cloud-Based, while Hybrid is closing the gap fastest as sovereignty requirements fragment single-cloud strategies.
Solution Type:
Application depth determines pricing power, with integrated suites commanding premiums over point solutions.
- Help Desk:Ticket orchestration systems with SLA tracking and escalation protocols anchor enterprise procurement. E-commerce platforms in the United States and India deploy these as workflow hubs connecting agent desktops to warehouse and logistics systems.
- Contact Center:Omnichannel routing engines integrate voice, chat, and social feeds into unified queues. Workforce optimization modules from NICE Systems deepen agent productivity metrics for large-scale deployments.
- Live Chat:Synchronous messaging interfaces with typing indicators and file transfer. This segment saturates in SaaS-native verticals seeking low-friction customer touchpoints.
- Knowledge Management:Article repositories with semantic search and generative AI authoring. Generative AI compression of creation overhead is accelerating procurement cycles for RAG-native vendors.
- Feedback Management:Survey engines and sentiment analysis tools closing experience measurement loops. Travel and hospitality chains deploy these to correlate service touchpoints with loyalty metrics.
Contact Center and Help Desk together capture the largest margin pools, though Knowledge Management is expanding most quickly as generative AI reduces content production friction.
Use Case:
Automation intensity separates high-value workflows from commoditized support tiers.
- Technical Support:Complex troubleshooting requiring diagnostic data and escalation protocols. Software vendors in the United States and Germany concentrate procurement here to deflect engineering resource drain.
- Service Automation:Agentic AI executing multi-step resolution without human intervention. Neural TTS engines achieving sub-200-millisecond latency are enabling tier-one voice automation in telecommunications.
- Query Resolution:Information retrieval for account status, policy terms, and procedural guidance. Banking sectors in India deploy these at scale for retail customer bases.
- Complaint Management:Escalation workflows with regulatory documentation and remediation tracking. Insurance carriers require these for compliance with national consumer protection mandates.
- Customer Engagement:Proactive outreach and lifecycle marketing integrated with service contexts. E-commerce platforms use these to convert support interactions into retention and upsell moments.
Technical Support retains the dominant procurement volume, while Service Automation is climbing the fastest as latency thresholds enable full voice automation.
Customer Industry:
Vertical compliance requirements reshape feature roadmaps and certification priorities.
- Banking:Transaction-linked support with fraud flag integration and audit trails. EU AI Act high-risk classification mandates bias auditing and human oversight protocols for automated decision systems.
- Insurance:Policy lifecycle management with claims status and beneficiary updates. French and Italian carriers are delaying full AI rollout until national regulators clarify enforcement guidance.
- Telecommunications:Subscriber provisioning, billing disputes, and network outage communications. FCC TCPA and robocall rules constrain outbound engagement automation in the United States.
- E-Commerce:Order tracking, returns processing, and inventory-linked recommendations. Brazilian under-500-agent deployments in this vertical remain 70% on-premises, creating SaaS migration whitespace.
- Travel & Hospitality:Booking modifications, loyalty program management, and disruption rebooking. Real-time voice synthesis is displacing IVR trees for tier-one support in this segment.
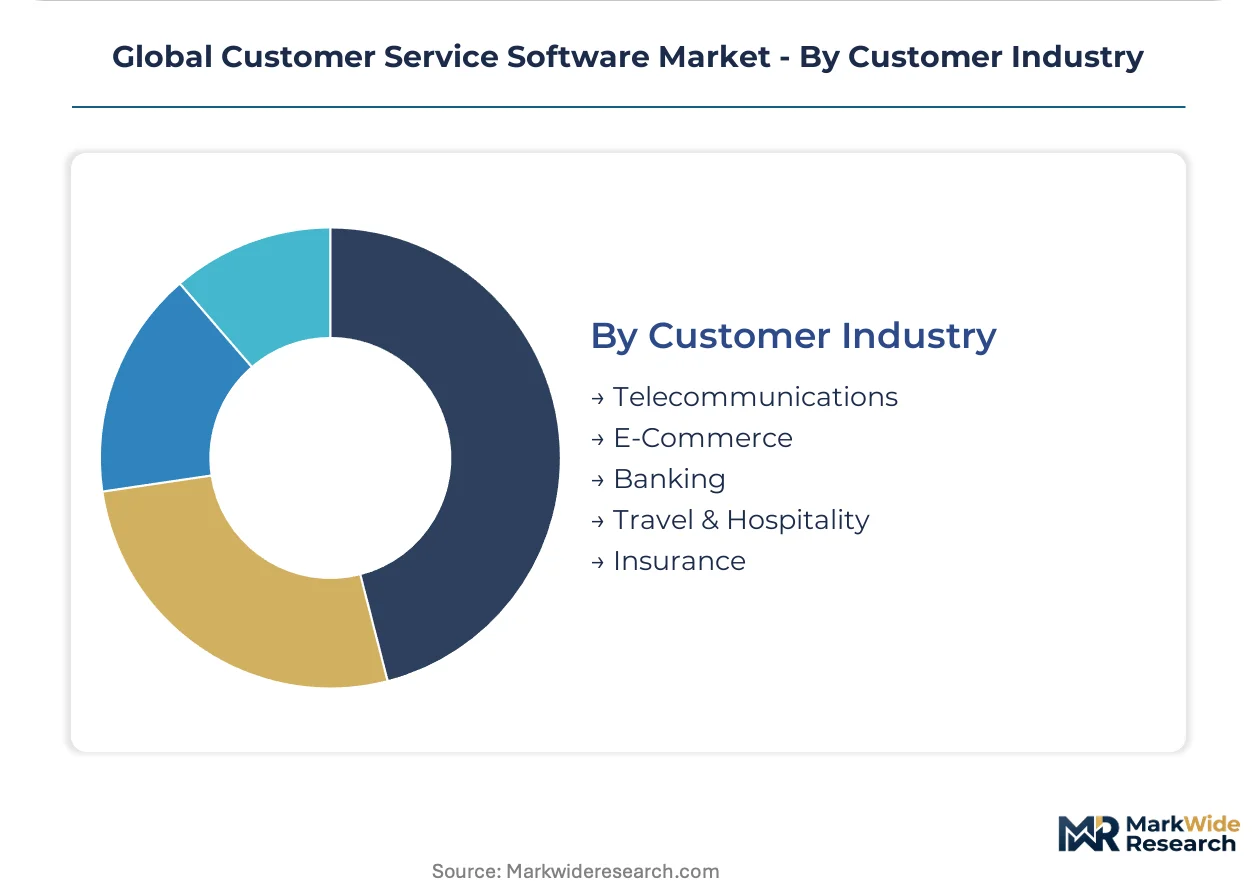
Banking and Insurance together anchor the highest-value contracts, while E-Commerce is gaining share fastest as mid-market digital commerce expands in Brazil and India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export cloud-native customer service platforms to enterprises across Germany, India, and Brazil, with cross-border data flows governed by divergent sovereignty frameworks.
United States
FCC enforcement of TCPA and robocall rules constrains outbound engagement automation for telecommunications carriers. Enterprise procurement in financial services and e-commerce concentrates agent headcount in Texas and Arizona contact center clusters. Domestic buyers prioritize consumption-based billing models that meter by resolved interaction volume rather than seat licenses.
Germany
GDPR and EU AI Act compliance mandates accelerate migration from on-premises Avaya and Cisco installations to certified cloud-native stacks. Banking and insurance sectors in Frankfurt and Munich delay full AI rollout pending clarified enforcement guidance from national regulators. Workforce optimization add-ons deepen agent productivity metrics for large-scale deployments.
India
Domestic IT services firms replace legacy infrastructure to support multinational client contracts requiring jurisdictional data control. TRAI regulations shape telecommunications subscriber provisioning and billing dispute workflows. Bangalore and Hyderabad anchor cloud migration whitespace as mid-market enterprises modernize contact center operations.
Brazil
Under-500-agent deployments remain predominantly on-premises, creating conversion opportunity for SaaS vendors. ANVISA and consumer protection mandates shape complaint management and escalation documentation requirements. São Paulo concentrates e-commerce platform demand as digital commerce expansion drives help desk procurement.
Japan
METI digital transformation subsidies explicitly cover contact center AI modernization for domestic manufacturers through 2026. Kanto and Kansai industrial corridors deploy neural TTS engines for tier-one voice automation in travel and hospitality chains. Procurement teams secure finance-department backing for variable cost structures tied to operational efficiency metrics.
Global Customer Service Software Market Competitive Landscape
Player mix skews toward CRM-native platform providers with embedded service workflows. Market structure exhibits tiered consolidation where large-suite vendors anchor enterprise procurement while modular specialists capture mid-market share. Strategic archetypes include CRM-integrated platform providers, workforce optimization specialists, and RAG-native knowledge management vendors. Competitive moves center on portfolio diversification into adjacent CX modules and geographic expansion through localized compliance certification.
Among CRM-native platform providers, Salesforce Inc. and Microsoft Corporation exemplify the integrated-suite archetype that collapses separate procurement budgets into single platform decisions. Zendesk Inc. occupies a position within the modular-pricing tier that lowers barriers for sub-1,000-agent deployments. NICE Systems Ltd. anchors the workforce optimization specialization where agent productivity metrics deepen platform stickiness for large-scale contact center operations.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Freshworks Inc. |
| Oracle Corporation |
| Genesys Telecommunications Laboratories Inc. |
| ServiceNow Inc. |
| SAP SE |
| Zendesk Inc. |
| NICE Systems Ltd. |
| Salesforce Inc. |
| Others |
Supply & Pricing Matrix
Neural TTS engine substitution for legacy IVR infrastructure simultaneously redistributes supply geography toward cloud inference clusters and compresses pricing premiums for voice automation tiers. This hardware-to-software transition collapses capital expenditure barriers for mid-market buyers while elevating operational expenditure exposure to GPU compute volatility.
Pricing Analysis
Next-generation agentic AI platforms command 40-60% premiums over current-generation rule-based routing systems, while prior-generation on-premises licenses face steep discounting as cloud migration accelerates. Three-tier pricing structure across enterprise, mid-market, and small-business levels reflects deployment complexity and GDPR certification status. Pricing pressure stems from NVIDIA H100 cluster cost volatility squeezing AI-native vendor margins. Small-business buyers exhibit highest price sensitivity, while banking and insurance sectors prioritize compliance certification over unit cost.
Supply Chain Analysis
Inventory compression for GPU accelerators has shortened procurement lead times from 26 weeks to 8 weeks as supply chain constraints ease. Cloud infrastructure concentrates in the United States, Ireland, and Singapore for data residency compliance. Raw material dependencies center on NVIDIA H100/H200 accelerators, high-bandwidth memory modules, and specialized optical interconnects. Single-source vulnerability around NVIDIA's foundry partnerships represents the dominant structural risk. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with consumption-based metering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment models and compliance jurisdictions creates niche opportunities for specialized vendors as mid-market buyers reject one-size-fits-all platform consolidation.
For Market Incumbents: Fortify platform stickiness through embedded workforce optimization modules that deepen agent productivity metrics and raise switching costs. Accelerate ISO 42001 AI management system certification to preempt European procurement delays. Defend against RAG-native knowledge management specialists by acquiring article-generation capabilities or forming strategic platform partnerships. For New Entrants and Emerging Players: EU AI Act fast-track certification for high-risk customer service automation creates immediate procurement access in Frankfurt and Munich banking corridors. Target Brazilian under-500-agent e-commerce deployments where 70% on-premises stickiness creates SaaS migration whitespace. Lead with consumption-based billing models that align vendor incentives with operational efficiency outcomes. For Investors and Strategic Acquirers: The market sits at a consolidation-early phase that favors workforce optimization specialists and RAG-native knowledge management platforms with demonstrated European compliance. Long-term viability hinges on agentic AI execution capabilities and hyperscaler partnership depth. Monitor GPU cost normalization as the inflection signal for AI-native vendor margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CRM and service data lakes into single procurement decisions for enterprise buyers. |
| Acquisition of Specialist Firm | Adds RAG-native knowledge management or workforce optimization capabilities to fill portfolio gaps. |
| Geographic Expansion | Establishes certified cloud regions in Germany and France to satisfy GDPR and EU AI Act mandates. |
| Strategic Partnership | Secures preferred GPU allocation agreements with hyperscalers to stabilize inference costs. |
| Product Launch | Introduces agentic AI systems with sub-200-millisecond voice synthesis for tier-one automation. |
Research Methodology
Cross-validation between primary interviews with CTOs, IT procurement officers, contact center operations directors, and platform integration specialists anchors the qualitative findings in practitioner-validated demand patterns. Secondary sources include SEC 10-K filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and TRAI regulatory circulars. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates across the analysis window.
Sensitivity analysis around GPU cost trajectories and compliance timeline slippage tests forecast robustness across deployment model, organization size, vertical industry, and regional adoption pattern segmentation. CAGRs derive from logistic diffusion curves fitted to historical cloud migration patterns and forward procurement intention surveys. Model inputs incorporate workforce optimization attach rates and generative AI feature adoption velocity by customer industry.
Decision-makers should treat outputs as directional under stable regulatory enforcement and normalized semiconductor supply assumptions; material deviation would warrant model refresh. Specific risk factors include divergent AI liability frameworks between Brussels and Washington, unexpected data residency fragmentation, and human-in-the-loop mandate expansion into additional sectors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Strategy Management Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Multi-Cloud SDN Market
Software & Services
Tag Management Software Market
Software & Services
Global Open Source Services Market
Software & Services
Global Membership Management Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Global Address Verification Software Market
Software & Services
Device Tracking Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Global Application Management Services Market
Software & Services
Global Permit Management Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
Global Mobile Application Market
Software & Services
Push Notifications Software Market
Software & Services
Global Time and Attendance Management Software Market