
 Webrtc Market | 2026-2036
Webrtc Market Size, Share, and Industry Trends Forecast 2026-2036
Webrtc Market Outlook
North American cloud infrastructure expansion is reshaping WebRTC service delivery models. Twilio Inc. leverages its programmable communications platform to anchor developer-centric deployment across enterprise verticals. Cisco Systems Inc. sustains market presence through integrated security architectures in unified communications. Agora competes aggressively on low-latency optimization for live streaming and interactive broadcast scenarios.
WebRTC (Web Real-Time Communication) denotes an open-source framework enabling browser-based peer-to-peer audio, video, and data transmission without proprietary plugins, operating through standardized JavaScript APIs and SRTP encryption protocols. Its primary commercial purpose centers on embedding real-time collaboration directly into web and mobile applications. Cloud-based deployment leads segment value generation due to elastic scaling economics and reduced capital overhead for enterprise buyers. Telehealth application demand is accelerating fastest among vertical use cases, propelled by reimbursement parity regulations and remote care infrastructure mandates. The corporate end-user category occupies the dominant margin pool, though small business adoption is widening as API-first platforms lower integration barriers.
FCC net neutrality rulings and HIPAA security rule enforcement shape how U.S.-based providers architect data routing and consent management for healthcare deployments. EMA guidance on remote patient monitoring and GDPR Article 32 technical safeguards create divergent compliance obligations across Atlantic markets. Stakeholders must monitor emerging spectrum allocation decisions and cross-border data localization statutes that could fragment interoperability standards.
Market Dynamics
Browser-native encryption protocols and SRTP standardization are compressing deployment timelines for real-time communications infrastructure, forcing legacy plugin-dependent architectures into rapid obsolescence across enterprise software stacks.
Growth Catalysts
- HIPAA Security Rule enforcement:Healthcare providers in the United States face mandatory technical safeguards for telehealth data transmission, accelerating compliant WebRTC adoption across hospital systems and remote care platforms.
- API-first platform economics:Developer-centric deployment models reduce integration barriers for small and mid-sized enterprises, expanding addressable market penetration beyond Fortune 500 deployments.
- Reimbursement parity regulations:Medicare and Medicaid payment equivalence for virtual consultations in the United States creates direct revenue incentives for telehealth WebRTC implementations.
Market Restraints
- Cross-border data localization statutes:Fragmented sovereignty requirements across EU member states and emerging economies force redundant infrastructure duplication, inflating operational overhead for global service providers.
- Legacy PSTN interconnection costs:Bridge services to circuit-switched networks impose per-minute termination fees that erode margin structures for browser-native calling applications.
- Browser vendor implementation variance:Inconsistent WebRTC codec support between Chrome, Safari, and Firefox creates client-side compatibility engineering burdens.
Strategic Opportunities
- India's digitization mandates:The country's national health stack and rural broadband expansion create greenfield deployment potential for low-bandwidth-optimized telehealth infrastructure.
- EU AI Act compliance tooling:Real-time transcription and sentiment analysis services face new transparency requirements, opening demand for explainable-AI-layered WebRTC platforms.
- Industrial IoT convergence:Integration of WebRTC data channels with OPC-UA and MQTT protocols enables remote equipment diagnostics and augmented-reality field support in manufacturing verticals.
Industry Challenges
- WebRTC engineering talent scarcity:Specialized expertise in ICE negotiation, STUN/TURN server optimization, and congestion control algorithms commands premium compensation, constraining development velocity for mid-market vendors.
- GDPR Article 32 technical implementation:Encryption key management and breach notification timelines for real-time streams require architectural investments that delay product launches by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Webrtc Market |
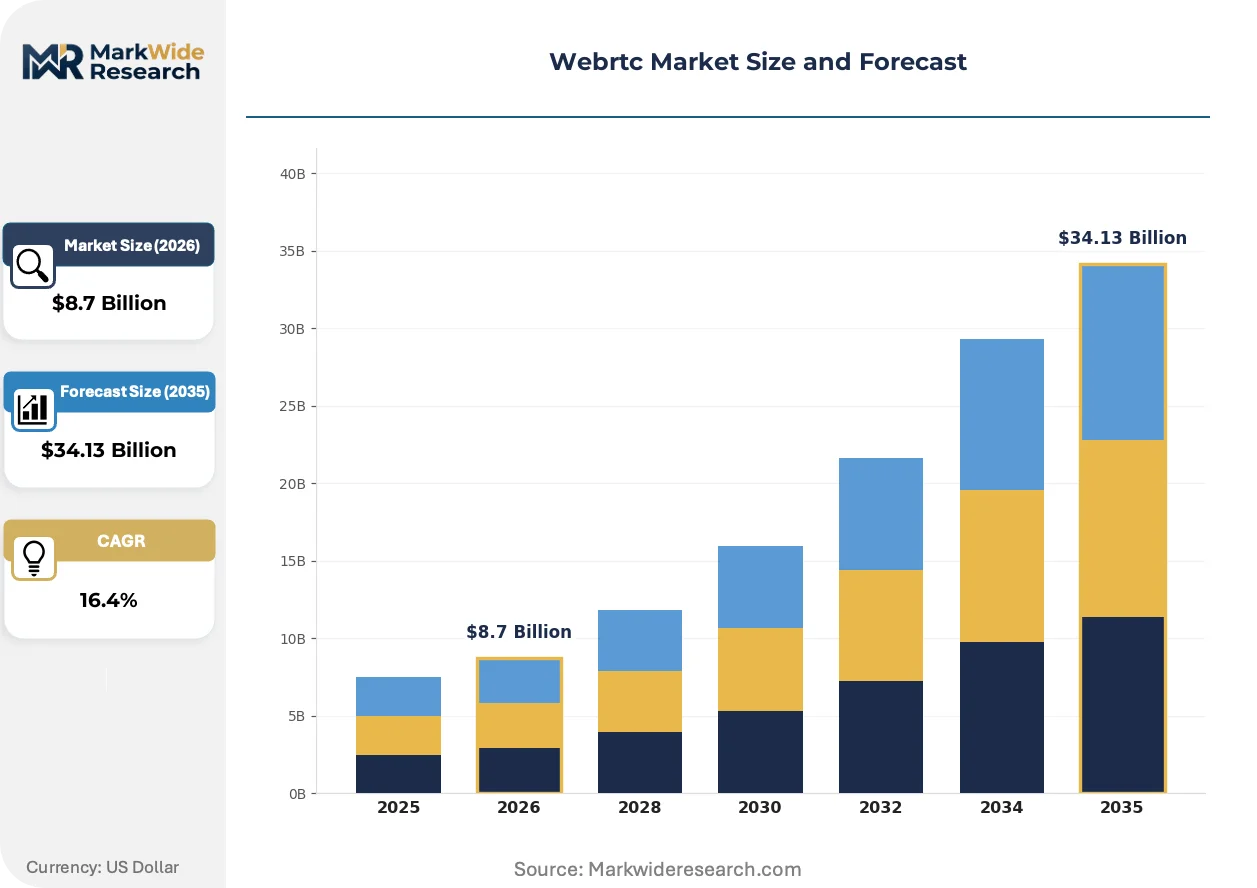
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Video Conferencing, Online Learning, Telehealth, Live Streaming Industry Vertical: Healthcare, Education, Entertainment, Telecommunications End User: Corporate, Small Business, Individual, Government |
| Companies Covered | Twilio Inc., AT&T Inc., Agora, Cisco Systems Inc., Daily.co, Avaya Inc., Vonage Holdings Corp., Oracle Corporation, WebRTC.ventures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Webrtc Market Strategic Shifts
Edge computing architectures and AI-accelerated media processing are redistributing computational loads away from centralized cloud infrastructure, compressing latency budgets and enabling new interactive use cases previously constrained by round-trip delays.
AV1 codec deployment is rendering obsolete H.264 and VP8 compression standards for bandwidth-constrained environments. Telehealth platforms serving rural broadband markets are adopting AV1 at accelerated pace to maintain video quality below 500kbps thresholds. This migration is rendering obsolete hardware-accelerated encoding investments tied to legacy codec royalties.
The EU AI Act's risk classification framework for biometric identification systems imposes conformity assessment obligations on emotion-recognition and speaker-verification features embedded in WebRTC applications. Platform providers must maintain technical documentation and human oversight protocols for high-risk AI functions. Healthcare and financial services deployments across Germany, France, and the Netherlands face the steepest compliance engineering requirements.
Enterprise procurement teams are consolidating vendor relationships for unified communications, collapsing point-solution WebRTC contracts into platform-wide agreements with Microsoft Teams, Cisco Webex, or Zoom. Channel partners and independent software vendors face margin compression as direct enterprise sales teams capture larger deal values. This concentration is most visible in United States Fortune 1000 accounts, where CIO-led standardization initiatives favor integrated security architectures over best-of-breed point solutions.
Webrtc Market Segmentation
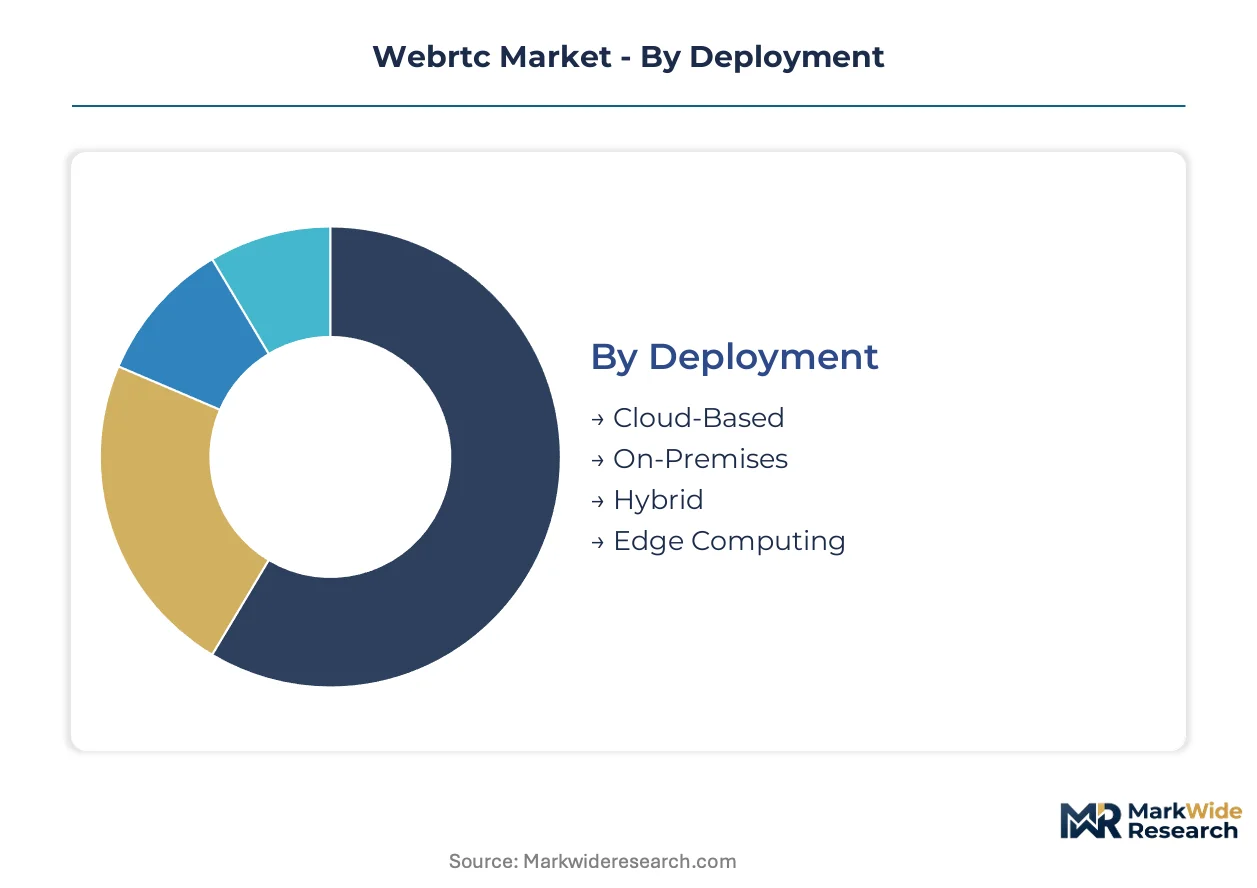
WebRTC deployment patterns diverge sharply across infrastructure preferences, use-case requirements, and regulatory exposure. Segmentation reveals how telehealth reimbursement rules in the United States, GDPR encryption mandates in Germany, and India's rural broadband expansion each reshape vendor prioritization and customer procurement criteria.
Deployment:
Use-case spectrum spans elastic scaling for viral consumer applications to air-gapped sovereignty for classified government communications.
- Cloud-Based:Elastic infrastructure enables automatic scaling during traffic spikes for live streaming events and viral telehealth consultations. United States healthcare providers favor this model to satisfy HIPAA Business Associate Agreement requirements without capital-intensive data center builds.
- On-Premises:Dedicated hardware deployments satisfy data residency requirements for German financial institutions and Saudi government entities. Fixed infrastructure costs amortize across high-volume contact centers with predictable 24/7 utilization patterns.
- Hybrid:Split architectures route sensitive signaling through controlled premises while offloading media relay to distributed cloud points of presence.
- Edge Computing:Sub-50ms latency targets for AR-assisted field maintenance and remote surgical consultation drive micro-datacenter deployments at network peripheries.
Established volume favors Cloud-Based; emerging adoption favors Edge Computing.
Application:
Cost tier differentiation separates premium real-time collaboration from commodity broadcast ingestion.
- Video Conferencing:Browser-native meeting platforms dominate corporate procurement with integrated calendar and document collaboration. United States enterprise IT departments consolidate vendor relationships around Microsoft Teams and Cisco Webex, compressing margins for standalone WebRTC providers.
- Telehealth:Reimbursement parity regulations in the United States create direct revenue incentives for HIPAA-compliant virtual care platforms. Medicare and Medicaid payment equivalence accelerates hospital system adoption across rural broadband markets.
- Online Learning:Synchronous classroom tools integrate assessment analytics and breakout room management for K-12 and higher education institutions.
- Live Streaming:Interactive broadcast scenarios demand sub-second latency for auction platforms and gaming spectator experiences.
Corporate procurement concentrates in Video Conferencing; regulatory tailwinds accelerate Telehealth most steeply.
Industry Vertical:
Customer type maturity separates regulated infrastructure buyers from experimental technology adopters.
- Healthcare:FDA-regulated remote patient monitoring and EMA-compliant telemedicine platforms require audit trails and encryption key escrow. German hospital networks and United States health systems drive compliance tooling investments across vendor roadmaps.
- Education:GDPR Article 32 technical safeguards and FERPA student privacy rules constrain platform selection for European and North American institutions.
- Entertainment:Interactive live events and fan engagement platforms prioritize low-latency optimization over security certification depth.
- Telecommunications:Carrier-grade WebRTC interconnection with legacy PSTN networks imposes per-minute termination cost structures that erode margin for browser-native calling applications.
Procurement sophistication peaks in Healthcare; Entertainment verticals expand addressable market breadth fastest.
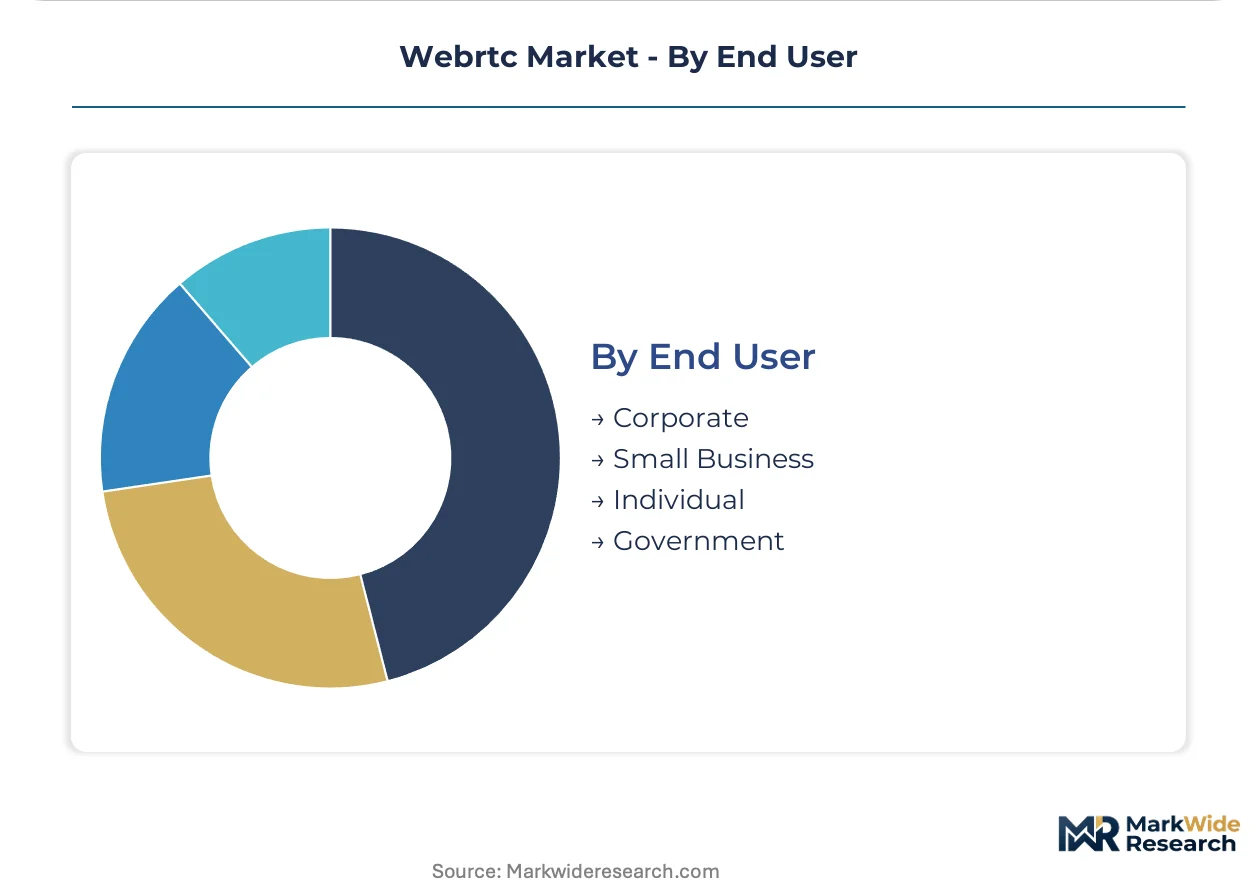
End User:
Margin concentration tracks organization scale and integration complexity.
- Corporate:Fortune 1000 enterprises demand SOC 2 Type II certification, custom SLA negotiations, and dedicated customer success management. CIO-led standardization initiatives in the United States collapse point-solution contracts into platform-wide agreements with integrated security architectures.
- Small Business:API-first platforms and no-code embedding tools reduce integration barriers, widening penetration beyond developer-intensive deployment models.
- Individual:Consumer-grade applications monetize through freemium conversion and in-app purchases rather than subscription contracts.
- Government:FedRAMP authorization in the United States and NATO information assurance certification impose 12-18 month procurement timelines with substantial compliance engineering overhead.
Revenue yield concentrates in Corporate; Small Business segments expand API consumption volume most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC net neutrality rulings and HIPAA security rule enforcement in the United States anchor demand patterns for compliant real-time communications infrastructure. National digitization programs and data localization statutes across Germany, India, China, and Brazil reshape vendor deployment strategies and procurement criteria.
United States
Enterprise digital transformation and healthcare modernization initiatives drive cloud-based WebRTC adoption. Medicare and Medicaid reimbursement parity for virtual consultations accelerates hospital system procurement. Silicon Valley and Seattle technology clusters concentrate developer-centric platform engineering for API-first deployment models.
Germany
Industrial IoT convergence and remote equipment diagnostics expand manufacturing use cases for low-latency data channels. GDPR Article 32 technical safeguards and BSI IT-Grundschutz standards impose encryption key management requirements. Munich and Stuttgart automotive clusters integrate WebRTC into augmented-reality field support systems for production line maintenance.
India
National health stack digitization and rural broadband expansion under the BharatNet program create greenfield telehealth opportunities. TRAI net neutrality guidelines and impending data protection legislation shape cross-border routing architectures. Bangalore and Hyderabad technology corridors host engineering centers optimizing codecs for sub-500kbps bandwidth environments.
China
MIIT spectrum allocation decisions and cybersecurity law data localization mandates force redundant infrastructure builds for foreign service providers. Yangtze River Delta manufacturing hubs adopt WebRTC data channels for OPC-UA protocol integration in smart factory deployments. Shanghai and Shenzhen dominate domestic platform development for live streaming and interactive broadcast applications.
Brazil
ANVISA regulatory frameworks for remote patient monitoring and LGPD compliance requirements accelerate healthcare platform investments. São Paulo and Rio de Janeiro financial services clusters deploy WebRTC for video-enabled customer authentication and digital banking interfaces. National broadband plan expansion into northern states widens addressable market penetration beyond southeastern industrial concentrations.
Webrtc Market Competitive Environment
Capability concentration sits with specialized low-latency engineering firms; scale advantage sits with diversified cloud communications platforms. The vendor base stratifies across three tiers: programmable API platforms serving developer ecosystems, integrated unified communications suites targeting enterprise IT consolidation, and vertical-specific telehealth specialists optimizing for regulatory compliance. Dominant competitive moves include strategic partnerships with electronic health record vendors and geographic expansion through local data center builds to satisfy data residency requirements.
Among United States-based platform providers, Twilio Inc. and Cisco Systems Inc. exemplify divergent strategic archetypes. Twilio anchors the developer-centric tier with programmable communications infrastructure. Cisco occupies the integrated security architecture position within unified communications procurement cycles. Agora represents the specialized low-latency optimization tier competing aggressively on interactive broadcast scenarios. Oracle Corporation and Avaya Inc. sit within legacy enterprise communications migration pathways, bridging circuit-switched infrastructure toward browser-native standards.
| Leading Market Players |
|---|
| Twilio Inc. |
| AT&T Inc. |
| Agora |
| Cisco Systems Inc. |
| Daily.co |
| Avaya Inc. |
| Vonage Holdings Corp. |
| Oracle Corporation |
| WebRTC.ventures |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific fiber cable routes between Los Angeles and Tokyo compress latency premiums for real-time media relay while amplifying cost differentiation between cloud-native and on-premises deployment tiers. This corridor's bandwidth economics concentrate pricing power with hyperscale infrastructure operators serving Fortune 1000 enterprises, while forcing mid-market vendors toward API-first consumption models that trade margin for volume access.
Pricing Analysis
Geographic price spreads of 40-60% separate North American enterprise contracts from emerging market deployments. Three-tier pricing structure across premium SOC 2-certified, standard HIPAA-compliant, and economy self-serve tiers dominates the market. Price differentiation rests on encryption key escrow capabilities and dedicated TURN server provisioning. Pricing pressure stems from API commoditization as Twilio and Agora race to capture developer mindshare. Small business segments exhibit highest price sensitivity, while government and healthcare buyers prioritize compliance depth over unit cost.
Supply Chain Analysis
Tariff exposure between United States and Chinese semiconductor manufacturing dominates supply chain risk planning for WebRTC hardware acceleration components. Component sourcing concentrates in Taiwan for advanced encoding chipsets, South Korea for memory modules, and United States for specialized signaling processors. Raw material dependencies span silicon wafers, rare earth elements for magnetic components, and high-purity copper for data center interconnects. Single-source vulnerability persists for AV1 hardware encoders. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels with minimal intermediary layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
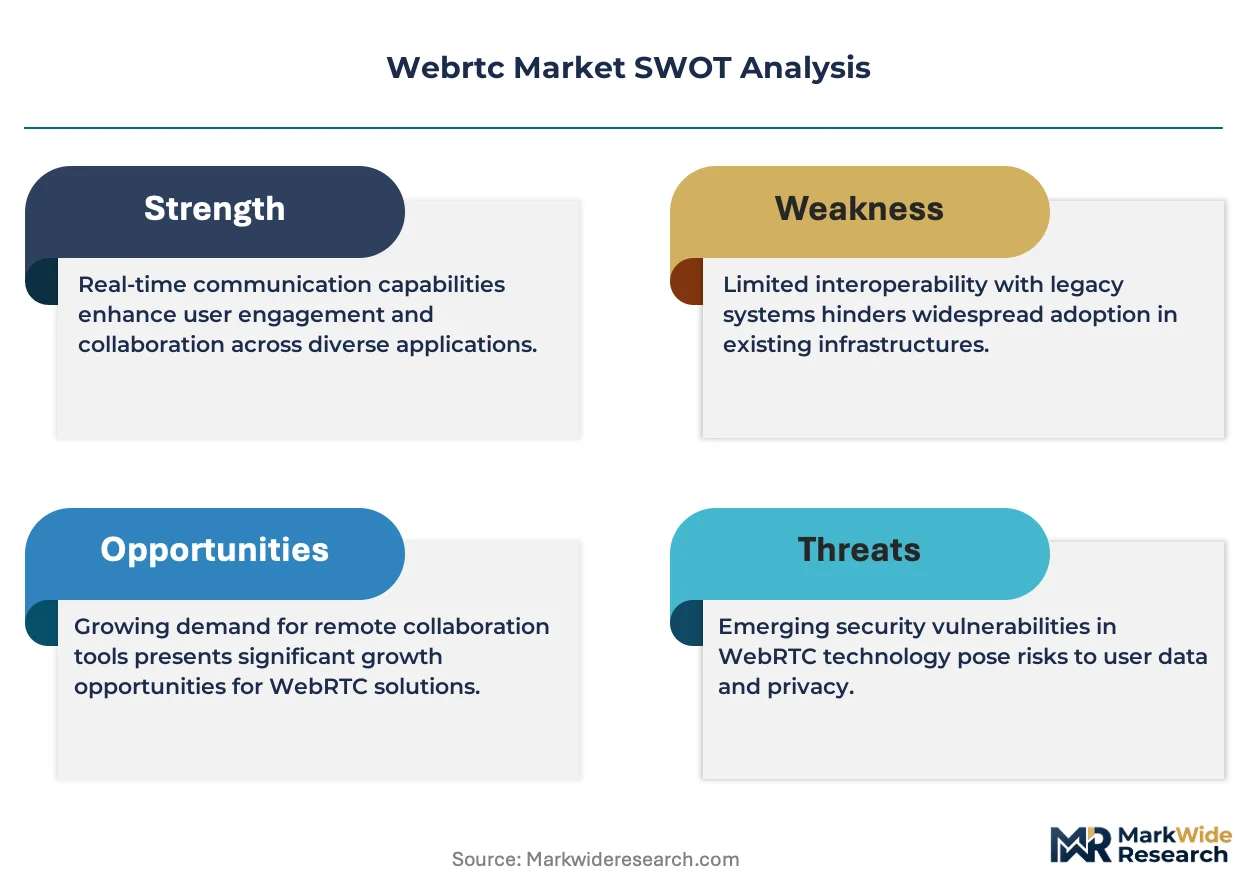
WebRTC incumbents face substitution pressure from proprietary real-time platforms embedded within Microsoft Teams and Zoom, requiring defensive architecture investments to maintain standalone relevance.
For Market Incumbents: Entrench through backward integration into edge computing infrastructure and captive certification tooling for EU AI Act compliance. Cisco and Twilio must defend against platform consolidation by embedding WebRTC deeper into electronic health record workflows. Priority lever centers on STUN/TURN server optimization patents that lock in latency-sensitive telehealth deployments.
For New Entrants and Emerging Players: Build out specialized low-latency offerings for India's rural broadband expansion under BharatNet, where incumbent presence remains thin. White-space opportunity concentrates in sub-500kbps codec optimization for telehealth in bandwidth-constrained markets. Go-to-market angle should emphasize no-code embedding tools that bypass developer talent scarcity.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy unified communications vendors with stranded PSTN interconnection assets and established healthcare compliance certifications. Long-term viability hinges on AI-augmented media processing capabilities that escape commodity API pricing. Signal to watch is AV1 hardware encoder supply availability as inflection indicator for codec migration velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Buildout | Sub-50ms latency targets enable AR-assisted surgical consultation and remote equipment diagnostics. |
| EU AI Act Compliance Tooling | Explainable-AI-layered platforms capture German and French healthcare procurement requiring conformity assessment. |
| Electronic Health Record Integration | Epic and Cerner partnerships lock in hospital system switching costs against platform consolidation. |
| AV1 Codec Migration Investment | Rural broadband telehealth deployments in India and Brazil demand sub-500kbps video quality maintenance. |
| API-First Developer Ecosystem Expansion | No-code embedding tools widen small business penetration beyond developer-intensive deployment models. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FCC rulings, EMA guidance documents, TRAI net neutrality guidelines, and hyperscaler capex disclosures. Primary interviews engaged platform engineering directors at cloud communications providers, telehealth procurement officers at United States hospital systems, regulatory affairs leads navigating GDPR Article 32 implementation, and integration specialists at electronic health record vendors. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs span deployment model adoption curves, vertical regulatory tailwinds, and codec migration timelines. Segmentation dimensions include infrastructure preference, application use case, industry vertical compliance depth, and end-user organization scale. CAGRs derive from elasticity-adjusted demand curves and technology substitution rates. Industry-specific inputs incorporate HIPAA reimbursement parity enforcement patterns and EU AI Act risk classification rollout velocity.
Sensitivities concentrate around spectrum allocation decisions, cross-border data localization statute expansion, and AV1 hardware encoder supply constraints. Forecasts reflect documented assumptions subject to revision from regulatory enforcement intensity and platform consolidation momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Dating Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Desktop Virtualization in Manufacturing Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Decision Support System Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Shipping Software Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Virtual Hiring Tools Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Data As a Service (Daas) Market