
 Global Jewelry Store Management Software Market | 2026-2036
Global Jewelry Store Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Jewelry Store Management Software Market Foresight
The gap between premium enterprise suites and entry-level point solutions is shifting as mid-market jewelers demand hybrid deployment flexibility without sacrificing analytics depth. Lightspeed Retail leverages its retail-native architecture to anchor cloud-based inventory workflows for independent stores. Shopify competes through embedded e-commerce synchronization that unifies online and physical channels. Square differentiates by controlling payment-hardware integration, reducing friction at the point of sale.
Jewelry store management software encompasses cloud, on-premises, hybrid, and SaaS deployment architectures that integrate inventory tracking, customer relationship management, point-of-sale processing, analytics, and staff scheduling into unified retail operating systems. These platforms typically employ real-time database synchronization across multiple store locations, with API-first designs enabling connectivity to gemological testing equipment and supplier portals. Cloud-based deployment leads current adoption among independent jewelers and online sellers seeking lower capital overhead, while subscription-based pricing dominates revenue models as vendors prioritize recurring revenue predictability over one-time license transactions.
The United States Federal Trade Commission enforces jewelry advertising standards that mandate accurate gemstone disclosure, compelling software vendors to embed certified inventory descriptors directly into product databases. Europe's GDPR and PCI-DSS requirements in North America shape data architecture decisions, particularly for customer relationship management modules handling biometric payment authentication and loyalty profiles. Stakeholders must evaluate whether hybrid deployment investments justify compliance automation gains as regulatory fragmentation between jurisdictions intensifies vendor certification burdens.
Market Dynamics
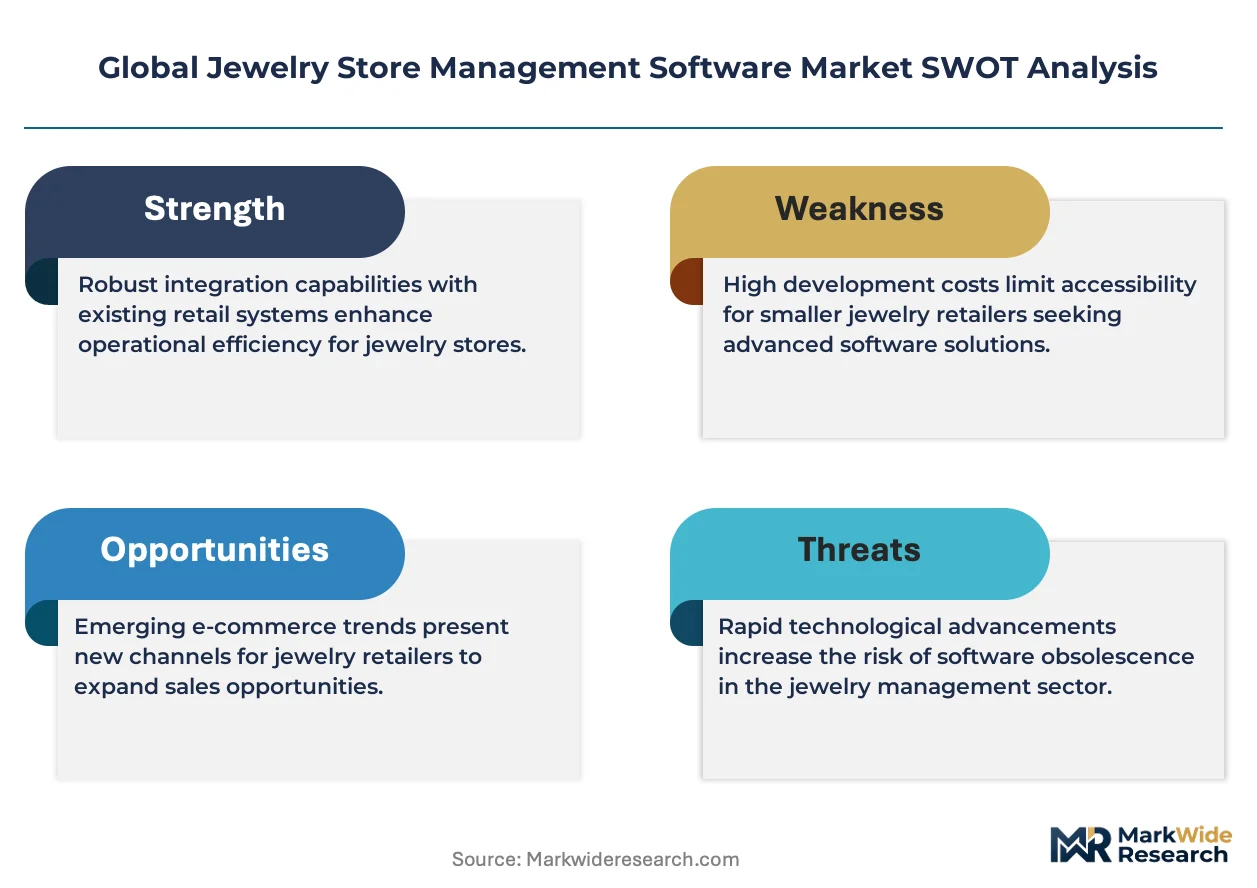
Cloud-native architectures are compressing deployment cycles for independent jewelers while PCI-DSS and GDPR mandates force simultaneous compliance investments across customer data modules.
Growth Catalysts
- GDPR-driven data governance:European jewelers are upgrading CRM systems to embed automated consent management and biometric payment authentication, creating replacement demand across Germany, France, and Italy.
- Multi-location chain consolidation:Retailers operating 10+ stores in the United States require unified SaaS platforms for real-time inventory synchronization across state jurisdictions.
- API-first integration:Connectivity to gemological testing equipment and supplier portals is streamlining procurement workflows for high-value diamond and gemstone tracking.
Market Restraints
- Subscription cost accumulation:Recurring SaaS fees strain independent jewelers with annual revenues under two million dollars, particularly in secondary US metropolitan markets.
- Legacy hardware lock-in:Proprietary point-of-sale terminals from 2015-2019 lack firmware upgrade paths, forcing premature capital expenditure for cloud compatibility.
- Regulatory fragmentation:Divergent state-level biometric privacy laws in Illinois, Texas, and Washington create compliance patchwork costs for CRM vendors.
Strategic Opportunities
- India's organized retail expansion:Tier-2 cities including Jaipur, Surat, and Ahmedabad present whitespace for cloud deployment as family-owned jewelers professionalize operations.
- AI-powered demand forecasting:Machine learning modules predicting seasonal inventory needs are penetrating mid-market chains seeking to reduce carrying costs on slow-moving SKUs.
- Embedded finance integration:Buy-now-pay-later APIs and jewelry-specific insurance APIs are opening new revenue streams for platform vendors.
Industry Challenges
- Specialized talent scarcity:Implementation consultants combining retail operations expertise with cloud architecture knowledge command premium rates, extending deployment timelines.
- PCI-DSS certification bottlenecks:Annual audits for payment processing modules face examiner backlogs, delaying product launches for six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Jewelry Store Management Software Market |
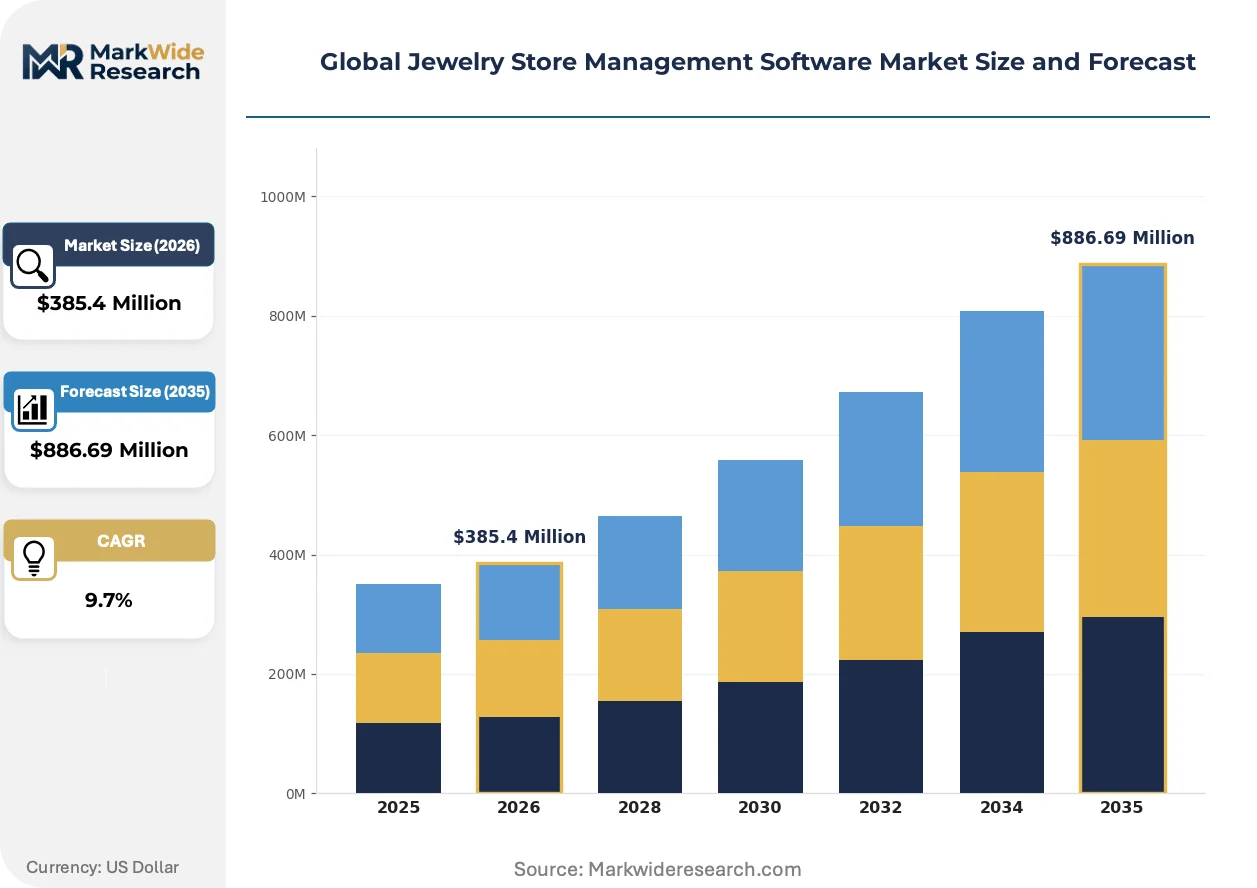
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Application: Inventory Management, Customer Relationship Management, Point of Sale, Analytics, Staff Management End User: Independent Jewelers, Chain Retailers, Online Jewelers, Wholesalers, Repair Specialists Pricing Model: Subscription-Based, One-Time License, Freemium, Pay-As-You-Go, Enterprise Licensing |
| Companies Covered | Lightspeed Retail, Shopify, Square, RepairDesk, Jewel Mate, PIRO Retail, NCR Corporation, Oracle Corporation, Valigara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Jewelry Store Management Software Market Shifts & Advancements
Real-time database synchronization and embedded e-commerce capabilities are redefining competitive minimums, while regulatory pressure on data handling accelerates architectural overhaul.
Mobile-first point-of-sale interfaces are overtaking traditional desktop terminals in independent jewelry stores. Boutique retailers in Brooklyn, Melbourne, and Amsterdam are deploying tablet-based checkout systems that untether staff from fixed counters. This hardware shift is compressing the traditional five-year POS replacement cycle to thirty-six months.
Europe's CSRD disclosure requirements are mandating supply-chain traceability documentation for precious metals and gemstones. Software vendors must now embed chain-of-custody tracking from mine to retail display. Mid-size chains in Belgium and Switzerland are responding by prioritizing platforms with built-in ethical sourcing modules.
Jewelry buyers are consolidating vendor relationships around unified platforms that span inventory, CRM, and e-commerce rather than maintaining separate point solutions. Multi-channel retailers in California and New York are demanding single-dashboard visibility across physical and digital storefronts. This preference compression is marginalizing standalone POS providers lacking native online synchronization.
Global Jewelry Store Management Software Market Segmentation
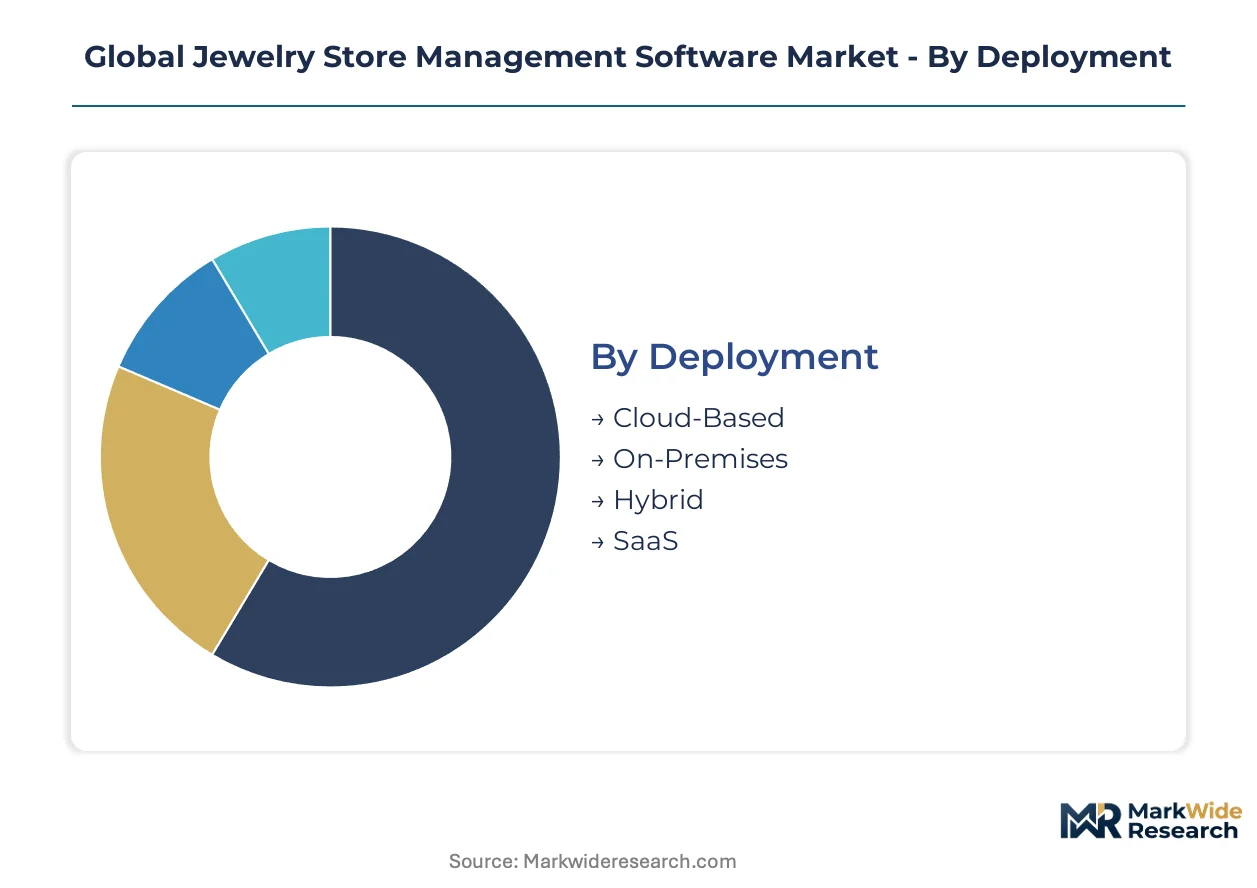
Jewelry store management software segments diverge sharply in compliance obligations. Cloud deployments face PCI-DSS audits for payment modules. On-premises systems trigger GDPR Article 32 assessments for biometric customer data storage. Hybrid architectures compound certification burdens across both frameworks.
Deployment:
PCI-DSS certification requirements split deployment preferences by store scale and transaction volume, with cloud-native vendors absorbing audit costs centrally while on-premises operators bear direct compliance liability.
- Cloud-Based:Real-time database synchronization across unlimited store locations with vendor-managed PCI-DSS Level 1 certification. Demand concentrates among independent jewelers in Brooklyn and Melbourne seeking zero hardware capital expenditure. GDPR Article 28 processor agreements dominate European procurement negotiations.
- SaaS:Subscription-native architecture with embedded automatic updates and API-first connectivity to gemological testing equipment. Multi-location chains in California and Texas prioritize unified dashboards over customization depth. Annual SOC 2 Type II attestation replaces discrete compliance projects.
- Hybrid:Sensitive inventory data resides on-premises while CRM modules sync to cloud instances. Mid-market retailers in Illinois and Washington navigate fractured biometric privacy laws. Split infrastructure doubles vendor management overhead.
- On-Premises:Legacy Windows Server deployments with SQL Server backends requiring direct GDPR accountability for customer biometric profiles. Family-owned operations in Surat and Ahmedabad maintain these systems for perceived data sovereignty.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
Application:
Functional modules carry divergent margin profiles, with analytics commanding premium pricing while staff management standardizes toward commoditization.
- Inventory Management:Real-time tracking of high-value SKUs with certified gemstone descriptors embedded per FTC mandates. Chain retailers in New York and Los Angeles demand RFID integration for vault-to-display traceability. Carrying cost reduction drives mid-market adoption.
- Customer Relationship Management:Biometric payment authentication and loyalty profile management triggering GDPR consent automation in Germany and France. European CSRD disclosure requirements now mandate ethical sourcing documentation links within customer-facing interfaces.
- Point of Sale:Tablet-based checkout systems compressing replacement cycles to thirty-six months. Brooklyn boutiques deploy these for floor mobility. PCI-DSS compliance certification bottlenecks delay product launches six to nine months.
- Analytics:Machine learning modules predicting seasonal demand for slow-moving diamond categories. Mid-market chains seek SKU-level forecasting to reduce capital tie-up.
- Staff Management:Scheduling and commission tracking with basic reporting. Standard functionality approaching feature parity across vendors.
Highest margin capture: Analytics. Broadest penetration: Inventory Management.
End User:
Customer scale dictates deployment complexity, with enterprise chains demanding multi-tenant architectures and independents tolerating single-store configurations.
- Chain Retailers:Unified SaaS platforms spanning ten-plus locations with real-time inventory synchronization across state tax jurisdictions. California and New York operations drive specification requirements. API connectivity to centralized procurement systems is non-negotiable.
- Independent Jewelers:Cloud-native point solutions with embedded e-commerce synchronization. Brooklyn and Amsterdam boutiques prioritize mobile-first POS interfaces. Subscription cost accumulation strains operators under two million dollars annual revenue.
- Online Jewelers:Native digital channel architecture with physical showroom add-ons. Shopify-embedded workflows dominate this segment. Buy-now-pay-later API integration opens incremental revenue streams.
- Wholesalers:B2B portal connectivity with supplier-side inventory visibility. Surat and Jaipur operations professionalizing through cloud migration. Family ownership transitions drive technology investment.
- Repair Specialists:Work-order tracking and customer notification systems with modest integration requirements. Niche positioning limits vendor customization incentives.
Deepest technology investment: Chain Retailers. Fastest professionalization: Wholesalers.
Pricing Model:
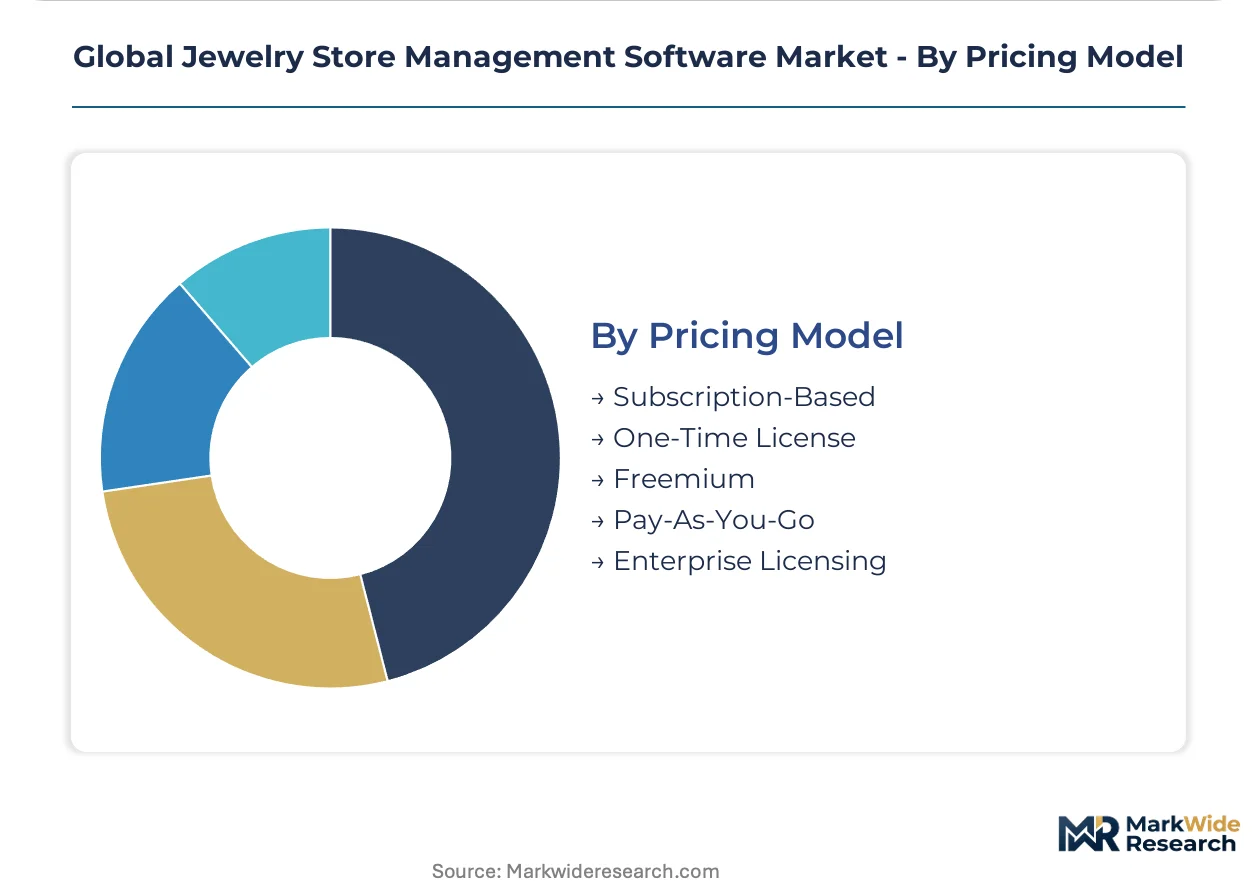
Revenue predictability preferences are shifting vendor strategies away from perpetual licenses toward recurring structures, though capital-constrained independents resist the transition.
- Subscription-Based:Monthly or annual recurring revenue with automatic feature updates and compliance patch delivery. Vendors prioritize this model for cash flow visibility. European jewelers accept premium pricing for embedded GDPR automation.
- Enterprise Licensing:Multi-year contracts with dedicated implementation support and custom API development. Chain retailers negotiating these for fifty-plus location deployments. Procurement teams demand SOC 2 documentation inclusion.
- One-Time License:Perpetual software ownership with annual maintenance fees. Legacy preference among risk-averse family operations. Declining vendor support for this structure limits future availability.
- Freemium:Core inventory tracking at zero cost with premium CRM and analytics upsells. Customer acquisition strategy for vendor market entry. Conversion rates to paid tiers determine segment viability.
- Pay-As-You-Go:Transaction-volume pricing aligned with seasonal jewelry sales fluctuations. Repair specialists and pop-up retailers favor this for demand elasticity. Revenue unpredictability discourages vendor investment.
Dominant revenue share: Subscription-Based. Steepest expansion trajectory: Enterprise Licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brooklyn's boutique jewelry corridor drives North American cloud adoption as independent retailers deploy tablet-based POS systems to compress checkout cycles. Multi-location chains in Manhattan and Los Angeles demand unified SaaS platforms spanning ten-plus stores.
United States
California and New York multi-location chains prioritize real-time inventory synchronization across state tax jurisdictions. FTC jewelry advertising standards mandate accurate gemstone disclosure, forcing vendors to embed certified descriptors into product databases. Brooklyn boutiques lead mobile-first POS deployment, cutting hardware replacement cycles to thirty-six months.
Germany
Family-owned jewelers in Munich and Hamburg upgrade CRM systems for automated consent management under GDPR Article 28. Germany's Federal Data Protection Authority enforces strict biometric payment authentication protocols. Stuttgart's mid-market chains invest in hybrid deployment to balance cloud CRM with on-premises inventory sovereignty.
India
Jaipur, Surat, and Ahmedabad family operations professionalize through cloud migration as generational ownership transitions accelerate. The country's central bank guidelines shape payment processing module requirements for domestic transactions. Surat's diamond polishing clusters adopt B2B portal connectivity for supplier-side inventory visibility.
United Kingdom
London's Hatton Garden district concentrates demand for embedded e-commerce synchronization between physical and digital channels. UK GDPR enforcement mirrors European consent automation requirements. Manchester's independent jewelers resist subscription cost accumulation, favoring pay-as-you-go models for seasonal demand elasticity.
Belgium
Antwerp's diamond trading houses prioritize platforms with built-in ethical sourcing modules to satisfy Europe's CSRD disclosure requirements. The country's national data protection authority audits biometric customer profile handling. Mid-size chains in Brussels consolidate vendor relationships around unified inventory-CRM-e-commerce dashboards.
Global Jewelry Store Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment architecture sophistication, with cloud-native vendors capturing recurring revenue predictability while legacy on-premises providers defend installed bases. The vendor base stratifies into three tiers: retail-native SaaS specialists, e-commerce-embedded platforms, and payment-hardware integrators. Consolidation pressure intensifies as multi-location chains demand single-dashboard visibility, marginalizing standalone POS providers lacking native online synchronization. Dominant competitive moves include API-first integration expansion and SOC 2 Type II attestation acquisition to accelerate enterprise procurement cycles.
Within the retail-native SaaS tier, Lightspeed Retail exemplifies cloud-based inventory workflow architecture for independent stores. Shopify occupies a position bridging e-commerce synchronization with physical channel unification. Square anchors the payment-hardware integration vector, reducing friction at jewelry point-of-sale terminals through controlled terminal ecosystems.
| Leading Market Players |
|---|
| Lightspeed Retail |
| Shopify |
| Square |
| RepairDesk |
| Jewel Mate |
| PIRO Retail |
| NCR Corporation |
| Oracle Corporation |
| Valigara |
| Others |
Supply & Pricing Matrix
Multi-location chain retailers in California and New York consolidating vendor relationships around unified SaaS platforms are forcing supply-side specialization, compressing margins for standalone POS providers while elevating premium pricing power for cloud-native vendors with native e-commerce synchronization.
Pricing Analysis
Value-based pricing anchored to inventory throughput and real-time synchronization uptime dominates enterprise negotiations. Three-tier pricing structure across premium, standard, and economy levels separates vendors with SOC 2 Type II attestation and API-first architectures from commodity players. Pricing pressure stems from subscription cost accumulation straining independent jewelers under two million dollars annual revenue. Chain retailers demonstrate lowest price sensitivity, prioritizing compliance automation and multi-location visibility over per-seat cost.
Supply Chain Analysis
India's domestic-content preferences for payment processing modules are reshaping sourcing patterns for vendors serving Surat and Jaipur operations. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure drawing from hyperscaler regions in Frankfurt, Singapore, and Virginia. Raw material dependencies include semiconductor components for POS terminals, cryptographic modules for PCI-DSS compliance, and API middleware for gemological equipment integration. Single-source vulnerability in biometric authentication chipsets poses structural risk. Distribution runs through direct vendor sales for enterprise chains and channel partners for independent jewelers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue payment-hardware control to reduce friction at jewelry point-of-sale terminals and capture recurring revenue streams.
For Market Incumbents: Anticipate margin compression from e-commerce-embedded platforms by deepening API-first integration with gemological testing equipment and accelerating SOC 2 Type II attestation acquisition to compress enterprise procurement cycles. Defend installed bases through backward integration into payment processing rather than relying on third-party PCI-DSS certification bottlenecks. For New Entrants and Emerging Players: Family-owned wholesalers in Surat, Ahmedabad, and Jaipur undergoing generational ownership transitions represent the most penetrable buyer archetype. Target this segment with cloud-native B2B portal connectivity and supplier-side inventory visibility modules. Lead with freemium inventory tracking to establish footprint before upselling CRM and analytics tiers. For Investors and Strategic Acquirers: The window for entry favors retail-native SaaS specialists with embedded finance integration capabilities over standalone POS providers lacking native online synchronization. Monitor API-first vendor consolidation velocity as the inflection indicator for platform maturity and enterprise procurement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies inventory, CRM, and e-commerce into single-dashboard visibility demanded by California and New York chains. |
| Acquisition of Specialist Firm | Consolidates API-first connectivity to gemological testing equipment and supplier portals. |
| Strategic Partnership | Accelerates PCI-DSS Level 1 certification through shared audit infrastructure with payment processors. |
| Product Launch | Deploys AI-powered demand forecasting modules targeting mid-market chains seeking SKU-level carrying cost reduction. |
| Geographic Expansion | Captures organized retail whitespace in Jaipur, Surat, and Ahmedabad as family operations professionalize. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and PCI-DSS certification registries formed the secondary backbone, cross-referenced with primary interviews involving CTOs at multi-location chain retailers, IT procurement officers at independent jewelers, platform engineers at cloud-native vendors, and integration specialists serving gemological equipment manufacturers. Bottom-up and top-down triangulation validated deployment model penetration rates and pricing tier distributions.
Bottom-up modeling aggregated individual vendor revenue estimates by deployment architecture and end-user segment, while top-down analysis calibrated total addressable market against retail jewelry sector technology spending patterns. Segmentation dimensions included deployment model, organization scale, functional application module, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to cloud adoption trajectories and SaaS pricing evolution, with inputs from API integration complexity indices and compliance automation penetration rates across the projection horizon.
Revisions become necessary when regulatory fragmentation between GDPR, state-level biometric privacy laws, and PCI-DSS standards intensifies vendor certification burdens beyond modeled scenarios, or when embedded finance integration fundamentally alters platform revenue composition. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe Digital Signage Software Market
Software & Services
Fire Software Market
Software & Services
App Building Software Market
Software & Services
IT Service Management Tools Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Photo Editing Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Telecom Billing Software Market
Software & Services
Event Management Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Global Saas Backup Software Market
Software & Services
Terminal Emulator Software Market
Software & Services
Global Gym Software Market
Software & Services
E-Invoicing Software Market
Software & Services
North America Automotive Software Market