
 Vacation Rental Software Market | 2026-2036
Vacation Rental Software Market Size, Share, and Industry Trends Forecast 2026-2036
Vacation Rental Software Market Outlook
Multi-source platform integration is shifting as the dominant procurement pattern among mid-sized property managers. Guesty anchors its position through deep channel management specialization across fragmented booking networks. Hostaway competes by extending geographic coverage into secondary vacation markets. OwnerRez differentiates through direct booking website capabilities that reduce platform dependency fees.
Vacation rental software denotes cloud-native and on-premises platforms that automate reservation workflows, synchronize availability calendars across distribution channels, and process payments through integrated gateways. These systems serve property managers and individual hosts by reducing manual coordination overhead and minimizing double-booking incidents. Cloud-based deployment leads the market structurally due to lower upfront infrastructure costs and automatic feature updates. Revenue management modules represent the fastest-growing service type as dynamic pricing algorithms replace static seasonal rate cards. SaaS delivery models capture the deepest margin pools through recurring subscription structures that improve customer lifetime value metrics.
The EU Digital Services Act and GDPR impose strict transparency and data handling requirements on platforms operating across European jurisdictions, forcing vendors to re-architect user data flows. The FTC in the United States scrutinizes deceptive pricing displays and hidden fee disclosures in online booking interfaces, shaping product design priorities. Stakeholders must monitor evolving short-term rental regulations at municipal levels, where licensing caps and occupancy restrictions directly impact software feature requirements for compliance tracking.
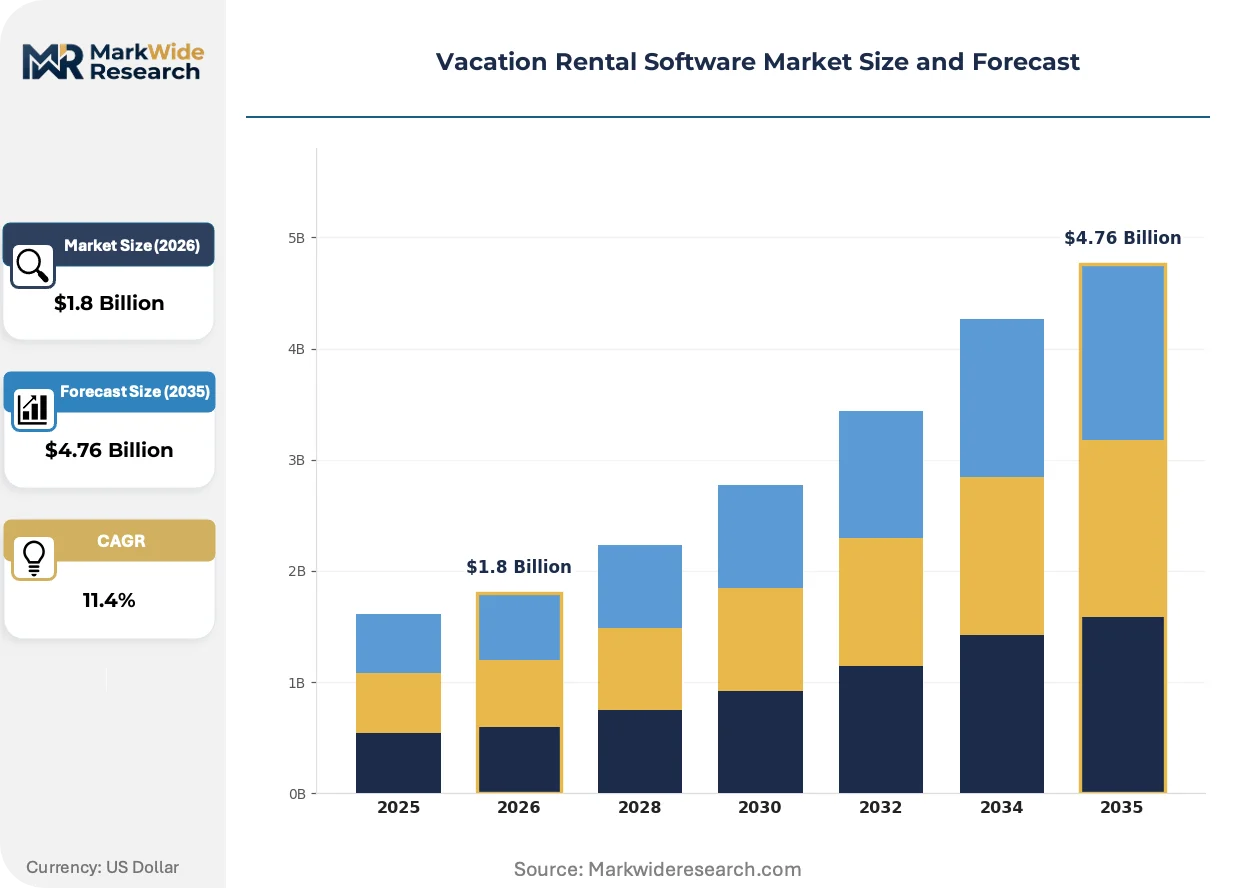
Market Dynamics
Property management companies are consolidating technology stacks around unified platforms that merge channel distribution, payment processing, and revenue optimization into single operational hubs.
Growth Catalysts
- GDPR and EU Digital Services Act:European compliance mandates are accelerating vendor investment in data governance architectures that property managers now require for cross-border operations.
- Dynamic pricing algorithms:Revenue management modules are displacing static seasonal rate cards as mid-sized operators seek yield optimization comparable to hotel chains.
- United States enterprise procurement:Large-scale property management companies are driving centralized software adoption that favors integrated suites over point solutions.
Market Restraints
- Cloud infrastructure concentration:Reliance on hyperscale providers creates single-point vulnerability for availability synchronization across global distribution networks.
- Municipal licensing fragmentation:Short-term rental caps and occupancy restrictions in cities like Barcelona, Amsterdam, and San Francisco force costly compliance feature customization.
- Payment gateway dependency:Integrated processing locks operators into specific financial service relationships with limited interchange rate negotiation leverage.
Strategic Opportunities
- Direct booking channel development:Website builder capabilities that reduce platform dependency fees represent underexploited margin recovery for independent hosts.
- Secondary vacation market expansion:Geographic coverage gaps in non-urban destinations create whitespace for specialized channel management tools.
- AI-powered guest communication:Convergence of natural language processing and automated messaging workflows offers service tier differentiation without proportional staffing increases.
Industry Challenges
- Revenue management expertise scarcity:Property managers lack analytical talent to configure dynamic pricing rules, creating implementation bottlenecks and underutilized software capabilities.
- Legacy PMS integration friction:Migration from established on-premises systems to cloud-native platforms requires data mapping complexity that extends deployment timelines and strains vendor support resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacation Rental Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Channel Management, Booking Management, Revenue Management, Customer Relationship Management Deployment: Cloud-based, On-premises, Hybrid, SaaS End User: Property Managers, Individual Hosts, Real Estate Companies, Travel Agencies Feature: Automated Messaging, Payment Processing, Listing Integration, Analytics Dashboard |
| Companies Covered | Hospitable, Smoobu, Guesty, Hostfully, Jurny, Hostaway, OwnerRez, iGMS, Lodgify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacation Rental Software Market Strategic Shifts
Artificial intelligence applications are penetrating operational workflows faster than regulatory frameworks can accommodate, compressing competitive differentiation cycles across vendor tiers.
Machine learning revenue optimization is consolidating pricing decision authority previously distributed across property manager intuition and static calendar rules. Mid-market operators with fifty to five hundred units are adopting these tools fastest, seeking parity with hospitality industry yield management practices. The technology is compressing margin dispersion between sophisticated and unsophisticated operators.
GDPR enforcement actions by CNIL in France and ICO in the United Kingdom are reshaping data retention and guest consent architectures. Vendors must now engineer granular deletion capabilities and audit trails that satisfy divergent national interpretations. Property managers operating across multiple European jurisdictions face compliance cost stacking that favors vendors with pre-certified multi-country deployments.
Buyer concentration among institutional property investors is shortening software evaluation cycles and hardening integration requirements. Large operators now demand API-first architectures that connect to proprietary business intelligence stacks, displacing standalone dashboard-centric products. This pattern is most visible in the United States, where private equity-backed property aggregators drive procurement standardization across portfolio companies.
Vacation Rental Software Market Segmentation
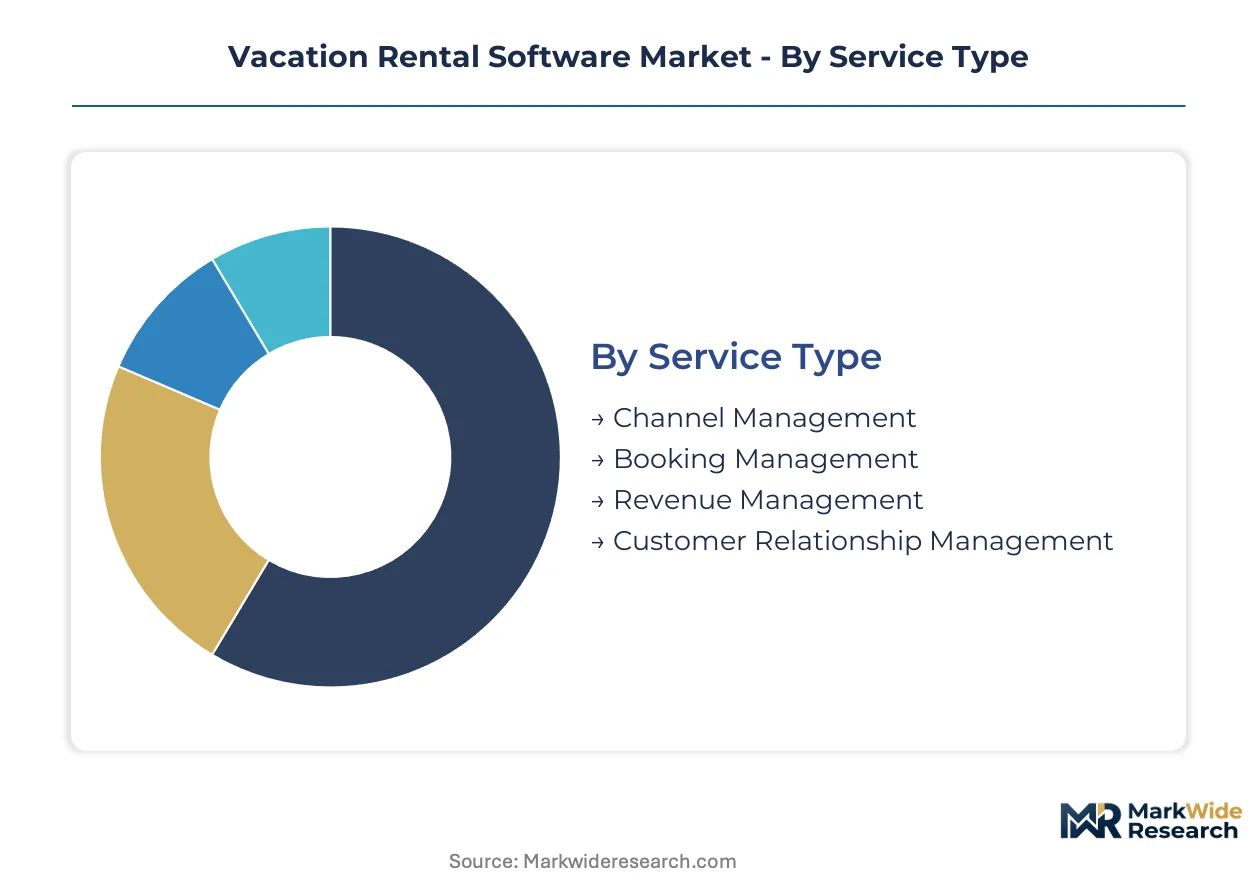
Vacation rental software segmentation reveals divergent technology requirements between enterprise property managers and independent hosts. Procurement patterns split sharply across deployment preferences and feature depth, with revenue optimization tools commanding premium pricing while basic channel management commoditizes.
Service Type:
Volume concentrates in operational workflow automation, while premium margins accrue to yield optimization intelligence.
- Channel Management:Synchronizes availability calendars across fragmented booking networks including Airbnb, Booking.com, and Vrbo through API connections. Demand concentrates among mid-sized property managers in the United States operating fifty to five hundred units who require unified inventory visibility without manual reconciliation overhead.
- Revenue Management:Deploys machine learning algorithms to adjust nightly rates based on occupancy forecasts, competitor pricing, and local event calendars. Property management companies in Florida and Arizona adopt these tools fastest as seasonal demand volatility rewards dynamic pricing sophistication over static rate cards.
- Booking Management:Handles reservation workflows, guest verification, and automated confirmation sequences.
- Customer Relationship Management:Tracks guest preferences, repeat visit patterns, and review solicitation timing.
Today's leader: Channel Management. Tomorrow's challenger: Revenue Management.
Deployment:
Cost tier stratification separates zero-infrastructure SaaS subscriptions from capital-intensive on-premises installations requiring dedicated IT staffing.
- Cloud-based:Delivers browser-accessible platforms with automatic feature updates and elastic scaling for seasonal demand spikes. Individual hosts in Portugal and Croatia favor this model for its elimination of server maintenance burdens and upfront hardware expenditure.
- SaaS:Structures pricing through recurring subscriptions tied to unit count or booking volume rather than perpetual licenses. Large property management companies in Texas and California drive enterprise procurement of multi-year SaaS contracts with API access for proprietary business intelligence integration.
- On-premises:Installs software on client-owned servers with full data sovereignty control.
- Hybrid:Combines cloud accessibility for guest-facing functions with local data retention for sensitive financial records.
Cloud-based deployment captures the deepest volume pools. SaaS delivery claims the steepest margin expansion trajectory.
End User:
Customer type determines feature complexity requirements and price sensitivity thresholds across the procurement spectrum.
- Property Managers:Operates multi-unit portfolios requiring unified dashboards, staff permission hierarchies, and consolidated financial reporting. Demand clusters in the United States among private equity-backed aggregators standardizing technology stacks across acquired portfolios.
- Individual Hosts:Manages one to five properties with prioritization of low-touch automation and direct booking website capabilities. Growth concentrates in secondary vacation markets across Spain and Italy where platform dependency fees erode margins for independent operators.
- Real Estate Companies:Integrates short-term rental operations within broader asset management frameworks.
- Travel Agencies:White-labels booking engines for package vacation distribution.
Property Managers currently dominate procurement value. Individual Hosts represent the fastest volume expansion opportunity.
Feature:
Maturity gradients separate table-stake functionality from differentiated service tier capabilities.
- Payment Processing:Integrates gateway connections for automated deposit collection, security hold authorization, and multi-currency settlement. Regulatory scrutiny by the FTC around fee transparency shapes vendor product roadmaps for disclosure-compliant checkout flows.
- Automated Messaging:Triggers guest communication sequences for booking confirmation, check-in instructions, and review requests through templated natural language generation. GDPR consent management requirements from CNIL and ICO force granular opt-in architectures for European deployments.
- Listing Integration:Pushes property descriptions and photography updates to distribution channels.
- Analytics Dashboard:Visualizes occupancy rates, revenue per available room, and channel contribution margins.
Payment Processing anchors current competitive positioning. Automated Messaging is gaining share fastest as AI convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance cost arbitrage is reshaping vendor deployment strategies as GDPR enforcement in Europe drives data infrastructure investment higher than in North American jurisdictions. Software providers are optimizing hosting architectures across regulatory boundaries to preserve margin structures while maintaining cross-border operational continuity.
United States
Enterprise property managers in Texas and Florida are consolidating procurement around unified SaaS platforms with API-first architectures. FTC scrutiny of hidden fee disclosures in online booking interfaces is forcing checkout flow redesigns among vendors serving US customers. Miami and Austin host the densest clusters of private equity-backed property aggregators standardizing technology stacks across portfolio companies.
Germany
Mid-sized property managers in Bavaria and North Rhine-Westphalia are prioritizing GDPR-certified multi-country deployments to avoid compliance cost stacking. The national data protection authority enforces strict guest consent architectures that vendors must engineer into automated messaging workflows. Berlin's concentration of proptech startups is accelerating AI-powered revenue management adoption among urban rental operators.
Spain
Independent hosts in Catalonia and Andalusia are driving demand for direct booking website capabilities to reduce platform dependency fees. Municipal licensing caps in Barcelona force software vendors to build compliance tracking features for occupancy restrictions. Valencia's secondary vacation market is emerging as a testing ground for specialized channel management tools targeting non-urban destinations.
United Kingdom
Property management companies in London and the Southeast are demanding granular data deletion capabilities following ICO enforcement actions on retention policies. The regulatory divergence from EU frameworks post-Brexit is creating dual-compliance architecture requirements for vendors operating across both jurisdictions. Edinburgh's festival-driven rental economy is rewarding dynamic pricing algorithm adoption among Scottish operators.
France
CNIL enforcement in Île-de-France is mandating audit trail engineering that exceeds baseline GDPR requirements for guest data handling. Revenue management modules are penetrating fastest in Provence-Alpes-Côte d'Azur where seasonal demand volatility rewards yield optimization sophistication. Lyon and Nice host growing clusters of mid-market operators seeking parity with hotel chain pricing practices.
Vacation Rental Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-powered differentiation and secondary market geographic coverage. The vendor base stratifies across three maturity tiers: legacy platforms with deep channel management specialization, cloud-native challengers with revenue optimization intelligence, and niche specialists in direct booking enablement. Dominant competitive moves include strategic partnerships with payment gateways and portfolio diversification into adjacent hospitality software categories.
Within the channel management archetype, Guesty and Hostaway exemplify platform consolidation strategies, while OwnerRez occupies a position emphasizing reduced platform dependency. These three anchors represent divergent strategic bets on whether property managers prioritize distribution breadth, geographic expansion, or margin recovery through direct guest relationships.
| Leading Market Players |
|---|
| Hospitable |
| Smoobu |
| Guesty |
| Hostfully |
| Jurny |
| Hostaway |
| OwnerRez |
| iGMS |
| Lodgify |
| Others |
Value Chain & Pricing Dynamics
Machine learning revenue optimization is compressing margin dispersion between sophisticated and unsophisticated operators while simultaneously concentrating procurement power among large-scale property management companies. This technological shift redraws cost economics across vendor tiers and tightens supply relationships around hyperscale cloud infrastructure providers.
Pricing Analysis
Platform dependency fees shape the dominant pricing structure, with SaaS subscriptions tiered by unit count and feature depth displacing perpetual licenses. Price differentiation rests on API access sophistication and GDPR certification tier, with enterprise buyers in Texas and Florida commanding volume discounts unavailable to independent hosts in secondary markets. Cost compression in mid-market tiers intensifies because channel management features commoditize while revenue management modules capture premium positioning. Individual hosts in Spain and Italy exhibit the highest price sensitivity, whereas private equity-backed aggregators prioritize integration depth over subscription cost.
Supply Chain Analysis
GDPR certification and SOC 2 Type II attestation gate vendor market access, forcing infrastructure investment that separates compliant from non-compliant suppliers. Software development concentrates in the United States, Israel, and Estonia, with cloud hosting anchored in AWS, Azure, and Google Cloud data centers across Frankfurt, Dublin, and Virginia. Raw material dependencies include API access fees from Airbnb and Booking.com, payment gateway interchange structures, and AI compute credits for dynamic pricing algorithms. Single-source vulnerability runs through hyperscale cloud concentration for availability synchronization. Distribution runs through direct vendor sales teams for enterprise accounts and self-service onboarding portals for independent hosts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as institutional property investors demand API-first architectures and pre-certified multi-country deployments, elevating premium-tier vendors while squeezing undifferentiated mid-market offerings.
For Market Incumbents: Lock in enterprise relationships through multi-year SaaS contracts with embedded revenue management modules that raise switching costs. Deepen backward integration into payment processing to capture interchange margin and reduce gateway dependency. Defend against cloud-native challengers by accelerating AI-powered guest communication deployment before feature parity erodes differentiation. For New Entrants and Emerging Players: Begin with direct booking website capabilities targeting independent hosts in Valencia, Nice, and secondary Italian markets where platform fee resentment runs highest. White-label channel management for regional property aggregators in Portugal and Croatia offers the most penetrable entry path. Lead with GDPR pre-certification to bypass compliance cost stacking that disadvantages point-solution vendors. For Investors and Strategic Acquirers: Roll-up economics work for revenue management specialists because yield optimization expertise scarcity creates captive customer bases with low churn. Target vendors with fifty-to-five-hundred-unit customer concentration and existing API ecosystems. Watch CNIL and ICO enforcement intensity as the signal indicating whether compliance cost stacking accelerates vendor consolidation or fragments procurement toward certified niche players.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies channel management, payment processing, and revenue optimization into single operational hubs for mid-sized property managers. |
| Geographic Expansion | Captures whitespace in secondary vacation markets across Portugal, Croatia, and non-urban Spanish destinations. |
| Strategic Partnership | Payment gateway alliances reduce interchange rate exposure and lock in financial service relationships. |
| Acquisition of Specialist Firm | Revenue management algorithm developers bring machine learning pricing authority to legacy channel management platforms. |
| Product Launch | AI-powered guest communication modules differentiate service tiers without proportional staffing increases. |
Study Parameters
Coverage spans North America, Western Europe, and Mediterranean secondary markets, with primary inputs from each region combined with secondary validation. Interviews with property management executives, CTOs at proptech startups, channel partners, and integration specialists anchored demand-side intelligence. Secondary sources include SEC filings from hospitality software vendors, GDPR enforcement databases from CNIL and ICO, and municipal short-term rental regulation trackers. Bottom-up unit economics modeling triangulated against top-down market sizing from SaaS subscription benchmarks.
Rate-of-change decomposition separates volume expansion from pricing evolution across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, feature complexity tier, and regional regulatory cluster. CAGRs derived from cohort-based adoption curves and replacement cycle analysis. Industry-specific inputs encompass channel management API connection fees and revenue management module attach rates.
Several conditions sit outside the modeled scope, including abrupt municipal licensing moratoriums, hyperscale cloud outages affecting availability synchronization, and payment gateway consolidation altering interchange structures. Forecasts reflect assumptions about regulatory enforcement continuity and enterprise procurement standardization patterns. A model refresh is warranted upon material change in FTC disclosure requirements or EU Digital Services Act implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Server Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Personal Budgeting Software Market
Software & Services
Global Kiosk Software Market
Software & Services
Multiphysics Software Market
Software & Services
Construction Estimating Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Global Backup Restore Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Global Printing Software Market
Software & Services
Tech Support Services Market
Software & Services
Managed Information Services Market