
 Cold Storage Warehouse Market | 2026-2036
Cold Storage Warehouse Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Storage Warehouse Market Analysis
The EU F-Gas Regulation is rebalancing cold storage investment toward ammonia and CO2 refrigeration systems across European logistics networks. Americold Logistics leverages its integrated national warehouse footprint to sustain temperature-controlled distribution density in North American protein corridors. Lineage Logistics anchors its position through automated high-bay facilities that reduce energy intensity per pallet position. Nichirei Logistics Group dominates Asia-Pacific frozen food logistics through coastal cold chain infrastructure tied to seafood processing clusters.
Cold storage warehouses are engineered facilities maintaining temperatures from 15°C down to -30°C through insulated envelopes, vapor barrier systems, and precision refrigeration plant; their primary purpose is preserving perishable inventory quality while extending shelf life for food, pharmaceutical, and chemical supply chains. Refrigerated storage occupies the largest capacity share as fresh produce and dairy distribution require controlled but non-freezing environments, while blast freezers represent the fastest-expanding product type due to surging demand for rapid temperature reduction in processed protein and ready-meal segments. Warehouse management systems increasingly sit at the margin pool center as software layers enable inventory traceability, energy optimization, and regulatory compliance documentation.
FDA regulations mandate continuous temperature monitoring and documentation for pharmaceutical distribution, while EPA SNAP program rules restrict high-GWP refrigerants in new cold storage construction. OSHA standards govern ammonia refrigeration safety protocols in industrial freezer facilities, shaping facility design and operational training requirements. Stakeholders must monitor refrigerant transition timelines and energy efficiency benchmarks as these regulatory vectors determine capital allocation priorities and facility obsolescence risk.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale refrigerant transition across European cold storage networks, compressing payback periods for ammonia and CO2 systems while rendering hydrofluorocarbon-dependent facilities economically obsolete.
Growth Catalysts
- Biologics cold chain expansion:Temperature-sensitive pharmaceutical therapies require validated storage infrastructure from manufacturing through last-mile distribution.
- India PLI scheme for food processing:Government-backed capital subsidies are accelerating integrated cold chain investments in agricultural export corridors.
- Automated high-bay densification:Robotics-enabled vertical storage is integrating with warehouse management systems to maximize pallet positions per square meter.
Market Restraints
- Copper and steel input volatility:Insulated panel and refrigeration coil costs fluctuate with commodity markets, squeezing contractor margins on fixed-price builds.
- Ammonia refrigeration safety protocols:OSHA standards mandate specialized engineering controls and operator certification, limiting retrofit feasibility in urban infill locations.
- Land scarcity in protein corridor hubs:Cold storage development concentrates near Chicago, Rotterdam, and São Paulo where industrial zoning constraints inflate site acquisition costs.
Strategic Opportunities
- India pharmaceutical export corridors:Temperature-controlled warehouse capacity lags behind biologics manufacturing growth in Hyderabad and Mumbai clusters.
- EU Green Deal refrigerant mandates:Natural refrigerant retrofits qualify for national decarbonization funds in Germany, France, and the Netherlands.
- Blockchain-IoT convergence:Distributed ledger technology is integrating with sensor networks to automate regulatory compliance documentation for FDA and EMA audits.
Industry Challenges
- Ammonia refrigeration technician scarcity:Specialized mechanical and safety expertise required by OSHA protocols outpaces vocational training pipeline output.
- Legacy WMS integration complexity:Automated material handling systems require middleware development to synchronize with incumbent enterprise resource planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Storage Warehouse Market |
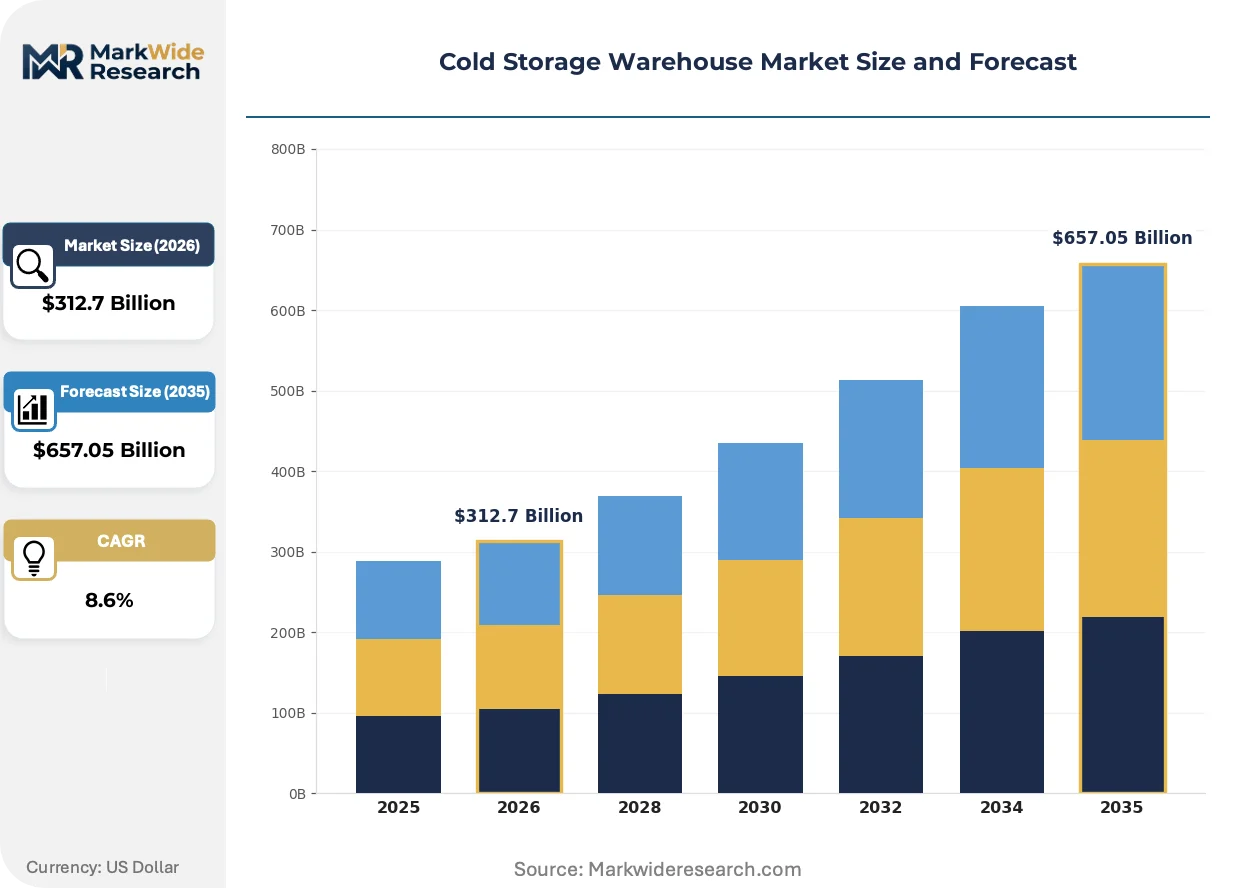
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Storage, Freezer Storage, Blast Freezers, Warehouse Management Systems End User: Food & Beverage, Pharmaceuticals, Chemicals, Agriculture Technology: Door Systems, Refrigeration Systems, Monitoring Solutions, Automation Technology Installation: On-site, Off-site, Modular, Design-Build |
| Companies Covered | Lineage Logistics, Americold Logistics, Nichirei Logistics Group, United States Cold Storage, Burris Logistics, NewCold Advanced Cold Logistics, VersaCold Logistics Services, A.P. Moller - Maersk, Swire Cold Storage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Storage Warehouse Market Emerging Trajectories
Refrigeration technology, regulatory compliance architecture, and buyer procurement models are simultaneously transforming how cold storage capacity is engineered, financed, and operated across pharmaceutical and protein supply chains.
Phase-change materials and advanced thermal mass storage are integrating with conventional mechanical refrigeration to shave peak demand charges and buffer against compressor failure. Pharmaceutical distributors with 24/7 validation requirements are adopting these hybrid systems fastest. The technology is integrating backup resilience into primary cooling architecture, reducing redundant plant capital for critical inventory.
The EU F-Gas Regulation mandates an 80% hydrofluorocarbon phase-down by 2030, prohibiting new high-GWP refrigerant installations and accelerating ammonia and CO2 adoption. Industrial freezer operators face accelerated depreciation of HFC-dependent assets. German and Dutch logistics networks are responding with district cooling integration and shared refrigeration plants.
Buyers are consolidating vendor relationships around full-service temperature-controlled logistics contracts that bundle storage, transportation, and compliance documentation. Protein processors and pharmaceutical manufacturers are displacing spot-rate warehouse procurement with multi-year capacity reservations. This concentration is most visible in North American and European markets where FDA and EMA audit trails favor integrated operators with validated systems.
Cold Storage Warehouse Market Segmentation
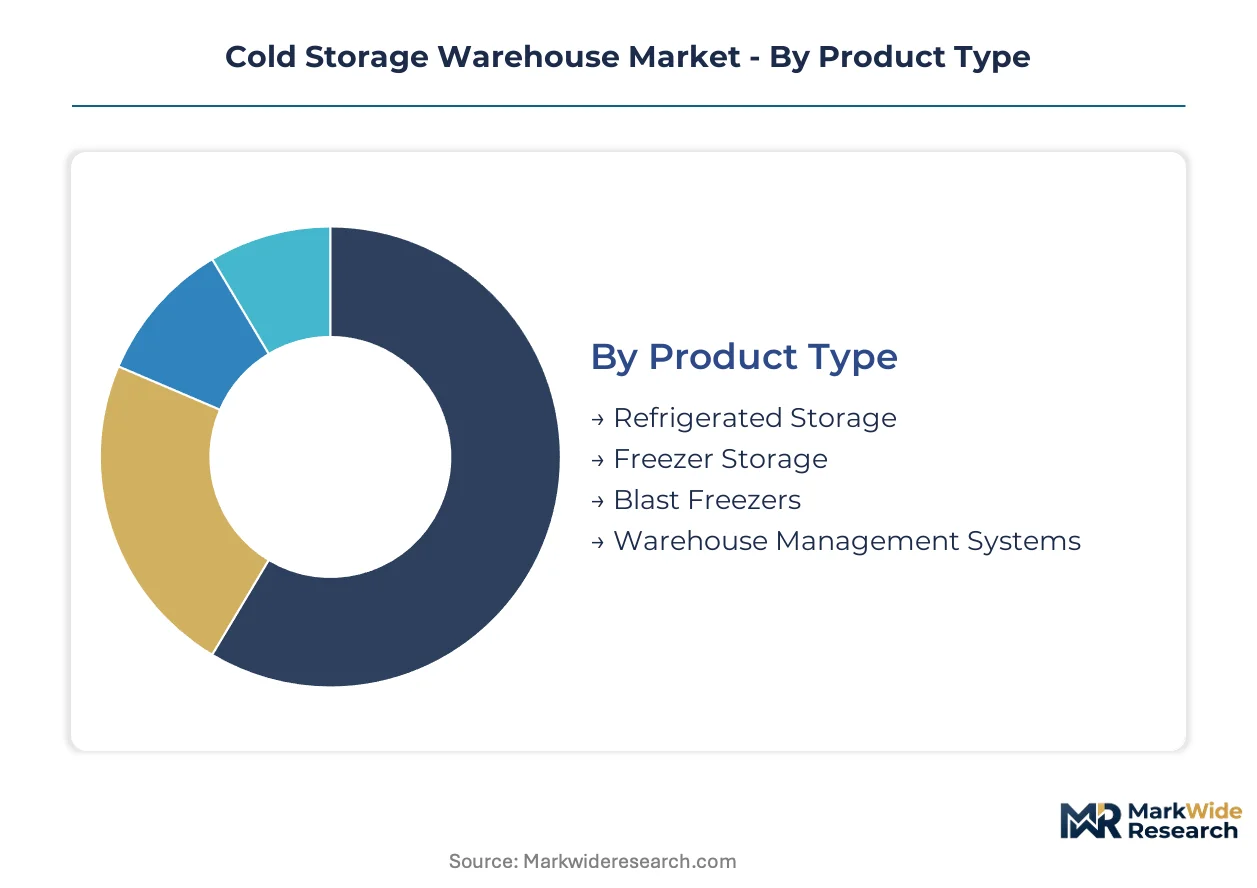
Cold storage warehouse segmentation reveals divergent investment priorities across temperature regimes, end-use validation requirements, and construction methodologies. Product type splits expose capacity concentration versus growth trajectory gaps. Technology and installation categories capture the operational complexity that separates commodity storage from premium pharmaceutical infrastructure.
Product Type:
Volume capacity concentrates in refrigerated storage corridors serving fresh produce and dairy distribution, while premium infrastructure investment chases specialized freezing and software layers.
- Refrigerated Storage:Maintains temperatures between 0°C and 15°C through insulated envelope systems and vapor barrier engineering. Demand concentrates in California's Central Valley and Netherlands distribution corridors where fresh produce export volumes require controlled but non-freezing environments. Energy efficiency benchmarking drives retrofit decisions as electricity tariffs escalate.
- Blast Freezers:Engineered for rapid temperature reduction from ambient to -30°C using high-velocity airflow and specialized coil configurations. Processed protein manufacturers in Brazil's São Paulo corridor and ready-meal processors in Germany deploy these systems to lock moisture content and extend shelf stability. Capital intensity limits deployment to high-throughput facilities.
- Freezer Storage:Sustains frozen inventory at -18°C to -25°C through conventional mechanical refrigeration and thermal mass management.
- Warehouse Management Systems:Software layers enabling inventory traceability, energy optimization, and regulatory compliance documentation for FDA and EMA audit trails.
Mature deployment sits with Refrigerated Storage. Newer deployment is concentrated in Blast Freezers.
End User:
Application requirements separate commodity food logistics from validated pharmaceutical infrastructure where regulatory documentation drives procurement decisions.
- Food & Beverage:Protein processors, dairy distributors, and produce exporters dominate capacity absorption across North American and European logistics networks. Temperature tolerance bands are wider than pharmaceutical standards, permitting multi-tenant warehouse configurations and shared refrigeration plants.
- Pharmaceuticals:Biologics manufacturers and vaccine distributors require continuous temperature monitoring, backup power redundancy, and validated storage protocols from manufacturing through last-mile distribution. FDA and EMA regulations mandate documentation systems that disqualify commodity warehouse operators.
- Chemicals:Specialty chemical manufacturers requiring controlled storage for temperature-sensitive intermediates and active ingredients.
- Agriculture:Seed preservation and grain conditioning operations in agricultural export corridors.
Margin concentration aligns with Pharmaceuticals. Volume concentration remains with Food & Beverage.
Technology:
Cost tier separation runs from basic door hardware through integrated automation stacks that determine labor efficiency and energy intensity per pallet position.
- Refrigeration Systems:Ammonia and CO2 plants are displacing hydrofluorocarbon-dependent equipment under EU F-Gas Regulation mandates. German and Dutch operators qualify for national decarbonization funds when retrofitting to natural refrigerants. Payback periods compress as carbon pricing mechanisms expand.
- Automation Technology:Robotics-enabled high-bay storage and automated guided vehicles maximize pallet positions per square meter while reducing labor dependency. Lineage Logistics and similar operators deploy these systems in greenfield facilities where land scarcity in Chicago and Rotterdam protein corridors inflames site acquisition costs.
- Door Systems:Rapid-cycle doors and air curtain technologies minimizing thermal infiltration during loading operations.
- Monitoring Solutions:Sensor networks and IoT platforms enabling real-time temperature logging and regulatory compliance automation.
Technology maturity clusters around Refrigeration Systems. Automation Technology commands the steepest expansion trajectory.
Installation:
Customer type and project scale determine whether owners deploy capital through turnkey contractors or modular prefabrication.
- Design-Build:Integrated engineering-procurement-construction contracts compress project timelines for pharmaceutical and protein processing clients requiring validated facility handover. Americold Logistics and comparable operators favor this model for national warehouse footprint expansion.
- Modular:Prefabricated panel and refrigeration skid packages reduce on-site construction duration for remote agricultural corridors and emerging market deployments. India's PLI scheme for food processing accelerates adoption in Hyderabad and Mumbai pharmaceutical export clusters.
- On-site:Conventional construction methodology for owner-operated facilities with specialized operational requirements.
- Off-site:Third-party leased capacity arrangements favored by seasonal agricultural exporters and spot-market protein distributors.
Established infrastructure relies on On-site construction. Modular installation is gaining share fastest in emerging market corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in protein export corridors while consumption spreads across pharmaceutical manufacturing clusters and fresh produce distribution networks. This geographic split shapes capital allocation and regulatory compliance requirements.
United States
Protein processing and pharmaceutical distribution drive warehouse construction across Midwest protein corridors and Northeast biotech clusters. FDA temperature monitoring mandates and OSHA ammonia safety protocols shape facility design standards. Chicago anchors the densest cold storage network, with automated high-bay facilities expanding near Atlanta and Dallas distribution hubs.
Germany
Ready-meal manufacturing and pharmaceutical exports sustain demand for blast freezer and validated storage capacity. EU F-Gas Regulation accelerates ammonia and CO2 retrofits, with national decarbonization funds subsidizing natural refrigerant transitions. The Ruhr industrial corridor and Bavarian logistics networks concentrate automated cold chain infrastructure serving EMA-compliant distribution.
India
Biologics manufacturing growth and agricultural export expansion outpace temperature-controlled warehouse supply in pharmaceutical and food processing corridors. PLI scheme subsidies for food processing infrastructure accelerate cold chain investments. Hyderabad and Mumbai pharmaceutical clusters face acute capacity shortages for validated storage serving CDSCO-regulated export requirements.
Brazil
Beef and poultry export processing sustains blast freezer demand across São Paulo state protein corridors. ANVISA pharmaceutical regulations and agricultural export standards drive facility validation investments. The Campinas and Sorocaba industrial regions concentrate multi-temperature warehouses serving Mercosur distribution networks.
Netherlands
Perishable re-export logistics and flower distribution sustain refrigerated storage demand through Rotterdam port corridors. EU Green Deal refrigerant mandates accelerate shared refrigeration plant and district cooling integration. The Randstad logistics network anchors automated facilities serving EMA-validated pharmaceutical transit to European markets.
Cold Storage Warehouse Market Vendor Landscape
The competitive structure tilts toward integrated national networks with validated systems. Consolidation favors operators combining warehouse ownership with transportation and compliance documentation capabilities. Three archetypes dominate: automated high-bay specialists, protein corridor incumbents with dense regional footprints, and pharmaceutical-validated infrastructure providers. Capacity expansion and M&A activity concentrate in North American and European markets where regulatory audit trails favor integrated operators.
Among North American integrated networks, Lineage Logistics, Americold Logistics, and United States Cold Storage occupy positions spanning automated storage deployment and national distribution density. Lineage exemplifies the automation-focused archetype through robotics-enabled vertical facilities. Americold anchors the protein corridor concentration model with temperature-controlled networks. United States Cold Storage represents regional density strategies in specialized agricultural and protein logistics segments.
| Leading Market Players |
|---|
| Lineage Logistics |
| Americold Logistics |
| Nichirei Logistics Group |
| United States Cold Storage |
| Burris Logistics |
| NewCold Advanced Cold Logistics |
| VersaCold Logistics Services |
| A.P. Moller - Maersk |
| Swire Cold Storage |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up cold storage specialists anchor supply discipline through portfolio-wide procurement leverage, compressing contractor margins while sustaining premium pricing for pharmaceutical-validated capacity. Their concentrated ownership patterns feed pricing power back into supply chain consolidation across protein corridor hubs.
Pricing Analysis
Margin tightening in commodity refrigerated storage reflects copper and steel input volatility squeezing fixed-price construction contracts. Three-tier pricing structure across pharmaceutical-validated, automated high-bay, and conventional multi-tenant levels separates FDA-compliant documentation tiers from basic food-grade warehousing. Cost compression accelerates in standard freezer segments as commodity spot buyers consolidate around integrated logistics contracts. Protein processors exhibit highest price sensitivity due to thin operating margins, while biologics manufacturers accept premium rates for continuous validation protocols.
Supply Chain Analysis
Single-source vulnerability sits with Chinese insulated panel manufacturing and German refrigeration compressor engineering. Cold storage construction draws from South Korean steel, Chinese aluminum, and domestic concrete supply bases. Tariff exposure on imported refrigeration components threatens project timelines for US Midwest protein corridor developments. Distribution runs through specialized cold chain logistics operators bundling warehouse ownership with temperature-controlled transportation assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
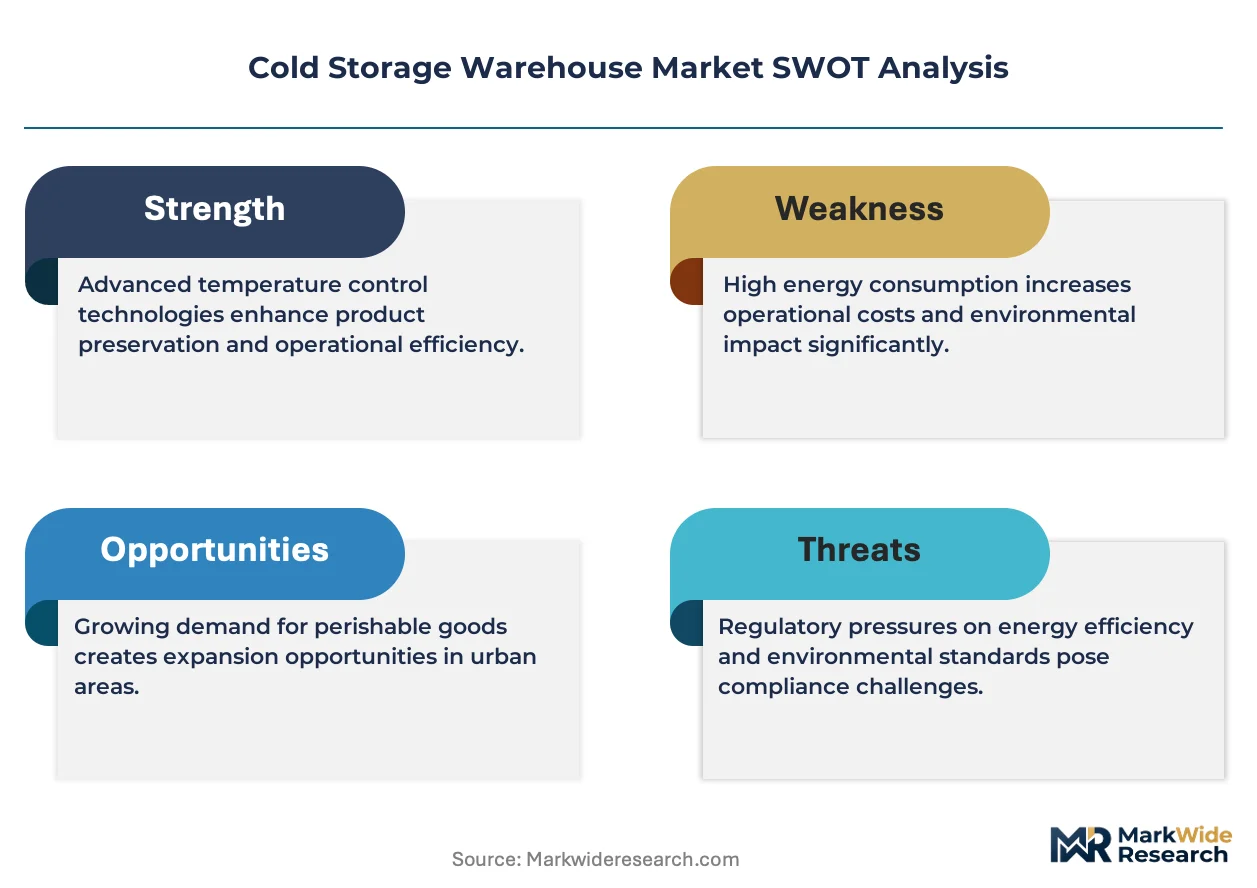
The cold storage warehouse sector sits in a refrigerant technology-transition phase, with ammonia and CO2 systems displacing hydrofluorocarbon-dependent legacy infrastructure under EU F-Gas Regulation mandates.
For Market Incumbents: Deploy automated high-bay densification to defend pallet-position economics against land scarcity inflation in Chicago and Rotterdam protein corridors. Accelerate ammonia refrigeration technician training pipelines to preempt OSHA compliance bottlenecks. Consolidate vendor relationships around full-service temperature-controlled logistics contracts that displace spot-rate competitors. For New Entrants and Emerging Players: Digital-channel integration with warehouse management system platforms offers the most penetrable entry vector for mid-market pharmaceutical distributors seeking validated inventory traceability. Target India's Hyderabad and Mumbai pharmaceutical export clusters where CDSCO-regulated capacity shortages outpace biologics manufacturing growth. Pursue modular prefabrication partnerships to compress construction timelines for PLI scheme-subsidized food processing infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor ammonia-retrofit-ready facilities in Germany and the Netherlands where EU Green Deal decarbonization funds subsidize natural refrigerant transitions. Long-term viability hinges on automated storage deployment density and pharmaceutical validation certification. Watch ammonia refrigeration technician wage inflation as the inflection signal for facility obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Retrofit | EU F-Gas Regulation compliance unlocks national decarbonization fund access in Germany and the Netherlands. |
| Automated High-Bay Deployment | Robotics-enabled vertical storage maximizes pallet positions per square meter in land-scarce Rotterdam and Chicago corridors. |
| Pharmaceutical Validation Investment | FDA and EMA audit trail documentation disqualifies commodity operators from biologics distribution contracts. |
| Modular Prefabrication Partnership | India's PLI scheme accelerates adoption of panel-and-skid packages in Hyderabad pharmaceutical export clusters. |
| Integrated Logistics Contracting | Multi-year capacity reservations displace spot-rate procurement for protein processors seeking supply security. |
Methodological Framework
Document review covered SEC filings from publicly traded logistics operators, EU regulatory impact assessments, and national cold chain infrastructure databases, complemented by interviews with cold storage facility engineering directors, pharmaceutical supply chain managers, and refrigeration contractor procurement leads. Secondary validation drew from OSHA ammonia safety protocol documentation, EPA SNAP program rulemakings, and customs trade data on insulated panel imports. Bottom-up capacity modeling triangulated against top-down pharmaceutical distribution volume projections.
Cross-referencing historical construction cost indices with industry panel input on technology adoption timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include temperature regime, end-use validation tier, automation technology level, and regional regulatory cluster. CAGRs derived from facility capacity expansion pipelines, pharmaceutical export growth trajectories, and refrigerant transition compliance schedules.
The model holds under stable commodity input pricing and regulatory enforcement continuity; deviation in copper and steel volatility or OSHA ammonia safety rule amendments would shift capacity expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Global Unified Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
Latin America Soft Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
Canada Facility Management Market