
 Canada Alcohol E-Commerce Market | 2026-2036
Canada Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Alcohol E-Commerce Market Insights
The capital-intensity divergence between delivery-platform operators and legacy provincial retailers is redrawing competitive boundaries in Canadian alcohol e-commerce. Drizly Canada leverages third-party logistics partnerships to sustain last-mile density without warehouse ownership. LCBO anchors its position through monopoly-controlled inventory access and established trust metrics. Wine Online differentiates by specializing in curated import portfolios that mass-market platforms cannot replicate.
Canada alcohol e-commerce encompasses the digital sale and fulfillment of beer, wine, spirits, and ready-to-drink beverages through websites, mobile applications, and affiliated delivery networks, with temperature-controlled logistics and age-verification protocols as core operational parameters. The primary commercial purpose is to bypass or supplement traditional brick-and-mortar distribution while satisfying provincial regulatory requirements for controlled substance retail. Wine and spirits command the deepest margin pools within product type segments, reflecting per-unit value density and consumer willingness to pay for provenance transparency. Direct-to-consumer channels represent the fastest-growing distribution vector, though online retailers still process the highest absolute transaction volumes due to aggregator economics.
Health Canada, the Canada Revenue Agency, and provincial liquor authorities including the Alcohol and Gaming Commission of Ontario collectively govern excise taxation, interprovincial shipping prohibitions, and age-gating standards that determine market access contours. These frameworks create substantial compliance overhead for national platform expansion while privileging incumbents with established provincial licenses. Stakeholders must monitor pending federal excise reform and provincial privatization debates to anticipate whether regulatory arbitrage opportunities will open for private digital entrants or consolidate further around crown corporation structures.
Market Dynamics
Provincial liquor board infrastructure decay is fragmentating fulfillment capacity across Canada, forcing private digital platforms to construct parallel cold-chain networks while crown corporations defend monopoly gatekeeping over inventory access.
Growth Catalysts
- Regulatory Modernization:Ontario's Alcohol and Gaming Commission of Ontario is relaxing direct-to-consumer shipping restrictions, enabling wineries in British Columbia and Quebec to bypass traditional distribution tiers and reach urban consumers directly.
- Demographic Migration:Millennial and Gen Z cohorts are relocating to secondary cities like Halifax and Victoria, bringing digital-native purchasing expectations that legacy provincial retail footprints cannot satisfy.
- Urban Density Concentration:Toronto and Montreal corridor populations are clustering in high-rise residential developments where last-mile alcohol delivery economics outperform brick-and-mortar accessibility.
Market Restraints
- Interprovincial Trade Barriers:Section 121 of the Constitution Act and provincial liquor control acts prohibit cross-border alcohol shipments, trapping inventory within provincial boundaries and duplicating warehousing requirements.
- Excise Tax Burden:Canada Revenue Agency administered excise duties on spirits create price floors that compress margin flexibility for digital discounting strategies relative to beer and wine categories.
- Crown Corporation Entrenchment:LCBO and SAQ monopoly structures control wholesale pricing and exclusive product access, constraining private platform assortment breadth and procurement leverage.
Strategic Opportunities
- Atlantic Canada Expansion:Newfoundland and Labrador's privatized retail environment offers regulatory arbitrage for digital-first entrants to establish market presence before competitive saturation.
- Ready-to-Drink Convergence:Premium canned cocktail formulations are attracting craft spirits producers and conventional breweries simultaneously, creating hybrid category white space underserved by existing platform taxonomies.
- Temperature-Controlled Logistics Partnerships:Third-party cold-chain specialists are building dedicated beverage infrastructure that reduces capital requirements for platform operators seeking national coverage without warehouse ownership.
Industry Challenges
- Age Verification Protocol Standardization:Health Canada guidelines for digital age-gating lack enforcement uniformity across provinces, forcing platforms to maintain multiple compliance workflows and liability exposure variations.
- Legacy System Integration:Provincial liquor board ERP systems utilize decades-old batch processing architectures that resist real-time inventory API connectivity, delaying stock visibility and order confirmation speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Alcohol E-Commerce Market |
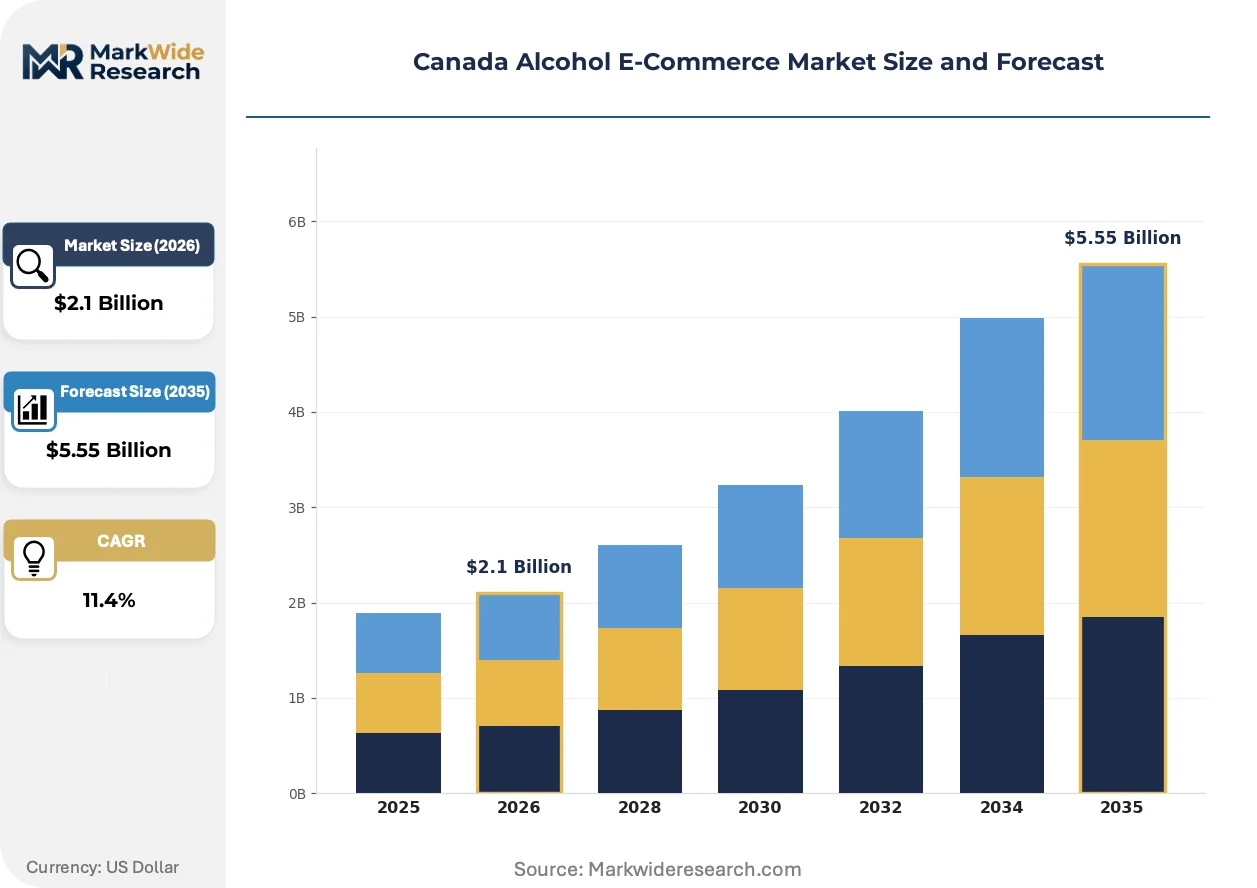
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Ready-to-Drink Distribution Channel: Direct-to-Consumer, Online Retailers, Delivery Services, Subscription Services Customer Type: Individual Consumers, Businesses, Bars, Restaurants Price Tier: Premium, Mid-Range, Economy, Discount |
| Companies Covered | The Beer Guy, Drizly Canada, Wine Online, Amazon Fresh Alcohol, Instacart Alcohol Delivery, South Park Liquor, LCBO, Local independent online liquor retailers, Toby's Liquor Store, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Alcohol E-Commerce Market Trends and Innovations
Digital identity infrastructure and predictive fulfillment algorithms are compressing delivery windows while regulatory technology solutions attempt to automate compliance across fragmented provincial frameworks.
Blockchain-based provenance tracking is miniaturizing supply chain transparency into consumer-facing mobile interfaces. British Columbia craft distilleries are embedding batch-level origin data into QR-coded labels. This authentication layer is miniaturizing the information asymmetry between mass-market and artisanal product positioning.
Health Canada's pending excise reform consultations are forcing platform operators to model scenario-based pricing architectures. The proposed volumetric taxation shift would compress spirits margin structures relative to lower-ABV alternatives. Wine Online and specialized import curators are accelerating cellar-door direct relationships to preempt distributor-tier cost absorption.
Subscription-based curation services are displacing transactional search-and-purchase behaviors among Toronto and Vancouver high-income households. These members receive algorithm-selected portfolios matched to consumption history and seasonal preference data. Quebec's SAQ monopoly structure limits this model's penetration relative to Ontario's more permissive private retail environment.
Canada Alcohol E-Commerce Market Segmentation
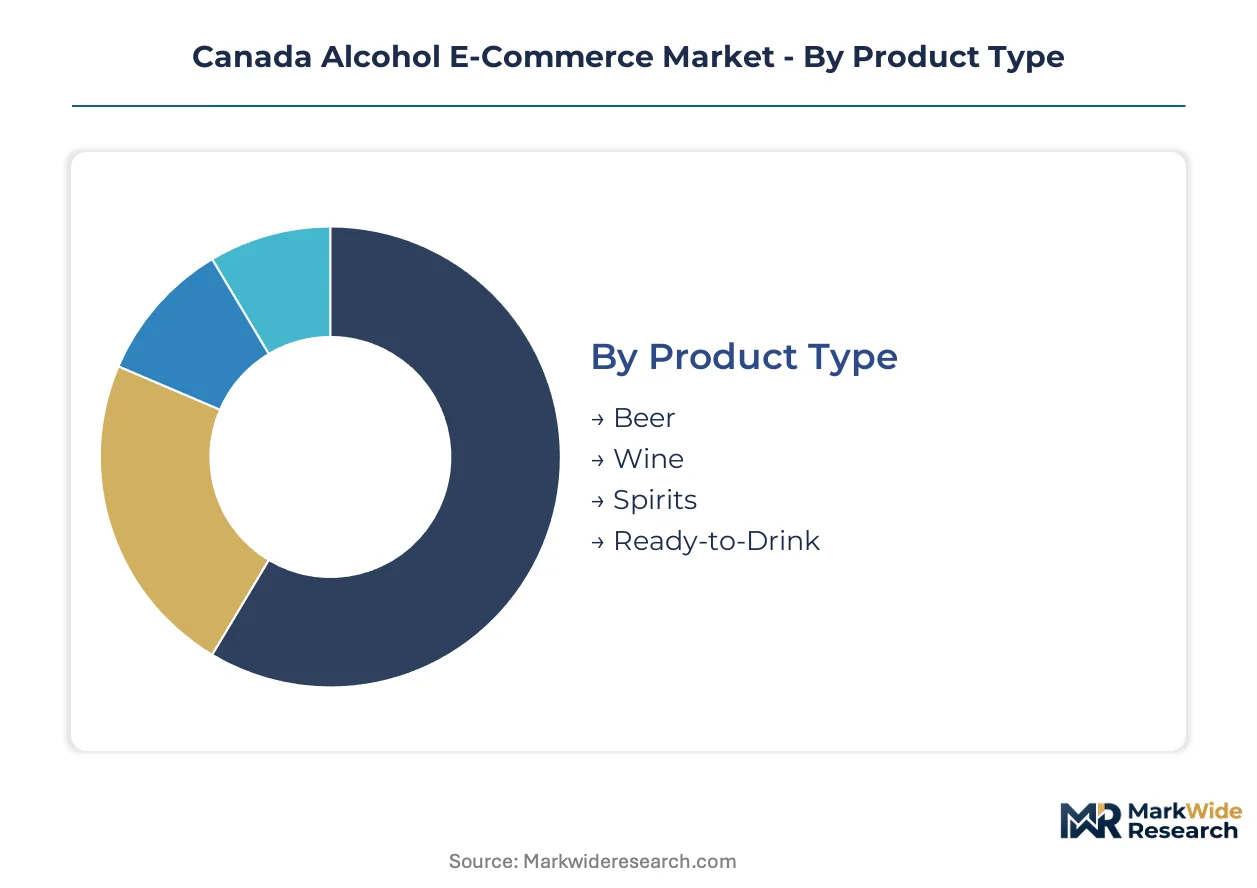
Segmentation in Canadian alcohol e-commerce reveals how provincial regulatory fragmentation and urban consumption patterns create divergent growth trajectories across product categories and channel types. Understanding these divides enables platform operators to allocate fulfillment infrastructure and procurement budgets against addressable demand pools.
Product Type:
Wine and spirits concentrate in Ontario and British Columbia direct-to-consumer channels, while beer dominates Quebec and Atlantic Canada through delivery-platform intermediaries.
- Wine:Domestic VQA products from Niagara and Okanagan Valley anchor inventory breadth, with import curation driving margin expansion in Toronto and Vancouver high-rise corridors where cellar-door access is limited. LCBO's monopoly pricing and SAQ's controlled distribution create procurement complexity for private platforms seeking Bordeaux and Burgundy allocations.
- Spirits:Craft distillery growth in British Columbia and Alberta generates SKU proliferation that legacy provincial systems struggle to merchandise digitally. Health Canada excise duties on spirits compress margin flexibility relative to lower-ABV alternatives, forcing platforms toward premium positioning to absorb taxation overhead.
- Beer:Ontario craft brewery density and Quebec microbrasserie culture sustain subscription curation demand, though provincial warehousing monopolies constrain cold-chain freshness guarantees for interprovincial shipments.
- Ready-to-Drink:Premium canned cocktails attract Toronto and Montreal millennial households seeking convenience without bar-premium pricing, creating hybrid category positioning between spirits and beer taxonomies.
Wine holds the largest share; momentum sits with ready-to-drink formulations.
Distribution Channel:
Channel economics diverge sharply between crown corporation integration requirements and pure-play digital fulfillment costs.
- Direct-to-Consumer:British Columbia and Ontario winery shipping law relaxation enables vineyard-to-door logistics that bypass distributor markups. Niagara and Okanagan producers leverage this channel to capture margin previously lost to LCBO and private wine shop intermediaries.
- Online Retailers:SAQ.com and LCBO.com process the highest absolute transaction volumes through monopoly-controlled inventory access, though platform UX limitations create frustration among digital-native consumers expecting aggregator-style discovery.
- Delivery Services:Drizly Canada and Instacart alcohol modules sustain last-mile density through third-party logistics partnerships without warehouse capital deployment, concentrating in Toronto, Montreal, and Vancouver postal codes where order frequency justifies driver utilization.
- Subscription Services:Algorithmic curation models penetrate Ontario and British Columbia faster than Quebec due to SAQ regulatory constraints on private retail experimentation, with Toronto households showing highest trial rates for wine club memberships.
Online retailers command current volume leadership; subscription services are climbing the fastest.
Customer Type:
Demand concentration shifts between urban residential clusters and foodservice recovery corridors.
- Individual Consumers:Millennial and Gen Z cohorts in Toronto and Vancouver high-rise developments drive same-day delivery adoption, with age-verification protocols creating friction points that platforms address through digital identity integration.
- Businesses:Corporate gifting and event procurement sustain mid-range wine and spirits demand, though bulk shipping regulations vary across provincial liquor authorities and complicate national account servicing.
- Bars:Toronto and Montreal independent establishments source specialty spirits through digital channels when LCBO and SAQ allocation systems create stockouts, particularly for craft amaro and mezcal SKUs.
- Restaurants:Post-pandemic restocking patterns favor delivery-platform speed over price optimization, with Vancouver and Calgary fine-dining segments prioritizing provenance documentation for wine list curation.
Individual consumers represent the dominant segment; restaurants are gaining share fastest amid foodservice normalization.
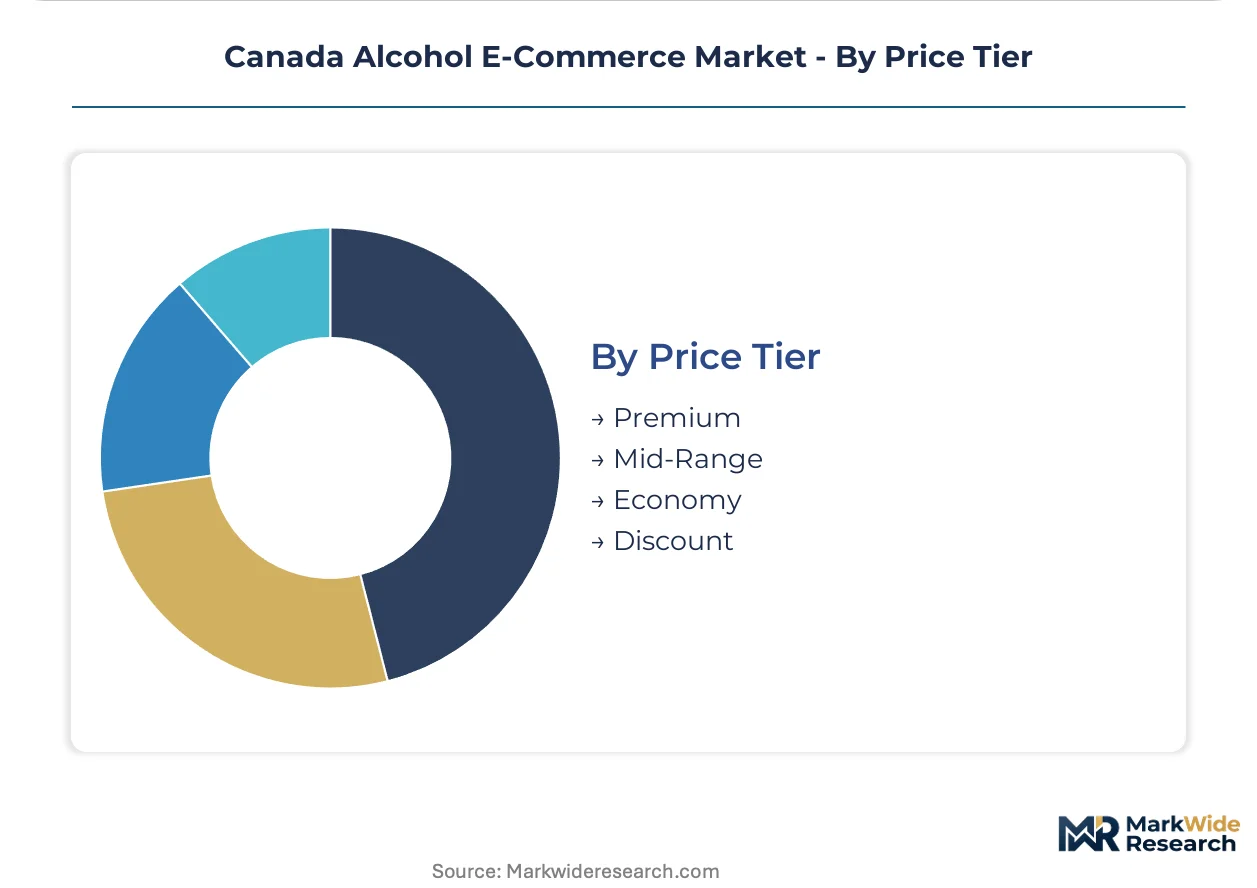
Price Tier:
Premium and mid-range tiers concentrate in Ontario and British Columbia where disposable income and import access align.
- Premium:Bordeaux futures, single-malt Scotch, and prestige Champagne command loyalty among Vancouver and Toronto high-net-worth households, with provenance authentication becoming a platform differentiator against mass-market competitors.
- Mid-Range:VQA wines and craft spirits from established Canadian producers balance margin and velocity, representing the core revenue pool for Wine Online and specialized import curators.
- Economy:Domestic lager and value wine SKUs sustain volume through delivery-platform promotions, though excise tax floors limit deep-discounting flexibility relative to US market comparisons.
- Discount:Private-label and closeout inventory moves through flash-sale mechanisms in Alberta's privatized environment, with regulatory restrictions preventing equivalent models in Ontario and Quebec.
Mid-range tiers anchor revenue stability; premium positioning shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's alcohol e-commerce trade flows remain trapped within provincial boundaries due to interprovincial shipping prohibitions, creating parallel inventory pools that duplicate warehousing investment and fragment fulfillment economics across the federation.
Ontario
Toronto's high-rise residential density and aging LCBO infrastructure drive same-day delivery adoption among millennial households. The Alcohol and Gaming Commission of Ontario is relaxing direct-to-consumer shipping restrictions, enabling British Columbia wineries to reach urban consumers directly. The Greater Toronto Area corridor concentrates order frequency for delivery-platform operators seeking driver utilization economies.
Quebec
Montreal's microbrasserie culture sustains craft beer subscription demand that SAQ's monopoly structure constrains from full digital experimentation. Provincial liquor control acts prevent cross-border inventory movement, forcing platforms to maintain separate Quebec-specific stock positions. The city's restaurant recovery corridor prioritizes provenance documentation for wine list curation through digital channels.
British Columbia
Vancouver's craft distillery proliferation generates SKU variety that legacy provincial systems struggle to merchandise digitally. Health Canada guidelines for digital age-gating create compliance friction that platforms address through digital identity integration. The Okanagan Valley wine cluster leverages relaxed shipping rules to capture margin previously lost to distributor intermediaries.
Alberta
Calgary's privatized retail environment enables flash-sale mechanisms and discount positioning unavailable in crown corporation provinces. The Canada Revenue Agency's excise duty administration creates price floors that compress margin flexibility for spirits-focused platforms. Independent retailers in Edmonton and Calgary postal codes experiment with algorithmic curation models ahead of eastern markets.
Atlantic Canada
Halifax's demographic in-migration from Ontario brings digital-native purchasing expectations that legacy retail footprints cannot satisfy. Newfoundland and Labrador's privatized structure offers regulatory arbitrage for digital-first entrants to establish market presence. The region's lower competitive saturation attracts platform operators seeking territory before incumbent consolidation.
Canada Alcohol E-Commerce Market Competitive Landscape
Concentration sits with crown corporation platforms and delivery-service intermediaries rather than pure-play digital natives. The competitive map splits between monopoly-controlled inventory access and third-party logistics partnerships that sustain last-mile density without warehouse capital deployment. Two strategic archetypes dominate: provincial retailers defending gatekeeping positions through exclusive product access, and aggregator platforms leveraging driver networks for speed-based differentiation. Competitive moves center on regulatory lobbying for shipping rule relaxation and cold-chain infrastructure partnerships that reduce fulfillment capital intensity.
Within the crown corporation tier, LCBO anchors Ontario's market through monopoly-controlled inventory and established trust metrics. Among delivery-platform specialists, Drizly Canada exemplifies the capital-light model through third-party logistics partnerships. Wine Online occupies a curated-import position that mass-market platforms cannot replicate, specializing in portfolios that emphasize provenance transparency for Vancouver and Toronto high-net-worth households.
| Leading Market Players |
|---|
| The Beer Guy |
| Drizly Canada |
| Wine Online |
| Amazon Fresh Alcohol |
| Instacart Alcohol Delivery |
| South Park Liquor |
| LCBO |
| Local independent online liquor retailers |
| Toby's Liquor Store |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with third-party cold-chain specialists lock in temperature-controlled logistics access and cost visibility for platform operators seeking national coverage without warehouse ownership. These arrangements anchor procurement economics in Ontario and British Columbia while insulating margins from spot-market volatility in refrigerated transport.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in Canadian alcohol e-commerce. Premium positioning absorbs Health Canada excise duties on spirits through provenance transparency and limited allocations, while economy tiers face compression from Canada Revenue Agency price floors that constrain discounting flexibility. Pricing pressure stems from crown corporation monopoly pricing power in Ontario and Quebec, which limits private platform margin expansion. Restaurant procurement teams show highest price sensitivity due to post-pandemic cash flow constraints, whereas Toronto and Vancouver high-net-worth households demonstrate lowest sensitivity for authenticated imports.
Supply Chain Analysis
Just-in-time inventory strategies dominate delivery-platform operations, though strategic stockpiling persists among specialized import curators managing Bordeaux and Burgundy allocations. Geographic supply concentration draws from France, Italy, and California for wine; Scotland and Japan for spirits; and Ontario and British Columbia for domestic VQA products. Raw material dependencies rest on glass bottle supply from Mexico and China, oak barrel cooperage from France and the United States, and aluminum can stock from domestic smelters. Single-source vulnerability concentrates in Okanagan Valley grape supply during climate-stressed vintages. Distribution runs through provincially licensed warehouses in crown corporation provinces and third-party fulfillment centers in Alberta and Atlantic Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from direct-to-consumer winery shipping that captures margin previously flowing through distributor tiers. Platform operators must navigate whether regulatory modernization opens arbitrage opportunities or consolidates crown corporation gatekeeping.
For Market Incumbents: Secure exclusive import allocations through cellar-door direct relationships before distributor-tier cost absorption intensifies. Lock in temperature-controlled logistics partnerships to reduce fulfillment capital intensity against delivery-platform competitors. Crown corporation pricing power and pending federal excise reform represent dual threats requiring proactive regulatory engagement and scenario-based pricing architectures.
For New Entrants and Emerging Players: Lead with regulatory arbitrage in Newfoundland and Labrador's privatized retail environment before competitive saturation closes the window. Target Halifax and Victoria demographic in-migration corridors where digital-native purchasing expectations outpace legacy retail infrastructure. Deploy algorithmic curation models in Ontario's permissive private retail environment, where SAQ constraints limit incumbent response speed.
For Investors and Strategic Acquirers: Curated-import specialists with provenance authentication capabilities offer the strongest acquisition target archetype for premium positioning defensibility. Long-term viability hinges on whether provincial shipping rule relaxation enables national platform economics or fragments further around crown corporation structures. Watch for Alcohol and Gaming Commission of Ontario regulatory announcements as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Shipping Expansion | Bypasses LCBO and SAQ distributor markups for Okanagan and Niagara producers. |
| Temperature-Controlled Logistics Partnership | Reduces capital requirements for national coverage without warehouse ownership. |
| Blockchain Provenance Integration | British Columbia craft distilleries embed batch-level origin data into consumer-facing interfaces. |
| Subscription Curation Service Launch | Penetrates Toronto and Vancouver faster than Quebec due to SAQ regulatory constraints. |
| Atlantic Canada Market Entry | Newfoundland and Labrador privatization offers first-mover positioning before saturation. |
Research Methodology
Operator-level perspectives from platform executives, provincial liquor board procurement directors, cold-chain logistics specialists, and winery direct-to-consumer managers anchored the qualitative base. Primary interviews combined with secondary validation from Canada Revenue Agency excise duty disclosures, Health Canada regulatory filings, Alcohol and Gaming Commission of Ontario proceedings, and provincial liquor authority annual reports. Bottom-up demand modeling across product type, distribution channel, customer segment, and price tier triangulated against top-down market sizing from customs and trade flow analysis.
Sensitivity analysis tested forecast outputs against regulatory modernization scenarios and excise reform variants across the analysis window. Segmentation dimensions modeled include product type, distribution channel, customer archetype, price tier, and provincial regulatory framework. CAGRs derived from trend extrapolation adjusted for demographic migration patterns and urban density concentration effects. Industry-specific inputs incorporated millennial and Gen Z purchasing behavior shifts and crown corporation infrastructure decay rates.
The analysis sits within stated boundaries; outcomes outside continued provincial monopoly structures or accelerated federal excise reform would require recalibration. Forecasts reflect documented assumptions regarding regulatory modernization timing and interprovincial shipping rule relaxation. Revision becomes warranted when Alcohol and Gaming Commission of Ontario policy announcements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Beer Glass Chillers Market