
 South and Southeast Asia Seed Market | 2026-2036
South and Southeast Asia Seed Market Size, Share, and Industry Trends Forecast 2026-2036
South and Southeast Asia Seed Market Analytics
Hybrid seed development revenue is narrowing as proprietary germplasm licensing replaces open-pollinated variety distribution across South and Southeast Asia. Bayer AG leverages its global trait library to anchor biotech cotton and corn positions in India and Pakistan. East-West Seed International B.V. dominates tropical vegetable genetics, while Charoen Pokphand Group controls integrated poultry-feed-seed supply chains from Bangkok into Indochina.
South and Southeast Asia seed encompasses genetically stable propagules selected for germination vigor, disease resistance, and yield uniformity across tropical monsoon and subtropical agro-ecologies, typically treated with polymer coatings containing fungicides and micronutrients to ensure field establishment under erratic rainfall. The product serves to secure food supply chains, reduce crop loss volatility, and enable contract farming compliance for export-oriented horticulture. Cereals and pulses occupy mature volume positions with thin margins, whereas fruits and vegetables command premium pricing through hybrid trait density and shorter breeding cycles. Distribution through agro-dealers and cooperatives sustains rural penetration, though online retail channels gain traction where last-mile cold chain infrastructure improves.
India's BIS seed certification standards, Thailand's Department of Agriculture quality enforcement, and Vietnam's Ministry of Agriculture and Rural Development variety registration requirements collectively restrict unregistered seed circulation and elevate formal sector compliance costs. These frameworks push smaller traders toward licensed distribution partnerships while rewarding R&D-intensive firms with protected variety portfolios. Stakeholders must monitor regulatory divergence between national seed policies and the ASEAN harmonization roadmap to anticipate cross-border licensing complexity.
Market Dynamics
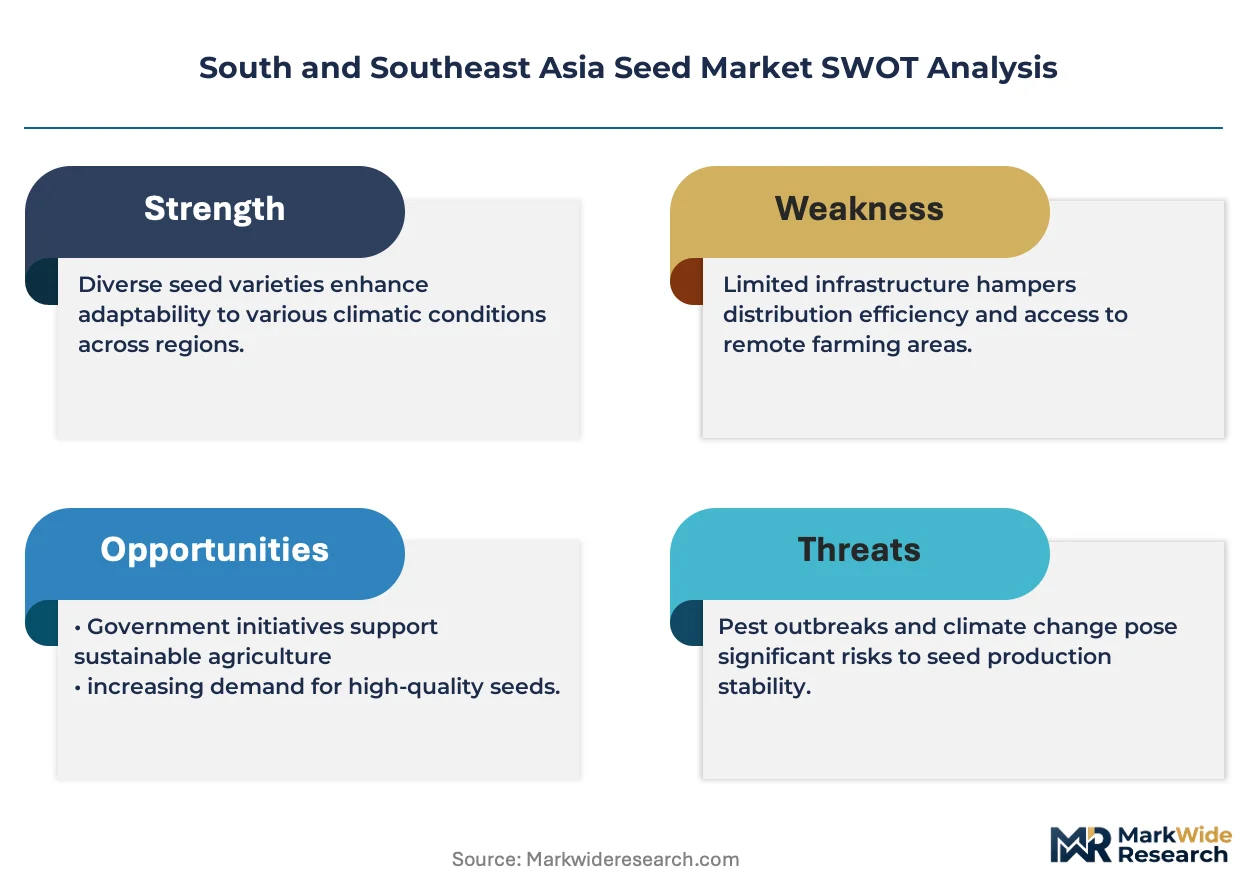
Proprietary germplasm licensing is displacing open-pollinated variety distribution across South and Southeast Asia, compressing margins for legacy seed traders while elevating compliance barriers for market entry.
Growth Catalysts
- India's PLI Scheme for Agriculture:Production-linked incentives accelerate formal channel penetration by subsidizing certified seed multiplication infrastructure in the Indo-Gangetic Plain.
- Hybrid Trait Density:Tropical vegetable genetics with stacked disease resistance and yield uniformity traits command premium positioning in Vietnam's Mekong Delta contract farming operations.
- Thailand's National Seed Certification Reforms:Department of Agriculture quality enforcement redirects informal traders toward licensed distribution partnerships with R&D-intensive firms.
Market Restraints
- Input Cost Volatility:Polymer coating materials and fungicide treatments face petrochemical price swings that compress treatment margins for seed processors.
- Regulatory Divergence:India's BIS certification standards, Thailand's quality enforcement protocols, and Vietnam's variety registration requirements create fragmented compliance costs across the ASEAN harmonization roadmap.
- Technical Limitation:Erratic monsoon rainfall patterns degrade germination vigor in untreated open-pollinated varieties, limiting farmer recourse against climate volatility.
Strategic Opportunities
- Underpenetrated Geography:Myanmar's Ayeyarwady Delta lacks formal seed certification infrastructure, creating first-mover positioning for integrated germplasm-licensing operators.
- Technology Convergence:Digital phenotyping platforms and drone-enabled field monitoring compress breeding cycle timelines for tropical vegetable hybrids.
- Channel Innovation:Online retail seed platforms gain traction in Indonesia's Java corridor where last-mile cold chain infrastructure improvements reduce post-harvest viability loss.
Industry Challenges
- Skill Gap in Molecular Breeding:Shortage of trained geneticists with marker-assisted selection expertise constrains local adaptation of proprietary trait libraries.
- Certification Timeline Compression:Vietnam's Ministry of Agriculture and Rural Development variety registration requirements extend multi-season field trials, delaying commercial launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South and Southeast Asia Seed Market |
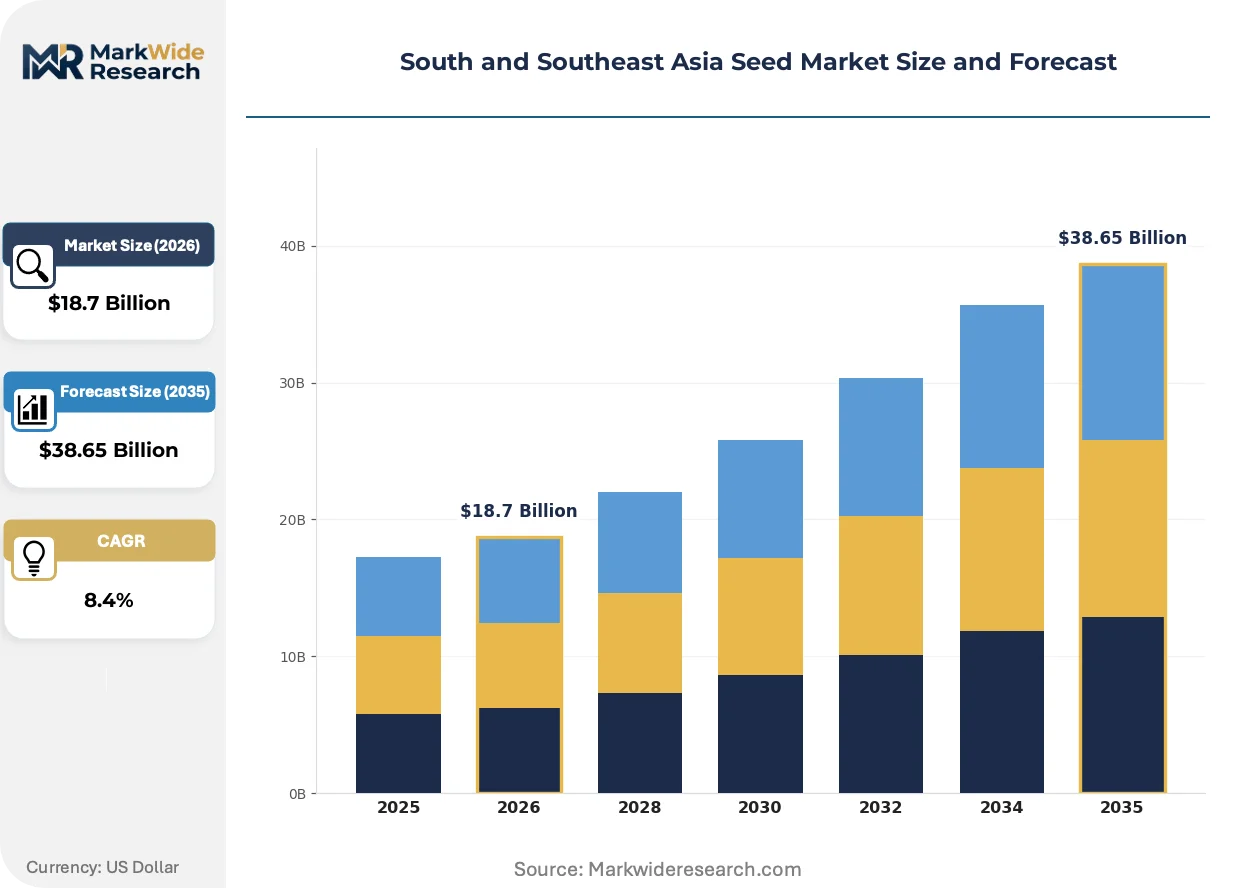
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Cereals, Pulses End User: Farmers, Agro-dealers, Cooperatives, Agricultural Institutions Distribution Channel: Online Retail, Direct Sales, Wholesale, Local Markets Application: Commercial Farming, Home Gardening, Research, Seed Breeding |
| Companies Covered | Syngenta Group, Bayer AG, East-West Seed International B.V., Charoen Pokphand Group, Groupe Limagrain, Known You Seed Co. Ltd., Nuziveedu Seeds Limited, Advanta Seeds International, Sakata Seed Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South and Southeast Asia Seed Market Evolving Landscape
Digital trait discovery platforms and climate-adaptive breeding pipelines are compressing traditional development timelines while regulatory enforcement hardens formal sector boundaries across the region.
Gene editing via CRISPR-Cas9 is collapsing the historical trade-off between disease resistance and yield stability in tropical rice germplasm. Indonesian state research institutes and Vietnamese commercial breeders are adopting edited lines for bacterial blight resistance at accelerated pace. The technology is collapsing multi-year backcrossing requirements into single-season trait introgression, enabling faster variety turnover in flood-prone lowlands.
Thailand's Department of Agriculture quality enforcement mandates now require polymerase chain reaction-based genetic purity testing for all certified hybrid seed lots. This industrial consequence elevates laboratory infrastructure requirements for domestic multipliers while disqualifying informal sector suppliers. Vegetable seed categories with shorter breeding cycles face the steepest compliance cost escalation, pushing consolidation toward vertically integrated breeding-to-certification operators.
Contract farming procurement now specifies certified hybrid germplasm as a condition of export-oriented horticulture supply agreements. Indonesian chili and Vietnamese dragon fruit aggregators are displacing traditional agro-dealer relationships with direct breeder-processor partnerships. This pattern concentrates most visibly in Thailand's central plains, where integrated poultry-feed-seed conglomerates enforce captive seed sourcing for contract vegetable growers supplying ASEAN retail chains.
South and Southeast Asia Seed Market Segmentation
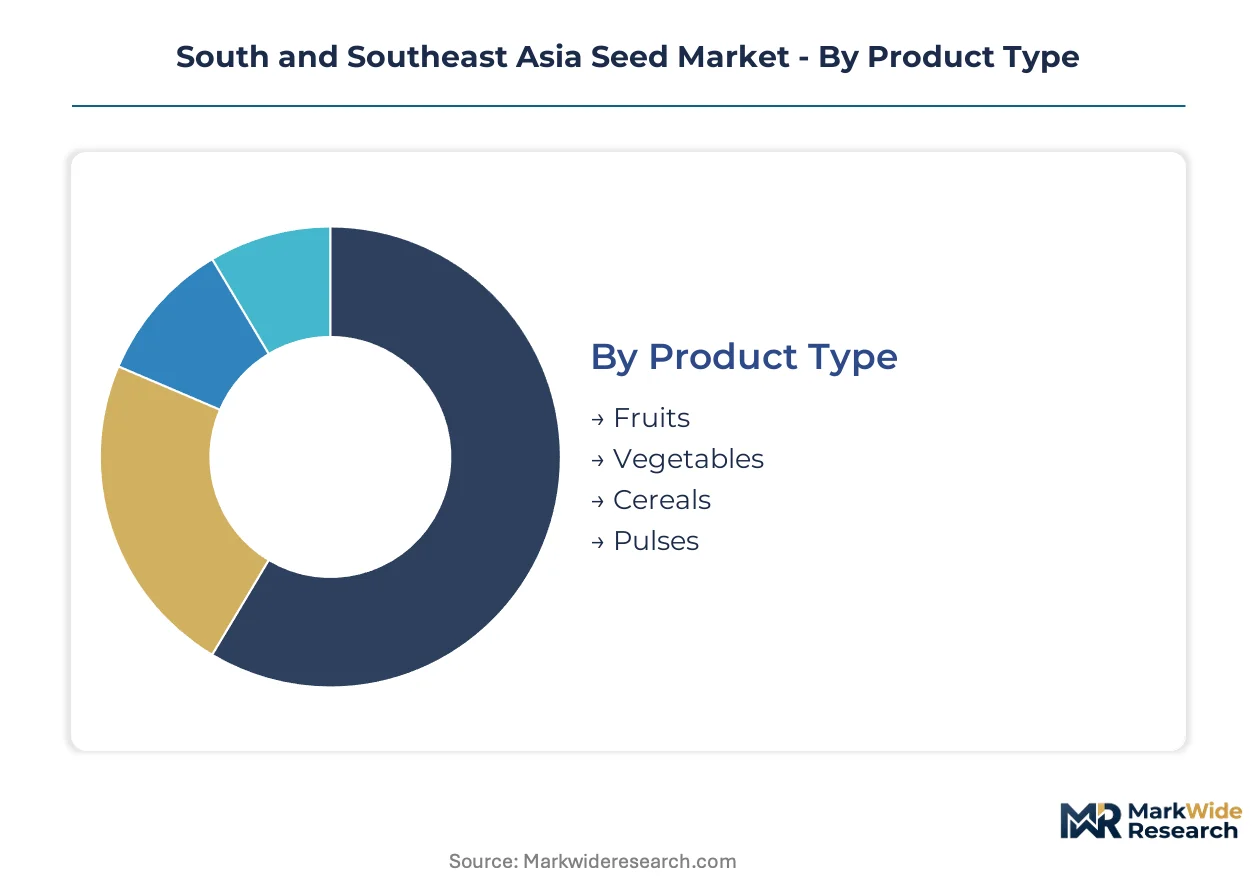
Seed portfolio strategy in South and Southeast Asia hinges on breeding cycle economics and trait density premiums. Segment boundaries determine margin capture, certification compliance costs, and channel access requirements across tropical agro-ecologies.
Product Type:
Cycle times vary dramatically across crop categories, with vegetables turning over in 18-24 months versus cereals requiring 5-7 year development pipelines.
- Vegetables:Tropical hybrids with stacked disease resistance and yield uniformity traits command premium positioning in Vietnam's Mekong Delta contract farming operations. Breeders compress development timelines through marker-assisted selection for bacterial wilt and powdery mildew resistance in solanaceous crops.
- Fruits:Polyembryonic mango and citrus rootstocks with graft compatibility and salinity tolerance anchor commercial orchards in Thailand's central plains and Indonesia's Java corridor. Long juvenile periods and clonal propagation requirements sustain higher entry barriers than annual crops.
- Cereals:Hybrid rice and maize occupy mature volume positions with thin margins across India's Indo-Gangetic Plain.
- Pulses:Open-pollinated varieties dominate farmer-saved seed systems in rainfed regions of Myanmar and Bangladesh.
Cereals anchor the volume base while vegetables gain share at the steepest rate.
End User:
Procurement sophistication and compliance capacity separate formal channel participants from informal sector actors.
- Agro-dealers:Licensed distributors with BIS certification compliance and cold chain infrastructure capture hybrid vegetable demand in India's Punjab and Haryana. Inventory financing constraints and working capital cycles determine geographic coverage depth.
- Farmers:Smallholder procurement concentrates in untreated open-pollinated varieties where seed-saving practices persist. India's PLI scheme for agriculture redirects volumes toward certified germplasm through subsidized multiplication infrastructure.
- Cooperatives:Bulk purchasing power and shared storage facilities reduce per-unit certification costs for member cultivators in Vietnam's Mekong Delta.
- Agricultural Institutions:State research stations and agricultural universities maintain breeder seed production for variety release pipelines.
Farmers constitute the largest addressable base while agro-dealers capture margin expansion most rapidly.
Distribution Channel:
Last-mile viability requirements and transaction scale dictate channel economics across the region's infrastructure gradients.
- Direct Sales:Breeder-processor partnerships displace traditional intermediaries in Indonesian chili and Vietnamese dragon fruit supply chains. Contract farming procurement mandates specify certified hybrid germplasm as a condition of export-oriented horticulture agreements.
- Online Retail:Digital platforms gain traction in Indonesia's Java corridor where cold chain improvements reduce post-harvest viability loss. Polymer-coated seed lots with extended shelf life suit e-commerce fulfillment models.
- Wholesale:Aggregated volumes flow through Bangkok-based distributors into Indochina markets.
- Local Markets:Unregistered seed circulation persists where formal certification infrastructure remains underdeveloped.
Wholesale channels dominate current volume flows while online retail climbs the fastest.
Application:
End-use specifications determine trait prioritization and pricing architecture across the value chain.
- Commercial Farming:Export-oriented operations in Thailand's central plains and Vietnam's Mekong Delta specify certified hybrid germplasm with genetic purity documentation. Charoen Pokphand Group enforces captive seed sourcing for contract vegetable growers supplying ASEAN retail chains.
- Seed Breeding:Proprietary germplasm licensing and trait library access anchor competitive positioning for tropical vegetable genetics. CRISPR-Cas9 editing collapses multi-year backcrossing into single-season trait introgression for bacterial blight resistance in Indonesian and Vietnamese rice programs.
- Home Gardening:Small-scale demand concentrates in untreated open-pollinated varieties with lower unit price points.
- Research:State institutes and commercial breeders conduct multi-season field trials under Vietnam's Ministry of Agriculture and Rural Development variety registration protocols.
Commercial farming absorbs the majority of premium hybrid volumes while seed breeding commands the highest per-unit value realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across South and Southeast Asia. Myanmar and Bangladesh farmers prioritize low-cost open-pollinated varieties, while Vietnam's Mekong Delta contract growers absorb premium hybrid pricing for export compliance.
India
Hybrid maize and cotton demand concentrates in Gujarat and Maharashtra's commercial farming belts. BIS seed certification standards enforce genetic purity testing for all certified lots. The Indo-Gangetic Plain corridor from Punjab to West Bengal anchors formal channel penetration through PLI-subsidized multiplication infrastructure.
Vietnam
Export-oriented dragon fruit and chili operations drive certified hybrid procurement in the Mekong Delta. Ministry of Agriculture and Rural Development variety registration protocols mandate multi-season field trials. Ho Chi Minh City-based aggregators displace traditional agro-dealers through direct breeder-processor partnerships.
Thailand
Integrated poultry-feed-seed conglomerates enforce captive germplasm sourcing for contract vegetable growers. Department of Agriculture quality enforcement mandates PCR-based genetic purity testing for certified hybrid lots. The central plains region surrounding Bangkok concentrates breeding-to-certification vertical integration.
Indonesia
Java corridor commercial farms specify polymer-coated hybrid seed for tropical vegetables with extended shelf life. State research institutes accelerate CRISPR-edited rice lines for bacterial blight resistance. Digital retail platforms gain traction where cold chain improvements reduce post-harvest viability loss.
Myanmar
Farmer-saved seed systems dominate the Ayeyarwady Delta's rainfed rice cultivation. Absence of formal certification infrastructure preserves unregistered circulation channels. First-mover positioning awaits integrated germplasm-licensing operators willing to build laboratory and field trial capacity.
South and Southeast Asia Seed Market Competitive Landscape
Global agrochemical conglomerates and tropical vegetable specialists split the market between trait-dense field crops and premium horticultural genetics. Bayer AG anchors biotech cotton and corn positions through proprietary germplasm licensing. East-West Seed International B.V. dominates solanaceous and cucurbit breeding for tropical conditions. Charoen Pokphand Group leverages Bangkok-based integration across poultry, feed, and seed supply chains into Indochina markets. Competitive moves concentrate on regulatory compliance capacity and captive distribution partnerships.
Within the tropical vegetable specialist tier, East-West Seed International B.V. and Known You Seed Co. Ltd. exemplify breeding-to-distribution integration for high-value solanaceous crops. Syngenta Group and Bayer AG represent the agrochemical-biotech complex, leveraging global trait libraries for field crop positions in India and Pakistan. Nuziveedu Seeds Limited anchors domestic Indian cotton and rice germplasm licensing. Sakata Seed Corporation occupies a position in premium brassica and Allium genetics for export-oriented East Asian supply chains.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| East-West Seed International B.V. |
| Charoen Pokphand Group |
| Groupe Limagrain |
| Known You Seed Co. Ltd. |
| Nuziveedu Seeds Limited |
| Advanta Seeds International |
| Sakata Seed Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in India's PLI-subsidized seed multiplication infrastructure drives aggressive pricing for certified hybrid germplasm while compressing margins for legacy open-pollinated variety traders. This utilization imbalance rewards R&D-intensive firms with protected trait libraries and forces smaller multipliers toward licensed distribution partnerships or exit.
Pricing Analysis
After-sales technical support and replanting guarantees drive lifetime value capture for tropical vegetable hybrid suppliers in Vietnam's Mekong Delta. Three-tier pricing structure across premium certified hybrids, standard certified open-pollinated varieties, and economy untreated farmer-saved seed dominates transaction architecture. Price differentiation rests on BIS genetic purity certification tier and polymer coating treatment grade. Cost compression in standard-tier untreated varieties is intensifying because petrochemical input volatility erodes treatment margins. Smallholder farmers in Myanmar's rainfed systems exhibit highest price sensitivity; export-oriented contract growers in Thailand's central plains absorb premium positioning with least resistance.
Supply Chain Analysis
Export-control restrictions on CRISPR-edited germplasm and proprietary trait libraries limit technology flows into Indonesian and Vietnamese breeding programs. Supply concentration centers on Thailand for integrated poultry-feed-seed conglomerates, India for cotton and rice germplasm licensing, and the Netherlands for tropical vegetable genetics. Raw material dependencies include polymer coating petrochemicals, fungicide active ingredients, and laboratory reagents for PCR-based purity testing. Single-source vulnerability in proprietary trait library access threatens breeding pipeline continuity. Distribution runs through Bangkok-based wholesale aggregators into Indochina markets, with licensed agro-dealers capturing last-mile penetration in India's Indo-Gangetic Plain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-Cas9 gene editing is collapsing multi-year backcrossing timelines into single-season trait introgression, disrupting traditional breeding economics and accelerating variety turnover across the region.
For Market Incumbents: Insulate proprietary germplasm positions through backward integration into certified multiplication infrastructure in Vietnam's Mekong Delta and India's Indo-Gangetic Plain. Deepen captive distribution partnerships with export-oriented contract farming aggregators to lock out emerging trait-library licensors. PCR-based genetic purity testing mandates from Thailand's Department of Agriculture elevate compliance barriers that favor incumbents with existing laboratory infrastructure. For New Entrants and Emerging Players: Myanmar's Ayeyarwady Delta presents first-mover positioning for integrated germplasm-licensing operators willing to build field trial and certification capacity from absence. Target Indonesian Java corridor online retail channels where cold chain improvements reduce post-harvest viability loss and polymer-coated seed lots suit e-commerce fulfillment. Pursue direct breeder-processor partnerships with dragon fruit and chili aggregators displacing traditional agro-dealer relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tropical vegetable specialists with breeding-to-certification vertical integration and captive distribution into contract farming supply chains. Long-term viability over the projection horizon favors R&D-intensive firms with protected variety portfolios and regulatory compliance capacity across divergent national seed policies. Monitor ASEAN harmonization roadmap progress as inflection indicator for cross-border licensing complexity reduction.| Strategic Initiative | Industry Significance |
|---|---|
| PCR-Based Genetic Purity Testing Investment | Thailand's Department of Agriculture mandates disqualify informal sector suppliers from certified hybrid lots. |
| Direct Breeder-Processor Partnership Formation | Indonesian chili and Vietnamese dragon fruit aggregators displace traditional agro-dealer intermediaries. |
| CRISPR Trait Library Licensing Expansion | Indonesian state research institutes accelerate edited rice lines for bacterial blight resistance. |
| Online Retail Platform Development | Java corridor cold chain improvements enable polymer-coated seed e-commerce fulfillment with extended shelf life. |
| Myanmar Certification Infrastructure Buildout | Absence of formal seed certification infrastructure preserves unregistered circulation and first-mover opportunity. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with seed company R&D directors, agro-dealer network managers, contract farming procurement officers, and Department of Agriculture regulatory leads; and secondary validation through BIS certification databases, ASEAN seed harmonization policy documents, customs germplasm import records, and PLI scheme disbursement filings. Bottom-up variety-level volume estimates triangulated against top-down national seed replacement rate projections.
Forecast inputs considered breeding cycle economics, trait density premium capture, and regulatory compliance cost escalation across the projection horizon. Segmentation dimensions modeled include crop category cycle times, end-user procurement sophistication tiers, distribution channel infrastructure gradients, and application-specific trait prioritization. CAGRs derived from weighted average of historical certified seed penetration trends and policy-driven formal channel acceleration scenarios. Industry-specific inputs incorporated monsoon rainfall variability indices and polymer coating input cost trajectories.
Practitioners should monitor ASEAN seed policy harmonization progress, CRISPR regulatory classification shifts, and PLI scheme renewal terms for early signals of forecast revision. Forecasts reflect documented assumptions regarding breeding pipeline continuity and certification infrastructure buildout timelines. Material shifts in ASEAN harmonization roadmap implementation or national seed policy divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Philippines Rice Seed Market
Seeds
Africa Seed Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Pumpkin Seeds Market
Seeds
United States Forage Seed Market
Seeds
Tomato Seed Market
Seeds
Fruit Seed Waste Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Quinoa Seed Market
Seeds
Tallow Tree Seed Market
Seeds
Africa Vegetable Seed Market
Seeds
North America Forage Seed Market
Seeds
Organic Chia Seeds Market
Seeds
United States Vegetable Seed Market
Seeds
Guar Market
Seeds
Drought Tolerant Seeds Market