
 Global Yield Monitoring Devices Market | 2026-2036
Global Yield Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Yield Monitoring Devices Market Intelligence
Software subscription revenue for crop yield analysis is fragmenting the traditional hardware-centric business model. Deere & Company leverages its extensive equipment network to integrate proprietary software services and data platforms. Trimble Inc. specializes in agnostic GPS-based systems compatible with multiple equipment brands, offering interoperability. AGCO Corporation competes through its Fuse smart farming platform, which provides a suite of digital tools for mixed-fleet operations.
Yield monitoring devices are integrated systems that measure and record crop flow during harvest. These units typically combine a grain flow sensor, a moisture sensor, and GPS technology to generate real-time, georeferenced yield data for field mapping. GPS-based systems remain the foundational technology, but optical sensors are gaining share in specialized applications like forage quality assessment. While crop yield analysis is the primary application, demand for resource management capabilities represents the fastest-growing segment.
Data privacy regulations like the EU's GDPR impact how farm data is managed and shared by device platforms. In the United States, USDA programs provide financial incentives for adopting precision agriculture technologies that improve sustainability. Vendor success will depend on creating open platforms that can integrate data from multiple sources while navigating disparate regional data governance rules.
Market Dynamics
The primary structural force is the transition from a hardware-centric model to a data-driven service economy. This shift is compelled by the increasing scale of farm operations and global sustainability mandates requiring auditable resource efficiency and crop traceability.
Growth Catalysts
- Precision Agriculture Mandates:The EU Green Deal's farm-to-fork strategy creates direct incentives for technologies that improve resource efficiency and reduce chemical inputs, boosting device adoption.
- Large-Scale Farming Economics:Demand for precision planting and harvesting from large agricultural enterprises in Brazil and the United States requires yield monitoring to optimize input costs across vast acreages.
- Sensor Technology Maturation:The decreasing cost and increasing accuracy of GPS receivers, grain flow sensors, and moisture sensors make yield monitoring systems economically viable for a wider base of farm operations.
Market Restraints
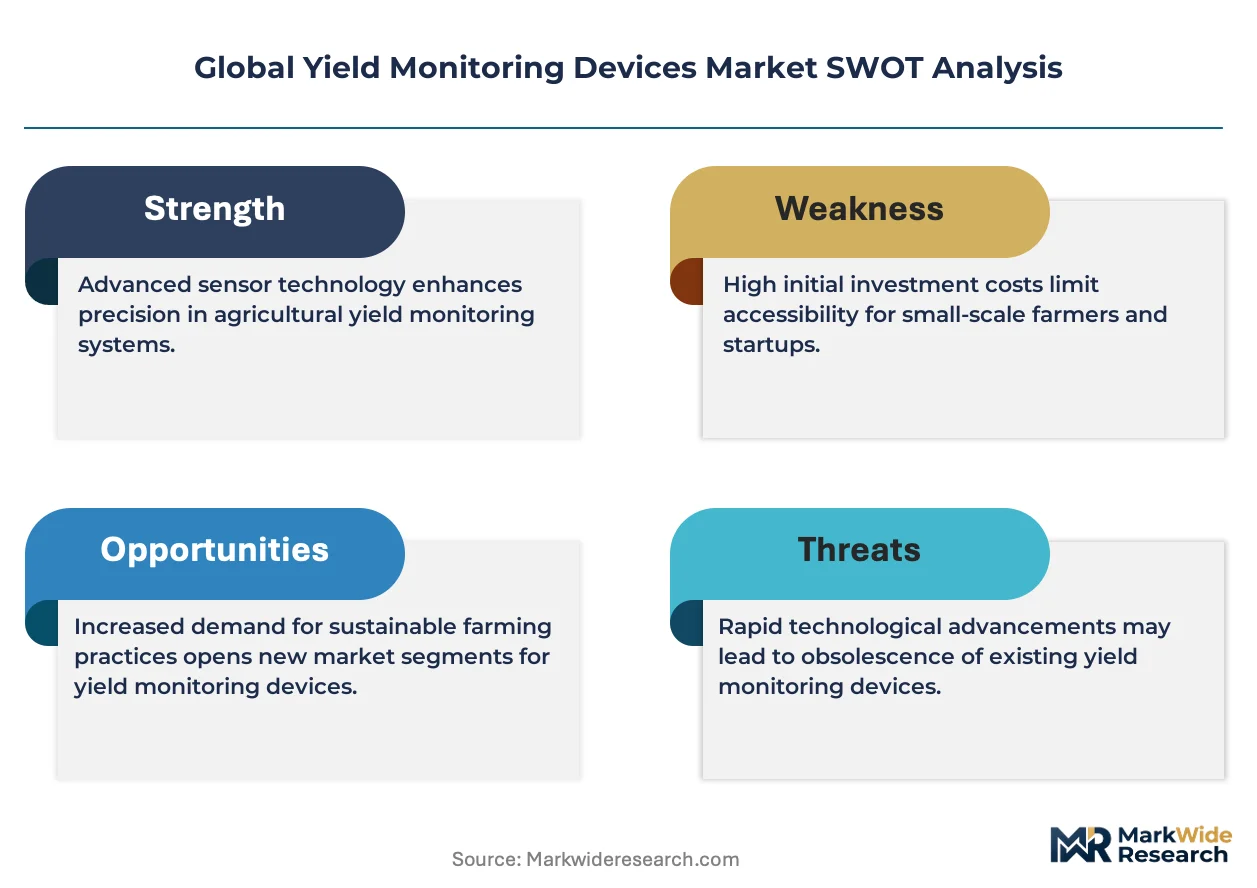
- High Initial Capital Outlay:The significant upfront investment for purchasing and installing yield monitoring hardware remains a primary barrier for small and medium-sized farms globally.
- Lack of Data Standardization:Incompatibility between data formats from different equipment manufacturers creates significant interoperability challenges, locking farmers into specific vendor ecosystems.
- Alternative Monitoring Technologies:The emergence of satellite imagery and drone-based surveying provides alternative, non-contact methods for yield estimation, presenting a substitution threat to on-combine hardware.
Strategic Opportunities
- Carbon Sequestration Verification:Integrating yield data with soil carbon measurements offers a new service opportunity, enabling farmers to participate in burgeoning agricultural carbon credit markets.
- Expansion into Emerging Markets:Agricultural economies in Southeast Asia, such as Vietnam and Indonesia, represent underpenetrated markets with modernizing farm sectors receptive to precision technologies.
- Predictive Analytics Integration:Combining real-time yield data with AI-driven weather forecasting and soil sensor information can create high-value predictive models for crop management and risk mitigation.
Industry Challenges
- Agronomic Data Science Skills Gap:A shortage of agronomists and farm managers trained in data analysis limits the ability of end-users to extract actionable insights from complex georeferenced yield maps.
- Legacy System Integration:Integrating modern yield monitoring systems with older farm equipment and disparate Farm Management Information Systems (FMIS) presents a significant technical and financial hurdle.
- Data Ownership and Privacy:Navigating complex and varied regional regulations, like the EU's GDPR, concerning farm data ownership, privacy, and cross-border data transfer complicates platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Yield Monitoring Devices Market |
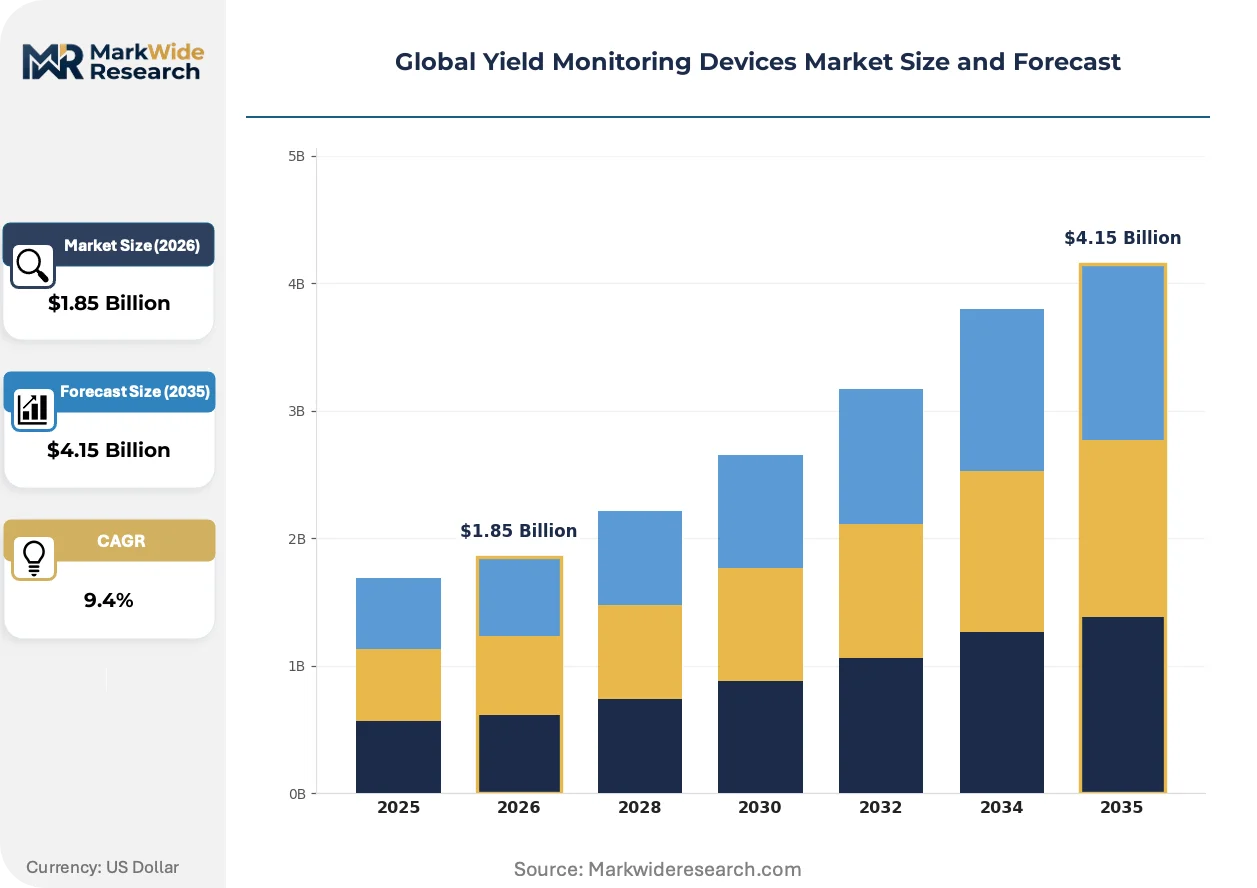
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain Yield Monitors, Forage Yield Monitors, Soil Moisture Sensors, Crop Scanners Technology: GPS-based Systems, Optical Sensors, Radar-based Devices, Ultrasonic Sensors Application: Precision Planting, Crop Yield Analysis, Field Mapping, Resource Management End User: Farm Operators, Agronomists, Agricultural Consultants, Research Institutions |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial N.V., Topcon Corporation, Raven Industries, Inc., AG Leader Technology, Prospera Technologies, CropX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Yield Monitoring Devices Market Strategic Shifts & Innovations
The market is pivoting from a focus on hardware accuracy to the value of integrated data analytics. This evolution is driven by the convergence of sensor technologies and regulatory demands for greater agricultural transparency, creating new service-based revenue streams.
Digital twin technology creates dynamic, virtual models of agricultural fields using real-time data. Large-scale farming enterprises are the primary adopters, seeking to optimize input application and forecast yields with greater precision. This advancement is virtualizing farm management, enabling scenario modeling for crop health and resource use before committing physical assets.
Data privacy mandates like the EU's General Data Protection Regulation (GDPR) govern how farm operational data is managed. This forces platform providers to implement robust consent management and data portability features within their software. The regulation most affects companies offering mixed-fleet data aggregation services, which must ensure compliance across multiple equipment brands.
Farm operators are shifting from one-time capital expenditures on hardware to recurring subscriptions for data analysis services. This model disrupts the traditional equipment dealership channel, which is now competing with software-as-a-service providers for farm management budgets. The subscription-based model is most prevalent in the United States and Western Europe where digital farming platforms are mature.
Global Yield Monitoring Devices Market Segmentation
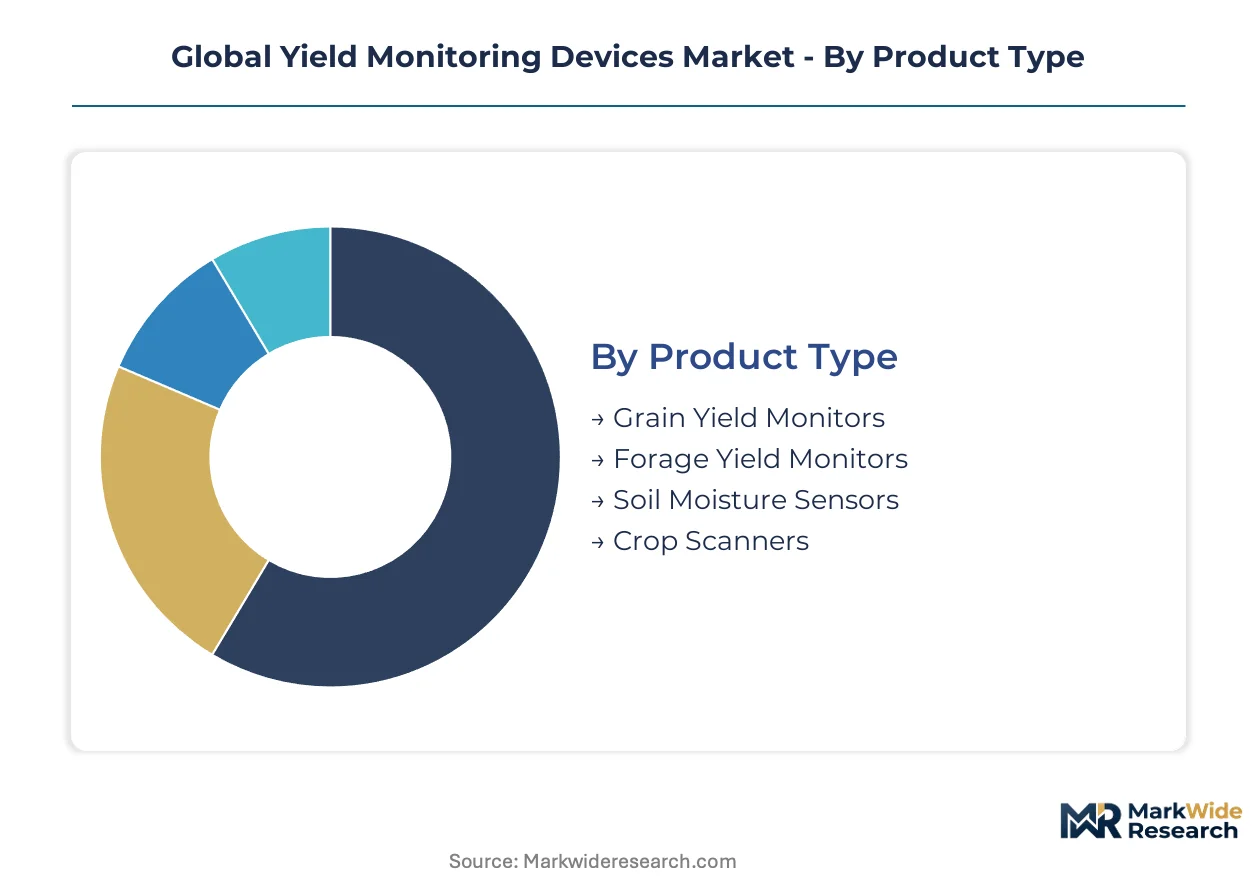
Market segmentation clarifies the distinct functionalities and user bases driving demand for yield monitoring devices. Understanding these categories helps stakeholders tailor solutions to specific agricultural requirements and technological preferences. This granular view highlights areas of concentrated growth and evolving user needs across the global agricultural landscape.
Product Type:
The use-case spectrum for yield monitoring devices ranges from granular crop measurement to broad resource assessment.
- Grain Yield Monitors:These integrated systems measure the mass flow of harvested grain, typically combining a grain flow sensor, a moisture sensor, and GPS technology. Demand from large-scale farm operators in the United States concentrates on these devices for optimizing harvesting efficiency across vast acreages.
- Forage Yield Monitors:Devices designed to estimate the biomass and quality of forage crops like hay or silage, often using optical or ultrasonic sensors. These monitors support livestock operations seeking to optimize feed management.
- Soil Moisture Sensors:Instruments that measure the volumetric water content in soil, providing critical data for irrigation scheduling and water resource management. Adoption is accelerating in Brazil, driven by mandates for sustainable water use in intensive crop production.
- Crop Scanners:Advanced sensors, often optical or hyperspectral, that assess crop health, nutrient status, and potential yield variations non-destructively. These tools support precision nutrient application strategies.
Established volume favors Grain Yield Monitors; emerging adoption favors Crop Scanners.
Technology:
Technology maturity dictates adoption rates and system capabilities across the market.
- GPS-based Systems:Global Positioning System technology provides georeferencing for yield data, mapping field variations and enabling precise input application. These foundational systems remain critical for field mapping applications across all major agricultural economies.
- Optical Sensors:These sensors use light wavelengths to detect crop characteristics like chlorophyll content, plant density, and stress levels, offering non-contact yield estimation. Specialized applications, such as forage quality assessment, are driving their expanding use in Western Europe.
- Radar-based Devices:Systems employing radar technology to measure parameters like crop height or biomass, often used in challenging environmental conditions where optical sensors may be less effective. Radar-based devices offer robust performance in adverse weather.
- Ultrasonic Sensors:These sensors emit sound waves to measure distances and detect objects, finding use in applications like plant height measurement or obstacle avoidance on agricultural machinery. Ultrasonic sensors provide reliable short-range detection.
Interoperability and data integration capabilities remain critical differentiators among these technological approaches.
Application:
Different customer types prioritize distinct applications, driving varied demand for yield monitoring functionalities.
- Crop Yield Analysis:The primary application involves interpreting georeferenced yield data to understand field variability, identify performance bottlenecks, and inform future planting decisions. This analysis is crucial for large agricultural enterprises aiming to maximize profitability per acre.
- Resource Management:This segment focuses on optimizing the use of inputs like water, fertilizer, and pesticides based on real-time and historical yield data. Demand for resource management capabilities represents the fastest-growing segment, propelled by global sustainability mandates.
- Precision Planting:Utilizing yield maps and other data to adjust planting rates and seed placement for optimal crop establishment and yield potential. Precision planting directly impacts initial input costs.
- Field Mapping:Generating detailed maps of agricultural fields that highlight variations in yield, soil type, and other agronomic factors. Field mapping provides the foundational layer for all precision agriculture practices.
The highest value creation stems from applications enabling proactive management decisions and cost optimization.
End User:
End-user volume directly influences the scale of data generation and the required analytical sophistication.
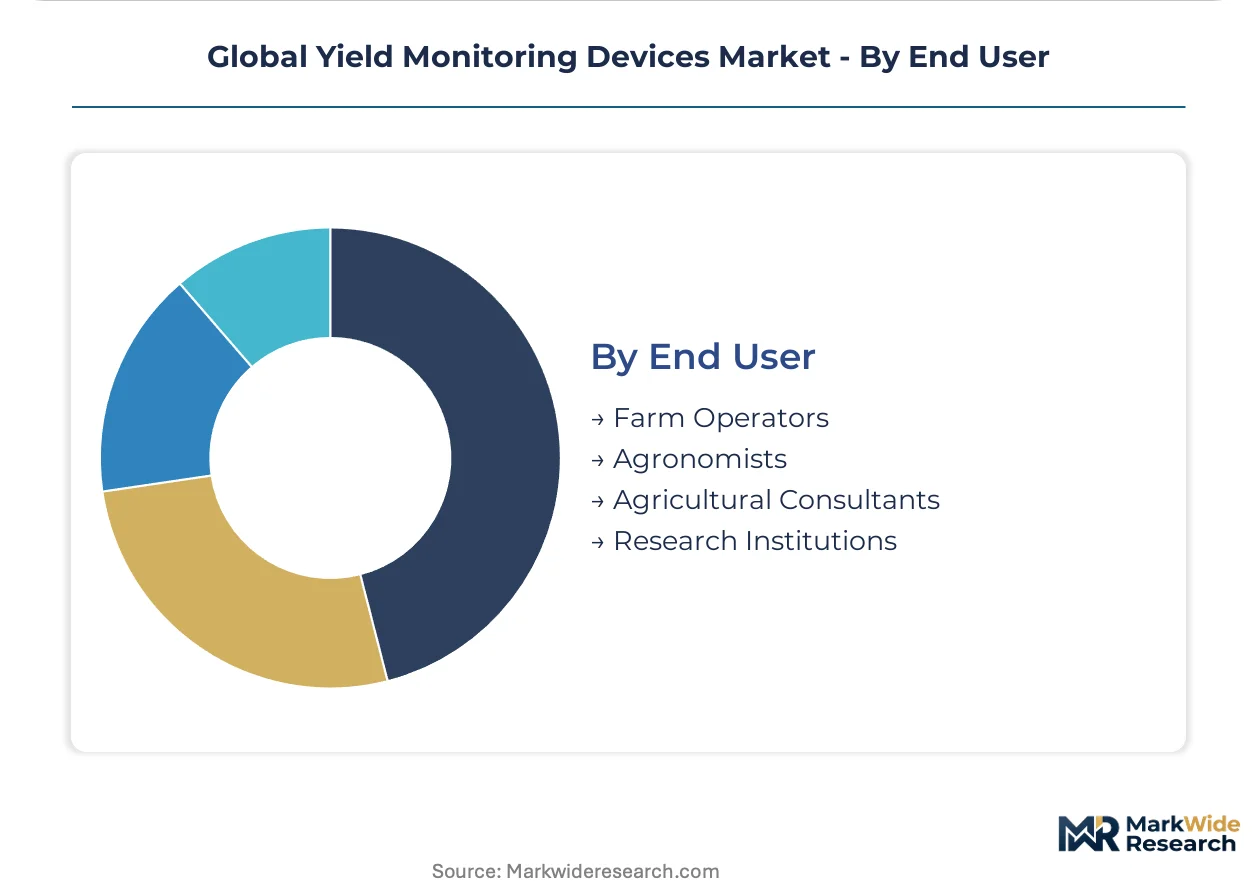
- Farm Operators:Individual farmers and large agricultural enterprises who directly use yield monitoring devices to inform daily operational decisions and long-term farm management strategies. Large-scale farm operators in the United States and Brazil represent a significant segment due to their extensive landholdings.
- Agronomists:Agricultural science professionals who advise farmers on crop production, soil management, and pest control, often utilizing yield data for tailored recommendations. Agronomists leverage detailed data to develop optimized crop plans.
- Agricultural Consultants:Independent advisors providing specialized expertise in precision agriculture technology implementation, data interpretation, and farm business planning. These consultants bridge the gap between complex technology and practical farm application for diverse clients.
- Research Institutions:Universities and government agricultural research bodies that use yield monitoring data for scientific studies, variety trials, and developing new farming techniques. Research institutions drive innovation in data-driven agriculture.
Effective data utilization is paramount for all end-user segments to maximize technology ROI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in established agricultural markets prioritize advanced data analytics, exhibiting lower price sensitivity. Conversely, emerging economies seek cost-effective solutions for initial adoption. This dynamic shapes regional demand and technology deployment strategies for yield monitoring devices.
United States
United States demand is driven by large-scale farm operators focused on precision planting and optimizing harvesting efficiency. USDA programs provide financial incentives for adopting precision agriculture technologies that improve sustainability. The Midwest agricultural belt, particularly states like Iowa, sees widespread adoption of grain yield monitors for optimizing vast corn and soybean acreages.
Brazil
Brazil's market expansion is propelled by mandates for sustainable water use in intensive crop production. ANVISA regulations for agricultural practices influence the adoption of yield monitoring devices. The Mato Grosso region leads in soil moisture sensor deployment to manage water resources for large-scale soybean and corn farms.
France
France experiences demand stemming from resource efficiency goals and the need for accurate forage quality assessment. The EU Green Deal's farm-to-fork strategy directly incentivizes technologies that reduce chemical inputs. The agricultural regions of Normandy and Brittany are expanding optical sensor use for precise forage yield and quality monitoring in livestock operations.
India
India's modernizing farm sectors and efforts to improve crop yield are creating nascent demand for yield monitoring devices. PLI schemes encourage local manufacturing and technology integration in agriculture. States like Punjab and Haryana show initial adoption for basic grain yield monitors to enhance efficiency in wheat and rice cultivation.
Global Yield Monitoring Devices Market Key Industry Players
Capability concentration sits with specialized technology providers, while scale advantage resides with established agricultural equipment manufacturers. The market structure is tiered, featuring a few dominant players alongside numerous niche software and sensor developers. Strategic archetypes include integrated hardware-software giants and agnostic data platform providers. Competitive moves involve expanding software service portfolios and forming strategic partnerships for data interoperability.
Integrated hardware-software giants, such as Deere & Company, exemplify a strategy of leveraging their extensive equipment networks to offer proprietary software services and data platforms, aiming for ecosystem lock-in. Trimble Inc. represents the agnostic GPS-based systems archetype, focusing on interoperability and broad compatibility across multiple equipment brands, appealing to diverse fleets. AGCO Corporation sits within the mixed-fleet operations segment, providing digital tools through its Fuse smart farming platform, emphasizing comprehensive solutions for varied agricultural machinery. These players define the competitive dynamics across hardware and data services.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Topcon Corporation |
| Raven Industries, Inc. |
| AG Leader Technology |
| Prospera Technologies |
| CropX |
| Others |
Cost & Logistics Intelligence
Component manufacturing concentration in East Asia influences the cost structure of yield monitoring devices, impacting downstream profitability for software-driven services. This upstream dependency shapes the value capture across the integrated hardware-software ecosystem.
Pricing Analysis
Recurring software subscription revenue for crop yield analysis drives lifetime value for yield monitoring device providers. The dominant pricing model transitions from one-time hardware sales to SaaS-tiered subscriptions. Price differentiation stems from brand premium and the level of integration with existing farm management information systems. Pricing softness results from alternative monitoring technologies, with small and medium-sized farms exhibiting the highest price sensitivity. Large agricultural enterprises, conversely, prioritize long-term value over initial cost.
Supply Chain Analysis
Extended payment terms for component suppliers underpin the capital intensity of yield monitoring device manufacturing. Geographic supply concentrates on specialized sensor and electronic components from China and advanced software development in the United States. Key dependencies include GPS modules, optical sensors, and microcontrollers. Single-source vulnerability for specialized sensor technology represents a structural risk, while distribution runs through established agricultural equipment dealership networks and direct-to-farm SaaS platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yield monitoring devices market presents a significant fragmentation opportunity driven by diverse regional sustainability mandates. This creates distinct niches for specialized solutions addressing specific agricultural requirements.
For Market Incumbents: Pre-empt the erosion of hardware margins by rapidly expanding proprietary software service offerings. Incumbents should invest in AI-driven predictive analytics capabilities to counter the threat from alternative monitoring technologies. Develop open platforms that integrate data from diverse equipment brands, leveraging existing equipment networks for broader ecosystem control. This strategy minimizes lock-in risks for farmers while securing long-term service revenue.
For New Entrants and Emerging Players: Underpenetrated markets in Southeast Asia, particularly Vietnam and Indonesia, represent a significant entry point for cost-effective yield monitoring solutions. Focus on developing specialized optical sensors for specific crop types like forage, addressing unmet regional needs. A direct-to-farmer SaaS model, coupled with strategic partnerships with local agricultural cooperatives, offers a viable go-to-market angle. This approach circumvents established dealership channels and reduces initial capital requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized sensor developers and data analytics platforms, offering attractive acquisition targets. Long-term viability hinges on companies capable of navigating diverse regional data governance rules and integrating multi-source data. Target agnostic data platform providers with strong AI capabilities for predictive crop management. The signal to watch is the increasing adoption rate of carbon credit verification services in agriculture, indicating scalable new revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Software-as-a-Service Portfolio | Enhances recurring revenue streams and strengthens customer lock-in for hardware manufacturers. |
| Develop Open Data Interoperability Standards | Reduces farmer lock-in, fostering broader adoption and trust across diverse equipment fleets. |
| Invest in AI-driven Predictive Analytics | Improves crop management decisions and risk mitigation through advanced data interpretation. |
| Form Partnerships with Agronomic Consultants | Bridges the agronomic data science skills gap for end-users, facilitating technology adoption. |
| Target Emerging Agricultural Economies | Captures initial market share in regions like Southeast Asia with modernizing farm sectors. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform this analysis. Primary interviews included farm operators, agronomists, agricultural consultants, and equipment manufacturers, validated against extensive secondary research. Secondary sources comprised USDA reports, EU Green Deal documents, company annual filings, and agricultural statistics databases. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and market sizing.
Quantitative models were calibrated through an iterative process integrating historical market performance with future projections across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional agricultural policy. Compound Annual Growth Rates were derived from regression analysis of historical trends and projected market drivers. Key forecast inputs included global farm size consolidation trends and the decreasing cost of sensor technology.
Practitioners should monitor shifts in agricultural policy and rapid technological disruption for early signals impacting market trajectory. Forecasts reflect documented assumptions regarding market dynamics and adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Bean Harvester Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Greenhouse Kit Market