
 Asia-Pacific Laser Hair Removal Market | 2026-2036
Asia-Pacific Laser Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Laser Hair Removal Market Analytics
Device servicing revenue is fragmenting between manufacturer-certified technicians and third-party maintenance networks across the Asia-Pacific region. Alma Lasers Ltd leverages its direct service infrastructure to sustain recurring revenue streams in South Korea and Australia. Candela Medical competes through specialized training programs that anchor clinician loyalty across Southeast Asian markets.
Laser hair removal employs selective photothermolysis, wherein melanin in hair follicles absorbs pulsed laser energy at wavelengths between 755 nm and 1064 nm to disable regrowth without damaging surrounding tissue. Diode laser systems dominate installed bases across clinics and salons due to efficacy across broader skin type ranges, while Nd:YAG technology leads growth in professional settings serving darker skin phototypes prevalent across South and Southeast Asia. Cooling technology segments command premium positioning as thermal injury risk management becomes a clinical differentiator.
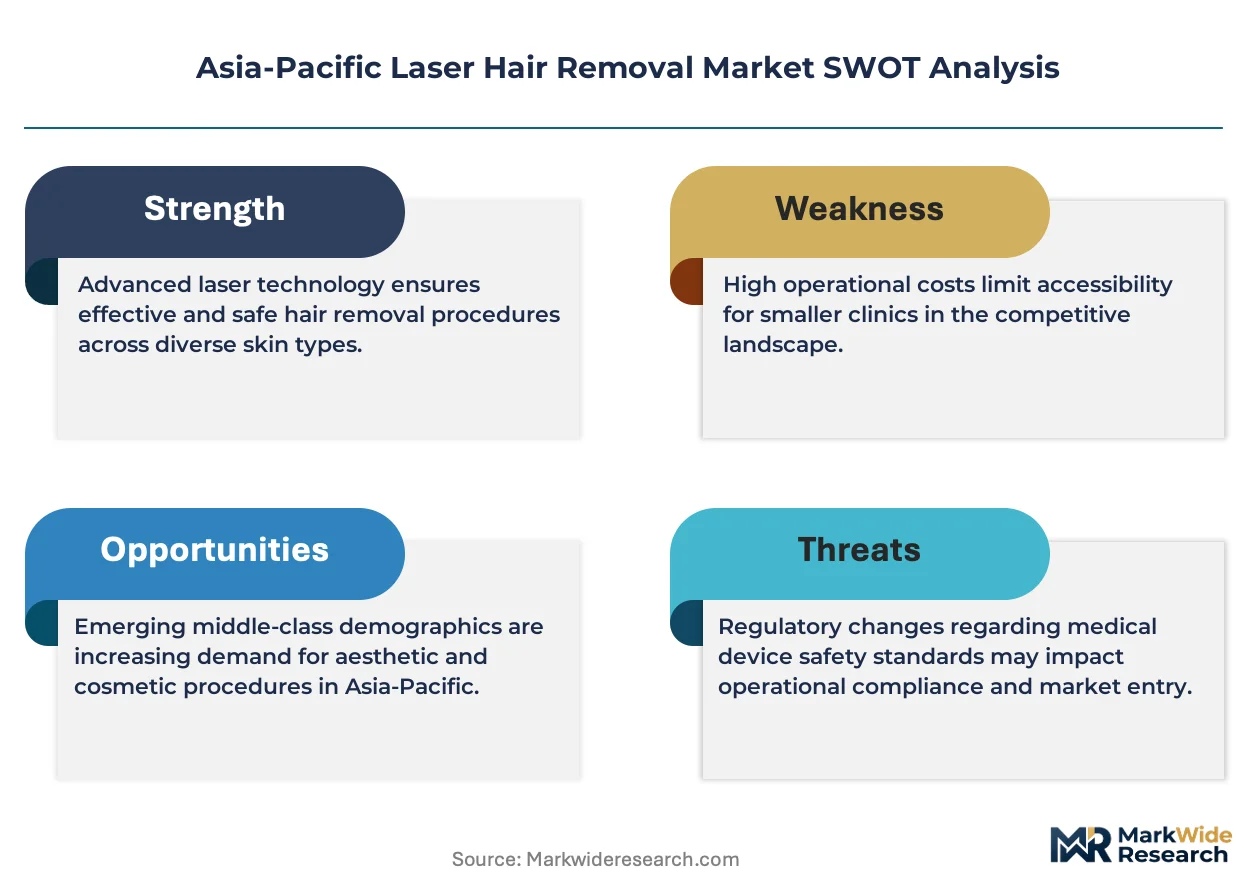
Japan's Ministry of Economy, Trade and Industry (METI) enforces electrical safety standards for aesthetic devices, while Australia's Therapeutic Goods Administration (TGA) classifies laser hair removal equipment as active medical devices requiring conformity assessment. China's National Medical Products Administration (NMPA) mandates clinical trial data for new laser registrations, extending approval timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement classifications for aesthetic procedures as healthcare regulators across the region reassess cosmetic versus therapeutic indications.
Market Dynamics
China's NMPA tightened device registration rules are forcing domestic manufacturers toward cooling-technology upgrades while South Korean and Japanese aesthetic clinics scale diode laser installations. This regulatory compression is reshaping competitive positioning across the region's installed base.
Growth Catalysts
- Rising disposable incomes:Urban professionals in Shanghai and Beijing drive demand for medical aesthetics chain expansions.
- Diode laser efficacy:Broader skin type compatibility accelerates clinic adoption across Southeast Asian markets.
- MFDS device standards:South Korea's regulatory clarity streamlines import pathways for advanced cooling systems.
Market Restraints
- Extended NMPA approval timelines:Clinical trial mandates for foreign manufacturers delay market entry by 18-24 months.
- Nd:YAG supply concentration:Professional-grade laser component sourcing clusters in German and Japanese suppliers.
- IPL substitution threat:Intense pulsed light devices capture price-sensitive salon segments in tier-2 Chinese cities.
Strategic Opportunities
- Underpenetrated Vietnam and Philippines:Medical tourism infrastructure gaps create first-mover openings for premium clinic chains.
- AI-assisted treatment planning:Machine vision integration with diode systems enables personalized fluence calibration.
- Australia's TGA active medical device classification:Conformity assessment requirements favor established cooling-technology suppliers with quality management systems.
Industry Challenges
- Certified technician scarcity:Manufacturer-certified service networks compete with third-party maintenance providers for trained personnel across Australia and South Korea.
- Legacy cooling system integration:Thermal injury risk management upgrades require substantial retrofit investment in installed base equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Laser Hair Removal Market |
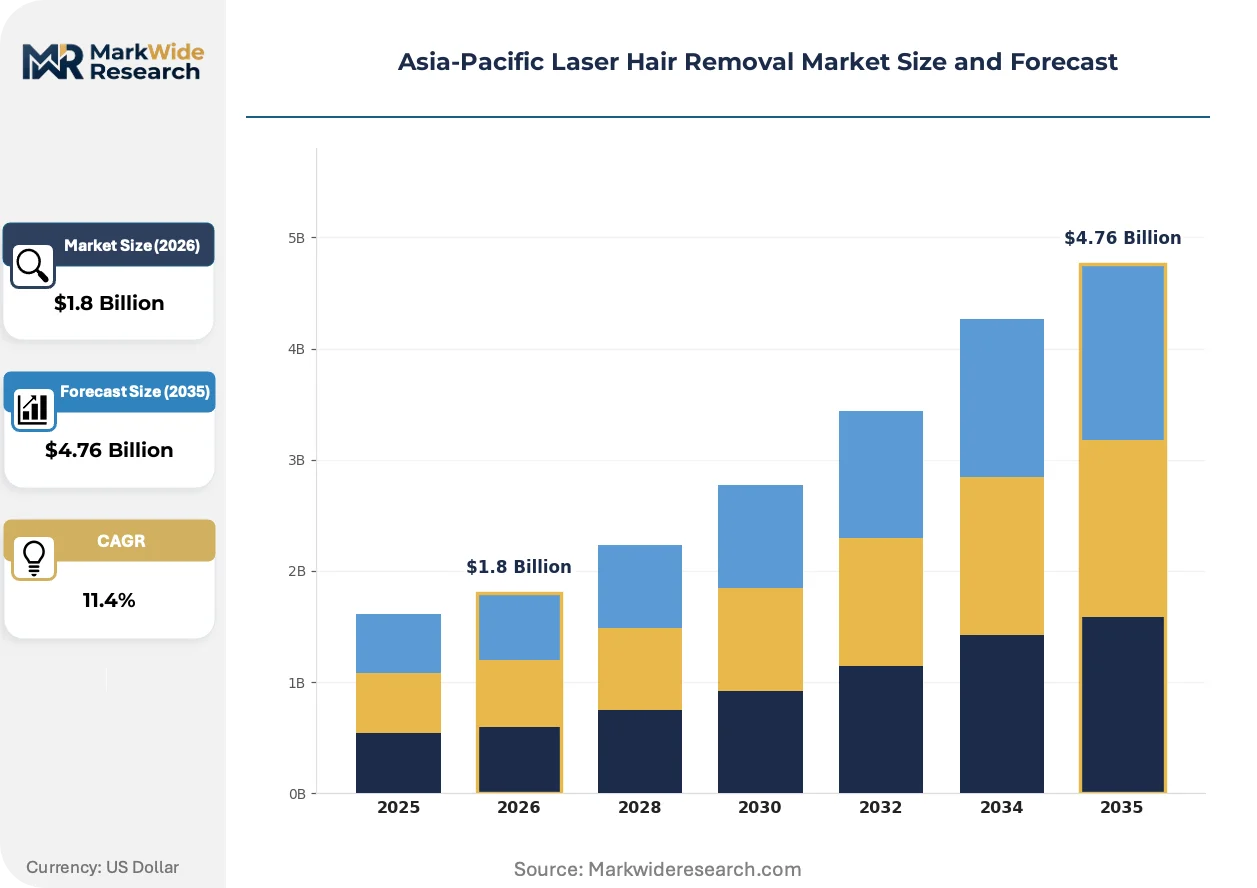
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Laser, Alexandrite Laser, Nd:YAG Laser, IPL End User: Clinics, Salons, Home Users, Hospitals Technology: Cooling Technology, Pulse Technology, Fractional Laser, Continuous Wave Application: Facial Hair Removal, Body Hair Removal, Unwanted Hair Removal, Sensitive Area Treatment |
| Companies Covered | Cynosure, Alma Lasers Ltd, Bausch Health Companies Inc, Cutera Inc, Candela Medical, Lumenis, Lutronic Corporation, Sciton Inc, Venus Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Laser Hair Removal Market Evolving Landscape
Technology convergence and regulatory differentiation are compressing product lifecycles across the Asia-Pacific laser hair removal landscape. Clinicians now prioritize thermal safety systems alongside treatment efficacy in procurement decisions.
Diode-Nd:YAG combination platforms are hybridizing treatment protocols across professional settings. Aesthetic chains in Bangkok and Kuala Lumpur deploy these systems to serve diverse skin phototypes within single patient populations. The technology is hybridizing competitive positioning by collapsing the need for separate device investments.
Japan's METI electrical safety standards now require updated isolation transformer specifications for imported aesthetic devices. Domestic distributors must recertify existing inventory, compressing margins on legacy stock. South Korean manufacturers with JIS-compliant production lines capture accelerated replacement demand.
After-sales service unbundling is fragmenting revenue models across the region. Clinics in Sydney and Melbourne now separately negotiate maintenance contracts from device procurement, displacing bundled warranty structures. This pattern concentrates in markets where TGA registration creates switching costs between service providers.
Asia-Pacific Laser Hair Removal Market Segmentation
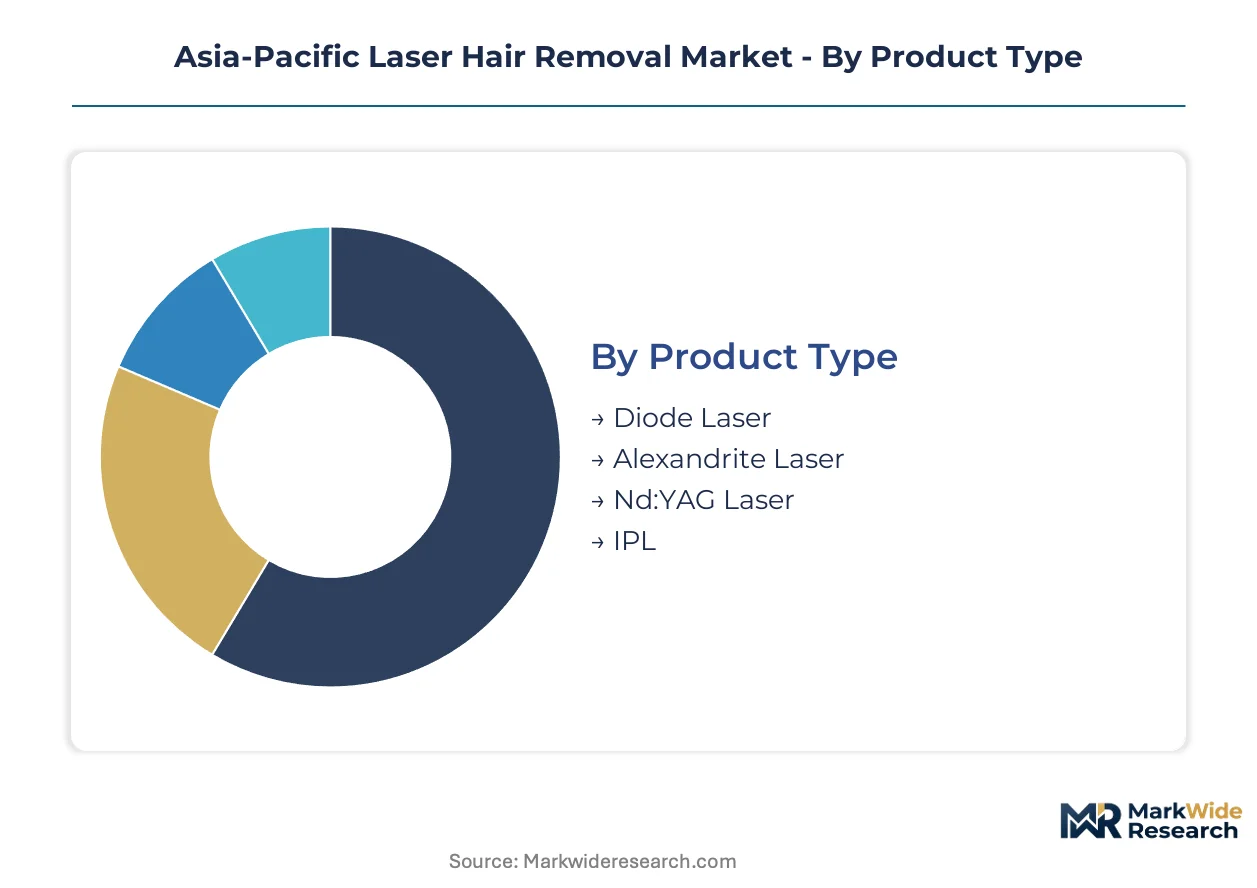
Segmentation in the Asia-Pacific laser hair removal market reveals how technology choices, end-user economics, and application-specific efficacy requirements fragment procurement decisions across the region's diverse regulatory and clinical environments.
Product Type:
Cost tier stratification across laser platforms determines clinic investment cycles and maintenance economics throughout metropolitan centers in China, Japan, and South Korea.
- Diode Laser:Semiconductor-based systems operating at 800-810 nm wavelengths deliver consistent melanin absorption across Fitzpatrick skin types I-V. Demand concentrates in Shanghai and Seoul aesthetic chains where high patient throughput justifies capital intensity and disposable incomes support premium pricing.
- Nd:YAG Laser:Long-pulse 1064 nm technology penetrates deeper dermal layers with reduced epidermal melanin competition. Bangkok and Kuala Lumpur clinics serving South and Southeast Asian skin phototypes IV-VI rotate these systems into installed bases as patient safety protocols tighten under national medical device regulators.
- Alexandrite Laser:755 nm wavelength systems target lighter skin types with rapid pulse repetition rates.
- IPL:Broadband light sources compete on acquisition cost in price-sensitive salon segments across tier-2 Chinese cities.
Diode systems hold installed capacity across the region's premium clinic networks. Nd:YAG configurations are rotating up the share rankings as darker skin phototype coverage becomes a competitive necessity.
End User:
Application setting determines device sophistication requirements, with regulatory classification intensity scaling from consumer self-treatment through hospital-grade therapeutic interventions.
- Clinics:Medical aesthetics chains in Beijing and Tokyo deploy multi-wavelength platforms with integrated cooling systems under physician supervision. Australia's TGA active medical device classification mandates conformity assessment documentation that favors established suppliers with quality management certifications.
- Salons:Beauty service providers in Jakarta and Manila operate IPL and entry-level diode systems without clinical oversight. NMPA registration requirements for laser classifications push these operators toward technically simpler intense pulsed light alternatives that fall outside medical device jurisdiction in several national frameworks.
- Home Users:Consumer-grade devices with reduced fluence outputs target discretionary spending among urban professionals.
- Hospitals:Dermatology departments integrate laser hair removal into broader therapeutic protocols for hirsutism and endocrine-related conditions.
Clinics command revenue concentration. Home user segments are climbing the fastest as consumer device manufacturers penetrate e-commerce distribution channels.
Technology:
Cooling and pulse modulation architectures differentiate competitive positioning as thermal injury risk management becomes a procurement priority across the region's regulatory environments.
- Cooling Technology:Contact cooling, cryogen spray, and air-cooled systems manage epidermal temperature during laser delivery. China's NMPA tightened device registration rules are forcing domestic manufacturers toward thermal management upgrades that previously differentiated premium imported platforms.
- Pulse Technology:Variable pulse duration and fluence calibration enable personalized treatment protocols. South Korea's MFDS device standards streamline import pathways for advanced pulse-modulation systems that anchor clinician loyalty through software-defined treatment libraries.
- Fractional Laser:Microbeam array configurations target specific application niches with reduced thermal diffusion.
- Continuous Wave:Sustained emission modes serve specialized industrial and research applications with limited aesthetic deployment.
Cooling technology holds installed capacity. Pulse technology platforms are expanding most quickly as AI-assisted treatment planning integrates with software-defined fluence calibration.
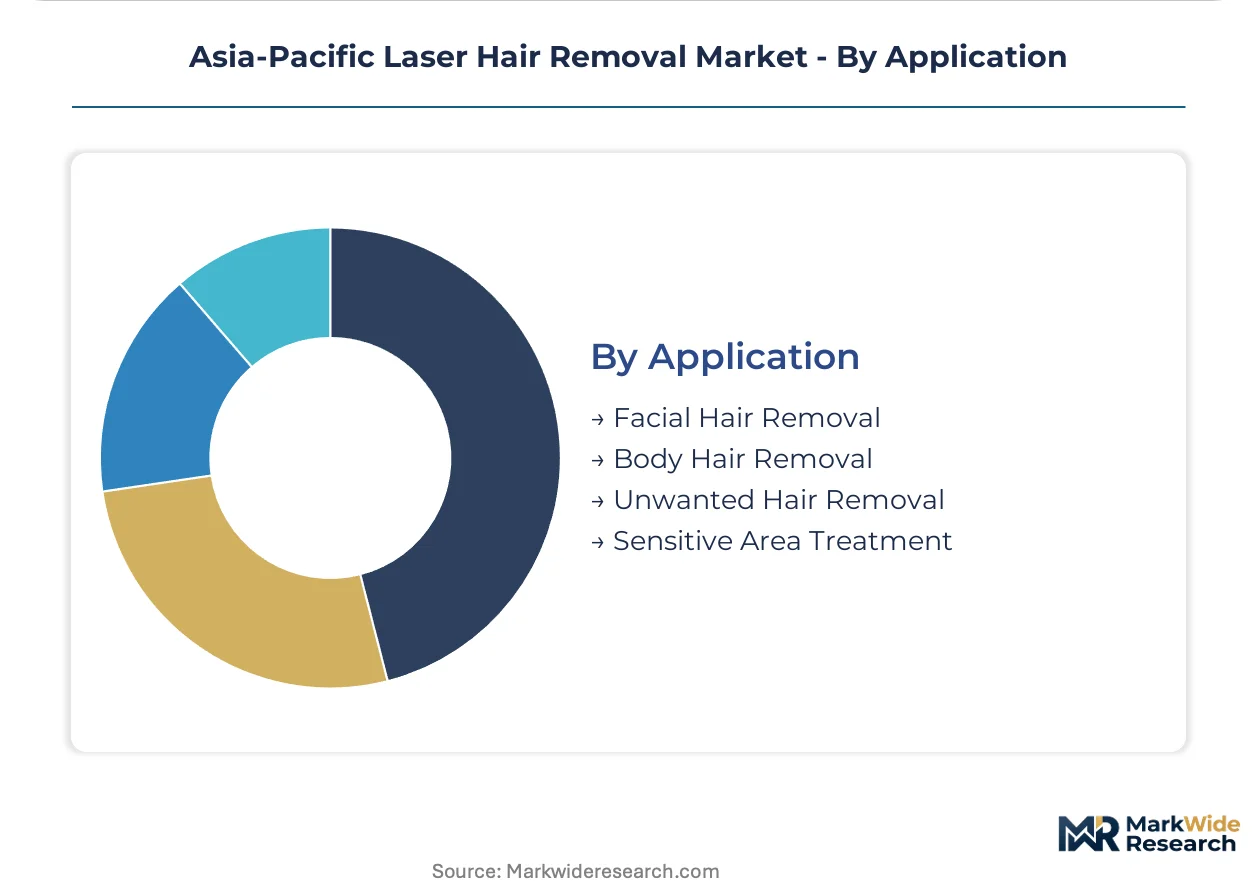
Application:
Body area specificity drives wavelength and spot size selection, with facial applications demanding precision optics and sensitive zones requiring enhanced thermal protection protocols.
- Facial Hair Removal:Precision targeting of coarse terminal hair in beard and mustache regions requires small spot sizes and epidermal cooling. Clinics in Osaka and Singapore report highest procedure frequency in this category as male grooming aesthetics normalize among urban professionals.
- Body Hair Removal:Large-area treatments on legs, arms, and back utilize high-repetition-rate diode systems with automated scanning handpieces. Australian clinic chains deploy these configurations for efficiency in high-volume metropolitan locations.
- Unwanted Hair Removal:General category encompassing elective depilation across all body areas without medical indication.
- Sensitive Area Treatment:Bikini line and underarm applications require enhanced cooling protocols and conservative fluence settings.
Body hair removal holds installed capacity. Facial applications are gaining share fastest as male patient demographics expand across Northeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments procurement patterns across the Asia-Pacific region. Tier-2 Chinese cities gravitate toward IPL alternatives while premium diode systems dominate Seoul and Tokyo clinic networks. This elasticity gradient reshapes manufacturer go-to-market strategies.
China
Shanghai and Beijing medical aesthetics chains deploy multi-wavelength platforms with integrated cooling systems. NMPA tightened device registration rules now mandate clinical trial data for new laser registrations, extending approval timelines for foreign manufacturers by 18-24 months. Domestic manufacturers in Guangdong and Jiangsu provinces accelerate cooling-technology upgrades to meet these standards.
Japan
Osaka clinics report highest procedure frequency in facial hair removal as male grooming aesthetics normalize among urban professionals. METI enforces updated electrical safety standards requiring isolation transformer specifications for imported aesthetic devices. Tokyo-based aesthetic chains recertify existing inventory, compressing margins on legacy stock while accelerating replacement demand.
South Korea
Seoul aesthetic clinics scale diode laser installations as disposable incomes rise among urban professionals. MFDS device standards streamline import pathways for advanced cooling systems and pulse-modulation platforms. Busan-Ulsan medical tourism corridors attract regional patients seeking premium hair removal protocols under physician supervision.
Australia
Sydney and Melbourne clinics separately negotiate maintenance contracts from device procurement, displacing bundled warranty structures. TGA classification of laser hair removal equipment as active medical devices mandates conformity assessment documentation. Queensland and Western Australia clinic chains deploy high-repetition-rate diode systems for efficiency in high-volume metropolitan locations.
Vietnam
Ho Chi Minh City salon operators purchase IPL systems that fall outside medical device jurisdiction in current national frameworks. Medical tourism infrastructure gaps create first-mover openings for premium clinic chains targeting regional patients. Domestic distributors in Hanoi establish service networks for imported diode platforms serving expatriate and affluent local demographics.
Asia-Pacific Laser Hair Removal Market Competitive Landscape
Full-stack device manufacturers and specialized aesthetic technology developers split the market into distinct capability tiers. The vendor base concentrates around firms with integrated cooling-system expertise and established quality management certifications. Two strategic archetypes dominate: multinational platform suppliers with direct service infrastructure, and regional specialists leveraging regulatory compliance advantages. Competitive moves center on M&A for technology portfolio expansion and strategic partnerships for distribution reach in underpenetrated Southeast Asian markets.
Within the multinational tier, Alma Lasers Ltd and Candela Medical exemplify contrasting service-model approaches. Alma Lasers Ltd anchors direct service infrastructure across South Korea and Australia to sustain recurring revenue streams. Candela Medical occupies a position emphasizing specialized training programs that secure clinician loyalty across Southeast Asian markets. Cynosure represents the scale-driven archetype among US-based aesthetic device manufacturers with broad wavelength platform portfolios. These three firms illustrate how geographic service density and regulatory navigation capabilities differentiate positioning in NMPA and TGA jurisdictions.
| Leading Market Players |
|---|
| Cynosure |
| Alma Lasers Ltd |
| Bausch Health Companies Inc |
| Cutera Inc |
| Candela Medical |
| Lumenis |
| Lutronic Corporation |
| Sciton Inc |
| Venus Group |
| Others |
Value Network & Pricing Analysis
German and Japanese laser component suppliers anchor upstream capacity for Nd:YAG resonator crystals and diode pump arrays, concentrating margin capture in the professional-grade device tier while downstream clinics in Seoul and Sydney compete on service bundling.
Pricing Analysis
After-sales service contracts now generate lifetime value exceeding original equipment sales across Australia's TGA-registered installed base. Three-tier pricing structure across premium, standard, and economy levels separates manufacturer-certified maintenance from third-party service networks and bare-bones warranty coverage. Price differentiation rests on cooling-technology certification grade and geographic proximity to authorized technician hubs. Cost compression in the salon-tier IPL segment is intensifying because NMPA registration exemptions for non-laser devices attract price-sensitive operators in tier-2 Chinese cities. Home user segments exhibit highest price sensitivity; premium clinic chains in Tokyo and Singapore demonstrate lowest elasticity.
Supply Chain Analysis
Upstre am feedstock for solid-state laser systems draws from optical-grade yttrium aluminum garnet crystal growers in Japan, semiconductor foundries in Taiwan and South Korea, and precision optics polishers in Germany. Raw material dependencies include rare-earth dopants for Nd:YAG rods, gallium arsenide substrates for diode arrays, and sapphire windows for beam delivery systems. Single-source vulnerability concentrates in high-purity yttrium oxide supply chains subject to export licensing protocols. Distribution runs through manufacturer-direct sales teams serving hospital-grade accounts, regional distributors covering salon-tier volume, and e-commerce platforms penetrating consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from regulatory compression cycles as NMPA approval timelines normalize and clinic capital expenditure resumes across metropolitan China.
For Market Incumbents: Insulate installed base revenue by deepening direct service infrastructure in South Korea and Australia where TGA and MFDS registrations create switching costs. Accelerate cooling-technology certification investments to defend against domestic Chinese manufacturers upgrading thermal management capabilities. Capture clinician loyalty through specialized training programs that anchor multi-wavelength platform adoption.
For New Entrants and Emerging Players: Build out white-space presence in Vietnam and Philippines where medical tourism infrastructure gaps and regulatory ambiguity around laser classifications create first-mover openings. Target Ho Chi Minh City salon operators with IPL alternatives that circumvent NMPA-equivalent registration requirements. Pursue partnership-based distribution with established regional service networks rather than greenfield direct sales investment.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with JIS-compliant production lines and established quality management certifications for METI and TGA jurisdictions. Long-term viability favors platforms with integrated AI-assisted treatment planning software and hybrid diode-Nd:YAG configurations serving diverse skin phototypes. Monitor NMPA approval velocity for foreign manufacturers as the primary inflection signal for market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cooling-Technology Certification Investment | Domestic Chinese manufacturers upgrade thermal management to meet NMPA tightened registration standards. |
| AI-Assisted Treatment Planning Integration | Machine vision calibration personalizes fluence settings across Fitzpatrick skin types I-VI in Bangkok clinics. |
| Direct Service Infrastructure Expansion | Manufacturer-certified technician networks in Sydney and Melbourne displace bundled warranty structures. |
| Hybrid Platform Development | Diode-Nd:YAG combinations collapse separate device investments for diverse patient populations in Kuala Lumpur. |
| Medical Tourism Corridor Partnership | Busan-Ulsan clinic chains attract regional patients seeking physician-supervised hair removal protocols. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aesthetic clinic medical directors, biomedical equipment procurement managers at hospital dermatology departments, laser device service technicians, and regulatory affairs specialists navigating NMPA and TGA pathways. Secondary validation incorporated MFDS device registration databases, METI electrical safety standard filings, Australian TGA conformity assessment documentation, and customs import records for laser aesthetic equipment. Bottom-up clinic census data triangulated against top-down manufacturer shipment estimates.
Calibration against historical NMPA approval timelines and installed base replacement cycles anchored volume projections across the analysis window. Segmentation dimensions modeled include laser platform type, cooling technology architecture, end-user regulatory classification intensity, and metropolitan versus tier-2 city demand patterns. CAGRs were derived from equipment procurement pipeline visibility and capital expenditure surveys among medical aesthetics chains. Industry-specific inputs incorporated melanin absorption efficacy data across skin phototype distributions and thermal injury incident rates by cooling system configuration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic Chinese manufacturers with state-backed cooling-technology R&D would shift outcomes beyond modeled ranges. Regulatory acceleration in Vietnam or Philippines could compress premium clinic entry timelines. Quarterly review of NMPA registration approval velocity and METI electrical safety standard revision schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Agitator Bead Mill Market
Others
Banknote Printing Machine Market
Others
Europe Astrology Market
Others
Badminton Apparel Market
Others
Human Enhancement Technology Market
Others
Asia-Pacific Telecom Transformers Market
Others
Telecom Transformers Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Smart Badge Market
Others
Propanil Market
Others
Cashew Kernel Market
Others
Europe Flow Battery Market
Others
Global Alpha Cypermethrin Market
Others
Connected Living Room Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Water and Waste Water Treatment Chemicals Market