
 Microbrewery Equipment Market | 2026-2036
Microbrewery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
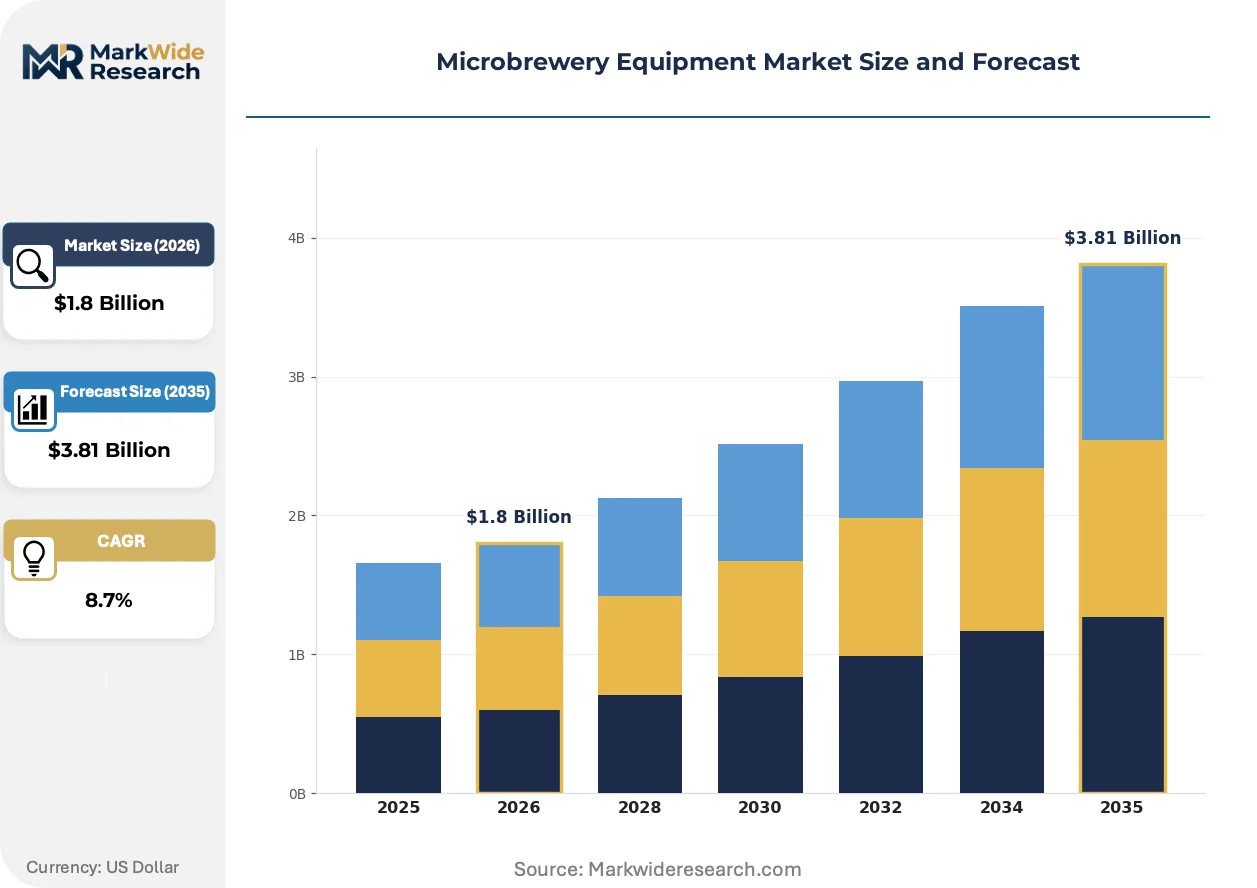
Microbrewery Equipment Market Outlook
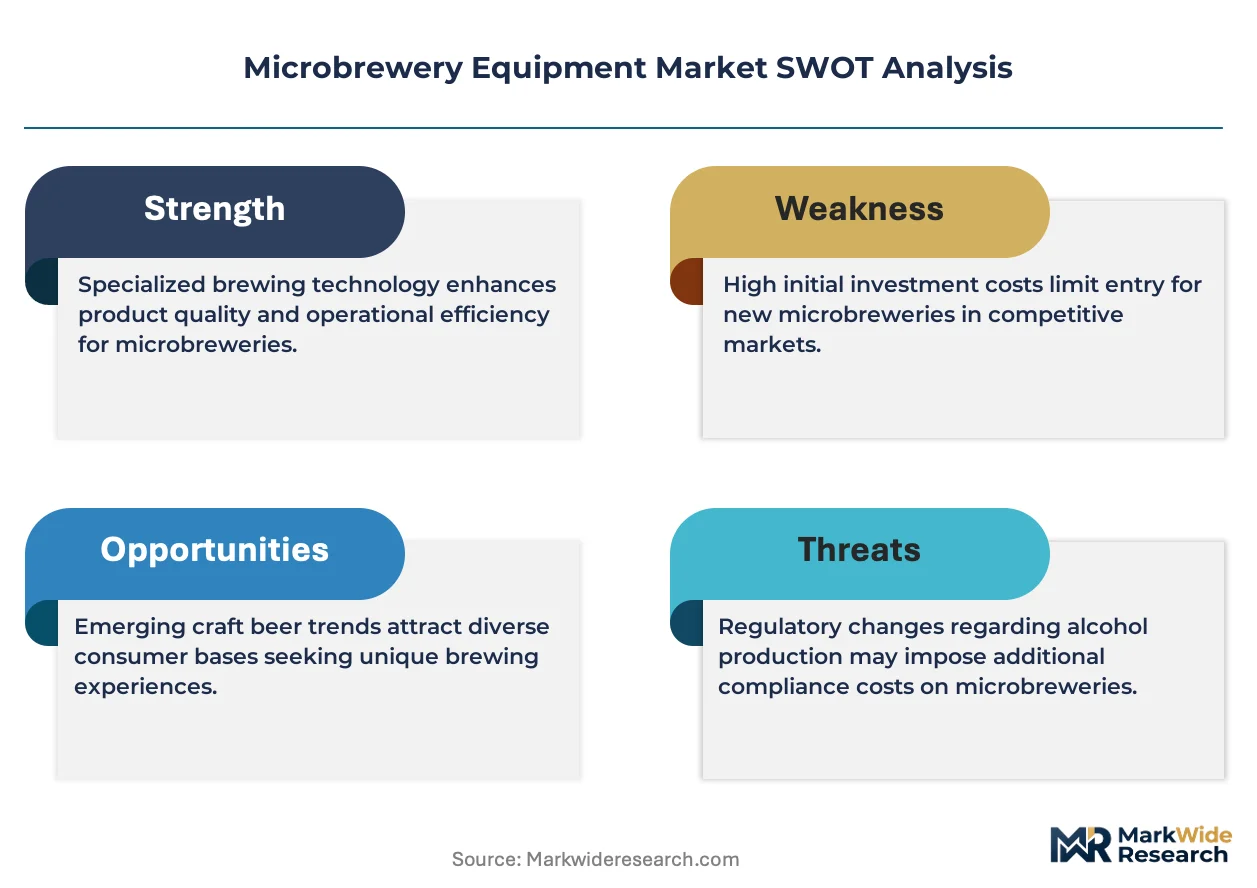
Multi-source procurement for stainless steel fermenter assemblies is realigning how mid-sized breweries manage capital expenditure and lead times. Alfa Laval leverages its heat-exchange expertise to dominate brewhouse utility skids across Nordic markets. Paul Mueller Company sustains its position through captive fabrication of custom tanks at its Springfield, Missouri facility. Ss Brewtech competes aggressively on modularity, offering turnkey systems that reduce installation complexity for new market entrants.
Microbrewery equipment encompasses vessels, heat-transfer apparatus, and control systems engineered to batch-produce beer at scales below industrial lager thresholds, typically employing 304 or 316L stainless steel with sanitary welded seams rated for CIP protocols. Fermenters command the largest share of replacement demand as breweries expand capacity without greenfield construction. Electric heating technology is displacing direct-fire configurations in urban brewpubs where municipal fire codes restrict open-flame operations, while steam heating retains preference among production breweries seeking thermal consistency across larger kettle volumes.
Regulatory oversight from the FDA's Food Safety Modernization Act, the EU's Machinery Directive with CE marking requirements, and Germany's WHG water hazard classification collectively shape equipment design, material certification, and market access protocols for vessel manufacturers. The EPA's effluent guidelines for brewery wastewater further constrain equipment specification in American installations. Stakeholders must monitor evolving energy labeling mandates and water reuse standards as municipalities tighten environmental compliance thresholds for food-grade production facilities.
Market Dynamics
Electric heating systems are displacing direct-fire configurations across urban brewpubs as municipal fire codes tighten and EU Ecodesign energy efficiency mandates accelerate equipment replacement cycles. This technology transition concentrates procurement power among vessel manufacturers capable of integrating heat-exchange skids with automated control architectures.
Growth Catalysts
- EU Ecodesign regulations:Tightening energy efficiency standards are mandating heat-recovery systems and electric kettle configurations, forcing equipment upgrades across Bavaria's craft beer corridor and Nordic brewpub clusters.
- Stainless steel supply localization:Mid-sized breweries are diversifying fermenter procurement across multiple fabrication sources, reducing lead time risk and enabling faster capacity scaling without greenfield construction.
- Urban brewpub zoning liberalization:Municipalities in Portland, Seattle, and Denver are relaxing occupancy restrictions on production facilities, stimulating demand for compact, electric-heated brewhouse systems.
Market Restraints
- Nickel price volatility:316L stainless steel input costs fluctuate with Indonesian and Philippine ore export policies, compressing margin predictability for custom tank fabricators.
- German WHG certification backlog:Water hazard classification testing for jacketed vessels creates six-to-nine-month approval delays, freezing capital deployment for export-bound equipment.
- Steam infrastructure dependency:Production breweries seeking thermal consistency remain tethered to legacy boiler systems, limiting electric conversion in facilities without grid capacity upgrades.
Strategic Opportunities
- India craft beer liberalization:State-level excise reforms in Karnataka and Maharashtra are licensing microbreweries for the first time, creating first-mover advantage for turnkey system suppliers.
- Water reuse mandate convergence:EPA effluent guidelines and German municipal wastewater standards are converging on closed-loop CIP recovery specifications, favoring equipment with integrated membrane filtration.
- Modular skid standardization:Containerized brewhouse units are enabling rapid deployment in secondary cities lacking specialized installation labor, compressing project timelines from months to weeks.
Industry Challenges
- Sanitary welding certification scarcity:ASME Section IX and orbital TIG proficiency gaps constrain production capacity at custom fabricators, extending order backlogs.
- Legacy control system integration:Breweries with existing SCADA architectures face protocol incompatibility when upgrading to IoT-enabled fermentation monitoring platforms.
- CE marking documentation burden:EU Machinery Directive technical file requirements impose substantial compliance overhead on small-batch equipment exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbrewery Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brew Kettles, Fermenters, Mash Tuns, Chillers Technology: Steam Heating, Direct Fire, Electric Heating, Indirect Heating Application: Ales, Lagers, Stouts, Specialty Beers End User: Independent Breweries, Brewpubs, Restaurants, Homebrewers |
| Companies Covered | Alfa Laval, DME Brewing Solutions, HG Machinery, Paul Mueller Company, Ss Brewtech, GEA Group, JV Northwest, LEHUI, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbrewery Equipment Market Strategic Shifts
Brewhouse automation architectures are converging with food-grade IoT platforms, enabling real-time fermentation monitoring that was previously restricted to industrial lager operations. This convergence is compressing the capability gap between craft and mass-production facilities.
Automated fermentation control systems with dissolved oxygen and pH telemetry are rewriting how urban brewpubs manage batch consistency. Small-scale operators in Copenhagen and Melbourne are adopting these platforms to reduce labor dependency during overnight fermentation cycles. The technology is compressing the minimum viable scale for quality parity with larger competitors.
REACH chemical restriction expansions are phasing out certain sealant compounds in European equipment manufacturing, forcing gasket and valve suppliers to reformulate product lines. German vessel fabricators are absorbing recertification costs while lobbying for extended transition periods. This regulatory pressure is accelerating material standardization across CE-marked equipment categories.
Direct equipment financing through brewery-specific leasing vehicles is displacing traditional capex procurement among independent operators. Regional banks in Oregon and Colorado are originating specialized equipment loans collateralized by fermentation vessels. This channel innovation is most visible in American microbrewery clusters where SBA lending programs have expanded eligibility.
Microbrewery Equipment Market Segmentation
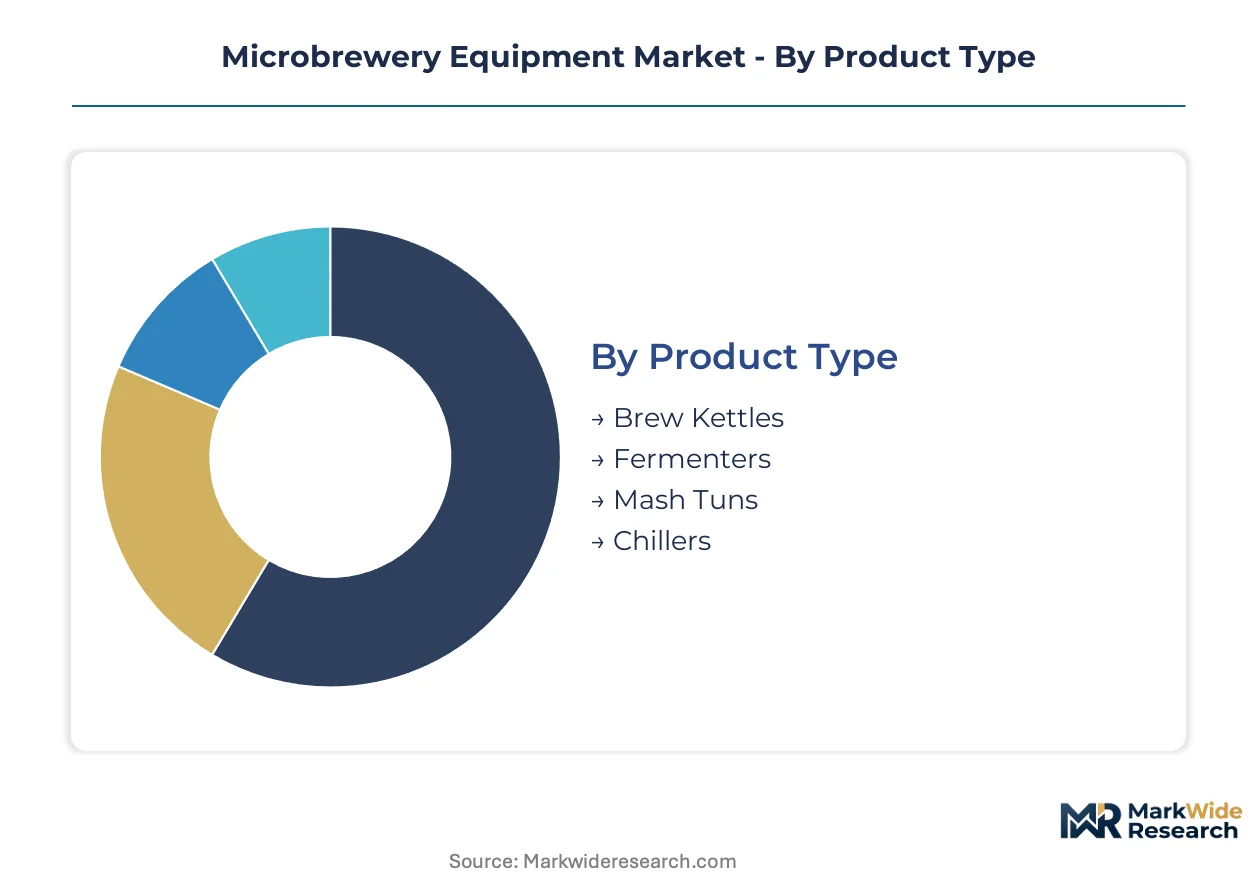
Equipment segmentation in microbrewing reflects divergent compliance burdens and capital intensity thresholds across vessel types and heating modalities. Certification requirements from the FDA, EU Machinery Directive, and Germany's WHG classification create divergent market access costs that reshape competitive positioning within each category.
Product Type:
Fermenters and brew kettles carry the heaviest certification loads, with ASME pressure vessel stamping and CE marking mandatory for jacketed units destined for EU markets or German WHG water hazard zones.
- Fermenters:Cylindrical-conical vessels in 304 or 316L stainless steel with sanitary welded seams rated for CIP protocols. Demand concentrates among independent breweries in Oregon and Washington seeking capacity expansion without greenfield construction, constrained by nickel price volatility affecting 316L input costs.
- Brew Kettles:Vessels engineered for wort boiling with integrated heat-exchange surfaces or direct-fire configurations. Procurement clusters in Bavaria's craft beer corridor as EU Ecodesign regulations mandate heat-recovery systems and electric configurations, forcing equipment replacement cycles.
- Mash Tuns:Lautering vessels with false bottoms and raker assemblies for grain bed separation. Specifications vary by batch size and automation tier.
- Chillers:Heat-exchange apparatus for wort cooling and fermentation temperature control. Plate-and-frame configurations dominate mid-scale installations.
Fermenters sit at the top of the volume ranking, with brew kettles climbing the fastest amid energy efficiency retrofit mandates.
Technology:
Heating modality selection hinges on municipal fire codes, grid capacity, and thermal consistency requirements, with electric systems gaining share in urban brewpubs and steam retaining preference among production breweries.
- Electric Heating:Immersion elements or external calandria configurations delivering precise temperature control without combustion. Displacing direct-fire across Portland, Seattle, and Denver brewpubs where zoning liberalization meets tightened fire safety enforcement, though constrained by grid capacity limitations in older buildings.
- Steam Heating:Jacketed vessels or internal steam coils leveraging central boiler infrastructure. Retains dominance among production breweries seeking thermal consistency across larger kettle volumes, tethering capital deployment to legacy steam infrastructure availability.
- Direct Fire:Open-flame burners beneath kettles or fired mash tuns. Municipal restrictions are accelerating displacement in urban cores.
- Indirect Heating:Thermal fluid or hot water intermediary systems separating heat source from process vessel. Niche adoption in specialized applications.
Steam heating retains the largest installed base, with electric configurations expanding most quickly under regulatory pressure.
Application:
Beer style segmentation drives divergent vessel specifications, with ales demanding shorter fermentation cycles and stouts requiring temperature-controlled conditioning capabilities that reshape equipment sizing.
- Ales:Top-fermented styles with warmer fermentation profiles and shorter maturation periods. Equipment specifications emphasize rapid turnaround and multi-batch scheduling flexibility.
- Lagers:Bottom-fermented styles requiring extended cold conditioning. Jacketed fermenters with precise temperature control dominate capital allocation.
- Stouts:Dark styles with roasted malt character and nitrogen dispensing requirements. Specialized conditioning tanks and serving pressure systems differentiate equipment needs.
- Specialty Beers:Sours, barrel-aged offerings, and experimental styles with non-standard process flows. Custom vessel configurations and extended aging infrastructure command premium pricing.
Ales command the broadest equipment base, with specialty beers gaining share fastest among differentiation-focused independent breweries.
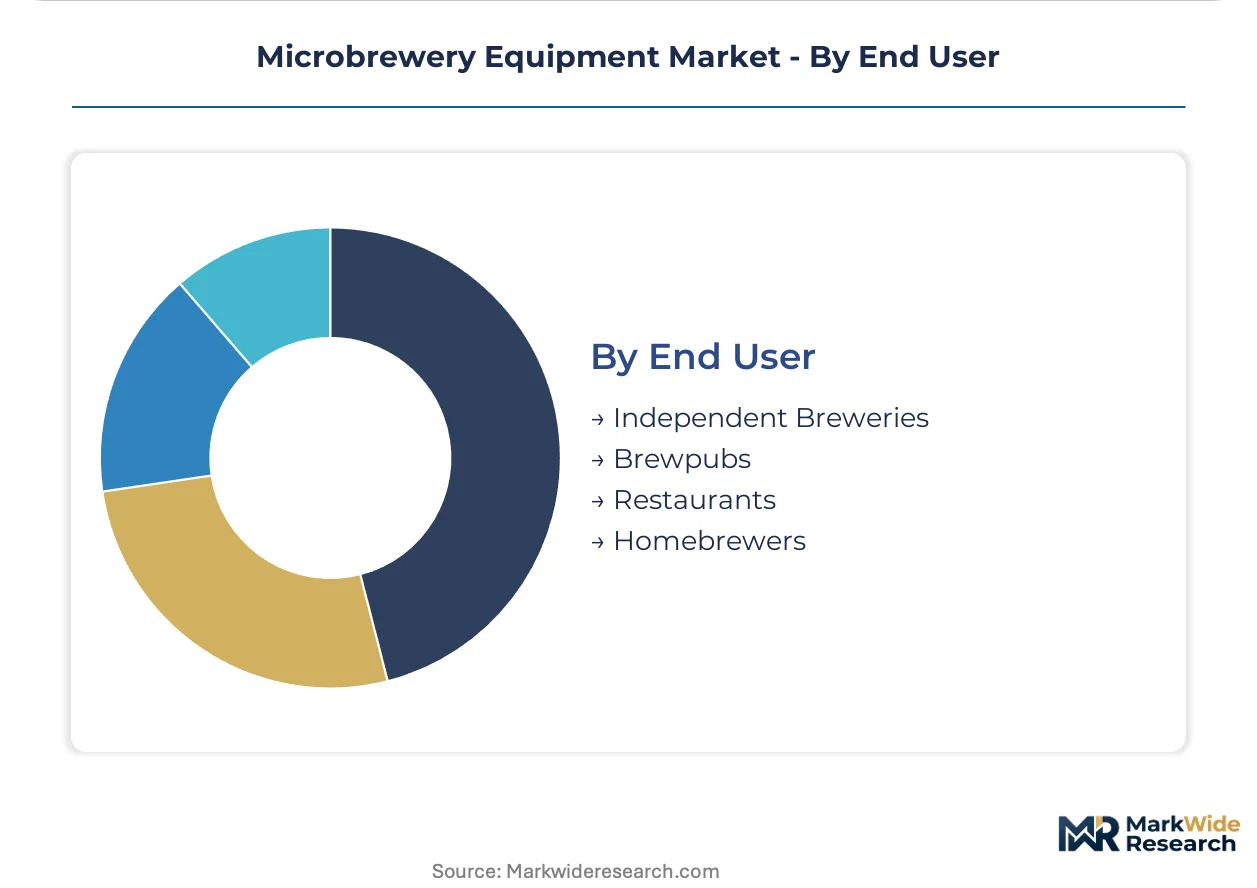
End User:
Customer type determines scale thresholds and automation sophistication, with independent breweries and brewpubs representing divergent procurement patterns around turnkey systems versus custom fabrication.
- Independent Breweries:Production-focused operations packaging for distribution. Capital deployment concentrates on fermenter capacity expansion and automated brewhouse skids, with financing increasingly sourced through regional equipment leasing vehicles.
- Brewpubs:On-premise consumption models with space-constrained footprints. Demand favors compact electric-heated systems and modular skid configurations that reduce installation complexity.
- Restaurants:Food-service operations with ancillary brewing programs. Smaller-scale equipment with simplified operational requirements dominates procurement.
- Homebrewers:Enthusiast segment with entry-level specifications. Price-sensitive demand concentrated in starter kits and small-batch vessels.
Independent breweries anchor equipment volume, with brewpubs climbing the fastest under urban zoning liberalization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's craft beer corridor anchors equipment procurement intensity, with independent breweries scaling fermenter capacity amid tightening EU energy mandates. Municipal zoning shifts and water hazard regulations are redistributing demand across four distinct national markets.
United States
Oregon and Washington breweries drive fermenter replacement cycles as capacity expansion outpaces greenfield construction. The EPA's effluent guidelines for brewery wastewater constrain equipment specifications in American installations. Pacific Northwest clusters concentrate procurement of electric-heated brewhouse systems as Portland and Seattle relax occupancy restrictions on production facilities.
Germany
Bavarian craft brewers face forced equipment upgrades under EU Ecodesign heat-recovery mandates. Germany's WHG water hazard classification creates six-to-nine-month approval delays for jacketed vessel exports. Munich-area fabricators absorb recertification costs while lobbying for extended transition periods on REACH chemical restrictions affecting sealant compounds.
India
Karnataka and Maharashtra state excise reforms are licensing microbreweries for the first time, opening turnkey system demand. The country's national food safety regulator imposes evolving standards on food-grade production equipment. Bangalore and Mumbai represent first-mover concentration points for modular skid suppliers seeking rapid deployment.
Australia
Melbourne urban brewpubs adopt automated fermentation control platforms to reduce labor dependency overnight. Australian therapeutic goods and food safety oversight shapes material certification requirements for imported vessels. Victorian craft beer clusters favor compact electric systems as municipal fire codes tighten in dense urban cores.
China
Shandong Peninsula equipment fabricators serve domestic craft beer growth alongside export markets. China's national standards administration governs pressure vessel certification and stainless steel grade specifications. Qingdao and Jinan manufacturing bases concentrate heat-exchange skid production for regional brewery expansion.
Microbrewery Equipment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modularity and service bundling to differentiate positioning. The vendor base stratifies across three capability levels: integrated system architects, specialist vessel fabricators, and turnkey skid assemblers. Dominant competitive moves center on captive fabrication investments and multi-source procurement partnerships that compress lead times for mid-sized brewery customers.
Among Nordic and North American system architects, Alfa Laval and Paul Mueller Company exemplify divergent strategic postures—one leveraging heat-exchange expertise across brewhouse utility skids, the other sustaining position through captive tank fabrication. Ss Brewtech occupies a position within the modularity-focused tier, competing on installation complexity reduction for new market entrants. These three anchors illustrate how geographic origin and organizational structure map onto distinct competitive archetypes in vessel supply.
| Leading Market Players |
|---|
| Alfa Laval |
| DME Brewing Solutions |
| HG Machinery |
| Paul Mueller Company |
| Ss Brewtech |
| GEA Group |
| JV Northwest |
| LEHUI |
| Krones AG |
| Others |
Value Chain & Pricing Dynamics
Electric heating system adoption across urban brewpubs is compressing cost economics while concentrating procurement power among vessel manufacturers with integrated heat-exchange capabilities. This technology transition simultaneously elevates input cost sensitivity for nickel-bearing 316L stainless steel and rewards fabricators with captive calandria production.
Pricing Analysis
Input cost pass-through from nickel price volatility directly pressures 316L stainless steel fermenter pricing, with Indonesian and Philippine ore export policies creating margin unpredictability for custom tank fabricators. Three-tier pricing structure across premium, standard, and economy levels separates ASME-stamped jacketed vessels from basic CIP-rated units from entry-level homebrew configurations. Cost compression in mid-tier electric brewhouse systems is intensifying because EU Ecodesign retrofit mandates accelerate replacement cycles. Homebrewers exhibit highest price sensitivity, while production breweries seeking WHG-certified jacketed vessels demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Refurbishment flows for jacketed fermenters and heat-exchange skids create secondary equipment channels that moderate new-build pricing pressure for entry-tier buyers. Geographic supply concentration centers on China, Germany, and the United States, with Shandong Peninsula fabricators and Bavarian vessel specialists anchoring regional production clusters. Raw material dependencies draw from Indonesian nickel ore, Swedish specialty steel, and Chinese control system components. Single-source vulnerability in orbital TIG welding certification constrains production capacity at custom fabricators. Distribution runs through direct OEM sales for large systems and specialized brewing equipment distributors for mid-scale and entry-tier segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier electric brewhouse systems where energy efficiency certification commands pricing power, while modular skid standardization reduces installation cost-to-serve for mid-market penetration.
For Market Incumbents: Deepen captive fabrication of heat-exchange skids to defend against modular turnkey competitors encroaching from below. Secure multi-source stainless steel supply agreements to buffer nickel price volatility. Invest in ASME Section IX welding certification pipelines to alleviate production bottlenecks constraining order fulfillment. For New Entrants and Emerging Players: Urban brewpubs in secondary Indian cities represent the most penetrable buyer archetype, with Karnataka and Maharashtra licensing creating first-mover terrain absent entrenched supplier relationships. Target containerized brewhouse configurations that compress deployment timelines where specialized installation labor remains scarce. Pursue direct equipment financing partnerships with regional banks to replicate Oregon and Colorado leasing channel success. For Investors and Strategic Acquirers: Valuations sit cheapest among specialist vessel fabricators lacking integrated control system capabilities but holding established WHG certification pathways. Long-term viability favors acquisition targets with demonstrated heat-exchange engineering depth and regulatory compliance track records across multiple jurisdictions. Monitor EU Ecodesign implementation enforcement intensity and Indian state-level excise liberalization momentum as inflection indicators for equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Exchange Skid Production | Secures margin control over brewhouse utility systems as electric heating displaces direct-fire configurations. |
| Multi-Source Stainless Steel Procurement | Reduces lead time risk and nickel price exposure for 316L fermenter fabrication. |
| Containerized Brewhouse Standardization | Enables rapid deployment in Indian secondary cities lacking specialized installation infrastructure. |
| Direct Equipment Financing Partnerships | Replicates SBA-backed leasing channel success in American microbrewery clusters. |
| ASME/WHG Certification Pipeline Investment | Alleviates sanitary welding certification scarcity constraining custom fabricator capacity. |
Study Parameters
Multiple input streams — technical director interviews at vessel fabricators, procurement lead discussions at independent breweries, and regulatory affairs engagement with EU and German certification bodies — were reconciled against trade flow data, customs records, and SEC filings from publicly listed equipment manufacturers. Bottom-up capacity assessments and top-down market sizing were triangulated to establish baseline volume figures.
Data-stream reconciliation across product type, heating modality, end-user scale, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from equipment replacement cycle analysis and capacity expansion trajectories observed across Pacific Northwest and Bavarian brewery clusters. Forecast inputs incorporated EU Ecodesign implementation schedules and Indian state-level licensing reform progressions.
Underlying measurement precision varies by segment; electric heating technology and established independent brewery categories carry tighter precision than emerging Indian market projections. Forecasts reflect assumptions regarding regulatory enforcement continuity and raw material supply stability. Practitioners should monitor Indonesian nickel export policy shifts and German WHG approval backlog durations for early signals of supply constraint or pricing pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
Food Recycler Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Bread Maker Market