
 Blockchain in Retail Banking Market | 2026-2036
Blockchain in Retail Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Retail Banking Market Intelligence
The retail banking blockchain landscape is rebalancing between institution-grade private deployments and commodity public-chain integrations. Ripple anchors correspondent banking liquidity through its pre-funded settlement architecture, while ConsenSys dominates Ethereum-compatible infrastructure for programmable retail products. HashCash Consultants competes on white-label remittance stacks across emerging-market bank partnerships.
Blockchain in retail banking denotes cryptographically linked distributed ledgers that enable atomic settlement, immutable audit trails, and programmable compliance for retail financial products, typically operating with sub-second finality on permissioned nodes. Payment Processing leads application adoption as banks displace legacy SWIFT messaging for real-time gross settlement, while Smart Contracts represent the fastest-expanding margin pool as programmable escrow and automated lending protocols mature. Private Blockchain technology sustains the dominant deployment model among Tier 1 retail banks, though Hybrid Blockchain architectures are gaining traction where institutions require selective data exposure to regulators without surrendering transactional privacy.
The US Office of the Comptroller of Currency and the SEC jointly shape bank participation in digital asset custody, with OCC interpretive letters conditioning national bank charters on segregated cold-storage protocols. The EU's MiCA framework and EBA stress-testing standards for crypto-asset exposures are forcing retail banks to maintain dual compliance stacks for tokenized and traditional liabilities. Stakeholders must decide whether to build captive blockchain infrastructure or rely on vendor-hosted nodes before regulatory capital requirements for crypto-asset risks crystallize.
Market Dynamics
Correspondent banks are dismantling pre-funded nostro-vostro liquidity pools in favor of real-time gross settlement rails, forcing infrastructure providers to compress settlement latency from T+2 to sub-second finality. This compression is redistributing value from messaging incumbents to atomic settlement engines.
Growth Catalysts
- EU MiCA Custody Mandates:The Markets in Crypto-Assets framework compels retail banks to deploy segregated cold-storage protocols for tokenized deposits, creating immediate infrastructure procurement cycles across Frankfurt, Paris, and Amsterdam banking clusters.
- Atomic Settlement Architectures:Distributed ledger finality eliminates counterparty exposure in cross-border corridors, reducing trapped liquidity requirements by pre-funding positions on-chain rather than across correspondent accounts.
- Singapore Tokenized Deposit Pilots:The Monetary Authority of Singapore's licensing of bank-led consortia for programmable money trials has concentrated vendor R&D investment in Southeast Asian deployment templates.
Market Restraints
- Dual Compliance Stack Costs:Banks must maintain parallel operational frameworks for traditional liabilities and tokenized assets, doubling audit, reporting, and capital reserve infrastructure spend without offsetting revenue streams.
- Validator Node Concentration:Permissioned network security depends on a narrow geographic base of infrastructure providers, creating systemic resilience risks if node hosting concentrates in single-jurisdiction data centers.
- Legacy Core Banking Integration Friction:COBOL-based ledger systems require expensive middleware layers to interface with blockchain settlement rails, extending deployment timelines and inflating total cost of ownership.
Strategic Opportunities
- Programmable Escrow Products:Smart contract automation of conditional payments—rent releases, milestone-based construction finance, trade settlement—opens margin pools in retail segments previously served by manual letter-of-credit processes.
- Hybrid Blockchain Architectures:Selective data exposure models allow banks to satisfy regulatory transparency requirements without surrendering transactional privacy to public chain observers, bridging institutional and commodity infrastructure.
- India CBDC Interoperability:The Reserve Bank of India's wholesale digital rupee pilots create openings for retail banks to build API bridges between central bank liabilities and tokenized commercial deposits.
Industry Challenges
- Distributed Systems Engineering Talent Scarcity:Banks compete with protocol foundations and DeFi protocols for cryptographers and consensus mechanism specialists, inflating compensation costs and extending hiring cycles.
- Regulatory Capital Treatment Uncertainty:The European Banking Authority has yet to finalize risk-weighting methodologies for crypto-asset exposures, freezing long-term infrastructure investment decisions pending prudential clarity.
- Cross-Chain Settlement Standardization Delays:Absent interoperable messaging standards between Ethereum-compatible, Hyperledger Fabric, and Corda networks, banks face vendor lock-in or expensive multi-stack maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Retail Banking Market |
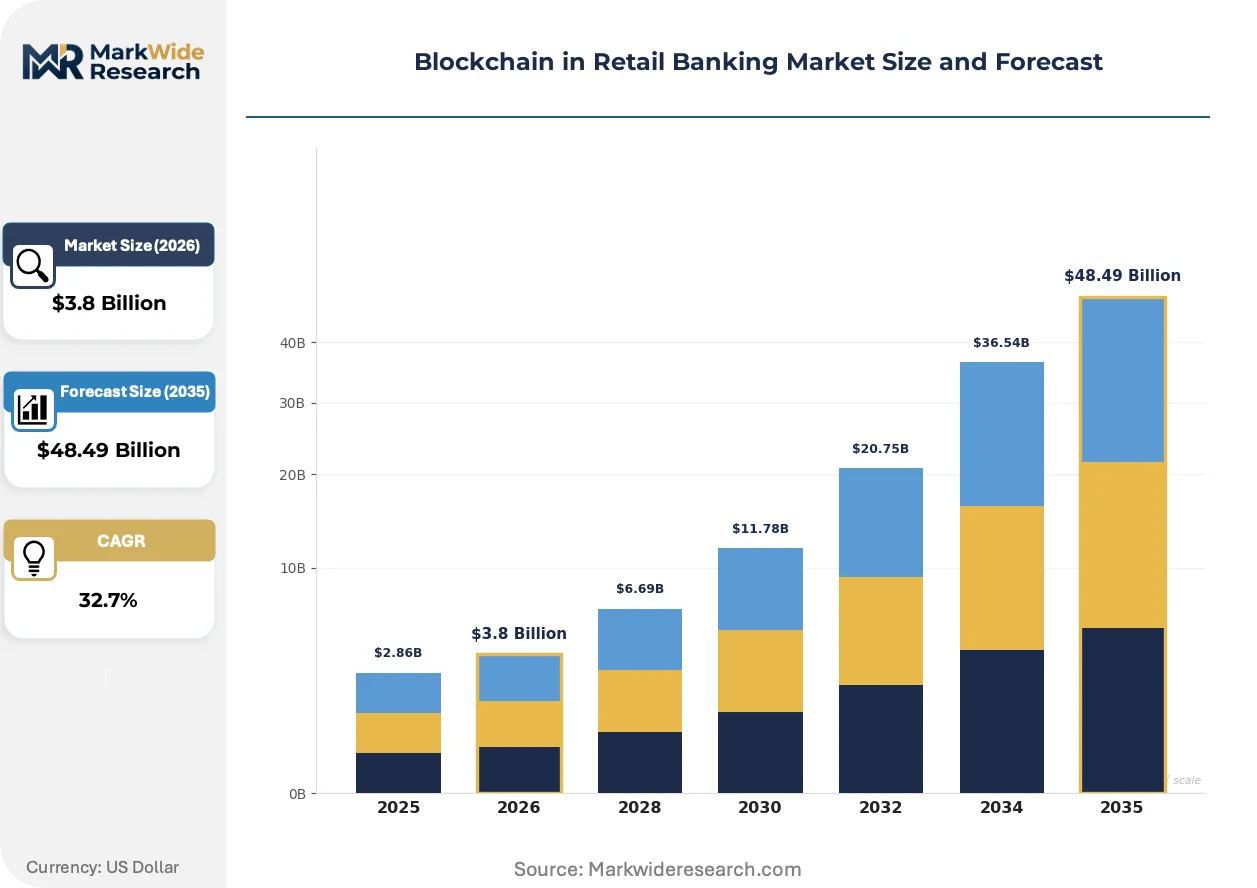
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $48.49 Billion |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Payment Processing, Identity Verification, Fraud Prevention, Smart Contracts Technology: Public Blockchain, Private Blockchain, Hybrid Blockchain, Consortium Blockchain End User: Retail Banks, Online Banking Platforms, Credit Unions, Financial Institutions Solution: Transaction Management, Asset Management, Compliance Solutions, Customer Authentication |
| Companies Covered | Coinbase, Kaleido, Ripple, LeewayHertz, HashCash Consultants, Chainalysis, ConsenSys, Innowise Group, Circle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Retail Banking Market Strategic Shifts & Innovations
Settlement infrastructure is converging around programmable compliance engines that embed regulatory logic directly into transaction execution, eliminating post-trade reconciliation and manual exception handling. This shift is compressing operational cost structures while raising the technical bar for infrastructure providers.
Zero-knowledge proof circuits are unifying privacy-preserving audit capabilities with real-time regulatory visibility. Tier 1 retail banks in Switzerland and Singapore are deploying zk-SNARK validation layers for tokenized deposit transfers, compressing compliance latency from batch-based reporting to continuous attestation. This unifying architecture enables selective disclosure to supervisors without exposing counterparty identities to network participants.
The EU's Digital Operational Resilience Act (DORA) mandates granular ICT risk management for financial entities handling crypto-asset infrastructure. Banks must map third-party dependencies across node hosting, oracle services, and smart contract audit providers, creating procurement friction that favors vertically integrated technology stacks over modular vendor assemblies. German and French supervisors are conducting joint stress tests of bank-led blockchain networks against DORA's incident response timelines.
Corporate treasury departments are consolidating liquidity management onto unified platforms that span fiat and tokenized deposit pools. Procurement teams at multinational manufacturers are demanding API-native cash management from relationship banks, displacing manual SWIFT messaging for intra-group funding. This concentration is most visible in Singapore's trade finance corridors, where programmable escrow has compressed working capital cycles for electronics and commodity traders.
Blockchain in Retail Banking Market Segmentation
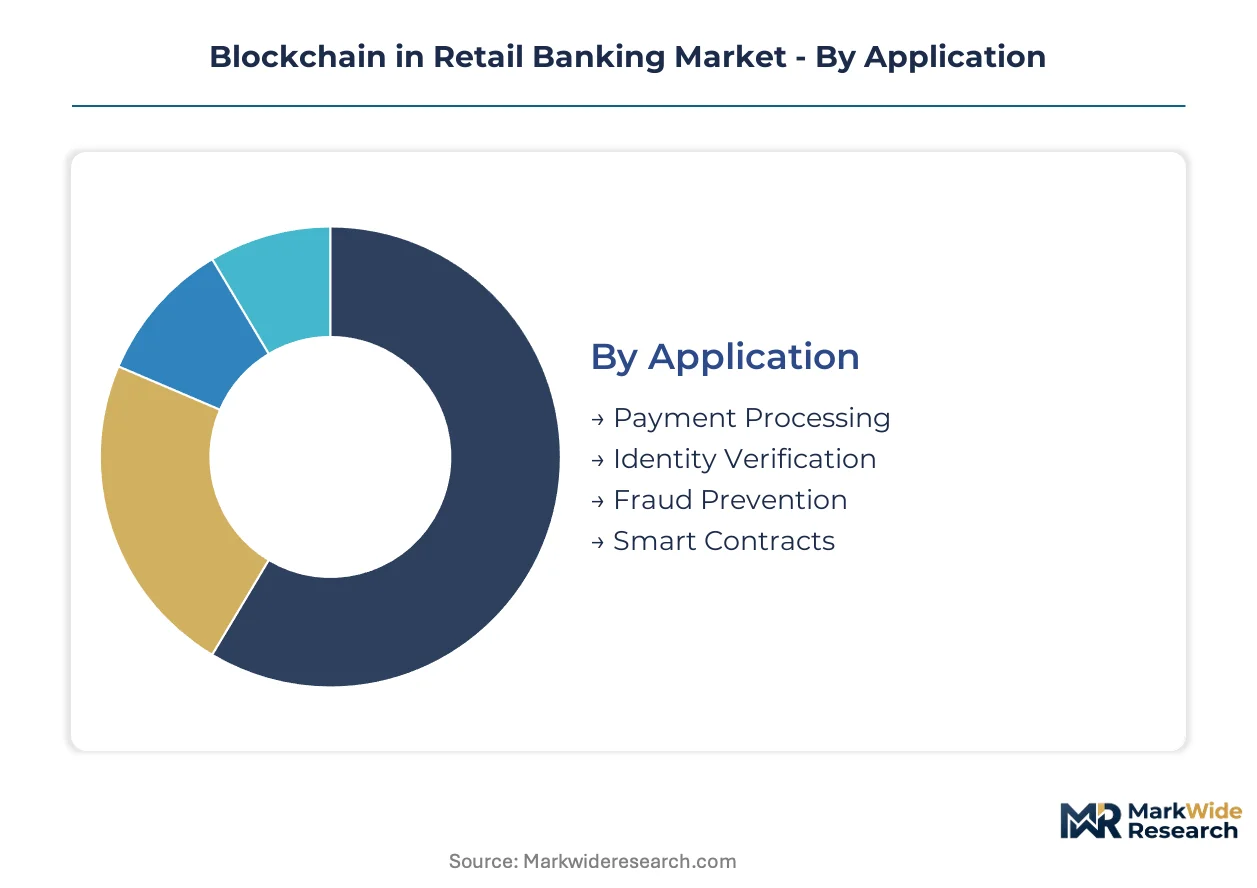
Segmentation in blockchain retail banking reveals how infrastructure investments cluster around compliance-heavy workflows versus customer-facing automation. Banks prioritize segments where regulatory capital treatment is clearest, delaying spend in ambiguous categories pending prudential guidance.
Application:
Payment Processing carries the heaviest certification load, requiring PCI-DSS attestation plus jurisdiction-specific payment service licenses. Identity Verification and Fraud Prevention face lighter formal burdens but demand continuous model validation under EU AI Act risk classifications.
- Payment Processing:Real-time gross settlement rails displace SWIFT messaging for cross-border corridors. Demand concentrates in Singapore and Frankfurt banking clusters, driven by MAS licensing of tokenized deposit pilots and ECB pressure on nostro-vostro liquidity efficiency.
- Smart Contracts:Programmable escrow and automated lending protocols execute conditional payments without intermediary reconciliation. Growth accelerates in trade finance applications where electronics manufacturers in Southeast Asia demand milestone-based release mechanisms.
- Identity Verification:Cryptographic credentialing replaces KYC document workflows. Regulatory acceptance varies by jurisdiction, with Swiss FINMA guidelines providing clearer deployment pathways than US state-level money transmitter frameworks.
- Fraud Prevention:Immutable audit trails enable pattern detection across distributed ledgers. Deployment lags in retail segments due to latency requirements for real-time transaction scoring.
Payment Processing sits at the top of the volume ranking, with Smart Contracts climbing the fastest.
Technology:
Cost structures diverge sharply across deployment models, with private infrastructure requiring captive data center investment while public-chain integrations rely on variable gas fees.
- Private Blockchain:Permissioned nodes with sub-second finality serve Tier 1 retail banks requiring transactional privacy. Frankfurt and Paris banking clusters dominate procurement, constrained by ECB operational resilience mandates for node geographic distribution.
- Hybrid Blockchain:Selective data exposure satisfies regulatory transparency without surrendering counterparty privacy to public observers. Singapore's bank-led consortia favor this architecture for tokenized deposit interoperability with wholesale CBDC pilots.
- Public Blockchain:Ethereum-compatible settlement rails reduce infrastructure capital requirements. Adoption concentrates among online banking platforms with lighter legacy core banking integration burdens.
- Consortium Blockchain:Shared infrastructure spreads compliance costs across correspondent banking networks. R3 Corda deployments in London trade finance corridors illustrate this model's viability for multi-party documentary credit workflows.
Private Blockchain commands the largest installed base, though Hybrid Blockchain is gaining share fastest among new procurement cycles.
End User:
Customer sophistication determines implementation approach, with established institutions prioritizing legacy integration over greenfield automation.
- Retail Banks:Full-service institutions with branch networks and correspondent relationships. Deployment concentrates in cross-border payment corridors where nostro-vostro liquidity compression delivers measurable capital efficiency gains.
- Financial Institutions:Broker-dealers and asset managers with lighter regulatory capital constraints. Demand focuses on tokenized deposit custody infrastructure under EU MiCA segregated cold-storage mandates.
- Online Banking Platforms:Digital-native operators without COBOL legacy systems. API-first architectures enable faster blockchain settlement rail integration than incumbent competitors.
- Credit Unions:Member-owned cooperatives with limited technology procurement budgets. Deployment lags due to shared service organization dependencies for core banking system upgrades.
Retail Banks absorb the majority of current infrastructure spend, with Online Banking Platforms expanding most quickly in greenfield markets.
Solution:
Margin pools concentrate where automation eliminates manual reconciliation workflows, particularly in regulatory reporting and exception handling.
- Transaction Management:Atomic settlement engines compress finality from T+2 to sub-second. Demand clusters in correspondent banking networks dismantling pre-funded liquidity pools.
- Compliance Solutions:Programmable logic embeds regulatory requirements directly into transaction execution. EU MiCA implementation drives procurement across Frankfurt, Amsterdam, and Paris banking clusters.
- Asset Management:Tokenized deposit and security token infrastructure for retail investment products. Growth constrained by EBA uncertainty on risk-weighting methodologies for crypto-asset exposures.
- Customer Authentication:Cryptographic credentialing replaces password and SMS-based verification. Deployment accelerates where PSD2 strong customer authentication mandates already modernized identity stacks.
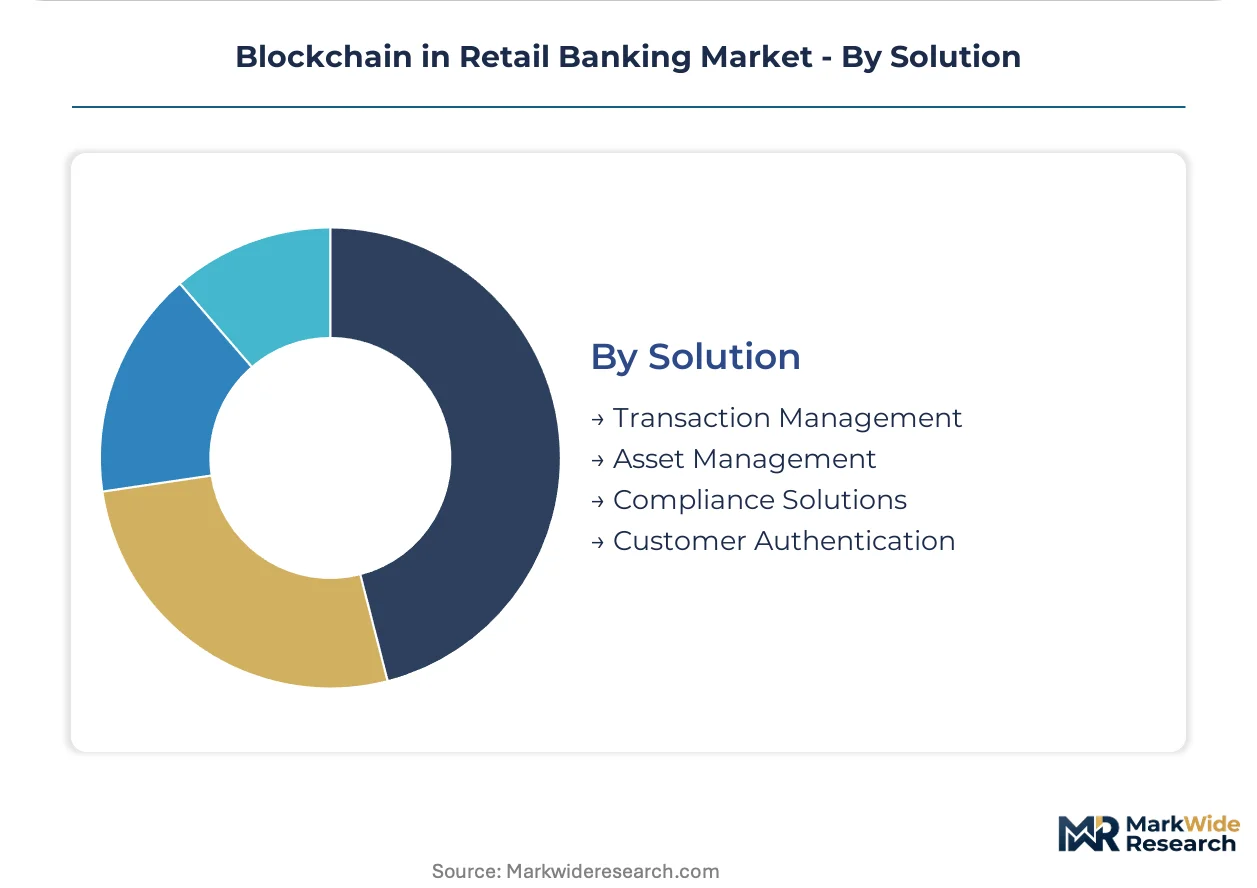
Transaction Management leads solution category revenue, with Compliance Solutions showing the steepest expansion trajectory as MiCA implementation deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore concentrates vendor R&D investment through MAS-licensed tokenized deposit pilots, while the United States fragments across competing regulatory interpretations from the OCC and SEC.
United States
Cross-border payment corridors absorb distributed ledger infrastructure as correspondent banks dismantle pre-funded nostro-vostro pools. The OCC and SEC jointly shape digital asset custody participation through interpretive letters conditioning national bank charters on segregated cold-storage protocols. New York and San Francisco banking clusters anchor procurement of atomic settlement engines.
Singapore
The Monetary Authority of Singapore has licensed multiple bank-led consortia for programmable money trials, concentrating demand for hybrid blockchain architectures. MAS regulatory frameworks provide clearer deployment pathways for tokenized deposit interoperability with wholesale CBDC pilots. Singapore's trade finance corridors compress working capital cycles through programmable escrow for electronics and commodity traders.
Germany
Frankfurt banking clusters dominate private blockchain procurement, constrained by ECB operational resilience mandates for node geographic distribution. The EU's Digital Operational Resilience Act mandates granular ICT risk management for crypto-asset infrastructure handlers. German supervisors conduct joint stress tests of bank-led blockchain networks against DORA's incident response timelines.
India
The Reserve Bank of India's wholesale digital rupee pilots create openings for retail banks to build API bridges between central bank liabilities and tokenized commercial deposits. RBI regulatory guidance shapes capital treatment for crypto-asset exposures pending final prudential clarity. Mumbai and Bangalore technology clusters concentrate distributed systems engineering talent for blockchain settlement rail integration.
Switzerland
Tier 1 retail banks deploy zero-knowledge proof validation layers for tokenized deposit transfers, compressing compliance latency from batch-based reporting to continuous attestation. Swiss FINMA guidelines provide clearer deployment pathways for cryptographic credentialing than US state-level money transmitter frameworks. Zurich banking clusters anchor privacy-preserving audit capabilities with real-time regulatory visibility.
Blockchain in Retail Banking Market Key Industry Players
Top-tier vendors anchor correspondent banking liquidity infrastructure, while mid-tier specialists compete on white-label remittance stacks and compliance automation. The vendor base stratifies between institution-grade private deployment providers and commodity public-chain integrators. Three archetypes dominate: settlement engine specialists, programmable infrastructure platforms, and regulatory compliance enablers. Strategic moves concentrate on consortia formation for shared compliance costs and API-native cash management platform development.
Among infrastructure-focused entities, Ripple and ConsenSys occupy positions at opposing poles of the deployment spectrum, while HashCash Consultants exemplifies the emerging-market partnership model. Ripple anchors pre-funded settlement architecture for correspondent banking networks. ConsenSys dominates Ethereum-compatible infrastructure for programmable retail products. HashCash Consultants competes across white-label remittance stacks through emerging-market bank partnerships.
| Leading Market Players |
|---|
| Coinbase |
| Kaleido |
| Ripple |
| LeewayHertz |
| HashCash Consultants |
| Chainalysis |
| ConsenSys |
| Innowise Group |
| Circle |
| Others |
Cost & Logistics Intelligence
Cloud compute spot pricing indices and specialized semiconductor foundry wafer costs cascade through blockchain infrastructure procurement tiers, compressing margins for node-hosting providers while concentrating pricing power with vertically integrated settlement engine vendors serving Tier 1 retail banks.
Pricing Analysis
Capacity additions in Singapore and Frankfurt are reshaping price floors for permissioned node deployments as MAS-licensed consortia expand tokenized deposit pilot infrastructure. Pricing stratifies across enterprise-grade private deployments, hybrid architectures with selective disclosure capabilities, and commodity public-chain integrations. Price differentiation hinges on sub-second finality guarantees and MiCA-compliant cold-storage certification tiers. Cost compression in public-chain integration tiers is intensifying because gas fee volatility exposes retail banks to unhedged operational expenditure. Online banking platforms exhibit highest price sensitivity due to limited legacy integration budgets, while correspondent banking networks prioritize finality reliability over unit economics.
Supply Chain Analysis
Distributed systems engineering talent scarcity in Mumbai, Bangalore, and Zurich shapes infrastructure provider location decisions and inflates compensation costs for consensus mechanism specialists. Supply concentration centers on Singapore, Germany, and Switzerland for node hosting and programmable compliance engine development. Raw material dependencies include specialized ASIC hardware for zero-knowledge proof validation, enterprise-grade server infrastructure, and cryptographic security modules. Single-source vulnerability persists for zero-knowledge circuit fabrication, with foundry capacity concentrated among advanced semiconductor manufacturers. Distribution runs through direct vendor relationships with Tier 1 retail banks and consortia-led procurement frameworks for shared compliance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in blockchain retail banking infrastructure flows from atomic settlement automation eliminating manual reconciliation workflows and correspondent banks' willingness to pay premium tiers for sub-second finality guarantees.
For Market Incumbents: Deepen captive node hosting capabilities across geographically distributed data centers to satisfy ECB operational resilience mandates for validator concentration limits. Fortify smart contract audit practices as DORA incident response timelines tighten procurement requirements for vertically integrated technology stacks. Counter emerging programmable infrastructure platforms by embedding regulatory logic directly into transaction execution layers. For New Entrants and Emerging Players: Capture white-space in credit union shared service organizations where core banking system upgrade dependencies delay blockchain settlement rail deployment. Target India API bridge development between RBI wholesale digital rupee pilots and tokenized commercial deposits. Pursue white-label remittance stack partnerships with emerging-market banks lacking in-house distributed systems engineering capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where dual compliance stack costs force smaller retail banks to abandon captive blockchain infrastructure investments. Five-to-ten-year viability favors vendors with vertically integrated programmable compliance engines and MAS-licensed deployment track records. Monitor EBA risk-weighting methodology finalization as the critical inflection signal for long-term infrastructure procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Consortia Formation for Shared Compliance | Spreads MiCA cold-storage infrastructure costs across Frankfurt and Paris banking clusters. |
| API-Native Cash Management Platform | Displaces SWIFT messaging for Singapore electronics manufacturers' intra-group funding. |
| Zero-Knowledge Proof Validation Layer | Compresses Swiss FINMA compliance latency from batch reporting to continuous attestation. |
| Hybrid Blockchain Architecture Deployment | Bridges institutional privacy requirements with MAS wholesale CBDC interoperability pilots. |
| Programmable Escrow Product Launch | Automates milestone-based construction finance releases previously served by manual letters of credit. |
Research Approach
Bottom-up retail bank procurement modeling reconciled against top-down settlement engine vendor capacity tracking forms the analytical core. Primary interviews with blockchain infrastructure CTOs, correspondent banking treasury heads, MiCA compliance officers, and MAS regulatory technology specialists combined with secondary validation from SEC interpretive letters, EBA stress-testing documentation, ECB operational resilience mandates, and Singapore MAS licensing records. Triangulation across deployment model segmentation and geographic regulatory cluster analysis ensures consistency.
Historical trendline analysis of nostro-vostro liquidity compression and tokenized deposit pilot expansion informs projection frameworks across the analysis window. Segmentation dimensions modeled include application type, technology deployment model, end-user institution category, and solution category, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from infrastructure procurement cycle timing and compliance deadline acceleration patterns. Forecast inputs incorporate validator node geographic distribution requirements and smart contract automation adoption curves in trade finance corridors.
Regulatory capital treatment uncertainty, cross-chain settlement standardization delays, and distributed systems engineering talent scarcity are the dominant revision risks. Forecasts reflect assumptions regarding MiCA implementation timeline adherence and EBA prudential guidance finalization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking Software Market
Banking
Japan Data Analytics in Banking Market
Banking
Embedded Banking Market
Banking
Global Banking BPS Market
Banking
Africa Data Analytics in Banking Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Europe Machine Learning in Banking Market
Banking
Banking ERP Software Market
Banking
Commercial Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
US Data Analytics in Banking Market
Banking
Global Big Data Analytics in Banking Market
Banking
China Retail Banking System Market
Banking
Europe Data Analytics in Banking Market
Banking
Global IoT in Banking and Financial Services Market
Banking
Banking-As-A-Service (Baas) Platform Market