
 Canada Data Analytics in Banking Market | 2026-2036
Canada Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Analytics in Banking Market Insights
Cloud delivery channels is reconfiguring how Canadian banks procure analytics infrastructure, shifting capital expenditure toward subscription models. Royal Bank of Canada leverages its AI research institutes in Toronto and Montreal to sustain proprietary model development. Toronto-Dominion Bank anchors its competitive stance through extensive customer data integration across retail and wealth platforms. International Business Machines Corp competes via hybrid cloud architectures tailored to OSFI-mandated data residency requirements.
Data analytics in banking encompasses the systematic extraction, processing, and modeling of structured and unstructured financial data to generate actionable intelligence for credit risk assessment, fraud detection, and customer segmentation. Core technical implementations require sub-second query latency on petabyte-scale data warehouses, typically deployed through columnar storage engines and in-memory processing frameworks. Predictive analytics solutions command premium pricing due to their direct linkage to loan loss provisioning accuracy and regulatory capital optimization. Cloud-based deployment is displacing legacy on-premise installations among mid-tier credit unions seeking to bypass capital-intensive infrastructure buildouts. Descriptive analytics retains dominant share in regulatory reporting, while prescriptive analytics represents the fastest-expanding margin pool as banks automate pricing and portfolio rebalancing decisions.
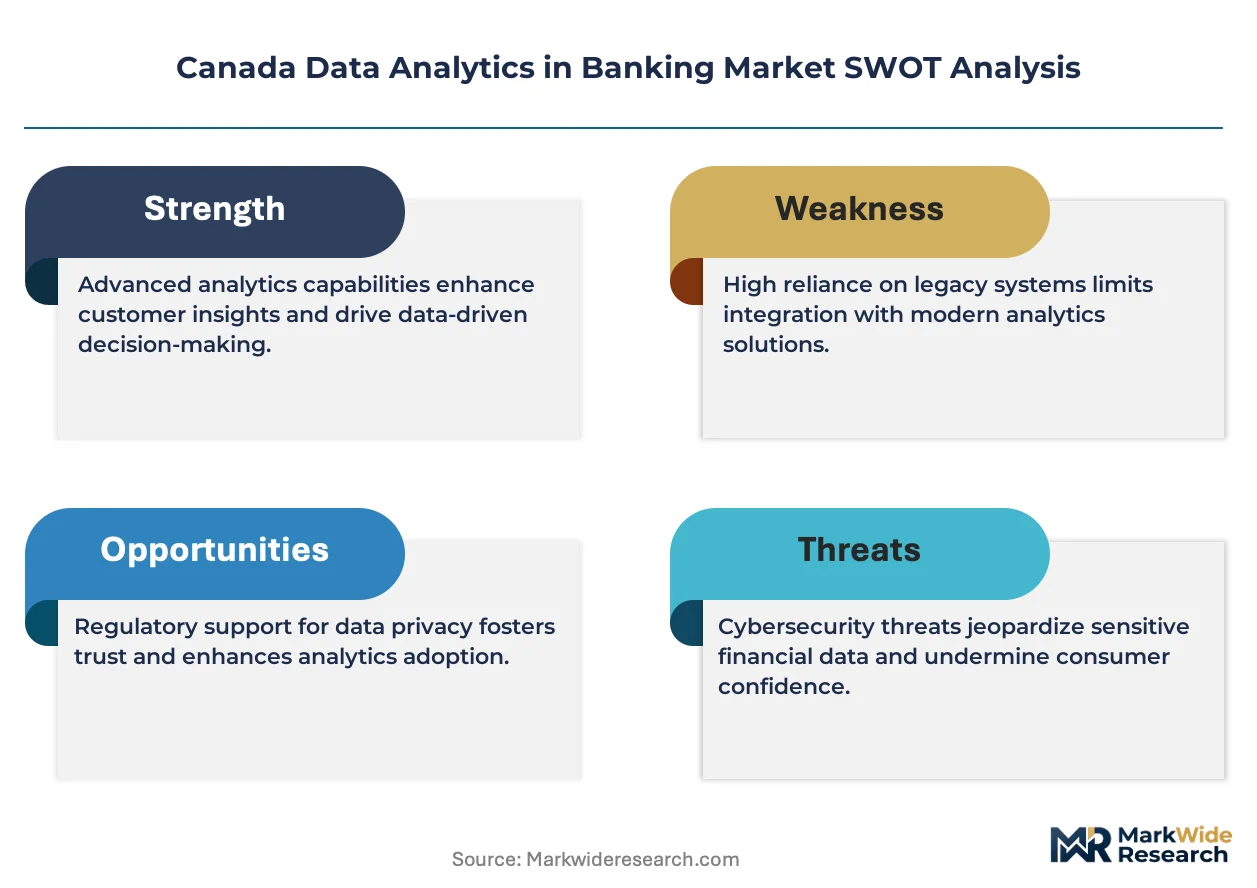
OSFI's Guideline B-13 mandates technology and cyber risk management standards that directly shape bank procurement criteria for analytics platforms, requiring demonstrable data lineage and model governance. Health Canada and PMRA do not regulate this sector; instead, the Personal Information Protection and Electronic Documents Act and provincial privacy commissioners enforce consent and data minimization protocols that constrain cross-border data flows. Stakeholders must monitor whether OSFI extends operational resilience expectations to third-party cloud providers, as this would force architectural redesigns across the vendor ecosystem.
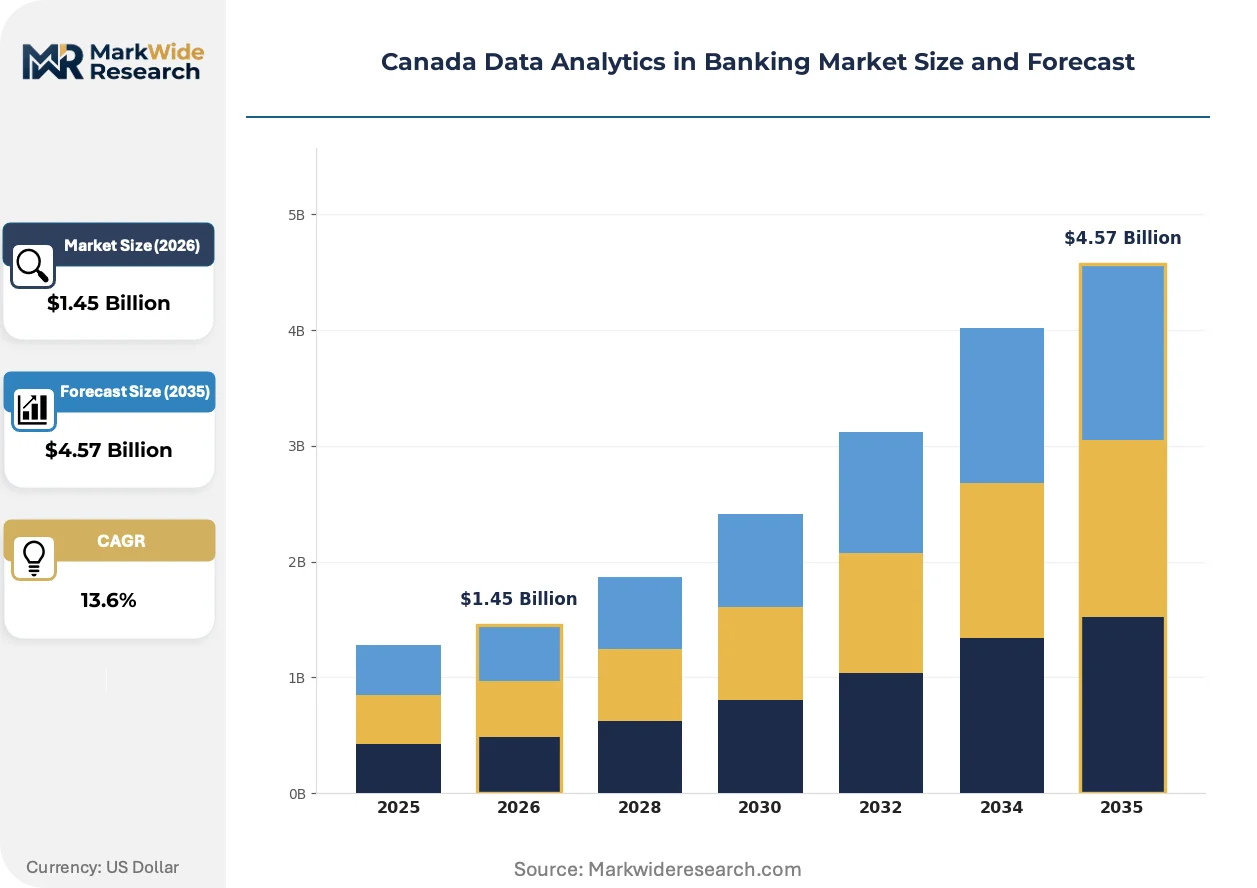
Market Dynamics
OSFI's Guideline B-13 is compressing procurement timelines as Canadian banks scramble to demonstrate compliant data lineage and model governance before regulatory deadlines. This single mandate is restructuring vendor selection criteria and accelerating cloud migration across the sector.
Growth Catalysts
- Real-time risk infrastructure:Retail banks are deploying sub-second query engines on petabyte-scale warehouses to support dynamic loan loss provisioning. Toronto's financial district concentrates this buildout.
- Guideline B-13 compliance:OSFI's technology and cyber risk standards mandate demonstrable model governance, forcing infrastructure replacement cycles that favor modern analytics platforms.
- Hybrid cloud architectures:Data residency requirements under PIPEDA are pushing institutions toward Canadian-sovereign cloud deployments that preserve cross-border operational continuity.
Market Restraints
- Specialized talent scarcity:Machine learning engineers with financial services domain expertise command premium compensation, constraining mid-tier credit union adoption.
- Legacy system entanglement:Core banking platforms at established institutions resist API-based integration, inflating customization costs for analytics overlays.
- PIPEDA consent protocols:Cross-border data flows face friction from provincial privacy commissioners, complicating multi-jurisdictional model training.
Strategic Opportunities
- Prescriptive analytics automation:Automated pricing and portfolio rebalancing decisions represent an underpenetrated margin pool as banks seek regulatory capital optimization.
- Montreal-Toronto AI corridor:Federal research funding and provincial talent pipelines are converging to create proprietary model development capabilities distinct from vendor offerings.
- Credit union cloud bypass:Mid-tier institutions are leapfrogging capital-intensive on-premise builds through subscription-based deployments.
Industry Challenges
- Model explainability standards:OSFI's evolving expectations for algorithmic transparency are forcing architectural redesigns of black-box predictive systems.
- Third-party vendor concentration:Dependency on a narrow set of cloud infrastructure providers creates systemic operational resilience concerns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Analytics in Banking Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Visualization, Predictive Analytics, Reporting Software, Data Warehousing End User: Retail Banks, Investment Firms, Credit Unions, Commercial Banks Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services Analytics Type: Descriptive Analytics, Prescriptive Analytics, Diagnostic Analytics, Streaming Analytics |
| Companies Covered | Royal Bank of Canada, Toronto-Dominion Bank, Bank of Montreal, Canadian Imperial Bank of Commerce, Bank of Nova Scotia, Desjardins Group, International Business Machines Corp, Oracle Corp, SAP SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Analytics in Banking Market Trends and Innovations
Canadian banking analytics is undergoing architectural virtualization as institutions dismantle monolithic data warehouses in favor of composable, cloud-native stacks. This transformation is redistributing value capture between infrastructure vendors and specialized analytics providers.
Columnar storage engines paired with in-memory processing frameworks are virtualizing traditional extract-transform-load pipelines. Mid-tier credit unions are adopting these technologies fastest, bypassing decades of technical debt. The shift is compressing time-to-insight from days to minutes while reducing total cost of ownership.
OSFI's Guideline B-13 is hardening procurement specifications across the sector. Banks must now demonstrate continuous model monitoring and automated drift detection. Tier-1 institutions are responding by building proprietary governance layers, while smaller players seek pre-certified vendor solutions.
Subscription consumption models are displacing perpetual license arrangements in analytics procurement. Canadian banks are unbundling software from implementation services, pressuring vendors to demonstrate standalone product value. This pattern is most visible among Toronto-based institutions modernizing wealth management platforms.
Canada Data Analytics in Banking Market Segmentation
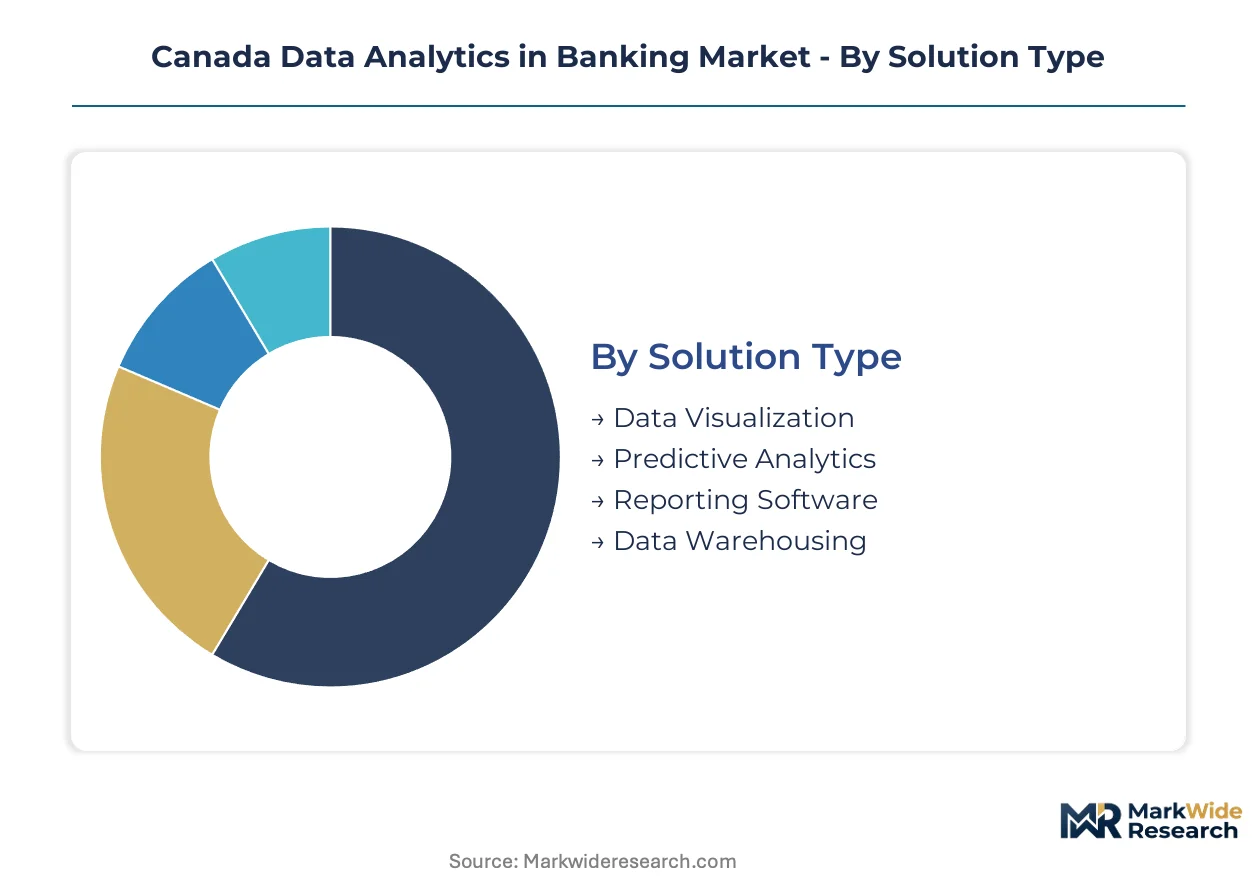
Canadian banking analytics procurement diverges sharply by institutional scale and regulatory exposure. Solution architecture, deployment modality, and analytical sophistication stratify across retail conglomerates, investment specialists, and cooperative credit structures.
Solution Type:
The use-case spectrum spans from executive dashboards to algorithmic decision engines, with complexity and price tier escalating proportionally.
- Predictive Analytics:Machine learning models forecast loan defaults, detect anomalous transactions, and optimize customer lifetime value calculations. Tier-1 institutions in Toronto concentrate procurement here, driven by OSFI-mandated stress testing and dynamic provisioning requirements.
- Data Warehousing:Petabyte-scale columnar repositories enable sub-second query latency across unified retail and wealth datasets. Demand clusters among established banks modernizing legacy core systems under compressed regulatory timelines.
- Data Visualization:Self-service dashboards democratize insight access across branch networks and executive suites.
- Reporting Software:Automated regulatory filing engines streamline OSFI submission workflows and reduce compliance labor.
The dominant share belongs to Data Warehousing, while Predictive Analytics is closing the gap fastest.
End User:
Customer type determines procurement sophistication, with asset scale dictating in-house capability versus vendor dependency.
- Retail Banks:National branch networks generate massive transaction volumes requiring real-time fraud detection and personalized product recommendations. These institutions anchor demand in Toronto's financial district, compelled by customer expectations for instant digital experiences.
- Commercial Banks:Corporate lending operations deploy sophisticated credit risk models and automated covenant monitoring. Mid-market exposure and syndicated loan participation drive analytics investment across Montreal and Calgary operations.
- Investment Firms:Portfolio construction and algorithmic trading platforms demand ultra-low latency market data processing.
- Credit Unions:Cooperative structures with constrained capital favor subscription-based cloud deployments over infrastructure ownership.
Retail Banks command the largest procurement budgets, though Credit Unions are expanding their analytics footprint most aggressively.
Deployment Model:
Cost tier structures vendor relationships, with capital availability determining build-versus-rent calculus.
- Hybrid:Canadian-sovereign data residency satisfies PIPEDA constraints while preserving burst capacity across border zones. Tier-1 institutions favor this architecture to maintain operational continuity during regulatory examinations.
- Cloud-Based:Subscription consumption eliminates upfront infrastructure expenditure and accelerates time-to-value for mid-tier players. Credit unions bypass decades of technical debt through this route.
- On-Premise:Legacy installations persist where data sovereignty concerns override cost optimization.
- Managed Services:Outsourced operations transfer operational risk to specialized providers.
Hybrid deployments hold the leading position, while Cloud-Based adoption is climbing the fastest among non-tier-1 institutions.
Analytics Type:
Maturity gradients separate retrospective reporting from forward-looking automation, with margin capture potential escalating along this progression.
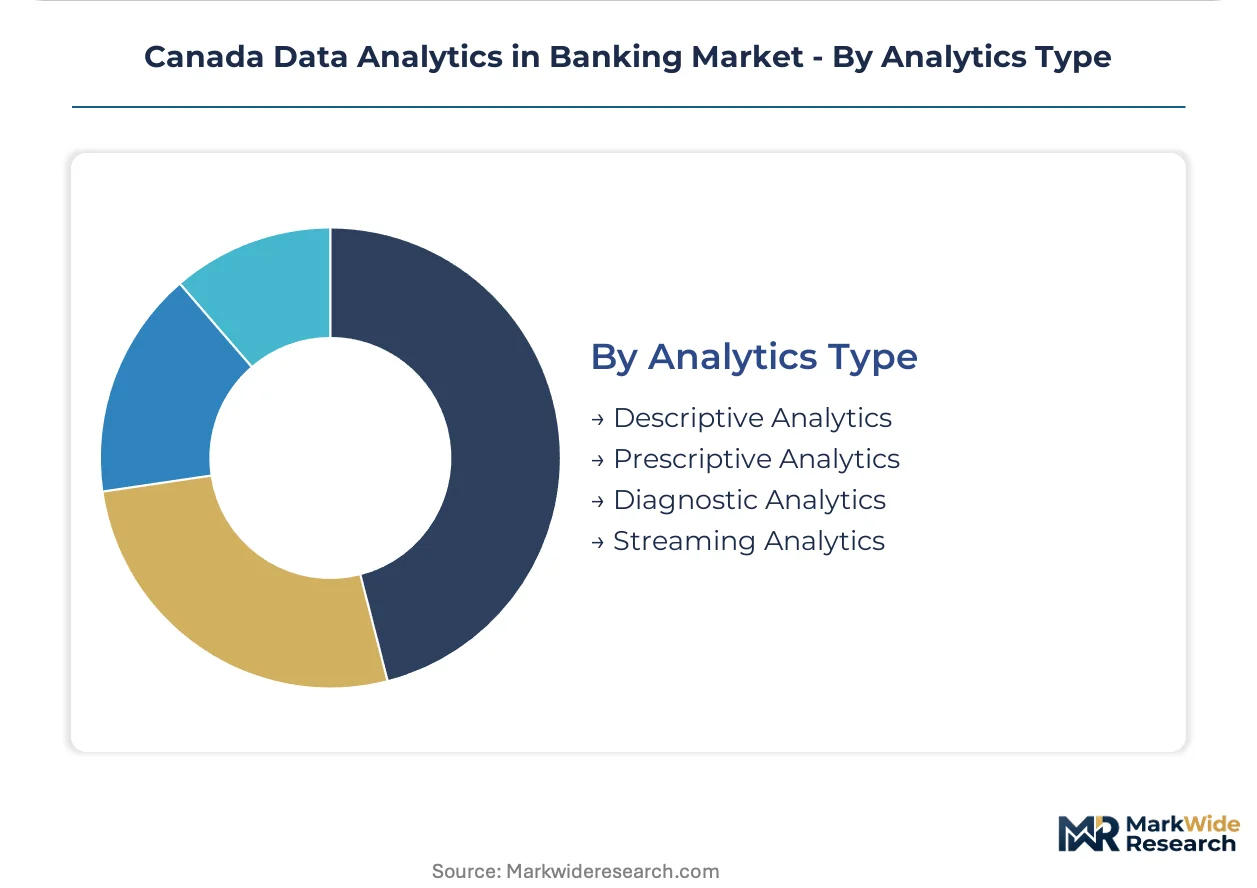
- Prescriptive Analytics:Automated pricing engines and dynamic portfolio rebalancing generate direct revenue impact through optimized capital allocation. Investment firms and commercial banking divisions concentrate adoption here, seeking regulatory capital efficiency.
- Descriptive Analytics:Historical performance aggregation and regulatory reporting remain foundational across all institution types. OSFI submission requirements perpetuate steady demand despite limited differentiation value.
- Diagnostic Analytics:Root-cause investigation tools isolate operational inefficiencies and customer churn drivers.
- Streaming Analytics:Real-time event processing enables immediate fraud intervention and market opportunity capture.
Descriptive Analytics retains the widest installed base, while Prescriptive Analytics is gaining share fastest as automation priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSFI's Guideline B-13 anchors regulatory pressure across Canadian provinces, accelerating infrastructure investment from British Columbia to Atlantic Canada. Provincial privacy commissioners enforce PIPEDA constraints that shape data residency decisions in every regional banking hub.
Ontario
Toronto's financial district concentrates tier-1 bank headquarters driving real-time risk dashboard deployment. OSFI's Toronto office conducts direct regulatory examinations that compress procurement timelines for analytics modernization. The Waterloo-Toronto corridor anchors AI research partnerships between banks and university laboratories.
Quebec
Montreal's AI research institutes supply machine learning talent to Desjardins Group and Bank of Montreal operations. The Autorité des marchés financiers enforces supplementary provincial standards that layer atop federal OSFI requirements. Montreal-Toronto corridor collaboration intensifies as federal research funding converges on bilingual talent pipelines.
Alberta
Calgary's energy-focused commercial banking divisions deploy credit risk models for oil patch lending exposure. The Office of the Privacy Commissioner of Alberta applies PIPEDA-aligned consent protocols that constrain cross-border data flows to US cloud zones. Calgary-Edmonton corridor institutions favor hybrid cloud architectures preserving operational sovereignty.
British Columbia
Vancouver's wealth management platforms generate demand for customer segmentation analytics across Pacific Rim client bases. The Office of the Information and Privacy Commissioner for British Columbia enforces data minimization standards affecting model training datasets. Vancouver fintech clusters supply specialized analytics vendors to regional credit unions.
Atlantic Canada
Halifax and regional credit union networks adopt subscription-based cloud deployments to bypass capital-intensive infrastructure builds. The Office of the Information and Privacy Commissioner of Nova Scotia coordinates with federal privacy frameworks on cross-border consent protocols. Atlantic institutions leverage federal Atlantic Canada Opportunities Agency funding for digital modernization programs.
Canada Data Analytics in Banking Market Competitive Landscape
Domestic banking conglomerates and global technology vendors split the market into vertically integrated and horizontally specialized camps. Tier-1 Canadian banks retain proprietary development capabilities while mid-tier institutions outsource to vendor ecosystems. Strategic archetypes include in-house AI research institutes, hybrid cloud infrastructure providers, and pre-certified compliance platforms. Dominant competitive moves encompass subscription model unbundling and Canadian-sovereign data residency certification.
Among domestic banking conglomerates, Royal Bank of Canada and Toronto-Dominion Bank occupy positions exemplifying proprietary model development strategies. International Business Machines Corp represents the global technology vendor archetype delivering hybrid cloud architectures. These three entities anchor the competitive structure without exhausting the vendor ecosystem.
| Leading Market Players |
|---|
| Royal Bank of Canada |
| Toronto-Dominion Bank |
| Bank of Montreal |
| Canadian Imperial Bank of Commerce |
| Bank of Nova Scotia |
| Desjardins Group |
| International Business Machines Corp |
| Oracle Corp |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
Toronto's financial district concentrates vendor development capacity for banking analytics platforms, compressing delivery timelines for tier-1 institutions while inflating implementation premiums for mid-tier credit unions seeking equivalent capability. This geographic concentration of technical expertise directly shapes procurement cost structures across Canadian banking.
Pricing Analysis
Price spreads between Toronto-based implementations and Atlantic Canada deployments reflect 40-50% differentials driven by specialist labor premiums and proximity to OSFI examination centers. Three-tier pricing structure across enterprise-grade, mid-market, and credit-union tiers dominates, with differentiation anchored in model governance certification depth and data residency assurance levels. Cost compression in mid-market segments is intensifying because cloud-native vendors are unbundling implementation from software subscriptions. Credit unions exhibit highest price sensitivity due to capital constraints, while tier-1 retail banks prioritize compliance-grade premiums over unit cost.
Supply Chain Analysis
Upstream compute infrastructure feeds from United States hyperscaler regions, Canadian sovereign cloud zones, and domestic colocation facilities. Specialized hardware components—GPU clusters for model training, columnar storage arrays, and in-memory processing frameworks—draw from Taiwan semiconductor fabrication, South Korean memory production, and domestic systems integration. Single-source vulnerability concentrates in hyperscaler routing equipment subject to cross-border data flow restrictions. Distribution runs through direct vendor relationships with tier-1 banks, regional systems integrators for mid-tier institutions, and cooperative purchasing consortia serving credit union networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates structural switching costs. OSFI's Guideline B-13 mandates embed vendor relationships through compliance certification dependencies that resist displacement.
For Market Incumbents: Harden proprietary model governance layers to preempt OSFI's evolving explainability standards. Deepen vertical integration into Montreal-Toronto AI corridor talent pipelines to offset machine learning engineer scarcity threatening mid-tier expansion. Vertical integration into cloud infrastructure ownership reduces third-party vendor concentration risk flagged by operational resilience examinations. For New Entrants and Emerging Players: Atlantic Canada credit union networks present the most penetrable white-space target, with subscription-based cloud deployments bypassing capital barriers that constrain incumbent on-premise alternatives. Prescriptive analytics automation for commercial banking divisions offers second-entry pathway, as investment firms seek regulatory capital optimization tools absent from established vendor portfolios. Go-to-market through cooperative purchasing consortia accelerates trust acquisition without direct tier-1 bank competition. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because OSFI's expanding third-party oversight requirements will force architectural redesigns across vendor ecosystems, favoring pre-certified platform providers. Acquisition target archetype: specialized analytics vendors with demonstrated B-13 compliance track records and Canadian-sovereign cloud certifications. Signal to watch is OSFI's operational resilience extension to cloud infrastructure providers, which would trigger consolidation mandates across mid-tier vendor landscapes.| Strategic Initiative | Industry Significance |
|---|---|
| Canadian-Sovereign Cloud Certification | OSFI data residency requirements favor domestic cloud zones over US hyperscaler alternatives. |
| Model Governance Layer Development | Automated drift detection capabilities satisfy B-13 continuous monitoring mandates for tier-1 banks. |
| Credit Union Consortium Partnership | Cooperative purchasing structures bypass individual institution capital constraints for analytics adoption. |
| Prescriptive Analytics Product Launch | Automated pricing engines capture margin pools in commercial banking divisions seeking capital efficiency. |
| Montreal-Toronto AI Corridor Expansion | Federal research funding convergence builds proprietary model capabilities distinct from vendor offerings. |
Research Methodology
Desk research of OSFI regulatory filings, vendor certification disclosures, and provincial privacy commissioner enforcement patterns preceded structured interviews with bank CTOs, credit union technology officers, cloud infrastructure procurement leads, and compliance risk directors. Primary fieldwork across Toronto, Montreal, and Vancouver banking centers combined with secondary validation against SEC 10-K filings from listed technology vendors and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from institutional procurement budget disclosures.
Assumptions held OSFI's Guideline B-13 enforcement trajectory and PIPEDA consent protocol stability fixed across the projection horizon, with variable stress testing applied to third-party cloud provider oversight expansion scenarios. Segmentation dimensions modeled encompass deployment modality, institutional tier, analytics maturity stage, and regional regulatory cluster. CAGRs derived from historical procurement velocity patterns and infrastructure replacement cycle analysis, with specific inputs including cloud subscription growth rates and compliance-driven platform refresh timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global hyperscalers seeking Canadian banking market entry would shift outcomes through pricing disruption. Cross-checking against OSFI examination priority disclosures and provincial privacy commissioner annual reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking Credit Analytics Market
Banking
Commercial Banking Market
Banking
GCC Mobile Banking Market
Banking
South Korea Data Analytics in Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Singapore Data Analytics in Banking Market
Banking
Global IoT in Banking and Financial Services Market
Banking
Banking Maintenance Support and Services Market
Banking
Cybersecurity in Banking Market
Banking
Germany Banking As a Service Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Europe Neobanking Market
Banking
Singapore Neobanking Market
Banking
API Banking Market
Banking
US Banking-As-A-Service Market
Banking
Middle East and Africa Neobanking Market