
 Cloud-Based Core Banking Market | 2026-2036
Cloud-Based Core Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Based Core Banking Market Analysis
Retail banking is rebalancing toward challenger banks and neobanks as primary demand generators for cloud-native core systems. Thought Machine leverages its Vault platform to anchor technology leadership in API-first architectures for tier-one institutions. Fiserv competes through its extensive channel control across North American credit unions and community banks. Mambu specializes in composable banking engines that extend rapid deployment capabilities across emerging market fintechs.
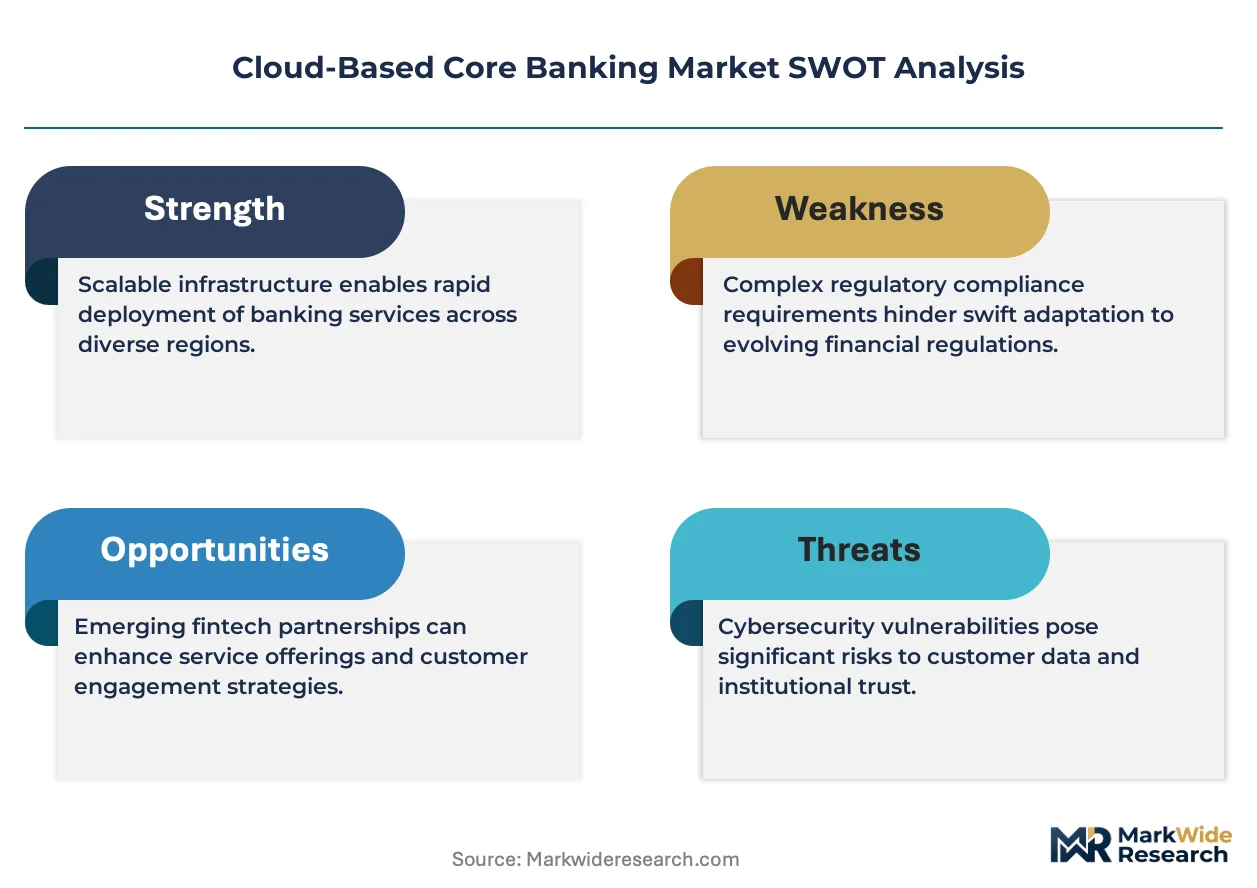
Cloud-based core banking denotes a fully virtualized, API-driven banking infrastructure that replaces on-premise legacy mainframes with elastic compute, microservices architecture, and real-time data processing typically operating at sub-100 millisecond transaction latency. Its primary commercial purpose is enabling financial institutions to launch products iteratively, reduce total cost of ownership, and interoperate with fintech ecosystems through standardized interfaces. Public cloud deployments now dominate greenfield implementations among digital-native challengers, while hybrid cloud configurations capture margin pools at tier-two commercial banks navigating phased migration from legacy COBOL systems. Regulatory compliance solutions within the solution type dimension are accelerating fastest as Basel III finalization and region-specific open banking obligations multiply reporting granularity requirements.
The European Banking Authority's PSD2 and GDPR frameworks, the US Federal Reserve's operational resilience guidance, and Singapore's MAS Technology Risk Management Notice shape product standards by mandating real-time data portability, cross-border encryption protocols, and disaster recovery thresholds that only cloud-native architectures satisfy cost-effectively. India's RBI cloud guidelines and Brazil's Central Bank PIX integration requirements further fragment compliance specifications across deployment jurisdictions. Stakeholders must monitor divergence between prescriptive national cloud sovereignty rules and the unified API standards that interoperability economics demand.
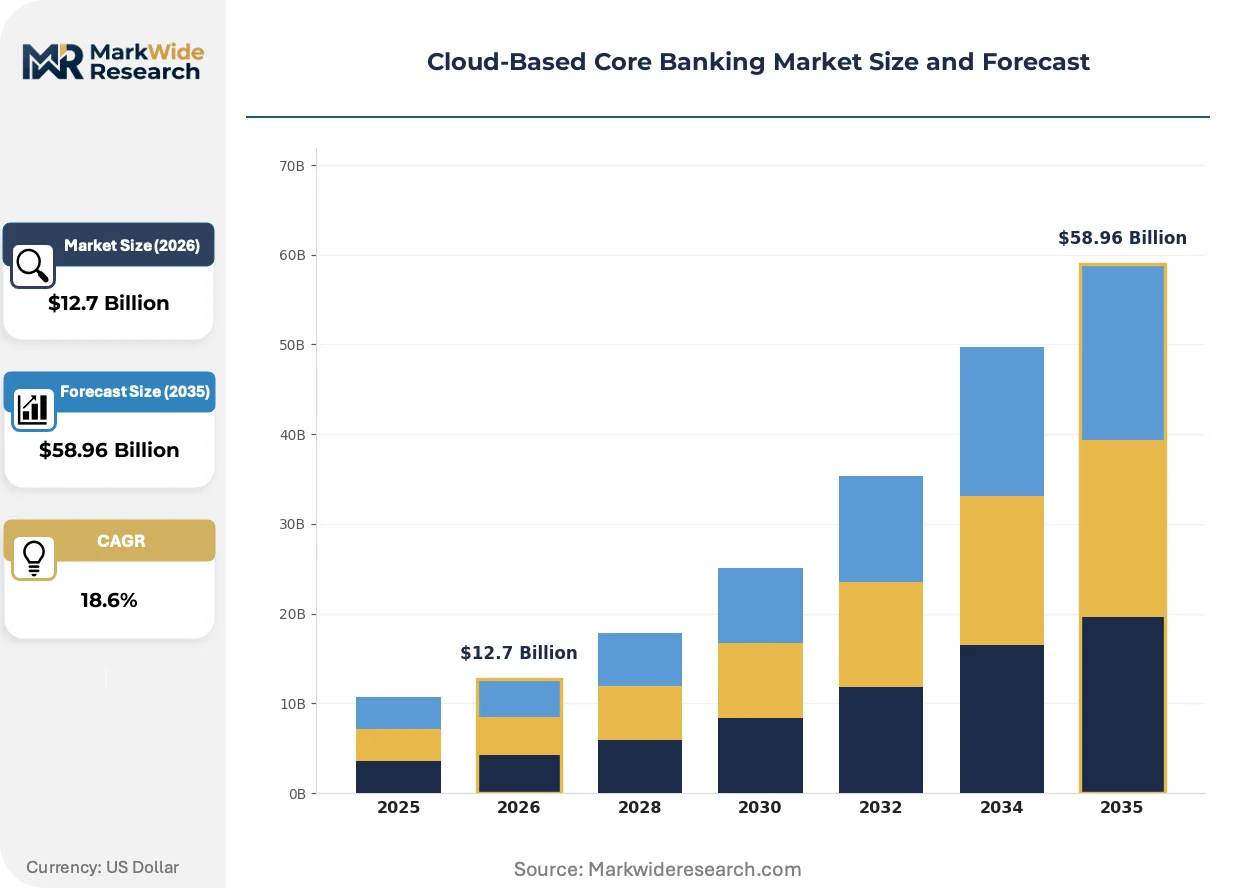
Market Dynamics
Regulatory mandates for real-time data portability and open banking interoperability are forcing wholesale replacement of COBOL-based legacy cores, compressing procurement cycles from multi-year implementations to 12-18 month cloud-native deployments. Tier-one institutions now face existential pressure from neobanks operating on elastic infrastructure with sub-100 millisecond transaction latency.
Growth Catalysts
- PSD2 and GDPR frameworks:The European Banking Authority's mandates require real-time API access and cross-border data portability that only cloud-native architectures satisfy cost-effectively, eliminating on-premise alternatives.
- Regulatory sandboxes in emerging markets:Brazil's Central Bank, Nigeria's SEC, and Indonesia's OJK enable fintechs to launch deposit and payment products without full banking licenses, accelerating greenfield cloud core adoption.
- Microservices architecture:Containerized, API-first banking engines allow product teams to iterate lending and deposit features independently, collapsing time-to-market from quarters to weeks.
Market Restraints
- Data residency requirements:India's RBI cloud guidelines, Singapore's MAS Technology Risk Management Notice, and EU GDPR cross-border encryption rules fragment deployment specifications, forcing costly multi-region infrastructure.
- Legacy system entanglement:Tier-two commercial banks operate hybrid configurations bridging COBOL mainframes to cloud cores, doubling integration complexity and operational risk during migration windows.
- Specialized talent scarcity:Cloud-native core banking requires engineers fluent in distributed systems, event-driven architecture, and financial services compliance, with supply concentrated in London, Singapore, and São Paulo fintech clusters.
Strategic Opportunities
- Basel III finalization:Granular real-time risk reporting requirements multiply demand for cloud-native regulatory compliance modules that ingest transaction streams continuously rather than batch-process overnight.
- PIX and instant payment rails:Brazil's Central Bank instant settlement system and India's UPI network require 24/7 uptime and elastic throughput scaling that legacy cores cannot provision economically.
- Embedded finance convergence:Non-bank platforms in Indonesia and Nigeria are integrating lending, deposits, and payments through Banking-as-a-Service APIs, creating new demand for composable core engines.
Industry Challenges
- Certification timeline compression:Multiple national regulators now require cloud-specific operational resilience audits before production deployment, extending go-live schedules by 6-9 months.
- Legacy integration complexity:Phased migrations from mainframe cores demand specialized middleware for transaction reconciliation, batch processing handoffs, and customer data synchronization across asynchronous systems.
- Disaster recovery threshold escalation:Singapore's MAS and the US Federal Reserve now mandate recovery point objectives under one hour and recovery time objectives under four hours, requiring multi-active cloud configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Based Core Banking Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.96 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Digital Banking Solutions, Payment Processing, Account Management, Regulatory Compliance End User Type: Retail Banks, Commercial Banks, Credit Unions, Challenger Banks Functional Area: Loan Management, Customer Relationship Management, Treasury Management, Core Processing |
| Companies Covered | Thought Machine, Fiserv, Mambu, Oracle FLEXCUBE, Finacle, Finastra, FIS, TCS BaNCS, Temenos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Based Core Banking Market Emerging Trajectories
Cloud-native core banking is converging with embedded finance infrastructure and real-time payment rails, compressing the boundary between traditional banking technology and platform-based financial services. Three structural developments are redefining competitive positioning.
Event-driven architecture using Apache Kafka and cloud-native streaming platforms is integrating real-time transaction processing with risk scoring and fraud detection pipelines. Tier-one institutions in London and Singapore are deploying these stacks to achieve sub-100 millisecond latency for instant payment settlements. This technology is integrating previously siloed core banking, payments, and compliance functions into unified data streams, eliminating overnight batch windows.
The EU AI Act and GDPR Article 22 automated decision-making provisions are mandating explainability in credit underwriting algorithms deployed on cloud cores. Banks must now maintain audit trails for machine learning model versions and feature drift. European challengers and neobanks are responding by investing in MLOps pipelines with built-in regulatory documentation, while US institutions await similar federal guidance from the CFPB.
Buyers are consolidating vendor relationships around full-stack cloud core providers rather than assembling best-of-breed components. Procurement teams at Southeast Asian retail banks now favor single-platform contracts covering ledger, payments, and regulatory reporting over multi-vendor integrations. This concentration is most visible in Indonesia and Vietnam, where tier-two institutions lack engineering bandwidth to manage fragmented technology stacks.
Cloud-Based Core Banking Market Segmentation
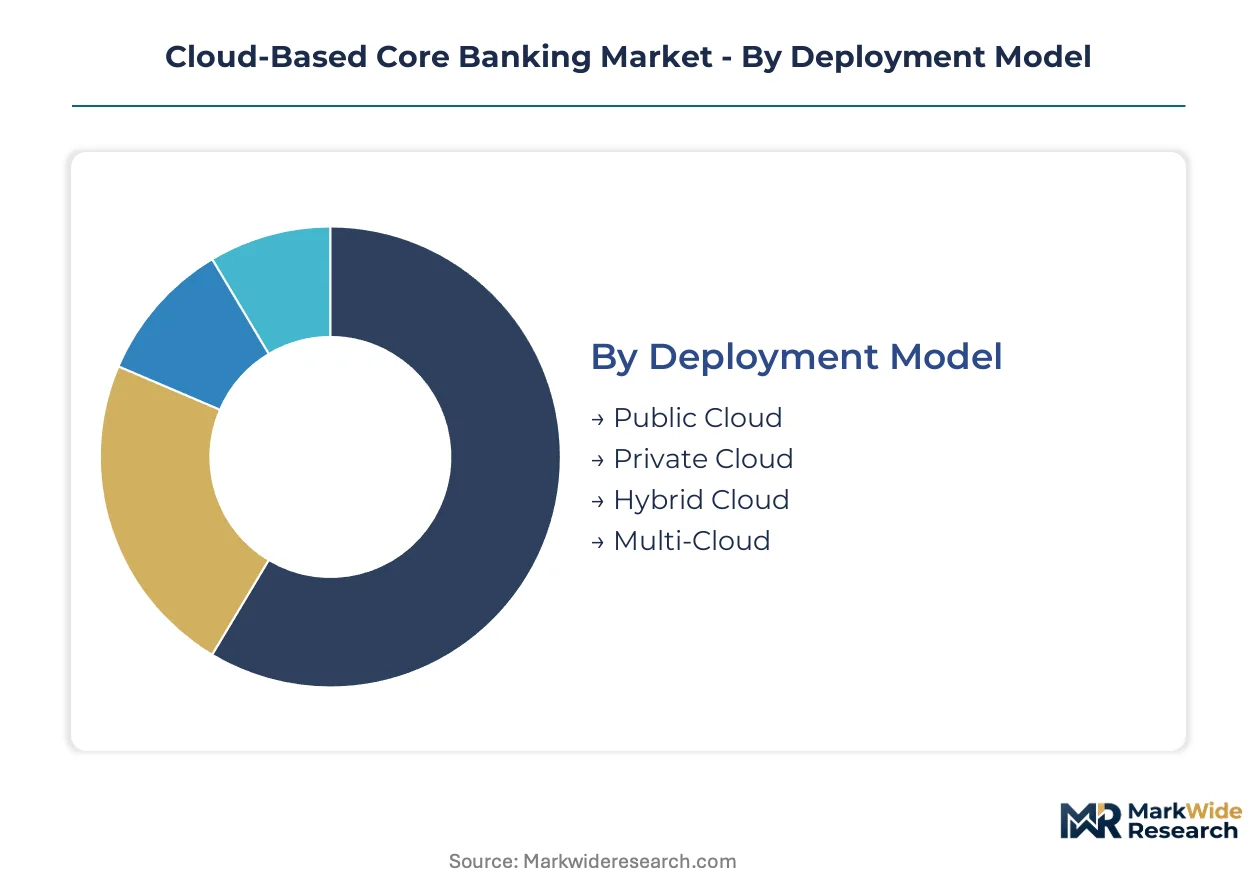
Cloud-based core banking architectures fragment across deployment configurations, regulatory use cases, and institutional buyer profiles. Each segmentation dimension carries distinct margin structures and vendor specialization patterns that determine competitive positioning.
Deployment Model:
Supply concentration in public cloud hyperscalers has compressed infrastructure provisioning costs while fragmenting vendor control over data sovereignty compliance.
- Public Cloud:Fully virtualized infrastructure operated by third-party hyperscalers with elastic compute scaling and pay-per-transaction economics. Challenger banks in Brazil and Indonesia concentrate procurement here, driven by zero capital expenditure requirements and instant payment rail integration demands.
- Private Cloud:Dedicated single-tenant infrastructure with isolated compute resources and custom encryption key management. Tier-one retail banks in Singapore and Germany deploy this model, constrained by MAS Technology Risk Management Notice and GDPR cross-border data localization mandates.
- Hybrid Cloud:Bridged architecture connecting on-premise legacy mainframes to cloud-native microservices through API gateways. Commercial banks navigating phased COBOL migration dominate this segment, facing doubled integration complexity during transition windows.
- Multi-Cloud:Distributed workload placement across two or more hyperscaler environments with automated failover orchestration. This configuration addresses disaster recovery thresholds under four hours mandated by the US Federal Reserve and Singapore's MAS.
Public Cloud absorbs the bulk of installed capacity among greenfield digital-native banks; Multi-Cloud is expanding most quickly as regulatory resilience requirements harden.
Solution Type:
Cost tier differentiation separates modular point solutions from integrated full-stack platforms, with compliance modules commanding premium pricing.
- Digital Banking Solutions:Customer-facing mobile and web interfaces with embedded onboarding, transaction history, and self-service product origination. Neobanks in Nigeria and Indonesia prioritize these for rapid market entry through regulatory sandboxes.
- Payment Processing:Real-time transaction routing engines with sub-100 millisecond latency for instant settlement rails. Demand concentrates where Brazil's Central Bank PIX and India's UPI networks require 24/7 elastic throughput scaling.
- Account Management:Core ledger functions spanning deposit products, interest calculation, and statement generation. Credit unions and community banks in North America represent the primary buyer base, migrating from legacy core processors.
- Regulatory Compliance:Continuous risk monitoring, automated reporting pipelines, and audit trail maintenance for Basel III and open banking obligations. This segment climbs the fastest as real-time granular reporting replaces overnight batch processing.
Digital Banking Solutions capture the largest revenue pool; Regulatory Compliance demonstrates the steepest expansion trajectory as supervisory frameworks multiply data granularity requirements.
End User Type:
Customer type determines implementation complexity, with incumbent institutions demanding phased migration support that elongates sales cycles.
- Retail Banks:Full-service consumer deposit and lending institutions with branch networks and established compliance operations. Southeast Asian institutions accelerate procurement here, replacing legacy infrastructure under PSD2 and open banking mandates.
- Commercial Banks:Corporate-focused institutions with treasury services, trade finance, and complex multi-entity account structures. These buyers require specialized middleware for batch processing handoffs during hybrid cloud transitions.
- Credit Unions:Member-owned cooperative financial institutions with constrained IT budgets and shared service arrangements. North American credit unions concentrate demand through Fiserv channel partnerships and community bank technology consortia.
- Challenger Banks:Digital-native institutions operating without legacy mainframe baggage and API-first from inception. These buyers in Brazil, Nigeria, and Indonesia represent the fastest-growing procurement segment, launching through regulatory sandboxes without full banking licenses.
Retail Banks retain the dominant share of legacy replacement spending; Challenger Banks are gaining share fastest as greenfield licensing accelerates in emerging markets.
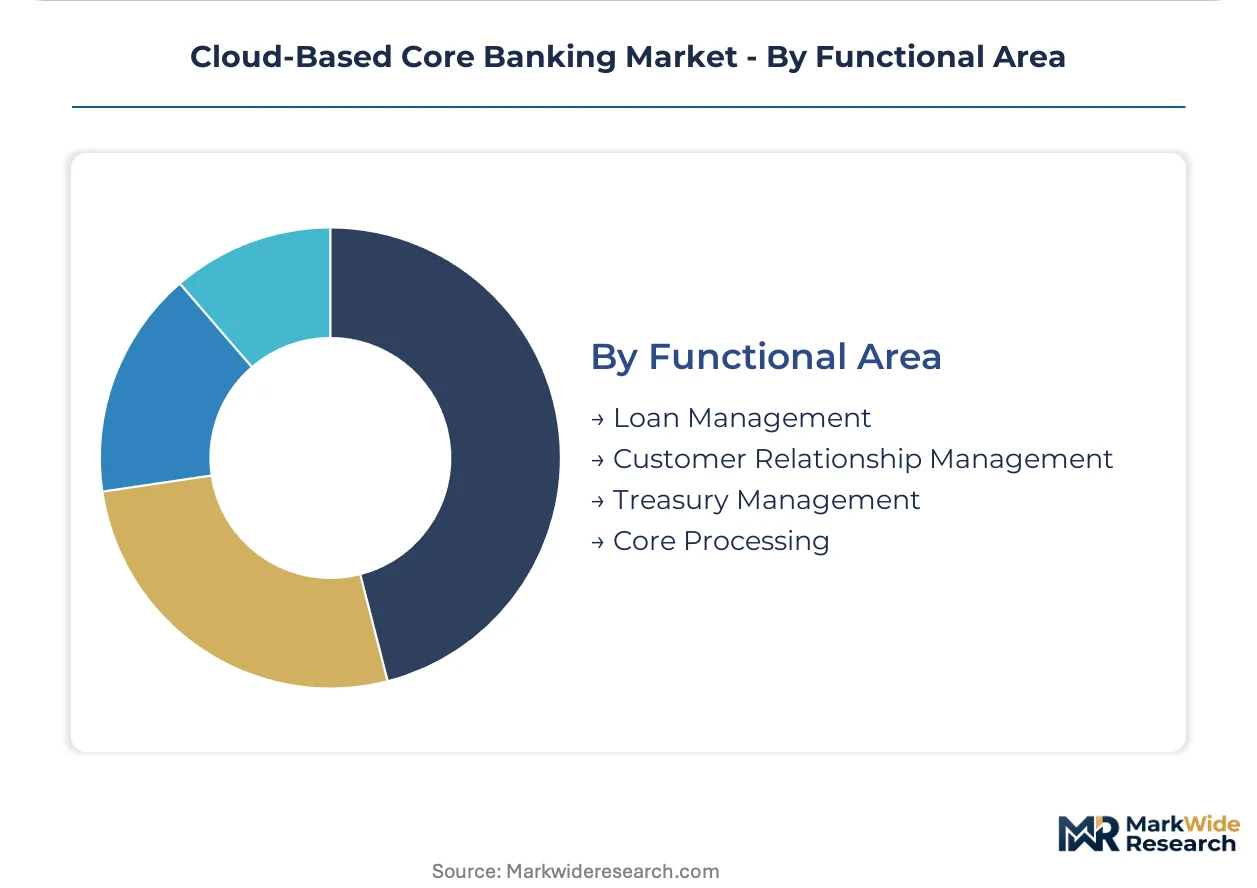
Functional Area:
Volume concentration in core processing and loan management has attracted the deepest vendor specialization and most mature API ecosystems.
- Loan Management:End-to-end credit origination, underwriting workflow, servicing, and collections automation. Embedded finance platforms in Indonesia and Nigeria integrate these functions through Banking-as-a-Service APIs for non-bank lenders.
- Customer Relationship Management:Unified customer data platforms with 360-degree views, interaction history, and personalized product recommendations. Tier-one institutions deploy these stacks to compete with neobank customer experience benchmarks.
- Treasury Management:Liquidity forecasting, cash positioning, and multi-currency exposure management for corporate clients. Commercial banks in London and Singapore concentrate investment here, driven by real-time FX volatility monitoring requirements.
- Core Processing:Foundational transaction posting, balance maintenance, and general ledger reconciliation engines. This functional area commands the largest technology budgets as it constitutes the irreplaceable center of banking operations.
Core Processing absorbs the bulk of technology spending; Loan Management is expanding most quickly as embedded finance convergence creates new distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay Financial Centre tax incentive zone concentrates cloud banking R&D investment, drawing tier-one institutions seeking regulatory sandbox access alongside established compliance frameworks.
United States
Community banks and credit unions drive procurement of hybrid cloud cores as they migrate from legacy Fiserv and FIS platforms. The Federal Reserve's operational resilience guidance mandates recovery time objectives under four hours, forcing multi-active cloud configurations. New York and San Francisco fintech clusters host the deepest engineering talent pools for distributed systems architecture.
United Kingdom
Challenger banks and neobanks dominate greenfield cloud core adoption, leveraging API-first infrastructures for rapid product iteration. The Financial Conduct Authority's open banking rules and PSD2 implementation require real-time data portability that only cloud-native systems satisfy cost-effectively. London's fintech corridor anchors European demand concentration for event-driven banking architectures.
Singapore
Tier-one retail banks accelerate phased migration from legacy mainframes under MAS Technology Risk Management Notice requirements. The central bank's regulatory sandbox enables fintechs to test deposit and payment products without full banking licenses. Marina Bay and Raffles Place financial districts host concentrated vendor implementation teams serving Southeast Asian expansion.
Brazil
Neobanks and digital challengers represent the fastest-growing procurement segment, launching through Central Bank regulatory sandboxes without legacy infrastructure baggage. PIX instant payment rail integration demands 24/7 elastic throughput scaling unavailable from COBOL-based cores. São Paulo's Vila Olímpia fintech cluster concentrates cloud-native engineering talent and vendor presales operations.
Germany
Sparkassen and cooperative banks navigate phased core replacement under ECB pressure for real-time payment readiness and PSD2 compliance. BaFin supervision of outsourcing arrangements shapes vendor selection criteria for cloud-specific operational resilience audits. Frankfurt's financial district hosts concentrated procurement decision-making for DACH-region cloud core deployments.
Cloud-Based Core Banking Market Vendor Landscape
Top-tier vendors anchor tier-one retail bank transformations, while mid-tier specialists capture emerging market neobank procurement through regulatory sandbox channels. The vendor base stratifies across three archetypes: full-stack platform providers, composable banking engine specialists, and legacy processor incumbents with cloud migration toolkits. Consolidation pressure intensifies as buyers favor single-platform contracts over multi-vendor integration complexity. Strategic moves concentrate on geographic expansion into regulatory sandbox markets and technology licensing partnerships with hyperscale cloud providers.
Within the API-first architecture tier, Thought Machine and Mambu exemplify divergent positioning strategies. Thought Machine occupies a position among vendors targeting tier-one institutions with vault-grade ledger infrastructure, while Mambu represents the composable banking engine archetype serving rapid-deployment fintechs in Brazil, Nigeria, and Indonesia. Fiserv anchors the incumbent processor segment, leveraging channel control across North American credit unions and community banks during hybrid cloud transition windows. These three vendors collectively illustrate how competitive positioning fragments across institutional buyer profiles and geographic deployment contexts.
| Leading Market Players |
|---|
| Thought Machine |
| Fiserv |
| Mambu |
| Oracle FLEXCUBE |
| Finacle |
| Finastra |
| FIS |
| TCS BaNCS |
| Temenos |
| Others |
Supply Flow & Price Mechanics
Captive hyperscaler partnerships anchor supply positioning and pricing power for cloud-native core banking vendors, with AWS, Azure, and GCP commitments determining infrastructure cost pass-through and margin retention across deployment models.
Pricing Analysis
Short lead-time premiums dominate vendor pricing, with 12-18 month deployment contracts commanding 15-25% markups over standard 24-month implementation schedules. Three-tier pricing structure across premium, standard, and economy levels segments buyers by regulatory complexity tier and customization depth. Pricing pressure stems from hyperscaler commoditization of base compute, compressing infrastructure margins. Challenger banks in Brazil and Nigeria exhibit highest price sensitivity, while tier-one institutions in Singapore and Germany absorb premium pricing for private cloud isolation and dedicated encryption key management.
Supply Chain Analysis
India's RBI cloud data localization mandates and Singapore's MAS Technology Risk Management Notice reshape hyperscaler sourcing, forcing multi-region infrastructure buildouts. Engineering talent concentrates in São Paulo, London, and Singapore fintech clusters, with distributed systems specialists commanding scarcity premiums. Raw material dependencies center on semiconductor availability for edge computing nodes, hyperscaler data center capacity reservations, and specialized financial services compliance middleware. Single-source vulnerability runs through AWS's dominance in challenger bank greenfield deployments. Distribution runs through direct enterprise sales teams for tier-one institutions and channel partnerships with systems integrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into regulatory compliance modules represents the decisive competitive race, with vendors capturing upstream documentation automation and downstream audit trail maintenance commanding sustainable margin positions.
For Market Incumbents: Cement channel control across North American credit unions through Fiserv-style shared service arrangements, insulating against Mambu's composable engine encroachment. Deepen in-house production of Basel III real-time risk reporting modules to offset margin compression in core ledger licensing. Prioritize certification investment for Singapore MAS and US Federal Reserve operational resilience audits to extend procurement cycle lock-in. For New Entrants and Emerging Players: Begin with regulatory sandbox deployments in Indonesia and Vietnam, where tier-two institutions lack engineering bandwidth for multi-vendor integration. Target white-space in hybrid cloud middleware for COBOL-to-microservices reconciliation, the most underserved migration pain point. Lead go-to-market with Banking-as-a-Service API bundles for embedded finance platforms in Nigeria's non-bank lending sector. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler strategic partnerships and tier-one bank technology subsidiary carve-outs. Long-term viability hinges on regulatory compliance module attach rates exceeding core licensing revenue. Monitor Brazil Central Bank PIX integration certification timelines as the critical inflection signal for emerging market vendor viability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Module Development | Captures Basel III real-time reporting demand that legacy batch systems cannot satisfy. |
| Hyperscaler Strategic Partnership | Locks in infrastructure cost advantages for AWS, Azure, and GCP deployment options. |
| Embedded Finance API Platform Launch | Opens distribution through Indonesia and Nigeria non-bank lending platforms. |
| COBOL Migration Middleware Acquisition | Addresses hybrid cloud transaction reconciliation complexity for tier-two commercial banks. |
| Multi-Cloud Disaster Recovery Certification | Meets Singapore MAS and US Federal Reserve sub-four-hour recovery time objectives. |
Methodological Framework
Multi-period observation of vendor implementation timelines, regulatory certification completion rates, and hyperscaler partnership announcements anchored the trend analysis, supplemented by interviews with cloud core banking CTOs, central bank sandbox administrators, tier-one bank transformation officers, and fintech engineering leads. Secondary validation drew from SEC 10-K filings of publicly traded processors, EBA PSD2 implementation reports, MAS Technology Risk Management Notice guidance documents, and Brazil Central Bank PIX integration statistics. Bottom-up procurement cycle analysis triangulated against top-down market sizing from deployment model segmentation.
Segment-weighting across deployment model, solution type, end user archetype, and functional area dimensions determined value allocation throughout the forecast period. CAGRs derived from elasticity modeling of procurement cycle compression and regulatory mandate acceleration curves. Industry-specific inputs included real-time payment rail integration velocity and open banking API adoption thresholds.
Regulatory timeline delays, hyperscaler capacity constraints, and legacy system entanglement complexity are the dominant revision risks to deployment assumptions. Forecasts reflect documented scenario parameters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Retail Core Banking Systems Market
Banking
AI and Automation in Banking Market
Banking
Commercial Banking Market
Banking
Credit Intermediation Market
Banking
Latin America Banking As a Service Market
Banking
Canada Data Analytics in Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Smart Machines in Banking Market
Banking
Disaster Recovery in Banking Market
Banking
Payment Bank Solutions Market
Banking
UK Retail Banking Market
Banking
Corporate Digital Banking Market
Banking
South Korea Data Analytics in Banking Market
Banking
US Commercial Banking Market
Banking
Global Certificate of Deposit Market
Banking
Asia-Pacific Challenger Banks Market