
 Electrolyte Beer Market | 2026-2036
Electrolyte Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolyte Beer Market Analytics
Health-conscious consumer purchasing is consolidating around athletic and fitness-oriented buyer segments. Athletic Brewing Company specializes in non-alcoholic electrolyte formulations that target post-workout recovery occasions. Anheuser-Busch InBev leverages its distribution infrastructure to extend electrolyte-enhanced variants into mainstream retail channels. Heineken competes through premium positioning of functional beer alternatives in European markets.
Electrolyte beer denotes a functional beverage category combining traditional brewing inputs with replenishment minerals formulated for hydration support. Sodium and potassium salts integrate into fermentation or post-fermentation processes, yielding products with electrolytic conductivity measured in milliequivalents per liter. Non-alcoholic beer and craft beer segments lead current volume, while hard seltzer variants capture expanding shelf space in specialty stores and online retail channels. Magnesium and calcium components command premium positioning among endurance athlete customer types, where mineral bioavailability drives repeat purchase behavior.
The FDA governs nutrient content claims and GRAS status for added electrolytes in malt beverages sold in the United States. EFSA health claim regulations in Europe restrict specific hydration and recovery assertions, forcing reformulation of marketing language across export portfolios. Japan's Ministry of Health, Labour and Welfare maintains distinct FOSHU approval pathways for functional beer products, creating compliance complexity for multinational brewers. Stakeholders must monitor evolving mineral additive thresholds and adapt labeling strategies to preempt regulatory friction in priority markets.
Market Dynamics
Functional beverage regulation is fragmenting across jurisdictions, forcing brewers to maintain parallel formulation portfolios and labeling systems that multiply compliance overhead without corresponding revenue premiums.
Growth Catalysts
- FOSHU Pathway Expansion:Japan's Ministry of Health, Labour and Welfare is streamlining functional food approvals, reducing time-to-market for mineral-enhanced malt beverages targeting endurance athletes.
- Post-Workout Consumption Rituals:Fitness enthusiasts in Germany and the United States are substituting traditional sports drinks with electrolyte beer during recovery windows, expanding occasion-based demand.
- Precision Fermentation:Bioavailability-optimized mineral integration during brewing is improving electrolyte retention without flavor degradation, solving a core technical barrier.
Market Restraints
- Input Cost Volatility:Magnesium and potassium salt prices fluctuate with agricultural fertilizer demand, compressing margins on premium formulations.
- Supply Concentration Risk:Specialty yeast strains for low-alcohol electrolyte beer concentrate among three European suppliers, creating vulnerability.
- Regulatory Friction:EFSA health claim restrictions prevent explicit hydration messaging in EU markets, limiting marketing differentiation against conventional sports nutrition.
Strategic Opportunities
- Underpenetrated Markets:Brazil's ANVISA is developing functional beverage frameworks that would enable first-mover positioning in South America's largest beer market.
- Direct-to-Consumer Channels:Subscription models for personalized electrolyte formulations bypass retail slotting fees and capture recurring revenue.
- Technology Convergence:Wearable hydration sensors paired with NFC-enabled packaging create data-linked consumption experiences for triathletes and marathon runners.
Industry Challenges
- Formulation Talent Scarcity:Brewers compete with pharmaceutical and sports nutrition firms for food scientists skilled in mineral bioavailability optimization.
- Dual Certification Timelines:Simultaneous FDA GRAS petitions and EFSA novel food approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolyte Beer Market |
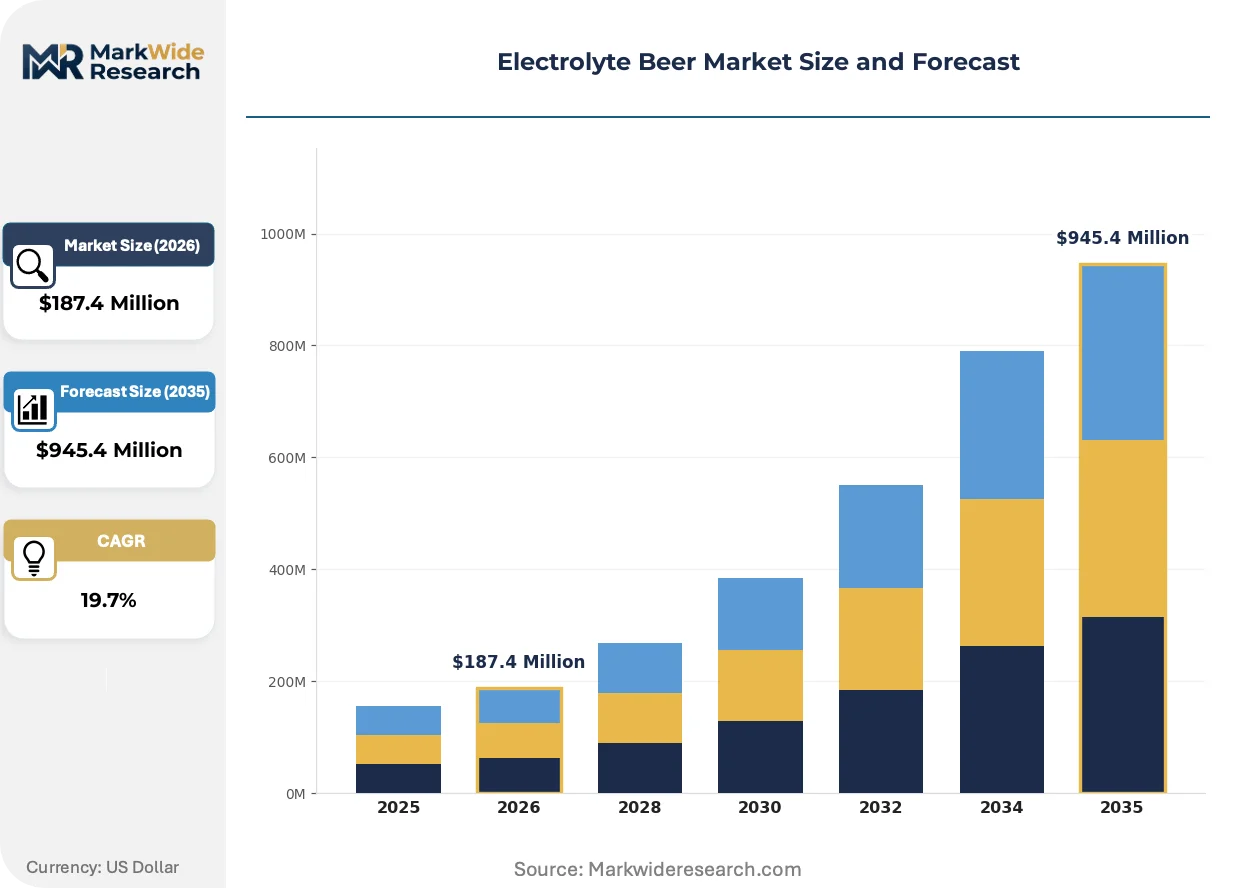
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Beer, Light Beer, Hard Seltzer, Non-Alcoholic Beer Component: Sodium, Potassium, Magnesium, Calcium Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Bars Customer Type: Health-Conscious Consumers, Athletes, Fitness Enthusiasts, Casual Drinkers |
| Companies Covered | Anheuser-Busch InBev, Molson Coors Beverage Company, Heineken, Asahi Group Holdings, Kirin Holdings Company, Athletic Brewing Company, Carlsberg Group, Constellation Brands, Suntory Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolyte Beer Market Evolving Landscape
Electrolyte beer innovation is converging on precision mineral delivery systems and regulatory-adaptive marketing frameworks that separate technical formulation from consumer-facing claims.
Continuous fermentation monitoring is automating real-time electrolyte dosing adjustments during production. Craft breweries in Oregon and Bavaria deploy these systems to maintain mineral consistency across small batches. This technology is automating quality control labor while enabling customization for regional taste preferences.
EFSA's 2023 guidance on implied health claims is forcing reformulation of packaging language across export portfolios. Brewers must strip recovery and hydration terminology from EU labels while retaining functional benefits through ingredient transparency. German and Dutch markets show the strongest compliance-driven packaging redesign activity.
Endurance athletes are consolidating purchasing through specialty running and cycling retailers rather than conventional liquor channels. These shops bundle electrolyte beer with training gear and nutrition plans, displacing supermarket volume. This pattern is most pronounced in Colorado, Tokyo's Setagaya ward, and Melbourne's inner suburbs.
Electrolyte Beer Market Segmentation
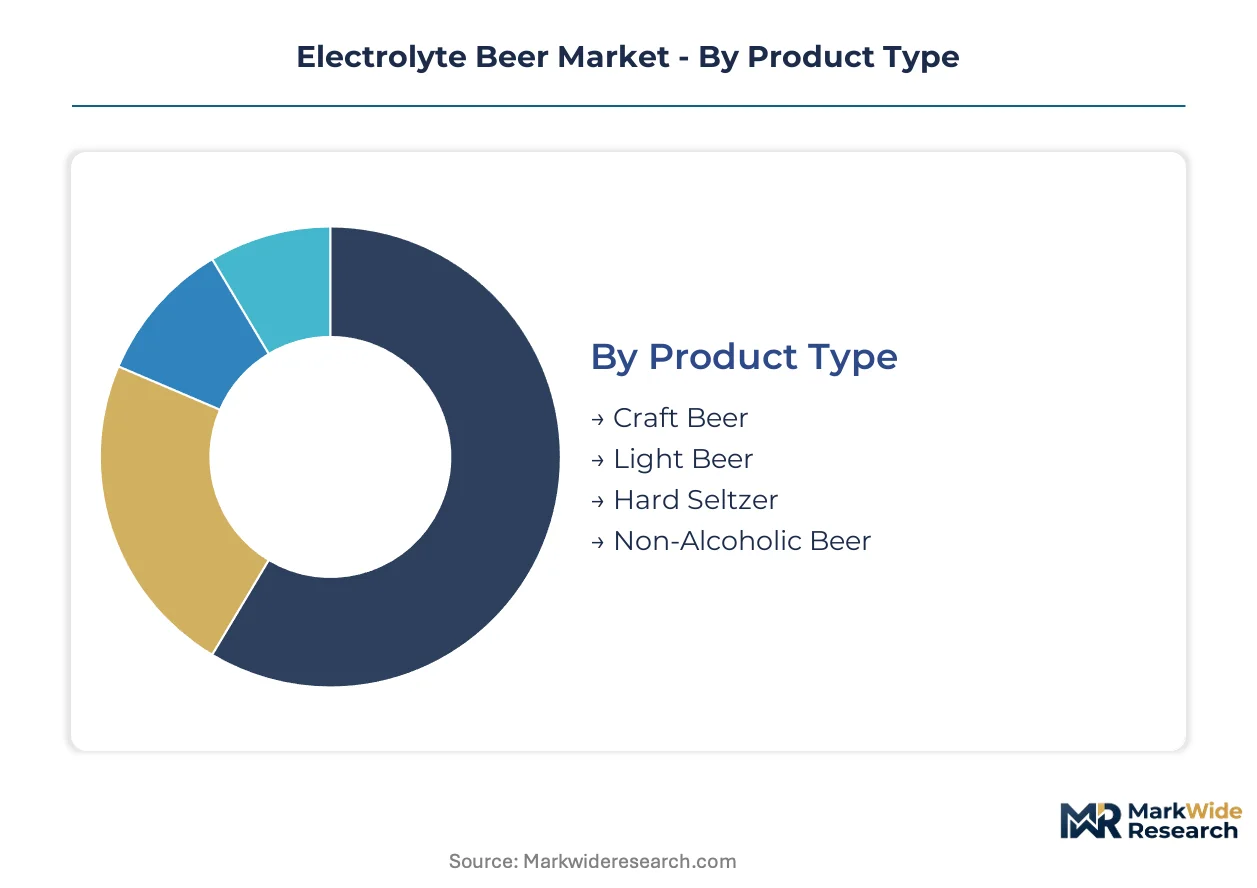
Electrolyte beer segmentation reflects divergent consumption occasions and mineral formulation priorities across buyer types. Product architecture, mineral composition, channel access, and user motivation each create distinct competitive battlegrounds requiring tailored positioning strategies.
Product Type:
Purchase decisions pivot on alcohol tolerance thresholds and occasion formality, separating recovery-focused consumption from social drinking contexts.
- Craft Beer:Small-batch production enables experimental mineral profiles with localized ingredient sourcing. Demand clusters in Oregon, Bavaria, and Colorado where brewery taprooms double as post-activity recovery venues for trail runners and cyclists.
- Non-Alcoholic Beer:Fermentation-arrested or dealcoholized bases carry sodium and potassium loads without ethanol interference, making these formulations suitable for mid-event hydration during ultramarathons and century rides. German and Japanese consumers show strongest repeat purchase behavior here.
- Hard Seltzer:Clear, low-calorie carriers allow precise electrolyte titration with minimal flavor masking requirements.
- Light Beer:Mass-market volume platforms with reduced alcohol and carbohydrate content accommodate mineral fortification at scale.
Volume sits with Light Beer; growth tilts toward Non-Alcoholic Beer.
Component:
Mineral selection follows sweat-loss profiling and bioavailability science, with endurance athletes prioritizing magnesium and calcium for cramp prevention.
- Magnesium:Chelated forms at 50-100mg per serving support muscle relaxation and ATP regeneration without the laxative effect of oxide variants. Triathletes and marathoners in Germany and Japan drive premium pricing tolerance for this component.
- Sodium:Chloride and citrate salts at 200-400mg per can replace sweat losses most directly, forming the baseline formulation for all commercial products. Standard sports-recovery applications across United States and European markets depend on this mineral.
- Potassium:Citrate and phosphate buffers maintain cellular membrane potential and acid-base balance during prolonged exertion.
- Calcium:Lactate and carbonate forms address bone density concerns among masters-age athletes.
Formulation standards center on Sodium; premium differentiation climbs fastest with Magnesium.
Distribution Channel:
Channel selection determines margin structure and consumer education depth, with specialty retailers enabling bundled training-advice sales.
- Specialty Stores:Running and cycling shops in Tokyo's Setagaya ward, Melbourne's inner suburbs, and Boulder, Colorado bundle electrolyte beer with gait analysis and nutrition planning. Staff certification in sports nutrition creates trust transfer that supermarkets cannot replicate.
- Online Retailers:Direct-to-consumer subscriptions capture recurring revenue with personalized mineral formulations based on sweat-testing data. United States and German consumers show highest subscription conversion rates.
- Supermarkets:Mass-market penetration depends on shelf-stable packaging and clear regulatory labeling for grab-and-go purchase.
- Bars:On-premise trial occasions introduce casual drinkers to functional positioning through draft variants.
Transaction volume flows through Supermarkets; customer lifetime value peaks with Online Retailers.
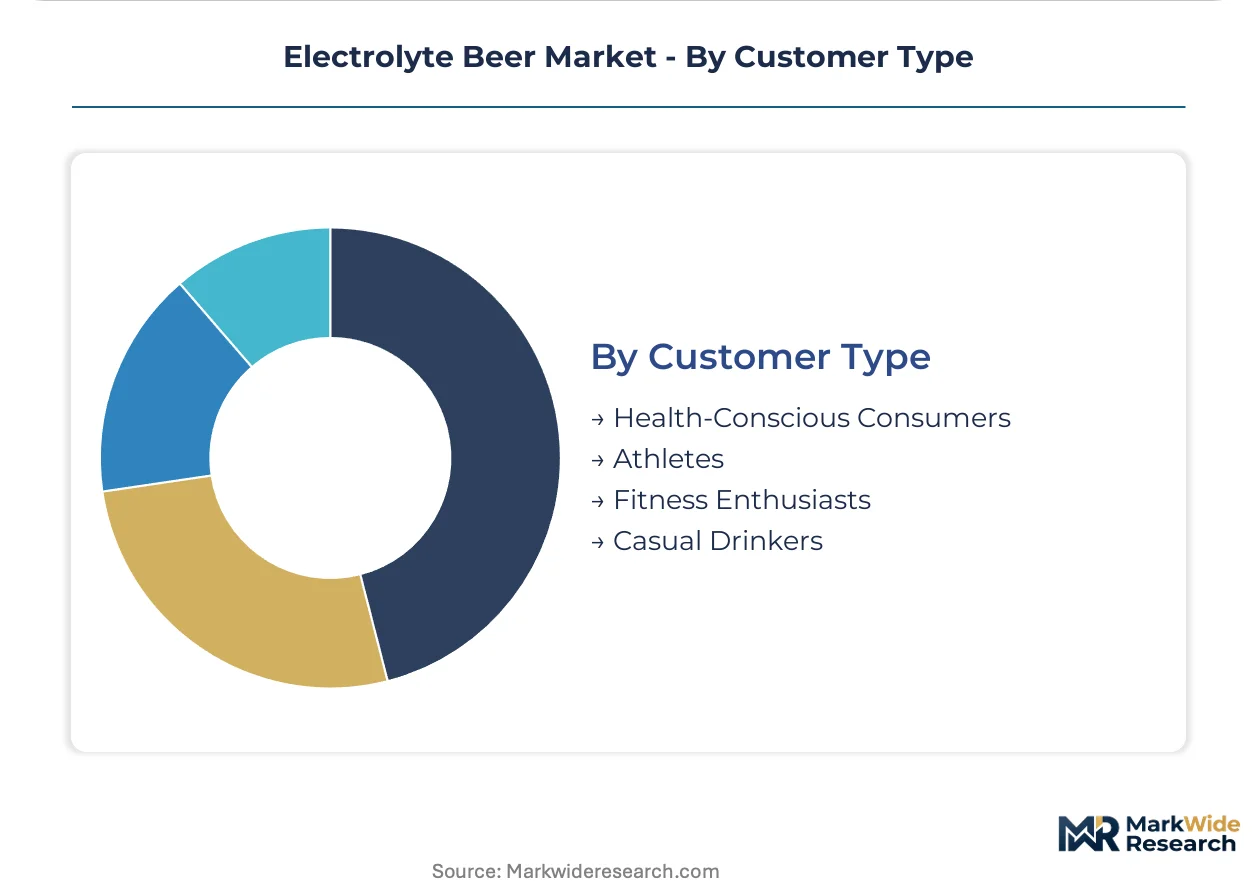
Customer Type:
User motivation separates performance-optimization buyers from wellness-curious experimenters, with distinct price elasticity and loyalty patterns.
- Fitness Enthusiasts:Regular gym-goers and weekend warriors seek post-workout recovery rituals without alcohol impairment. This segment concentrates in United States urban markets and German fitness-studio corridors, purchasing 2-3 times weekly.
- Athletes:Competitive endurance specialists demand batch-tested mineral content with third-party certification. Ironman and ultramarathon communities in Japan, Germany, and Colorado sustain premium pricing for FOSHU-approved or NSF-certified products.
- Health-Conscious Consumers:Wellness-oriented buyers prioritize clean-label ingredients and moderate alcohol content.
- Casual Drinkers:Occasion-driven purchasers respond to novelty positioning and social media visibility.
Population scale favors Health-Conscious Consumers; revenue per user climbs steepest among Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand for electrolyte beer concentrates in the United States, Germany, and Japan, where fitness culture and functional beverage acceptance intersect most strongly. Regulatory frameworks diverge sharply across these markets, forcing brewers to maintain parallel compliance portfolios. Urban clusters with endurance sports communities drive disproportionate volume.
United States
Post-workout recovery rituals among CrossFit practitioners and marathon runners sustain weekly purchase frequencies of 2-3 cans per enthusiast. The FDA governs GRAS status for sodium and potassium additives in malt beverages, requiring pre-market notification for novel mineral concentrations. Boulder, Colorado and Portland, Oregon anchor craft brewery taprooms that double as trailhead recovery venues for cyclists and trail runners.
Germany
Fitness-studio corridors in Berlin and Munich generate repeat purchases of non-alcoholic electrolyte variants for post-gym consumption without ethanol impairment. EFSA health claim restrictions prevent explicit hydration messaging on packaging, forcing reformulation of marketing language toward ingredient transparency. Bavaria's small-batch breweries deploy continuous fermentation monitoring to maintain mineral consistency across experimental regional formulations.
Japan
Endurance athletes in Tokyo's Setagaya ward and Osaka's Kansai region sustain premium pricing for FOSHU-approved products with batch-tested mineral content. The Ministry of Health, Labour and Welfare maintains distinct approval pathways for functional beer, creating compliance complexity for multinational entrants. Specialty running shops in Setagaya bundle electrolyte beer with gait analysis and nutrition planning, displacing supermarket volume.
Australia
Triathlon communities in Melbourne's inner suburbs and Sydney's eastern beaches consolidate purchasing through specialty cycling retailers rather than liquor channels. The Therapeutic Goods Administration (TGA) oversees borderline functional beverage claims, creating uncertainty for hydration-focused marketing. Melbourne's craft brewing precincts experiment with magnesium-chelated formulations targeting cramp prevention among masters-age athletes.
Brazil
Health-conscious consumers in São Paulo's fitness-studio corridors and Rio de Janeiro's beach athletic communities represent nascent demand for functional beer alternatives. ANVISA is developing functional beverage regulatory frameworks that would enable first-mover positioning in South America's largest beer market. São Paulo's emerging craft brewery clusters pilot mineral-enhanced formulations awaiting formal approval pathways.
Electrolyte Beer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue non-alcoholic and craft positioning to capture fitness-oriented occasions. The market exhibits moderate consolidation around multinational brewers with distribution infrastructure, while specialty players carve defended niches in premium mineral formulations. Three archetypes dominate: legacy brewers extending functional variants through existing retail networks; craft specialists building direct-to-consumer subscription models; and non-alcoholic pure-plays targeting endurance athletes with FOSHU or NSF certifications. Competitive moves center on portfolio diversification into electrolyte variants and strategic partnerships with specialty sports retailers.
Within the multinational tier, Anheuser-Busch InBev and Heineken exemplify legacy brewers leveraging distribution scale to extend electrolyte-enhanced variants into mainstream channels. Athletic Brewing Company occupies a specialist position, representing the non-alcoholic pure-play archetype that targets post-workout recovery occasions with mineral-optimized formulations. These three anchors illustrate divergent strategic paths: infrastructure-driven mass-market penetration versus niche premium positioning through certification and occasion-specific marketing.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Molson Coors Beverage Company |
| Heineken |
| Asahi Group Holdings |
| Kirin Holdings Company |
| Athletic Brewing Company |
| Carlsberg Group |
| Constellation Brands |
| Suntory Holdings Limited |
| Others |
Value Network & Pricing Analysis
Potassium chloride spot prices on the Midwest fertilizer index cascade directly through electrolyte beer manufacturing, compressing margins on premium magnesium-chelated formulations while forcing standard sodium-fortified variants toward commodity-like pricing tiers.
Pricing Analysis
Volume concentrates in mass-market light beer with thin margins, while margin capture clusters in non-alcoholic and craft segments where FOSHU certification and third-party NSF testing command premium positioning. Three-tier pricing structure separates FOSHU-approved premium formulations from standard sports-recovery SKUs and economy light beer variants. Cost compression in the premium tier is intensifying because magnesium citrate and chelated mineral inputs face agricultural fertilizer demand competition. Health-conscious consumers in urban fitness corridors show highest price sensitivity, whereas competitive endurance athletes in Japan and Germany demonstrate lowest elasticity due to batch-testing requirements.
Supply Chain Analysis
Empty can and bottle returns from specialty running shops in Boulder, Colorado and Tokyo's Setagaya ward feed regional recycling streams, though mineral residue complicates standard beverage reprocessing protocols. Manufacturing concentrates in Germany, Japan, and the United States where precision fermentation infrastructure and regulatory expertise co-locate. Production draws from European specialty yeast strains, Chinese magnesium oxide and citrate precursors, and domestic malted barley. Single-source vulnerability concentrates in three European low-alcohol yeast suppliers. Distribution runs through multinational brewer wholesale networks for mass-market SKUs, with direct-to-consumer subscription channels capturing premium mineral-customization demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyte beer manufacturing is transitioning from batch mineral dosing to continuous fermentation monitoring systems, with bioavailability-optimized precision delivery replacing legacy post-fermentation additive blending.
For Market Incumbents: Hedge against formulation talent scarcity by captive hiring of sports nutrition food scientists from pharmaceutical competitors, while securing multi-year offtake agreements with European specialty yeast suppliers to mitigate single-source concentration risk. Defend mass-market positioning through backward integration into malted barley processing to buffer agricultural input volatility. For New Entrants and Emerging Players: Begin with direct-to-consumer subscription models targeting triathletes and ultramarathoners in Melbourne's inner suburbs and Colorado's Front Range, where specialty retail bundling with gait analysis and nutrition planning creates trust transfer unavailable through supermarket channels. Brazil's ANVISA regulatory framework development represents the most penetrable geography for first-mover functional beverage positioning. For Investors and Strategic Acquirers: The window for entry favors craft brewery specialists with existing precision fermentation infrastructure and FOSHU petition experience, as multinational brewers will likely consolidate these capabilities rather than build organically. Monitor ANVISA regulatory finalization and EFSA health claim guidance revisions as inflection signals for geographic expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Infrastructure Investment | Continuous mineral dosing automation reduces quality control labor while enabling regional taste customization in Bavaria and Oregon. |
| FOSHU Certification Pathway Completion | Japan's Ministry of Health, Labour and Welfare approval unlocks premium positioning among Tokyo endurance athlete communities. |
| Direct-to-Consumer Subscription Launch | Sweat-testing data integration enables personalized mineral formulations with recurring revenue capture in United States and German markets. |
| Specialty Sports Retailer Partnership | Running and cycling shops in Setagaya and Boulder bundle electrolyte beer with training gear, displacing supermarket volume. |
| Backward Integration into Mineral Sourcing | Captive supply of magnesium citrate buffers agricultural fertilizer demand volatility affecting premium formulation margins. |
Research Methodology
Document review covered FDA GRAS petitions, EFSA novel food approval filings, and Japan FOSHU functional food registrations, complemented by interviews with craft brewery production directors, sports nutrition food scientists, specialty running shop buyers, and endurance athlete community organizers. Secondary validation drew from customs trade data on magnesium and potassium salt imports, SEC 10-K beverage segment disclosures, and retail audit data from Nielsen and Circana. Bottom-up volume modeling triangulated against top-down category sizing from national alcoholic beverage taxation records.
Segment-level value outputs across product type, mineral component, distribution channel, and customer motivation dimensions were generated through structured growth accounting. CAGRs were derived from trend extrapolation with elasticity adjustments for regulatory approval timelines and fitness culture penetration rates. Mineral bioavailability science advancements and FOSHU pathway streamlining served as key forecast inputs.
Underlying measurement precision varies by segment; non-alcoholic and craft beer categories with established certification frameworks carry tighter precision than nascent hard seltzer electrolyte variants awaiting regulatory clarity. Forecasts reflect assumptions on ANVISA framework finalization and EFSA health claim interpretation consistency. Practitioners should monitor potassium chloride fertilizer index movements and specialty yeast supplier consolidation for early signals of margin compression or supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Global Liquor Confectionery Market
Alcoholic Beverages
Brewing Enzymes Market