
 Braiding Machine Market | 2026-2036
Braiding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Braiding Machine Market Intelligence
The integration of Computer Numerical Control (CNC) into braiding machine architecture is reshaping how complex composite materials are manufactured. This shift enables higher precision and repeatability for intricate patterns required in technical textiles. HERZOG GmbH leads in developing sophisticated CNC solutions for specialized applications. Meanwhile, Wardwell Braiding Co. leverages its long-standing expertise in mechanical systems for high-volume production, and Kyang Yhe Delicate Machine Co., Ltd. competes by offering a wide range of semi-automatic and automatic machines.
A braiding machine interlaces three or more strands of material, such as fiber or wire, to create a rope, sleeve, or solid structural component. The machine's complexity is defined by its number of carriers and axes of motion, which dictates the final braided structure's density and angle. Among product types, automatic and CNC machines command higher value, especially for producing aerospace components and composite materials. While flat braiding technology is mature, circular braiding for electrical cables remains a high-volume segment.
Product quality for medical and aerospace applications is governed by stringent standards, including FDA requirements in the United States and CE marking for machinery safety in Europe. In China, GB standards dictate compliance for industrial equipment. These regulations influence material selection and process validation for end-products. The key decision for manufacturers now involves balancing investment in high-cost, versatile CNC systems against specialized, high-throughput mechanical braiders for specific market niches.
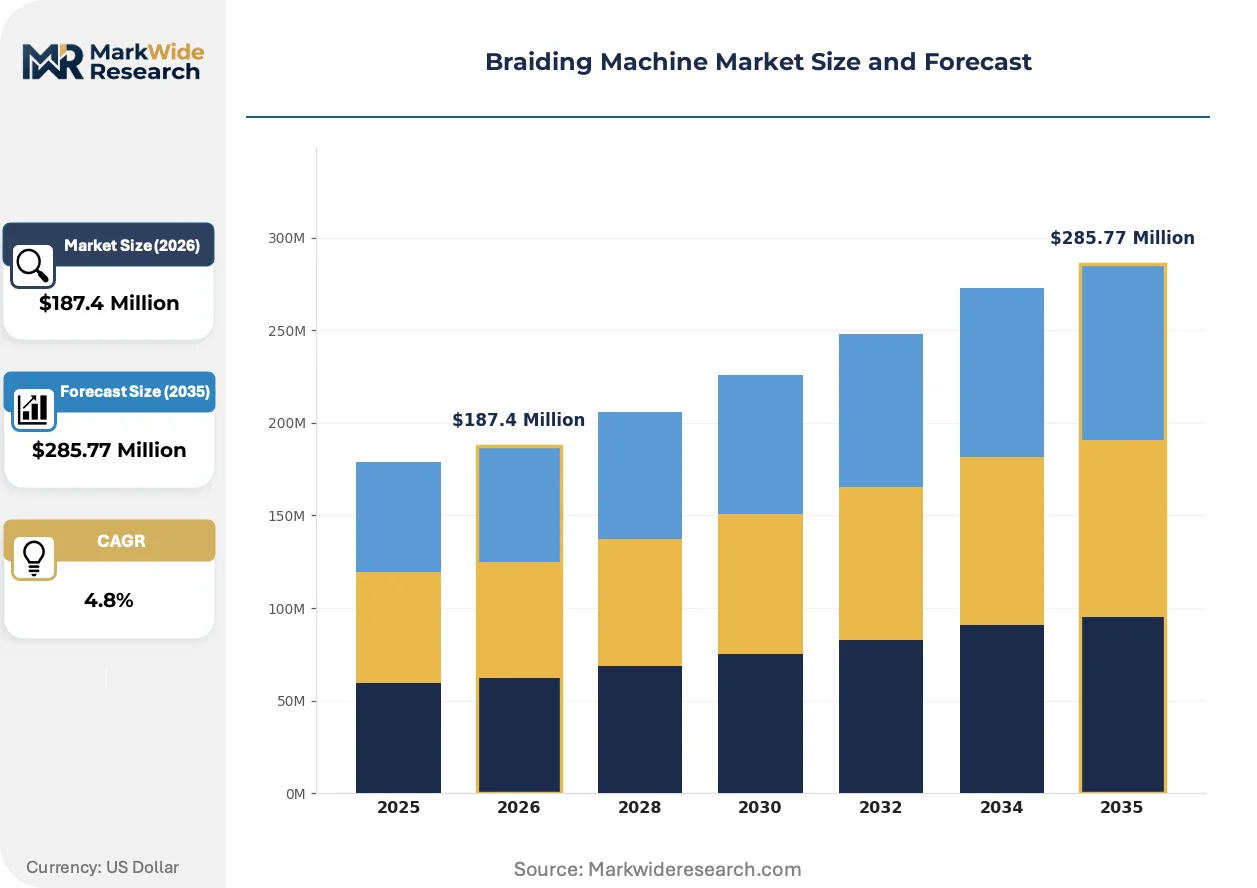
Market Dynamics
The central structural force shaping the market is the bifurcation of investment between high-cost, versatile CNC braiding systems and specialized, high-throughput mechanical braiders. This decision point defines a manufacturer's competitive strategy, balancing flexibility against scale for specific end-use applications.
Growth Catalysts
- Aerospace Lightweighting:Demand for lightweight composite components in the aerospace industry, especially for airframes and engine parts in the United States and France, drives adoption of advanced braiding for producing high-strength, complex preforms.
- Medical Device Miniaturization:The continuous development of minimally invasive surgical tools and catheters requires intricate, strong, and flexible braided components, with production governed by stringent FDA material and process validation requirements.
- Advanced Industrial Textiles:The expansion of technical textile applications, from high-performance ropes to filtration media, increases the need for braiding machines capable of handling advanced fibers like aramid and UHMWPE under various industrial standards.
Market Restraints
- High Capital Investment:The significant upfront cost of multi-axis CNC braiding machines presents a substantial barrier to entry for smaller manufacturers, limiting their ability to compete in high-value composite sectors.
- Specialized Component Dependency:A reliance on a concentrated group of suppliers for critical components like CNC controllers, servo motors, and specialized software creates supply chain vulnerability and pricing pressure.
- Substitution from Alternative Processes:For non-structural or low-performance applications, competing technologies such as filament winding, pultrusion, or advanced knitting offer lower-cost alternatives to braiding, limiting market scope.
Strategic Opportunities
- Renewable Energy Sector:The production of composite reinforcements for wind turbine blades and lightweight structural components for electric vehicles represents a significant new application area for large-format braiding technology.
- Smart Textiles Integration:The opportunity to integrate conductive fibers and sensors directly into the braiding process opens up the market for smart textiles used in wearable technology, healthcare monitoring, and structural health monitoring.
- Service and Software Models:Developing subscription-based software for pattern design and simulation, alongside remote diagnostics and predictive maintenance services, creates new recurring revenue streams beyond initial machine sales.
Industry Challenges
- Skilled Operator Scarcity:A persistent shortage of technicians and engineers with the dual expertise in mechanical braiding principles and CNC programming hinders the effective deployment and optimization of advanced automated systems.
- Lengthy Certification Cycles:The time and expense required to achieve certification for products in the medical and aerospace sectors, including compliance with FAA and MDR regulations, delay revenue generation from new machine installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Braiding Machine Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, CNC Technology: Overbraiding, Circular Braiding, Square Braiding, Diamond Braiding, Flat Braiding Application: Aerospace Components, Marine Equipment, Sporting Goods, Electrical Cables, Composite Materials End User Industry: Textile Manufacturers, Defense Contractors, Construction Firms, Medical Device Makers, Electronics Producers |
| Companies Covered | Steeger USA, Kyang Yhe Delicate Machine Co., Ltd., Wardwell Braiding Co., Niehoff Schwabach, Cobra Braiding Machinery, Mayer & Cie., O.M.A., Spirka Schnellflechter, HERZOG GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Braiding Machine Market Strategic Shifts & Innovations
Automation and material science are converging to redefine braiding machine capabilities. Systems are evolving beyond simple interlacing to become sophisticated manufacturing cells that can process novel fibers and produce complex, near-net-shape composite structures with minimal manual intervention.
Multi-material braiding technology allows for the interlacing of dissimilar fibers, such as carbon and thermoplastic, within a single braided structure. The automotive and sporting goods industries are adopting this for components requiring localized stiffness and impact resistance. This capability is hybridizing the function of braiding machines, transforming them from basic sleeving tools into advanced composite preform manufacturing systems.
The European Union's CE marking directives for machinery safety impose strict design and control system requirements on manufacturers. This forces the integration of certified safety interlocks, redundant controls, and validated software into the core machine architecture. The medical device segment is most impacted, as equipment must simultaneously meet CE standards and the EU's Medical Device Regulation (MDR) for market access.
A demand-side shift toward smaller, customized production batches is challenging the traditional high-volume manufacturing model. This dynamic disrupts the economic advantage of large-scale mechanical braiders, creating an opening for more flexible, quick-changeover CNC systems. This pattern is particularly evident in the aerospace prototyping and custom medical catheter markets in North America and Europe.
Braiding Machine Market Segmentation
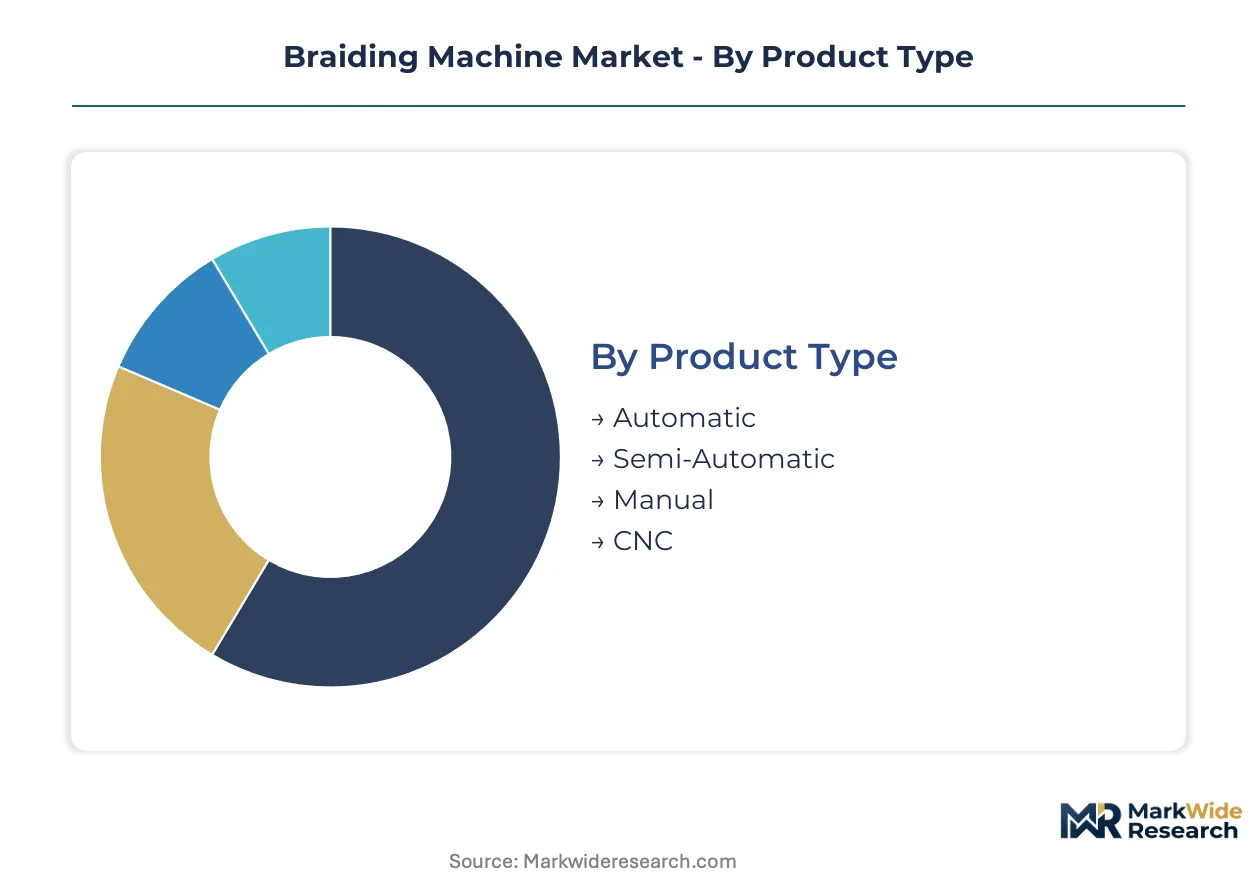
The Braiding Machine Market's segmentation reveals the diverse technological requirements and end-use applications driving innovation and investment across the industry. Understanding these distinct segments allows manufacturers to tailor machine capabilities and strategic focus, addressing specific market demands for material processing and product output.
Product Type:
The product type segmentation highlights the varying levels of automation and control available, ranging from established mechanical systems to advanced digital platforms.
- CNC:These machines integrate computer numerical control for precise, multi-axis motion, enabling the production of complex geometries and intricate patterns for advanced composite preforms. Demand for CNC systems is concentrating in aerospace and medical device manufacturing, driven by the need for high-strength, lightweight components in countries like the United States and France.
- Automatic:Automatic braiding machines perform continuous, unattended operation once set up, optimizing throughput for standardized products with minimal operator intervention. These systems find significant demand in the electrical cable and industrial textile sectors, where consistent quality and high production volumes are critical for cost efficiency.
- Semi-Automatic:Semi-automatic machines require some manual intervention during operations, offering a balance between automation benefits and lower capital expenditure for specialized or smaller batch runs.
- Manual:Manual braiding machines rely entirely on operator control for interlacing strands, typically used for prototyping, educational purposes, or very low-volume, artisanal production.
Automatic machines retain volume leadership; CNC systems hold the steepest expansion curve.
Technology:
Different braiding technologies cater to specific structural requirements and material types, influencing machine design and end-product characteristics.
The technological segmentation emphasizes the functional diversity of braiding processes, each optimized for distinct material forms and performance outcomes.
- Overbraiding:This technology applies a braided sleeve over an existing core, providing reinforcement, protection, or aesthetic finishing, commonly used for aerospace components and medical catheters. Precision overbraiding is essential for airframe parts, ensuring structural integrity and weight reduction.
- Circular Braiding:Circular braiding machines produce tubular structures, ideal for ropes, hoses, and electrical cable sheathing, characterized by continuous production and uniform wall thickness. This technology remains a high-volume segment, particularly for infrastructure and automotive wiring applications.
- Flat Braiding:Flat braiding creates two-dimensional structures, such as tapes, belts, and narrow fabrics, often used in industrial textiles and composite reinforcement where planar strength is required.
- Square Braiding:Square braiding forms components with a square cross-section, offering unique structural properties for specialized industrial applications and composite preforms.
- Diamond Braiding:Diamond braiding produces a distinct pattern that enhances flexibility and aesthetic appeal, frequently used in decorative cords and some technical textile applications.
Overbraiding technology is advancing rapidly due to its role in complex composite manufacturing, while circular braiding maintains its market position through consistent demand for electrical cables.
Application:
The application segment highlights the diverse end-uses for braided products, each with unique performance requirements and regulatory standards.
This segment categorizes the market based on the specific industries and product functions that utilize braided components, reflecting varying value propositions.
- Aerospace Components:Braiding machines produce lightweight, high-strength composite preforms for aircraft structures, engine parts, and interior components, driven by stringent FAA and EASA certification requirements. Demand for these advanced materials is strong in aerospace manufacturing hubs within the United States and France.
- Composite Materials:This application focuses on creating braided preforms that are subsequently infused with resin to form advanced composite structures, offering superior strength-to-weight ratios for various industries. The automotive and renewable energy sectors, particularly for wind turbine blades, are driving demand for these specialized components.
- Marine Equipment:Braided ropes, cables, and structural elements are essential for marine applications, requiring high tensile strength, abrasion resistance, and durability in harsh environments.
- Sporting Goods:Braiding machines produce components for high-performance sporting equipment, including fishing rods, tennis rackets, and protective gear, where strength and flexibility are critical.
- Electrical Cables:Braided sheathing provides insulation, shielding, and mechanical protection for electrical wires and cables, crucial for consumer electronics and industrial power transmission.
Aerospace components command significant investment due to performance demands, while composite materials applications are expanding machine capabilities for new markets.
End User Industry:
The end user industry segmentation illustrates the diverse customer base for braiding machines, each with distinct operational scales and product specifications.
This category delineates the market by the primary industrial sectors consuming braiding machines, reflecting varied purchasing drivers and regulatory landscapes.
- Medical Device Makers:This industry uses braiding machines to produce intricate, strong, and flexible components for minimally invasive surgical tools, catheters, and implants, requiring strict FDA and EU MDR compliance. Continuous development of miniaturized devices drives demand for high-precision systems.
- Defense Contractors:Braiding machines support the defense sector by manufacturing specialized ropes, ballistic protection, and composite parts for military vehicles and equipment, adhering to rigorous performance standards. These applications demand extreme durability and reliability for critical systems.
- Textile Manufacturers:Traditional textile manufacturers utilize braiding machines for producing a wide range of fabrics, cords, and decorative elements for apparel, home furnishings, and industrial textiles.
- Electronics Producers:This sector employs braiding machines for creating protective sleeves, shielding, and specialized cables for consumer electronics, communication systems, and industrial control units.
- Construction Firms:Braided materials find application in construction for reinforcement, lifting slings, and specialized geotextiles, requiring robust and durable products.
Medical device makers impose exacting standards on machine output, while defense contractors prioritize performance and reliability for mission-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences the regional demand for braiding machines, particularly for high-precision, advanced composite manufacturing in aerospace and medical sectors. These specialized applications drive investment in sophisticated CNC systems across developed economies. Conversely, high-volume production of electrical cables and industrial textiles sustains demand for automatic and semi-automatic machines in emerging manufacturing hubs.
United States
Demand for advanced braiding machines in the United States stems from the aerospace components sector and medical device miniaturization. FAA regulations govern the production of critical aircraft parts, while FDA requirements dictate material and process validation for medical devices. Manufacturing clusters in Seattle, Washington, focus on aerospace preform production, and Boston, Massachusetts, leads in high-precision medical catheter braiding.
France
France exhibits strong demand for braiding technology, driven by its robust aerospace industry and composite materials research. EASA certification mandates strict quality control for airframe components, influencing machine specifications. The Toulouse region anchors significant aerospace manufacturing, leveraging advanced overbraiding technology for lightweight structures, while technical textile innovation occurs near Lyon.
Germany
Germany's market for braiding machines focuses on high-performance industrial textiles, automotive composites, and specialized machinery. CE marking directives ensure machinery safety and performance standards for industrial equipment. The Stuttgart area supports advanced automotive component manufacturing, and the Chemnitz region remains a hub for textile machinery innovation and production.
China
China's market demand for braiding machines spans high-volume electrical cable production and growing composite materials applications. GB standards enforce compliance for industrial equipment, influencing local manufacturing practices. The Yangtze River Delta region concentrates significant industrial manufacturing capacity, driving demand for both automatic and semi-automatic braiding systems for diverse applications.
India
India's braiding machine market is expanding due to growth in industrial textiles, defense applications, and infrastructure development, particularly for electrical cables. BIS standards ensure product quality and safety across various industrial sectors. Manufacturing centers in Gujarat focus on textile production, while Bengaluru contributes to defense and aerospace component development.
Braiding Machine Market Key Industry Players
Channel-controlling players compete with product-specialist players across the braiding machine market, creating a landscape of both generalists and niche experts. The market structure exhibits fragmentation among smaller, specialized manufacturers, while a few larger entities offer comprehensive solutions. Strategic archetypes include innovation leaders, cost-efficient volume producers, and regional specialists. Portfolio diversification and strategic partnerships represent dominant competitive moves.
Within the innovation-driven segment, HERZOG GmbH exemplifies a focus on sophisticated CNC solutions for specialized applications, particularly in advanced composites. Wardwell Braiding Co. occupies a position as a long-standing expert in mechanical systems, anchoring high-volume production requirements. Kyang Yhe Delicate Machine Co., Ltd. represents a broad offering across semi-automatic and automatic machines, catering to diverse industrial needs.
| Leading Market Players |
|---|
| Steeger USA |
| Kyang Yhe Delicate Machine Co., Ltd. |
| Wardwell Braiding Co. |
| Niehoff Schwabach |
| Cobra Braiding Machinery |
| Mayer & Cie. |
| O.M.A. |
| Spirka Schnellflechter |
| HERZOG GmbH |
| Others |
Cost & Logistics Intelligence
Under-capacity in specialized CNC braiding machine production drives supplier behavior and pricing posture, reflecting high demand from aerospace and medical device sectors. This demand for advanced systems, particularly for complex composite preforms, influences investment decisions across the value chain, balancing innovation with manufacturing scale.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material costs like carbon fiber or specialized alloys, govern pricing for advanced braiding machines. Price differentiation stems from precision capabilities for intricate patterns and adherence to stringent certifications like CE marking and FAA standards. Pricing pressure intensifies for high-volume mechanical braiders due to increased competition from Asian manufacturers. Aerospace and medical device manufacturers exhibit lower price sensitivity compared to general industrial textile producers, prioritizing performance and regulatory compliance.
Supply Chain Analysis
Single-source vulnerability for specialized CNC controllers and servo motors dominates the braiding machine supply chain, creating dependency risks for manufacturers. Geographic supply concentrates in Germany for advanced machinery, China for high-volume components, and the United States for specialized aerospace-grade fibers. The supply chain draws from critical components like motion control systems and proprietary software. Distribution runs through direct sales channels for high-value CNC systems and established distributor networks for automatic and semi-automatic machines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The braiding machine market is entering a cyclical recovery, driven by renewed investment cycles in aerospace and medical device manufacturing post-global economic shifts.
For Market Incumbents: Build technological moats through continuous R&D in multi-axis CNC capabilities and proprietary software for complex composite preforms. Deepen integration with aerospace and medical device OEMs to counter potential substitution from alternative processes like advanced knitting. Prioritize investment in automated quality control systems to meet FAA and MDR compliance requirements.
For New Entrants and Emerging Players: Build out niche capabilities in specialized material handling or rapid prototyping solutions for emerging applications like smart textiles. Target underpenetrated segments such as the renewable energy sector for large-format braiding technology. Offer flexible, customizable CNC systems with subscription-based software models to address demand for smaller, customized production batches.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the advanced CNC braiding segment, reflecting the high investment required for precision manufacturing. Focus on mid-sized firms with strong intellectual property in CNC software or specialized material handling technologies for long-term viability. A key signal to watch is the growth in R&D spending by aerospace primes on composite structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Integration and AI | Enhances machine versatility and enables production of complex, intricate braided patterns. |
| Multi-material Braiding R&D | Expands application scope into automotive and sporting goods for hybrid composite structures. |
| Regional Manufacturing Hubs | Reduces lead times and strengthens supply chain resilience for key aerospace markets. |
| Service Model Expansion | Creates recurring revenue streams through remote diagnostics and predictive maintenance offerings. |
| Certification Focus | Ensures compliance with stringent FDA and CE marking standards, crucial for medical device market access. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings and quantitative projections. Primary data collection involved discussions with R&D directors, procurement officers at aerospace OEMs, medical device engineers, and textile manufacturing plant managers. Secondary data sources included industry association reports, government trade statistics, company annual reports, and technical journals, enabling bottom-up and top-down triangulation.
Calibration of historical market data against macroeconomic indicators informs the analytical framework for future projections across the analysis window. The market segmentation dimensions, including product type (CNC, automatic), technology (overbraiding, circular braiding), application (aerospace, medical), and end-user industry (medical device makers, defense contractors), were modeled. Compound annual growth rates were derived from market growth rates, competitive dynamics, and industry-specific inputs like aerospace build rates and medical device approval trends.
Practitioners should monitor shifts in aerospace regulatory standards and medical device innovation for early signals of forecast revision. Forecasts reflect assumptions regarding technological adoption curves and global economic stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Fabric Reversing Machines Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market