
 Global Custom T-Shirt Printing Market | 2026-2036
Global Custom T-Shirt Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Custom T-Shirt Printing Market Foresight
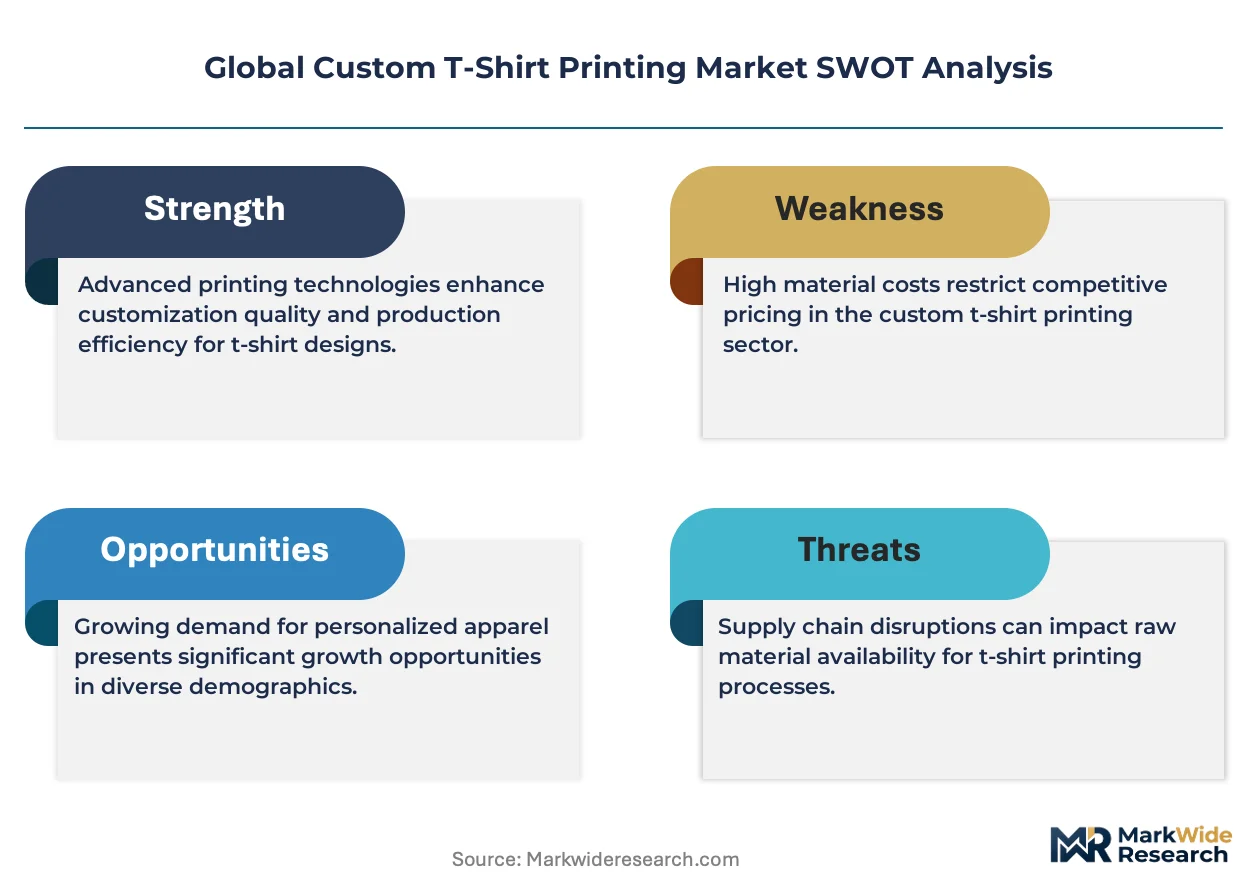
Event merchandise demand is decoupling from conventional bulk screen-printing contracts as corporate clients and independent creators shift toward on-demand, low-minimum-order workflows. Printful leverages its distributed fulfillment network to sustain same-day production across North America and Europe. CustomInk anchors the United States market through proprietary design tools and direct-to-consumer brand strength. Spreadshirt competes via marketplace-driven creator economics that reduce inventory risk for individual sellers.
Custom t-shirt printing encompasses the application of pigmented or dye-based formulations onto woven or knitted textile substrates through mechanical, thermal, or digital deposition methods, with resolution thresholds ranging from 300 to 1200 DPI for photorealistic output and curing temperatures between 160°C and 190°C for plastisol and water-based inks. Its primary commercial purpose is enabling brand differentiation, identity expression, and promotional reach without the capital burden of traditional garment manufacturing. Direct-to-garment technology leads in image complexity and color gamut but carries higher per-unit costs that constrain its share in high-volume sportswear contracts. Screen printing dominates promotional campaigns and corporate branding where single-color or limited-palette designs justify setup amortization across thousands of units. Heat transfer and sublimation segments are maturing in fashion apparel applications as polyester-blend fabrics gain share in athleisure lines.
REACH regulates chemical composition of textile inks across European supply chains, while FDA color additive regulations govern skin-contact safety for printed garments sold in the United States. China's GB standards and evolving MEE directives on volatile organic compound emissions are tightening compliance requirements for export-oriented print houses in Guangdong and Zhejiang provinces. Stakeholders must monitor how divergent chemical safety frameworks across the European Union, United States, and China reshape ink formulation strategies and cross-border fulfillment economics.
Market Dynamics
Direct-to-garment inkjet systems are compressing minimum order quantities from hundreds toward single-unit fulfillment, forcing print houses to reconfigure production floors around distributed micro-factories rather than centralized bulk lines.
Growth Catalysts
- REACH chemical compliance:European ink manufacturers reformulating pigment chemistries ahead of 2025 substance restrictions are opening premium pricing tiers for certified water-based formulations.
- Polyester-blend athleisure demand:Sublimation-ready fabric adoption in sportswear and fitness apparel is expanding addressable substrate range beyond traditional cotton-dominant workflows.
- India's PLI scheme for textiles:Production-linked incentives for technical textile manufacturing are drawing garment finishing investment toward Gujarat and Tamil Nadu clusters.
Market Restraints
- Pretreatment chemical costs:DTG workflows require specialized polymeric coatings that add per-unit material burden not present in screen-printing economics.
- Guangdong print house concentration:Export-oriented fulfillment capacity clusters in southern China create geographic single-point vulnerability for cross-border supply chains.
- Plastisol ink substitution pressure:PVC-based formulations face displacement from phthalate-free alternatives, forcing equipment recalibration and chemistry requalification cycles.
Strategic Opportunities
- Germany's circular textile mandates:Extended producer responsibility frameworks for garment recycling create service revenue streams for take-back and reprint programs.
- AI-assisted design-to-print pipelines:Automated vector generation and color separation tools are converging with e-commerce APIs to compress creative-to-fulfillment timelines.
- Creator marketplace channels:Platform-integrated dropshipping models reduce inventory carrying costs for independent designers accessing on-demand production nodes.
Industry Challenges
- Color management specialist scarcity:ICC profiling expertise for multi-substrate calibration remains concentrated among veteran operators, constraining quality consistency at scale.
- Dual-chemistry equipment capex:Print houses serving both cotton and polyester lines face parallel capital commitments for DTG and sublimation hardware stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Custom T-Shirt Printing Market |
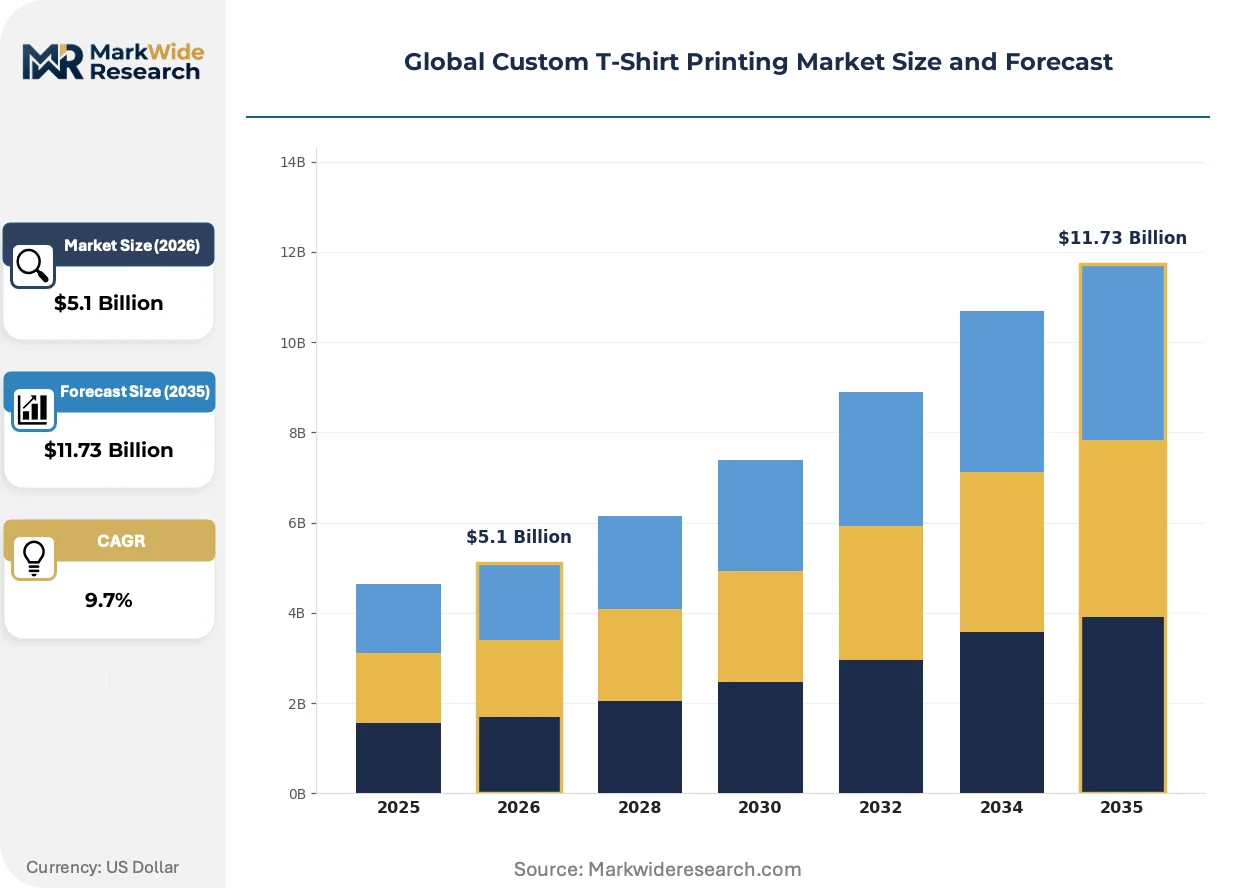
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $11.73 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Printing Technology: Screen Printing, Direct-to-Garment, Heat Transfer, Sublimation, Embroidery, Vinyl Cutting Application: Corporate Branding, Event Merchandise, Sportswear, Fashion Apparel, Promotional Campaigns, Personal Use Customer Type: Small Businesses, Online Retailers, Educational Institutions, Nonprofit Organizations, Design Agencies, Freelancers Fabric Type: Cotton, Polyester, Blends, Bamboo, Organic Fabric, Linen |
| Companies Covered | CustomInk, Printful, Vistaprint, Cimpress, Spreadshirt, CafePress, RushOrderTees, Threadbird, UberPrints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Custom T-Shirt Printing Market Shifts & Advancements
Digital deposition technologies are rewriting throughput economics while regulatory chemistry shifts and platform-enabled creator economies reshape who controls design-to-fulfillment value chains.
Nano-pigment aqueous ink formulations are converging with high-speed single-pass printheads to close the cost gap with screen printing at run lengths below fifty units. Athletic apparel brands in the United States and Germany are piloting these systems for limited-edition capsule drops. The technology is converging with automated pretreatment stations to enable lights-out production shifts in distributed fulfillment nodes.
REACH Annex XVII restrictions on organotin catalysts and specific phthalate esters are forcing reformulation of plastisol and discharge inks across European supply chains. German and French textile finishers face six-to-twelve month requalification timelines for substitute chemistries. Water-based pigment systems are capturing share in premium promotional segments where skin-contact safety certification commands buyer preference.
Corporate merchandise procurement is fragmenting from annual bulk contracts toward campaign-triggered micro-orders synchronized with event marketing calendars. Marketing procurement teams in technology and financial services verticals are displacing retained inventory models with API-integrated on-demand fulfillment. This pattern is most visible in United States metropolitan markets where same-day delivery expectations have normalized across consumer and B2B channels.
Global Custom T-Shirt Printing Market Segmentation
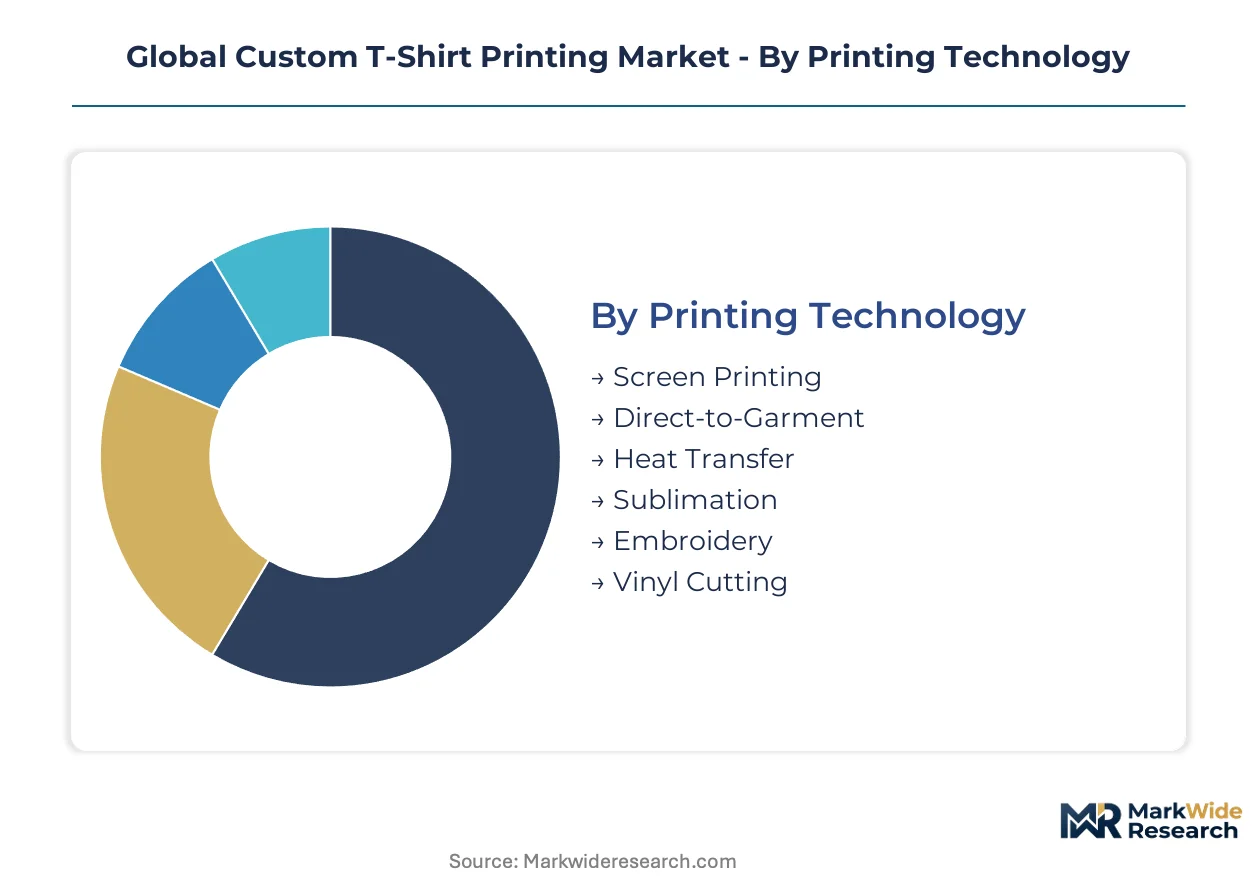
Segmentation in custom t-shirt printing reveals how technology choices, fabric substrates, and customer workflows create distinct margin profiles and capital requirements. Understanding these divides helps stakeholders allocate equipment investment and inventory positioning across divergent demand patterns.
Printing Technology:
Customization intensity spans from fully automated digital deposition to labor-intensive manual setups, with each technology occupying a different point on the unit-economics spectrum.
- Screen Printing:Mesh-based stencil systems force ink through polyester screens onto substrates, requiring separate screens per color and substantial setup labor. Corporate branding contracts in the United States and Germany concentrate here, where amortization across thousands of units justifies fixed costs despite REACH-driven chemistry reformulation cycles.
- Direct-to-Garment:Piezoelectric inkjet heads deposit aqueous pigment inks directly onto cotton garments without screens or transfer media, enabling single-unit fulfillment with photorealistic resolution. Fashion apparel designers in metropolitan United States markets gravitate toward DTG for capsule drops and influencer collaborations, though pretreatment chemical costs compress margins on low-price-point orders.
- Heat Transfer:Thermal or pressure-based bonding of pre-printed films or vinyl onto garment surfaces suits short-run promotional campaigns with simple graphics.
- Sublimation:Dye diffusion into polyester fibers at high temperature delivers permanent, crack-resistant prints for sportswear applications.
- Embroidery:Computerized stitching machines create textured, durable decoration for corporate uniforms and premium merchandise.
- Vinyl Cutting:CAD-driven blade systems excise designs from colored film for heat application, dominating personalized athletic numbering and single-color graphics.
Leading the category by volume: Screen Printing. Expanding most quickly: Direct-to-Garment.
Application:
Volume concentration and margin structure diverge sharply between inventory-heavy seasonal cycles and event-triggered micro-batch procurement.
- Corporate Branding:Uniform programs, retail merchandise, and employee apparel requiring color consistency and repeatability across multi-year contracts. Procurement teams at technology and financial services firms in the United States are displacing annual bulk orders with API-integrated on-demand fulfillment synchronized to hiring calendars and product launches.
- Event Merchandise:Conference, concert, and festival merchandise historically ordered in bulk pre-event, now shifting toward distributed micro-factories producing same-day near venues. Music and sports promoters in Germany pilot this model to reduce unsold inventory risk and capture impulse purchases.
- Sportswear:Team uniforms, fan merchandise, and fitness apparel with performance fabric requirements and seasonal demand spikes.
- Fashion Apparel:Designer collections and limited-edition drops emphasizing aesthetic complexity and rapid turnaround.
- Promotional Campaigns:Trade show giveaways and marketing activations prioritizing low unit cost over durability.
- Personal Use:Individual consumers ordering single units through marketplace platforms or direct-to-consumer websites.
Dominating revenue concentration: Corporate Branding. Steepest expansion trajectory: Event Merchandise.
Customer Type:
Order scale and technical sophistication separate enterprise procurement functions from individual creator workflows.
- Small Businesses:Local print shops and regional decorators serving community organizations with mixed-technology production floors.
- Online Retailers:Marketplace sellers and brand operators leveraging dropshipping integrations to eliminate inventory carrying costs.
- Educational Institutions:Universities and K-12 systems ordering spirit wear, uniforms, and fundraising merchandise with seasonal concentration.
- Nonprofit Organizations:Cause-driven merchandise campaigns with mission-aligned messaging and donor-funded procurement.
- Design Agencies:Creative studios managing brand identity programs and campaign-specific apparel for corporate clients.
- Freelancers:Independent graphic designers and illustrators accessing platform-integrated production nodes without capital investment.
Highest order frequency: Online Retailers. Fastest-growing participant base: Freelancers.
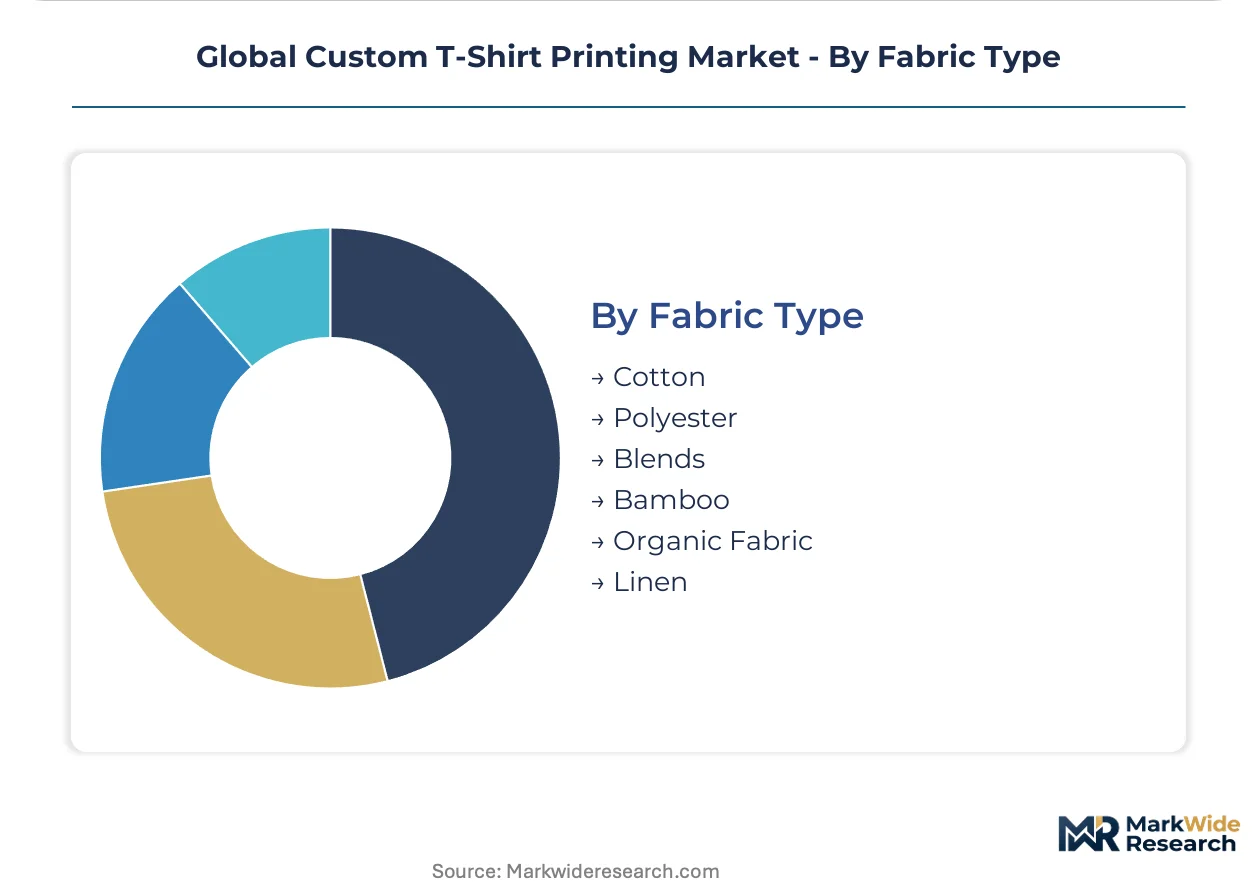
Fabric Type:
Substrate chemistry dictates compatible printing technologies and determines compliance requirements across regulatory jurisdictions.
- Cotton:Natural fiber dominant in casual and promotional segments, compatible with DTG, screen printing, and heat transfer methods. India's PLI scheme for technical textiles is expanding domestic cotton finishing capacity in Gujarat and Tamil Nadu clusters, reducing import dependency for export-oriented print houses.
- Polyester:Synthetic fiber requiring sublimation or specialized discharge inks, capturing share in athleisure and performance sportswear. German and United States athletic brands drive demand for recycled polyester blends as circular textile mandates tighten.
- Blends:Cotton-polyester combinations balancing comfort and durability for corporate and educational uniforms.
- Bamboo:Cellulosic fiber marketed for sustainability positioning in premium promotional segments.
- Organic Fabric:Certified cotton and alternative fibers commanding price premiums where skin-contact safety certification influences procurement.
- Linen:Bast fiber with natural texture favored in fashion and resort merchandise applications.
Highest volume throughput: Cotton. Gaining share fastest: Polyester.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Tamil Nadu concentrate garment finishing investment through India's PLI scheme for technical textiles, while REACH compliance costs in Europe and FDA color additive enforcement in the United States reshape regional competitive positioning.
United States
Corporate procurement teams in technology and financial services displace annual bulk orders with API-integrated on-demand fulfillment synchronized to hiring calendars. FDA color additive regulations govern skin-contact safety for printed garments sold domestically. Metropolitan markets in California and New York normalize same-day delivery expectations across consumer and B2B channels.
Germany
Extended producer responsibility frameworks for garment recycling create service revenue streams for take-back and reprint programs in corporate branding segments. ECHA REACH Annex XVII restrictions on organotin catalysts force six-to-twelve month requalification timelines for substitute chemistries. Textile finishers in North Rhine-Westphalia pilot water-based pigment systems for premium promotional segments.
India
Production-linked incentives for technical textile manufacturing draw garment finishing investment toward Gujarat and Tamil Nadu clusters. BIS standards and evolving DGFT directives on export compliance tighten requirements for print houses serving European and North American buyers. Domestic cotton finishing capacity expands in Surat and Coimbatore, reducing import dependency.
China
Export-oriented fulfillment capacity clusters in Guangdong and Zhejiang provinces create geographic concentration for cross-border supply chains. MEE directives on volatile organic compound emissions tighten compliance requirements for print houses. Shenzhen and Dongguan maintain dominant positions in bulk screen-printing contracts despite chemistry reformulation pressures.
Global Custom T-Shirt Printing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform-integrated players capturing creator economy workflows while traditional decorators retain corporate uniform contracts. The vendor base organizes around three archetypes: vertically integrated fulfillment networks, proprietary design-tool operators, and marketplace-driven creator platforms. Consolidation pressure concentrates among North American and European players seeking geographic coverage. Technology licensing and strategic partnerships dominate competitive moves as chemistry compliance costs rise.
Among branded specialists, CustomInk anchors the United States market through direct-to-consumer brand strength and proprietary design tools. Printful occupies a position within the distributed fulfillment archetype, sustaining same-day production across North America and Europe through its micro-factory network. Spreadshirt exemplifies marketplace-driven creator economics, reducing inventory risk for individual sellers through platform-integrated dropshipping models.
| Leading Market Players |
|---|
| CustomInk |
| Printful |
| Vistaprint |
| Cimpress |
| Spreadshirt |
| CafePress |
| RushOrderTees |
| Threadbird |
| UberPrints |
| Others |
Supply & Pricing Matrix
ICC profiling specialists concentrated in North Rhine-Westphalia and Guangdong command wage premiums that propagate through three-tier pricing structures across premium, standard, and economy levels. Labor-cost differentials between these certified color-management hubs and emerging Tamil Nadu clusters widen spreads for photorealistic DTG output versus basic screen-printed contracts.
Pricing Analysis
Lead-time compression commands premium positioning: same-day fulfillment in United States metropolitan markets extracts margins above standard five-day turnaround economics. Price differentiation hinges on REACH certification tier and pretreatment chemical grade, with water-based pigment systems carrying cost premiums over plastisol alternatives. Pricing pressure stems from nano-pigment aqueous ink convergence eroding volume thresholds for screen-printing amortization. Small business procurement teams exhibit highest price sensitivity, while corporate branding buyers prioritize color consistency over unit cost.
Supply Chain Analysis
Freight cost volatility from Guangdong and Zhejiang export clusters to North American and European end-users is reshaping regional fulfillment economics. Raw material dependencies center on piezoelectric printheads from Japan, aqueous pigment formulations from Germany, and cotton substrates from India. Single-source vulnerability concentrates in Guangdong bulk screen-printing capacity for cross-border e-commerce. Distribution runs through platform-integrated dropshipping nodes that bypass traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-garment inkjet systems are displacing screen-printing dominance in sub-fifty-unit workflows, compressing legacy equipment utilization rates. This technology-transition phase demands repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: Acquire automated pretreatment station networks to defend against nano-pigment aqueous ink entrants eroding mid-volume contracts. Backward integration into water-based pigment formulation secures REACH compliance ahead of Annex XVII catalyst restrictions. Channel control through API-integrated fulfillment platforms locks in corporate procurement fragmentation. For New Entrants and Emerging Players: Begin with creator marketplace infrastructure serving freelancer designers in underserved German secondary cities. Event merchandise micro-factory deployment near United States conference venues captures impulse-driven demand away from bulk pre-order models. Go-to-market leverage rests on same-day production guarantees rather than price competition. For Investors and Strategic Acquirers: Re-rating potential sits with distributed fulfillment network operators given corporate procurement API integration accelerating across technology and financial services verticals. Long-term viability favors micro-factory platforms over centralized bulk decorators. Monitor ECHA substance restriction timelines as inflection signals for chemistry reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Pretreatment Station Deployment | Enables lights-out production shifts in distributed nodes serving same-day delivery expectations. |
| REACH-Compliant Ink Formulation Investment | Secures premium pricing tiers as ECHA Annex XVII restrictions force competitor requalification delays. |
| API-Integrated Fulfillment Platform Launch | Captures corporate procurement fragmentation from annual bulk contracts toward campaign-triggered micro-orders. |
| Creator Marketplace Channel Partnership | Reduces inventory carrying costs for independent designers accessing on-demand production nodes. |
| Micro-Factory Geographic Expansion | Positions capacity near United States and German metropolitan demand centers to compress last-mile delivery economics. |
Research Methodology
Independent corroboration across print house operations directors, textile chemical formulators, corporate procurement managers, and e-commerce platform engineers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through customs records, SEC filings of listed apparel decorators, and ECHA substance restriction databases. Bottom-up unit economics modeling triangulated against top-down market sizing from trade association data and national textile production statistics.
Rate-of-change decomposition across the analysis window segments volume trajectories by printing technology, fabric substrate chemistry, and customer workflow archetype. The analytical framework models direct-to-garment, screen printing, sublimation, and heat transfer segments separately, with cross-elasticity parameters capturing substitution effects as nano-pigment aqueous inks compress run-length thresholds. CAGRs derive from fitted growth curves against historical capacity installation data and procurement pattern shifts documented in primary interviews.
Underlying measurement precision varies by segment; direct-to-garment and screen printing carry tighter precision than emerging sublimation workflows in recycled polyester blends. Forecasts embed assumptions regarding ECHA regulatory timelines and PLI scheme disbursement rates in India that could revise trajectories if implementation accelerates or delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Textile Winding Machine Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Dyeing Machine Market